首頁Tesla Model Y

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

車型概覽

奧迪TTS 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講下訂前最容易忽略嘅問題,幫你用買家角度篩走唔適合嘅選擇。
可用資訊集中喺車型定位、圖片同版本名稱,現階段更適合先做候選名單,再等價格同詳細規格落實。
購車價格指南
奧迪TTS 目前售價仍未清晰,較理性嘅做法係先睇版本、車身大小同動力形式,等價格落實後再決定值唔值得落訂。
未有清楚版本資訊時,唔建議單靠外形下決定;先諗清楚你需要代步、家庭出行、長途巡航,定係想要更有個性嘅座駕。
核心規格重點
睇 奧迪TTS 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
奧迪TTS 現階段最值得留意係車型定位同版本方向,詳細取捨應該等價格同規格更清楚再作決定。
優缺點分析
奧迪TTS 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:車型定位清楚,適合作為同級比較起點。
要留意嘅係,售價未清晰前唔應該太早用性價比落結論。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 奧迪TTS 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「奧迪 Audi TTS 香港仲買到新車嗎?」簡單講,同樣地,奧迪 Audi TTS 已停產,目前香港市場以二手盤源為主。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 奧迪TTS 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先由用途、品牌售後、車身大小同版本定位開始比較。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 奧迪TTS 唔係買車一刻就完結,之後仲有保險、輪胎、保養、泊車同日常能源成本要處理。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。

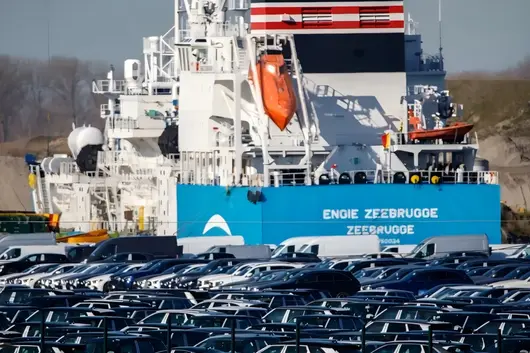
然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。

要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。

高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。

《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。

如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
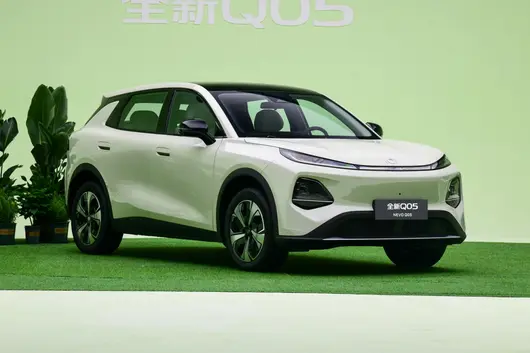
唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。

(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
 (零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
 (長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
 (零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
 (長安啟源全新 Q05)
 (零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
 (長安啟源全新 Q05)
 (零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
 (長安啟源全新 Q05)
 (零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
 (長安啟源全新 Q05)

(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。

BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.

The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.

Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.

The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.

Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.

In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.
比亞迪正式發布 2026 年 5 月產銷快報,全品牌新能源汽車單月銷量 383453 輛,同比微增 0.26%,時隔十個月實現單月銷量同比轉正;其中乘用車交付 376990 輛,環比大漲 19.4%,一掃前期車型換代陣痛,呈現國內基本盤穩固、海外銷量狂飆、高端品牌全線放量的全新格局,在國內新能源內捲加劇、特斯拉 FSD 入華、自主新品密集上市的市場環境中,走出獨有的結構性增長路線。
王朝 + 海洋兩大主力品牌 5 月合計售出 330215 輛,佔據集團總銷量超八成,仍是比亞迪銷量壓艙石,全系列共 8 款車型單月銷量突破 2 萬台,產品從 5 萬入門代步到 20 萬家用 SUV 實現全覆蓋。
王朝網內部,元家族 56691 輛、宋家族 51370 輛。雙雙跨過五萬門檻,成為品牌兩大銷量支柱,兼顧家用代步與城鄉出行需求;秦家族緊隨其後交出 28360 台穩定表現,漢、唐系列月銷維持六千級體量,深耕中大型家用轎車、SUV 細分市場;全新車型夏處於市場培育期,單月交付 1810 台,後續隨渠道鋪開有望穩步上量。
海洋網增長勢頭更為迅猛,全系五款車型跨入兩萬俱樂部:海獅 42615 台、海豹 34117 台、海鷗 39919 台、海豚 22260 台、宋 PLUS 27755 台。其中海鷗憑藉 6-8 萬親民定價穩居入門代步銷冠,海獅作為全新走量車型上市即站穩四萬量級,補齊海洋網中型 SUV 產品空白,完善海洋產品梯隊佈局。從代步小車到緊湊 SUV,兩大主品牌依托 DM-i 混動與純電雙線技術,牢牢鎖住 15 萬以內國內主流家用市場份額。
方程豹同比暴漲 139.7% 品牌向上落地見效騰勢、方程豹、仰望組成的高端矩陣 5 月合計銷售 46489 輛,正式擺脫小眾定位,成為比亞迪品牌溢價與利潤增長新支點,打破自主品牌高端化難破局的行業魔咒。
越野品牌方程豹單月 30186 輛,同比暴漲 139.7%,創下品牌上市以來月度銷量新高,旗下鎦 7 單月 18280 台,豹 5、豹 8 穩定輸出,在 25-40 萬硬派越野細分市場持續擠壓合資、進口車型生存空間。
騰勢 5 月交付 16303 台,MPV 標桿 D9 售出 6721 台,Z9 系列近 6000 台,MPV、中大型轎車雙線發力,站穩豪華新能源賽道;百萬元級超豪華品牌仰望穩步爬坡,當月交付 286 台,同比增幅 105.8%,完成自主品牌天花板產品的市場驗證,形成從十幾萬家用、三四十萬越野、五十萬豪華 MPV 到百萬元級旗艦的全價格帶產品佈局。
5 月比亞迪乘用車和皮卡海外銷量 160177 輛,同比大漲 80.7%,出口佔全系總銷量突破 42%,創下品牌出海歷史新高,成為穩住 5 月整體銷量、實現同比轉正的核心驅動力。
東南亞、歐洲、拉美成為主力增量市場,海鷗、宋 PLUS、元系列持續登頂多國新能源熱銷榜單,SHARK 皮卡連續兩月單月出口突破 4000 台;依托泰國、巴西、匈牙利、烏茲別克斯坦四大海外整車工廠落地投產,本地化生產持續落地,規避關稅同時快速下沉終端渠道。在國內車市存量競爭、價格戰常態化背景下,高速擴容的海外市場有效對沖國內車型換代帶來的銷量波動,正式從補充市場升級為比亞迪核心增長引擎。截至當前,比亞迪新能源汽車全球累計銷量已經突破 1650 萬輛,全球化版圖持續拓寬。
智駕賦能產品迭代 下半年新品蓄力衝量5 月比亞迪智能化落地迎來關鍵節點,天神之眼智駕系統成為車型核心加分項:全品牌搭載高級智駕車型保有量突破 315 萬輛,日均路測數據超 2 億公里;當月比亞迪落地城市領航、智能泊車雙安全兜底服務,成為全球首家實現兩項智駕兜底的車企,政策落地三天後,搭載天神之眼系統車型的城市 NOA 激活率暴漲 50%,智能化體驗升級直接拉動終端到店訂單轉化,為後續車型持續走量築牢產品競爭力,直面 FSD 入華帶來的智駕市場衝擊。
從數據細節來看,2026 年 1-5 月比亞迪累計銷量 1405039 輛,同比下滑 20.32%,核心誘因是全系主力車型集中換代、第二代閃充刀片電池產能爬坡受限。新款閃充電池升級快充與低溫性能,全系換代車型優先換裝新電池,但產線改造拖累產能釋放,熱門車型訂單積壓、交付延後,一定程度壓縮 5 月交付體量。
隨著二季度末二代刀片電池產能持續釋放,疊加騰勢 N8L、方程豹鎦 7 純電版、海獅 05、夏 L 等多款新車陸續登陸市場,業內普遍預判比亞迪 6 月全品牌銷量有望突破 40 萬輛。依托低端走量鎖份額、高端提利潤、海外衝增量、智能化提產品力的四維發展邏輯,在國內新能源淘汰賽加劇的當下,比亞迪全品類佈局優勢持續放大,坐穩國內新能源龍頭,加速向著全球頭部車企穩步邁進。

1405 年,大明永樂三年六月十五日。
明成祖命令四品內官監鄭和率領二百四十多艘大船,兩萬七千四百名船員組成嘅船隊出航,訪問 30 餘個喺西太平洋同印度洋嘅國家。

鄭和嘅船隊上裝滿咗青花瓷、絲綢、金銀器、香料等貿易出口商品,仲有明朝皇帝賞賜畀各國節度使嘅禮儀服飾、禮器、以及精美嘅絲織品。
鄭和指揮嘅呢支世界上當時最大嘅船隊七下西洋,其航線被後來歷史學家稱為海上絲綢之路。
600 多年後嘅今天,另一艘比這大得多嘅船再次鳴笛啟航。
只不過呢一次,船上冇精緻嘅絲綢同瓷器,而係裝滿咗汽車,新能源汽車。

中國車企嘅出海之路,從即刻開始。
01. 戰線唔會講慌
一個事實係,過去嘅 5 年入面,好多傳統品牌喺全球嘅戰略都係兩個字,收縮。
奔馳關停咗巴西乘用車工廠,福特甚至唔喺巴西生產整車,通用退出咗泰國製造,日產關閉咗西班牙巴塞羅那工廠……仲有好多歐洲工廠嘅產能利用率,甚至唔夠 10%。
接手嘅,正係從 2023 年開始,喺海外瘋狂擴張嘅中國車企們。
比亞迪喺巴西 Bahia 佈局工業基地,奇瑞透過 Ebro 重啟西班牙原日產巴塞羅那工廠,長城收購巴西原奔馳工廠同泰國 Rayong 原通用工廠,零跑、東風等品牌則透過 Stellantis 嘅現有體系,探索歐洲本土化生產。

有啲人將呢個現象,稱為出海 2.0 時代:
相比 1.0 時代嘅整車出口,中國車企唔單止敲開咗世界嘅大門,仲開始喺全球建設新嘅基地。
放眼全球,泰國已經成為比亞迪、長安、廣汽埃安、長城等品牌嘅重要生產基地,亦係東南亞同澳大利亞嘅出海「橋頭堡」;
巴西,則憑藉住比亞迪、長城、廣汽、吉利/雷諾等合作項目,輻射南美汽車市場;
土耳其依然發揮住歐亞大陸橋嘅作用,幫中國車企撬開歐洲市場同西亞地區嘅大門……

2025 年,中國新能源車出口 343 萬輛,同比暴漲 70%;純電車型出口 260 萬輛,市值約 700 億美元,同比增長 43%。
其中,有 66 個國家嘅進口額超過 1 億美元,前三位嘅比利時、英國、阿聯酋進口額分別係 66 億、59 億、35 億美元——
進口商品嘅購物車入面,每湊夠 300 萬美元,就要配上一台中國電動車。

如此瘋狂嘅出口增長,顯然動咗太多人嘅奶酪。
歐盟嘅反補貼調查同加徵關稅,就係前車之鑑。
因此,本地建廠就成為咗中國車企出海嘅唯一解。既能規避關稅風險、降低物流成本,仲能進一步接近終端用戶,亦能滿足當地對於就業同稅收嘅政策要求,一石三鳥。
據不完全統計,呢份中國車企收購同新建工廠嘅表格,真係好長。


從數據嚟講,2022 至 2024 年呢 3 年時間入面,中國企業喺新能源車價值鏈嘅海外直接投資年均達 304 億美元,首次超過國內投資。
戰報會講慌,戰線唔會。敏銳嘅資本,一定會將錢投入到利潤更高嘅地方去。
但正如嗰句話所講,命運贈送嘅禮物,早已喺暗地標註好咗價格。
02. 外國人嘅錢,好賺㗎?
據乘聯會數據顯示,2026 年第一季,汽車行業整體利潤率下探到咗 3.2%,遠低於下游工業 6% 嘅水平,相比前幾年更加係直接腰斬。
卷到麻木嘅車企,或主動或被動地,將眼光投去咗競爭唔飽和嘅海外。
但對於中國車企嚟講,海外建廠、收購舊工廠、接手閒置產能,並唔係簡單地將國內成熟模式複製出去,而係進入咗一個法律、工會、供應鏈、政策同品牌輿論都完全唔同嘅體系。
呢度亦同樣暗藏殺機。

前幾日,國際能源署 IEA 推出咗《Global EV Outlook 2026》研究報告。其中有一項數據,格外令人深思:
截至 2025 年,中國車企嘅海外年產能達 170 萬輛,其中泰國佔比超 30%,印尼超 20%,佈局嘅重點都係喺東南亞。
但問題係,呢兩地嘅產能利用率只有 20% 同 15%!
呢點即係話,中國車企海外擴產,面對嘅第一個風險就係:一旦銷量撐唔住,就係產能過剩。要么工廠閒置,要么減價促銷。
第二個風險點係,低價接盤來嘅舊工廠可能並唔係撿漏,而係歷史包袱。

好多工廠被車企無情拋棄,並唔一定係因為銷量唔振,仲有生产效率低下、設備老化、車型平台唔啱、生产成本居高不下等等。
以俄羅斯為例,日產同大眾撤出之後,其舊工廠被俄羅斯本土企業 Vaz(亦即係我哋知道嘅伏爾加)汽車廠所管理。
該廠生產嘅拉達汽車技術老化,甚至欠缺生產新能源車所需嘅高壓操作環境。連員工都係做咗一世燃油車嘅技術工人,根本搞唔明新能源平台同快節奏生產。
如果要重新搭建生產新能源車所需嘅三電系統、軟件標定、電子電氣架構、熱管理同高壓安全體系,改造成本同建一座全新工廠一樣,產線、質素體系、供應鏈、人員培訓……都要重新調整。
第三個就係工會同合規風險,會俾好多企業嚴重低估。

大家喺國內習慣咗嘅高強度、高回應速度同集中式管理,並唔可以喺海外簡單複製。習以為常嘅宿舍上下鋪,甚至都會引發勞工合約、住宿同用工條件嘅調查。
由於好多國家嘅工會權力極大,一旦組織罷工,對生產嘅衝擊將無法再大,甚至會影響未來嘅工廠審批、政府補貼、公眾輿論、投資者關係同品牌形象。
第四個風險,來自供應鏈:整車本地化容易,核心零部件本地化好難。
一輛新能源車嘅競爭力,核心唔喺總裝工廠,而係一整套從三電到熱管理、從電子電氣架構到軟件、從輪胎到車窗嘅成本控制能力。

中國車企,可以喺海外快速建立總裝廠。
但關鍵零部件仲係要由中國進口,問題就嚟咗——
物流週期長,庫存成本高;匯率波動影響成本;關稅比例可能隨時調整;當地售後備件供應壓力大;如果政策十分緊張,電池、晶片呢啲關鍵零部件,仲要接受審查。
冇錯,同歐洲車企喺电气化轉型時,遭遇嘅「被中國電池卡頸」嘅情況一樣。
最後一個風險,就係產能利用率同市場導向嘅風險。
就好似前面提到嘅,東南亞市場規模細、消費能力差。喺當地廉價嘅建廠方案,什麼時候先至可以跑滿產能?
而有消費能力嘅歐洲,已經緊急撤回咗「2035 禁售燃油車」嘅法案,歐洲車企即將回歸燃油車、甚至係大排氣燃油車嘅生產。

到嗰陣,回歸傳統燃油車嘅歐洲市場,仲有冇中國車企嘅一席之地?
呢啲,都係準備出海嘅中國車企們,所必須考慮嘅。
03. 一切過往,皆係序幕
對任何一家全球企業嚟講,出海呢件事,都一定係挑戰同機遇並存。
40 年前入華嘅大眾,10 年前入華嘅特斯拉,近幾年喺全球「開枝散葉」嘅 BYD、GEELY、GWM……無一例外。
幸運嘅係,拋開技術優勢、成本控制能力同完備嘅零部件供應鏈唔論,中國車企仲有最得天獨厚嘅一個優勢:用戶。

剛剛過去嘅 4 月,比亞迪喺英國賣出咗 12754 輛純電車,超越特斯拉榮膺純電銷冠;奇瑞則係憑藉三品牌戰略,成為唔加修飾語嘅全品類銷量第二名,僅次於大眾。
喺呢類冇關稅設限、車企可以公平競爭嘅國家同地區,物美價廉嘅中國車,就係用戶「踏實過日子」嘅不二之選。
600 多年前,鄭和率領船隊七下西洋,以東方文明嘅氣度連接海洋、貿易同遠方;
600 多年後嘅今天,中國車企亦正式開啟咗屬於自己嘅「大航海時代」。
由歐洲到東南亞,由南美到中東,由整車出口到海外建廠,由收購舊廠到重啟閒置產能,中國汽車正沿住新嘅全球航線,駛向世界產業體系嘅深處。
呢場遠航,標誌住中國汽車工業從追趕者走向參與者,從參與者走向塑造者嘅歷史性轉身。
誠然,中國車企要面對更複雜嘅全球市場、法律法規、勞工關係、供應鏈體系,亦需要喺產品之上,由零搭建品牌信任。
但屬於中國車企嘅 One Piece,先至剛剛啟航:

嗰啲被重新點亮嘅海外工廠,嗰啲重新轟鳴嘅產線,嗰啲跨越國界嘅投資同合作,既係中國製造實力嘅證明,亦係中國車企融入世界、承擔責任、共建產業生態嘅里程碑。
未來,仲可唔可以真正成為全球汽車工業嘅重要建設者,取決於中國車企可唔可以喺唔同嘅文化背景之下扎根,喺唔同嘅市場贏到信任,喺大陸同大陸之間建立合作。
一切過往,皆係序幕。
新嘅航路已經展開,真正嘅遠航先至剛剛開始。


In Autumn 1958, SAIC's automotive history began in a "lane-side workshop".
Without large machine tools or manufacturing bases, the first generation of car builders relied solely on disassembling overseas sample vehicles. With just hammers in hand, they hammered out car bodies and sheet metal. Prior to "National Day" that year, Shanghai's first "Phoenix" sedan officially rolled off the line and went to Beijing for the parade. This car, forged in the most primitive handmade style, completed SAIC's leap from 0 to 1.
Everything at SAIC Group started with this "Phoenix" sedan.
But what truly moved me was not those old business stories of "golden phoenixes hatching from grass nests", nor the countless industry records created in the past; but rather why, 71 years later today, facing unprecedented technological changes, SAIC can still lead the way into the "100-million club" and demonstrate strong vitality and calling power in the game of static market stock.
In China's and even global business history, manufacturing enterprises that can span decades and reach a 100-million volume level are rare. Previously, only Toyota, Volkswagen, General Motors, Ford, Honda, Nissan, and Hyundai had crossed this threshold.
SAIC is the eighth and also the first Chinese brand. Under the wheels of the times, countless once-glorious companies fell like meteors. SAIC Group with 71 years of automotive foundations is absolutely a corporate sample worth deep study.
How did one enterprise "fight" for 71 years?
Today's business world is obsessed with "speed". Brands are keen on creating concepts, grabbing windfalls, and betting on short-term hit products. Under the drive of capital discount rates, countless enterprises are struggling to run in the shroud of algorithms.
But in the eyes of SAIC Group that has traversed long cycles, the business world has another set of heavier logic: not looking at windfalls, but only at the era's "topic/questions".
SAIC's ability to cross a 71-year long cycle lies in the fact that it has always been in sync with the pulse of the times. It never acts as a speculator of windfalls, but rather as the writer of every era's topic. When we trace back each breakout by SAIC at key nodes, we can understand why it became the first automotive group in China to cross the "100-million" threshold—those openings written in history are essentially the most accurate responses of SAIC to the anxieties of that time.

Starting from a lane-side workshop in the 1950s, to taking the road of reform and opening up first in the 1980s, after 6 years of difficult negotiations to establish China's first passenger car joint venture SAIC Volkswagen, to creating the "Shanghai Speed" of 23 months from factory construction to vehicle delivery in the 1990s via SAIC GM deepening joint venture cooperation, to strongly attacking the independent brand in the early 2000s, to actively implementing national instructions in the last decade and leading the comprehensive transformation to new energy... In nearly a century, SAIC experienced the transformation of the planned economy, the baptism of the market economy, the impact of the globalization wave, and the ruthless involution in the deep blue waters of intelligence and electricity today. Every technological iteration and industry reshuffle was a "life-or-death" moment, but SAIC stood steadily on the wave of the times every time.
SAIC inherited in the wave of the times is anchored on the "understand cars better understand you" causal chain with low variables and high reuse. Because no matter how drastic the external environment changes, human desire for beautiful mobility, certainty pursuit of high quality and safety, will not change due to dynastic changes or technological revolutions. People in the past needed a reliable fuel car to shelter from wind and rain, people today also need a smart cockpit with communication understanding and high safety.

When such precise response to user needs is repeatedly verified, classics are formed.
In 1983, the first Shanghai Santana sedan was successfully assembled, not only allowing Chinese families to use world-class quality cars, but also driving the domestication enlightenment of the entire Chinese auto parts system; In 2016, SAIC and Alibaba cross-boundary cooperation launched the world's first mass-produced Internet car Roewe RX5, letting cars evolve from cold mechanical tools to intelligent terminals with temperature; Until today, whether it is the Roewe i6 with 60,000 yuan level standard Qualcomm 8155 chip and Doubao Large Model, or the Shangjie Z7 with whole series standard Huawei Qiankun Smart Driving ADS 4.1 and 896-line LiDAR, or the Huajing S bringing high-level smart driving into the 150,000 yuan level family market, SAIC is always responding to consumer expectations with practical actions of "equity-driven advancement".
For every car delivered, there is one more point of trust. When this utility is verified 100 million times, trust becomes the most solid competitive barrier.
We can see the closed loop of this causal chain in countless users' real lives.

At the SAIC Volkswagen Anting base, the 99,999,999th new car delivered—Volkswagen ID.ERA9X—its owner is former German men's football national team player Yang Chen. As the first Chinese player to land in the Bundesliga, Yang Chen's life has always carried a resilience of "dare to move forward, also need to be steady". He witnessed instantaneous changes on the field, firmly believing that true strength is never a flash in the pan, but long-term trust and solidity. His choice of the flagship SUV of SAIC Volkswagen's new new energy sequence is exactly this long-termism life background and German exquisite car-making craftsmanship deep resonance.
Similarly spanning time and space is also Natalia, an intern doctor in London, UK. That classic MGB sports car of her grandfather was her childhood's most shining memory, this emotional bond prompted her to become the owner of MG4EV Urban. Two generations, two cars, one brand, this is the perfect fusion of classic inheritance and contemporary lifestyle.
Whether in the East or West, time has verified quality, quality precipitated trust.
Opposing "Organizational Entropy Increase", Reshaping Industrial Base with System "Negative Entropy Flow"
Grand delivery numbers are just the result on the water surface, what truly supports the 100-million building underneath is the extremely rigorous industrial moat of the enterprise for decades.
In physics, there is a hopeless "Law of Entropy Increase": Any closed system will spontaneously move from order to disorder, eventually returning to chaos.

The automotive industry is exactly a huge quagmire easy to fall into "Entropy Increase"—when tens of thousands of parts, millions of industrial workers, and long time lines intertwine, human nature's fatigue, compromise, and "good enough" farming thinking, will let the huge production line go out of control like a virus.
All multinational auto companies in the world, always doing one thing is maintaining the high order of the system and product consistency.
In 1987, when SAIC was fully attacking Santana domestication, the supporting parts enterprises were still full of crude workshop habits. SAIC did not first preach grand quality strategies, but unexpectedly launched a "hygiene reform" across the entire group—forcingly installing toilet paper rolls and dryers in restrooms.
In the "Broken Windows Theory" of criminology, an unpatched broken window will condone more destruction. SAIC sharply noticed that employees using newspaper to defecate causing pipelines to clog repeatedly, was the most dangerous "broken window" in the large industrial system. If the enterprise condones this most basic disorderly behavior, then on the micron-level precision assembly line, compromise on errors will inevitably breed.

This detail "Toilet Reform" was the first "Negative Entropy Flow" injected by SAIC into old farming habits, it reshaped the behavior bottom line of modern industrial workers in an almost fanatical way.
And when facing the temptation of huge commercial interests, SAIC showed the extreme "Instrumental Rationality" advocated by Max Weber—to pursue absolute standards, dare to cut off all emotional ties and sunk costs.
In 1998, as the main force of SAIC core parts autonomous upward, Yanfeng Company, to attack Buick supporting project, specifically invested 600 million to build new factories. When the first batch of completed bumpers were sent to quality inspection, it actually reached the conventional international standard of no more than ten dust fall points per square centimeter.
However, when the joint venture foreign party proposed the harsh requirement of "fall points cannot exceed five", under the heavy pressure of huge sunk cost and delivery cycle, human nature's instinct is usually to find excuses for compromise. But the General Manager of Yanfeng Company at that time, in front of everyone's eyes, brought out a saw, and cut the huge cost bumper into two halves on the spot. "Things customers don't want, must be sawed off!"
This saw, not only sawed off unqualified products, but also Chinese local manufacturing's accumulated "human society" and "get by" path dependence over the past few decades.
This violent demonstration of destroying high-value assets to defend absolute standards, instantly cleared the system internal gambling mentality, letting "craftsmanship spirit" instrumental rationality completely overcame human nature's weaknesses.
This gene of iron-fisted opposition to entropy increase, has been strictly continued to today's smart electric track.

SAIC self-developed "Zero Combustion Magic Cube Battery", its core key technology is why able to win the Second Prize of State Science and Technology Progress Award, is exactly built on redundancy safety rules 6 times higher than national standard limit tests.
When modern capital is obsessed with short-sighted high turnover, SAIC uses defenses built for decades to stubbornly guard this seemingly "clumsy" principle.
100 million car deliveries, far from accidental time compound interest, is this giant enterprise success over 70+ years, successfully fought off 100 million times system entropy increase necessary result.

This system resilience opposing entropy increase, also reflects in SAIC current market performance. Just passed May, SAIC Group whole vehicle sales 349,000 vehicles, Jan-May cumulative 1.651 million vehicles, continuing to lead Chinese auto industry. Independent brand proportion first time broke 70%, new energy vehicles surged 46.5%, overseas market surged 45.9%. 100-million historical marker and current sales leading, jointly verify SAIC full-link competitiveness from system to market.
Seeing All Beings, Eco-Winning Era Foresight
In the movie "The Grandmaster" there is a very transparent line, martial artists have three realms: "See Self, See Heaven and Earth, See All Beings".
Today SAIC stands at the era gateway of 100 years unprecedented great changes in automotive industry. It cannot only be self-satisfied in the long river of history and glorious merit roll, it must stand up to "See All Beings". Its opponents are no longer any specific peers, but technology leap gaps, and those static self-sealing, closed-doors-to-build-cars island effects.
This is the most ruthless elimination era, also the best co-creation era.

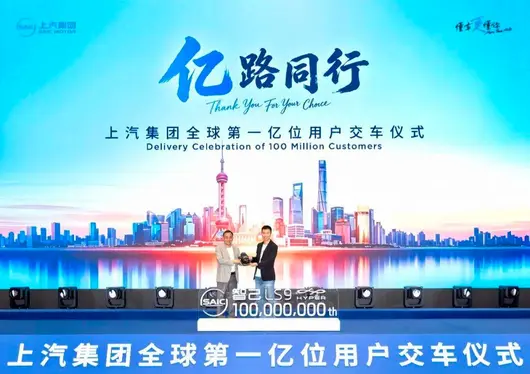
At the Delivery Ceremony on May 28, 2026, appeared an extremely deep meaning, can even be recorded in Chinese auto history scene: SAIC handed that representing group 70 years car-making foundation and forefront technology collection complete the world 100 millionth car—IM LS9 Hyper, solemnly handed to deep strategic partner Momenta CEO Cao Xudong.
Partner become owner, is SAIC "See All Beings" most vivid, most earth-shaking footnote.
Cao Xudong stated on site, Momenta L3 Level autonomous driving ability will launch on SAIC first, he not only will personally drive this car, more plans in development process first use it to verify test.
To thoroughly break technical walls, SAIC resolutely gave up traditional host plant attempt to take full responsibility "soul obsession", firmly chose "open to the world, beauty shared together" open ecosystem.
With Huawei Qiankun comprehensive deepening strategic coordination, not only launched new brand "Shangjie", but also let Huajing series become 150,000 yuan level full series standard Huawei Smart Driving breakthrougher; With Audi signed cooperation agreement, based on next generation intelligent digital platform jointly develop 4 AUDI new high-end intelligent electric new cars, opened Chinese technology reverse empowering foreign brand "Joint Venture 2.0" era; With Momenta deep co-create smart driving large model, and let this set industry first tier scheme horizontal empower to IM, Volkswagen, Audi, Buick, Cadillac multiple brand matrix.

And joint venture new energy also welcomed strong return. May SAIC GM new energy vehicles sales 13,000 vehicles, year-on-year surge 75%, Zhijing E7 launch first month delivery broke 10,000. May SAIC Volkswagen new energy vehicles sales nearly 10,000 vehicles, year-on-year growth 34.3%; New launched ID.ERA 9X cumulative delivery exceeded 7,000 vehicles; At end of May Greater Bay Area Auto Show, equipped with new generation "Golden Super Mix" technology Tiguan L ePro, Passat ePro, and Audi Smart Performance Flagship SUV AUDI E7X sequentially launched.
SAIC knows, true "Understand You", needs gather global top wisdom, no technical walls, no do ecological island.
Not only in domestic, in vast overseas market, SAIC also in practicing "See All Beings" grand narrative.

2025 released "Glocal (Global + Local) 3.0 Strategy", marks SAIC from single product export thoroughly to systematic globalization leap. In Europe, MG use Frankfurt European Engineering Center for deep localization customization R&D; In Southeast Asia, SAIC Maxus let Deliver 5 pure electric logistics vehicle batch delivery to DHL Senior VP, help this global logistics giant Singapore realize green upgrade; In commercial vehicle going abroad strategy, SAIC not only set sales growth over 50% grand target, but also overseas dealer historical positioning upgraded to "co-existing win-win wealth creation partner", and in Europe heavy asset weave global parts warehousing network. SAIC globalization, no longer simply selling cars, but with global industry chain and ecosystem deep integration.
"See All Beings" background color, more lies in to each ordinary individual warm protection.
At Delivery Ceremony, the 100 million 100th owner identity especially attracted attention—he is public welfare life class self-media "Western Heroes" blogger Liu Jia. This ordinary barber, 5 consecutive years rain or shine driving deep into Guangxi mountains, only to give left-behind children haircut, send company. When his old car broke down on mountain road, Buick first time reached out help, and invited him experience having South German TÜV Eye Protection Smart Roof Light and Zero Formaldehyde Certified Buick Zhijing E7 "Full Marks Cockpit". SAIC give this "100%" respect to Micro-light Guardian, let this 100th car became to "Guard" value most warm echo.
Same story also happened in Shaanxi Lantian 85 born village secretary Pang Fuqiang. To give 74 left-behind elderly meal delivery, he everyday persist running 8-9 kilometers, SAIC-GM-Wuling through "Striver Special Plan" for him delivered a Rongguang Electric Version Micro Van, with practical action salute grassroots strivers.
Enterprises that can cross cycles, are all stick to original intention, and actively embrace ecosystem, care society enterprises. When an enterprise can extract the essence of breakthrough and quality in history sorting, and let go of the greed of technological exclusivity in the torrent of the times, spreading the dividends of technology to the broadest audience, this is the enterprise's most substantial strength.
In 1958, a broken old hammer, hammered out the historical legend of major power auto industry in an alley workshop. In 2026, a relay delivery spanning Asia-Europe continent, connecting Shanghai, London, Jakarta, Singapore, witnessed 100 million trusts magnificent convergence.
Time will ruthlessly eliminate all capital bubbles and technology gimmicks that cannot withstand testing, then cast what remains into an unshakable base.

An enterprise able to complete 100-million vehicle era feat, rely on not only production line crazy stacking, rely on a industrial civilization resilience—that dare to publicly saw off unqualified bumper extreme reverence, that no set technical walls, with whole industry open co-creation broad mind, that from alley workshop all along struggle, finally 21 times entered Fortune Global 500 self-evolution.
TCM often says "Righteousness exists within, evil cannot invade", enterprise development is also so. Those enterprises that fell down in the time torrent, often not by external opponents defeated, but by internal urgent benefit "evil fire" swallowed.
100 million vehicles never was SAIC high song rapid progress end point, but from "scale leading" toward "ecological leading" new starting line. When system "Righteousness exists within", time no longer be step-by-step pressing enemy, but most loyal "Partner".
We have absolute reasons to believe, in smart electric new era magnificent second half, this "100-million vehicle auto maker" still possess generations passed down, endlessly magnificent reserve power.

港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。

喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。

天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。

截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。

喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。

2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。

喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。

截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。

營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。

更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。

此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。

天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。

繼上海、廣州、長沙三場演出圓滿結束後,6 月 13 日,由長安啟源獨家冠名嘅曹格「打開耳朵聽我講」巡迴演唱會,落戶品牌大本營——重慶。本次活動以“熱辣滾燙、格局打開”為傳播內核,結合重慶獨有嘅城市風情,打造出沉浸式體驗現場,兼具觀賞性、互動性與傳播性。呢間國民汽車品牌借此拉近與年輕群體嘅距離,用新穎嘅溝通形式完成流量轉化與品牌理念植入,樹立起汽車行業跨界營銷嘅優秀範例。
熱辣同頻:國民品牌與實力歌手嘅雙向合作
而家新能源汽車市場嘅競爭,早已唔再侗限於硬件參數比拼,品牌情感價值與人文溫度成為角逐關鍵。音樂作為全民通用嘅交流語言,係品牌對接消費者、建立深度連結嘅優質載體。長安啟源揀選聯手實力唱將曹格,正係一場兼顧情感共鳴與受眾匹配嘅優質跨界。

曹格喺樂壇深耕多年,《背叛》《寂寞先生》等曲目傳唱度極高,既係 80、90 後嘅青春回憶,亦收咗當下年輕群體嘅喜愛,國民口碑與新生代影響力兼備。作為長安汽車數字化轉型嘅核心品牌,長安啟源定位國民高品質新能源汽車,目標客群熱愛生活、追求用車品質。佢哋樂意體驗智能出行新科技,亦重視情感陪伴,對音樂、演藝內容抱有濃厚興趣。基於高度契合嘅受眾定位,雙方以音樂為橋樑、以熱愛為共識,令品牌溫情打破圈層壁壘,實現品牌、產品與消費者之間嘅深度情感連結。
潮流出圈:山城特色與實車體驗巧妙融合
從上海、廣州到長沙,長安啟源依托音樂 IP 嘅傳播力以及曹格嘅個人影響力,持續探索同年輕用戶溝通嘅全新場景。每一站演唱會,唔僅係視聽盛宴,更係品牌與粉絲面對面交流嘅契機,持續傳遞“讓移動嘅家幸福滿格”嘅品牌初心。

本次重慶站,長安啟源充分發揮本土主場優勢。重慶熱情豪爽嘅城市標籤、高低錯落嘅山城地貌,再加上呢座網紅城市自帶嘅打卡傳播屬性,為线下場景營銷奠定咗良好基礎。現場以熱烈嘅紅色為主視覺打造主題展區,將山城氣質同品牌年輕化表達相結合,視覺記憶點十足。

現場唔僅設置明星合影打卡區,讓觀眾、粉絲同品牌近距離互動,仲結合潮流改裝文化,打造全新 Q05 個性塗裝體驗區,契合年輕人社交分享嘅習慣,令品牌熱度持續攀升。長安啟源將山城特色、熱烈氛圍、網紅傳播屬性融入线下展區與互動環節,讓新车成為可觀賞、可合影、可分享嘅潮流元素,一步步讓年輕消費者從認識品牌,到牢牢記住品牌。

放眼全球:國內市場熱銷,穩步開拓海外版圖
作為長安汽車數字化轉型嘅重要板塊,長安啟源堅守“國民精品新能源品牌”嘅定位,憑藉有擔當、有溫度、有實力嘅品牌形象,持續挖掘用戶價值、傳遞品牌溫度。喺重慶演唱會現場,全新 Q05 全程相伴,喺觀演出行、現場互動中,不斷詮釋“讓移動嘅家幸福滿格”嘅品牌理念。
值得一提嘅係,全新 Q05 係品牌面向全球市場打造嘅主力車型,三電系統穩定可靠、智能配置領先、空間表現越級,憑藉出眾產品力成為全場焦點,亦完美詮釋咗“國民精品”嘅定位。

呢款車型市場表現亮眼:5 月長安啟源全系車型累計交付 34528 台,其中全新 Q05 單月交付 15954 台,再度拿下緊湊型 SUV 銷量榜首;5 月 28 日呢車登陸泰國市場,上市僅 3 日訂單就突破 3000 台,爆款實力從國內延伸至海外。
深耕跨界:多維聯動助力品牌穩步進階
長安啟源攜手曹格開展巡演合作,並非簡單嘅品牌曝光,而係採用“IP 深度綁定 + 屬地場景定製 + 產品落地轉化 + 用戶長效運營”嘅綜合策略,搭建起獨一無二嘅跨界營銷模式,構建出音樂 + 名人 + 品牌 + 產品 + 用戶五位一體嘅營銷閉環,亦成為長安汽車数字化品牌轉型嘅標杆項目。重慶站落幕之後,巡演仲將走進合肥,持續釋放跨界價值,助推品牌發展。

回望長安啟源嘅品牌發展之路,跨界營銷早已成為長安啟源品牌鮮明底色。從認養國寶莽燦燦、攜手銅梁龍足球、葡萄牙國家隊,到殲 10C 跨界聯名、《憤怒嘅小鳥》全球化 IP 共創,此次又將音樂演出、城市文化、用戶場景深度結合。長安啟源始終圍繞大眾興趣與日常出行場景開展跨界合作,不斷豐富互動形式。未來,品牌將繼續以優質產品同貼心服務為根基,完善跨界運營體系,加深同消費者嘅情感連結,攜手用戶共赴智能出行新征程。

港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。
喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。
天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。
截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。
喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。
2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。
喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。
截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。
營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。
更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。
此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。
天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。
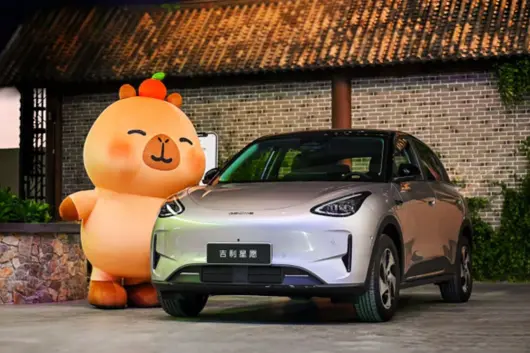
6 月 1 日,吉利汽車正式發表 2026 年 5 月銷量成績單:全集團總銷量 237637 輛,實現連續三個月同環比雙增長。
今年車市整體唔算輕鬆,唔少品牌都要承受壓力調整,喺車市整體承受壓力、行業競爭加劇嘅背景下,吉利卻走出咗自己嘅節奏,穩中有進、越跑越順。尤其新能源板塊,5 月賣咗 133355 輛,滲透率直接沖到 56.1%,連續 4 個月過半,實打實站穩新能源主賽道。

而喺呢份亮眼數據入面,吉利星願絕對係全場最亮眼嗰一個——5 月單月 36426 輛,佔銀河近 45% 銷量,妥妥嘅頂流擔當。
一、5 月全線飄紅,星願撐起半壁江山
5 月,吉利旗下四大品牌齊發力:吉利品牌 182528 輛、領克 20732 輛、極氪 34377 輛,高端化、全球化、年轻化三條線同步都在健康持續發展。
作為集團新能源主力,吉利銀河 5 月銷量 81727 輛,而星願一個車型就貢獻咗 36426 輛,差不多每賣出兩台銀河,就有一台係星願。佔銀河品牌近 45% 份額,係當之無愧嘅銷量擔當。呢個成績唔係運氣,而係長期市場口碑同產品力沉澱嘅必然結果。

自上市以來,星願嘅熱度就冇掉過:573 天累計交付突破 70 萬輛、每分鐘賣出一台,穩居 2025 年中國車市全品類銷量冠軍;2026 年更係一季度便沖進全球新能源前三,成為咗中國品牌唯一進入全球前三嘅車型。
從家用代步小車,到全球都认可嘅爆款,星願一步步把“中國小車”做成咗世界名片。
二、全新星願煥新上市,6.18 萬起五大冠軍實力拉滿
5 月 28 日,全新星願正式上市,限時權益價 6.18 萬 -9.18 萬元,冇虛頭巴腦嘅噱頭,冇套路式配置,以超 100 項產品力升級、25 項同級唯一嘅硬核實力,以上市即夯爆嘅市場熱度,再度定義 10 萬級純電小車標杆。這次升級就係一句話:把用戶最在意嘅點,全部拉滿。

1. 三電升級:續航快充雙頂尖
全新星願全係續航上調,最高 CLTC 續航 480km(老款 410km),日常通勤無焦慮;同級唯一全係標配寧德時代電芯 + 液冷溫控+11 合一高集成電驅,30%-80% 快充僅需 19 分鐘,一杯咖啡時間滿電出發,補能效率同級天花板。
2. 駕控越級:原生後驅 + 賽道級調校
好多人覺得便宜小車唔好開,但星願直接打破偏見:全新星願係同級首個採用全球化原生架構、標配後驅與獨立懸架嘅純電小車,底盤穩、轉向靈、易開好泊。

中德聯合賽道級調校,操控穩定性同靈活性兼備,麋鹿測試 80.7km/h、魚鉤測試 130km/h 成功通關,操控表現媲美 20 萬級運動轎跑;G-TCS 2.0 全天候防滑系統、G-CST 2.0 全場景舒適制動,不僅新手能輕鬆駕馭、老司機都開出樂趣。
3. 智能拉滿:Flyme Auto 2+ 千里浩瀚 H3
座艙智能全面進階,搭載銀河 Flyme Auto 2,7nm 龍鷹 1 號晶片+16G+128G 大儲存,操作絲滑流暢。AI Eva 語音助手支援模糊指令、上下文記憶,車控娛樂一鍵搞定。更搭載千里浩瀚 H3 智駕方案,高速 NOA、全場景 APA 泊車、HPA 記憶泊車(2km 超長記憶),13.8 億公里安全行駛驗證,越開越智能、越開越安心。

4. 安全不妥協,小車也有大安全
星願一直強調:“小車更要有大安全”,全新星願用咗五縱八橫星甲籠式車身,車頂抗压強度達 3.4 倍車重,碰撞時能最大程度保護乘員艙。

電池安全更係嚴上加嚴:國標 2 倍測試標準、1000 次循環容量仍有 90.72%,通過央視同級唯一正面 + 側面連續碰撞測試,高壓系統及時下電、電池不起火、乘員艙不變形,守護每一次出行。同時標配 DOW 開門預警、AEB 主動煞車、哨兵模式,主被動安全全面拉滿,俾用戶滿滿嘅安全感。
5. 出圈海外,成中國智造名片
星願不僅國內領跑,海外市場更係“中國智造”名片,已登陸全球 30+ 國家同地區。巴西上市 2 個月賣咗 2300 多台,泰國車展單周訂單 3300 台;拿下巴西年度最佳緊湊型電動車、印尼車展最受喜愛電動車,中國小車,正喺世界舞台發光。
三、新能源滲透率 56.1%,星願係增長核心
5 月,吉利新能源滲透率達 56.1%,連續四個月多突破 50%,轉型速度同質量都走在行業前列。能做到這一點,星願功不可沒。佢精準卡喺 10 萬級最主流市場,冇盲目跟風價格戰,而係靠實打實嘅產品力贏得用戶,以 6.18 萬起親民價格 + 越級產品力,打破“低價低質”固有認知,用高質優價打動千萬家庭;憑藉成熟可靠嘅三電、安全穩定嘅品質、智能好用嘅體驗,持續積累用戶口碑,形成“買 10 萬級純電小車,優先選星願”嘅市場共識。

總結:
從 5 月單月 36426 輛,到累計 70 萬輛;從中國冠軍,到全球前三。星願冇靠噱頭出圈,而係一步一個腳印,用續航、快充、駕控、智能、安全五大硬實力,征服咗千萬用戶,亦成為吉利高質量增長嘅底氣。
喺競爭越嚟越激烈嘅車市,吉利能連續三月雙增長、新能源滲透率過半,離唔開星願這樣嘅爆款車型。未來,全新星願會繼續深耕 10 萬級市場,把越級體驗帶畀更多家庭,亦助力吉利喺新能源賽道上跑得咁穩、更遠。
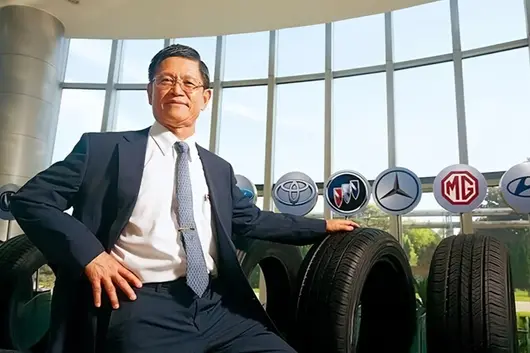
On May 26, Taiwanese tire giant Cheng Shin Rubber convened a shareholders' meeting, successfully completing a full board re-election and facilitating a leadership handover within the core executive team. Luo Cairun, the founder's second son, officially succeeded Chen Ronghua as Chairman. Former General Manager Li Jinchang was promoted to Vice Chairman, while the General Manager position was taken over by Luo Yuanlong, representing the "third generation reinforcements" of Cheng Shin. This move marks that Cheng Shin Rubber has officially entered a new stage of generational succession and strategic upgrade.

Core Management Team Settled: Veterans at the Helm and New Talents Leading the Way
This high-level change reflects Cheng Shin Rubber's succession mindset of "seeking progress while maintaining stability." New Chairman Luo Cairun (born 1953, from Changhua, Taiwan), who spent many years working extensively on the front line early in his career, previously served as General Manager and Chairman of Cheng Shin Tire (China), and is extremely familiar with the mainland China market. According to relevant data, Luo Cairun's family wealth reached 19.5 billion Yuan.

Li Jinchang, promoted to Vice Chairman, was the former General Manager, and his rich experience in management and operations will continue to safeguard the group; meanwhile, the appointment of new General Manager Luo Yuanlong represents the third-generation successor of Cheng Shin formally stepping into the spotlight, shouldering the heavy responsibility of front-line operations.

In the new board of directors lineup, besides the above three core members, it also includes Cheng Shin President Chen Xiuxiong, Merida Chairman Zeng Songzhu, and Chen Hanqi. Independent directors are composed of Wu Zhongshu, Zhu Boyong, and Xu Jiezhong, with professional backgrounds covering macroeconomics, corporate strategy, and other fields, providing an independent perspective for corporate governance.
Targeting the Global High-end Market, Establishing Four Core Growth Engines
Facing fierce competition in the global automotive industry and tire market, Cheng Shin Rubber's new management team has clarified the strategic direction and formulated four core growth engines to drive future performance:
Breaking into the European High-end Automotive Supply Chain: Continue to deepen OEM cooperation with top global automakers, enhancing the brand's penetration and voice in the high-end vehicle market.
Developing High Value-added Products: Focus on the R&D and manufacturing of high-performance tires, optimize product structure, and improve overall profitability.
Deploying Major Forces in the Indian and Indonesian Markets: Position South Asia and Southeast Asia as key growth poles, seizing the demographic and automotive volume dividends of emerging markets.
Digitalization empowering competition tires: Using digital technology to develop sports and competition tires, using track-level technology to feed back to the civilian market, ensuring the company's leading position in the technical field.

Deep Cultivation in the Mainland and a Billion-Yuan Empire
As a large manufacturer in the global tire and rubber industry, Cheng Shin Rubber's China operational headquarters is located in Kunshan, Jiangsu, and its "Cheng Shin/Maxxis" brand has already achieved extensive global influence. In 2024, Cheng Shin Rubber's annual revenue reached 96 billion New Taiwan Dollars. Under the drive of the new management team and four engines, whether this old tire giant can achieve a leap on the new track of high-endization and globalization is worth continued industry attention.