首頁香港

搜尋歷史
熱門搜尋
經銷商登入 / 註冊


玲瓏輪胎 (601966.SH) 曾寄予厚望嘅「7+5」全球戰略,正面臨全面擱淺。2026 年 5 月,玲瓏輪胎喺短短 5 日內先後宣佈終止陝西銅川、巴西兩大新建項目,加上安徽項目嘅擱置,公司擴產阻礙重重。玲瓏輪胎誓言:到 2030 年,產銷量達到 1.6 億條,銷售收入超過 800 億元,產能規模目標為世界前五。如今來講,玲瓏輪胎呢啲目標顯得遙遙無期。
 力爭產銷量達 1.6 億條
4 月 28 日,玲瓏輪胎喺發布嘅 2025 年年報中表示,「我哋會繼續堅定推進『7+5』全球戰略布局,依托國際化生產基地,攜手全球合作夥伴,致力於產品品質躍升、供應鏈精益管理及技術創新突破,共同推動產業鏈協同發展,積極構建開放、多元、包容嘅合作生態。」

6 年多來,玲瓏輪胎嘅「7+5」全球戰略曾經歷過「升級」,但如今恐怕要「破產」。
2020 年 3 月,玲瓏輪胎發布中長期發展戰略規劃(2020-2030 年)綱要,綱要明確指出,隨著玲瓏輪胎業務嘅不斷拓展、公司規模嘅不斷擴大,公司先前嘅「5+3」發展戰略已唔滿足公司发展需求,為推動製造、銷售、服務本地化,更好嘅貼近用戶同市場,細分市場,提高佔有率,實施「6+6」發展戰略,即:國內六個生產基地,海外六個生產基地,到 2030 年產銷量突破 1.6 億條輪胎產能。
彼時,玲瓏輪胎喺國內已擁有招遠、德州、柳州、荊門四個生產基地。
2021 年 6 月,玲瓏輪胎將原「6+6」戰略變更為「7+5」戰略,其中陝西銅川基地立項。
2021 年 12 月 14 日,玲瓏輪胎中國第五個、全球第七個生產基地—吉林玲瓏輪胎有限公司全鋼一期首條輪胎下線儀式喺長春舉行。
同時,玲瓏輪胎國內兩大擬建嘅生產基地分別喺銅川同合肥。而且,玲瓏輪胎已擁有泰國同塞爾維亞兩個海外基地,並喺巴西規劃建設第三個海外工廠。
「7+5」戰略嘅總體目標冇變化,即計劃到 2030 年,產銷量達到 1.6 億條,銷售收入超過 800 億元,產能規模目標為世界前五。

銅川項目終止
然而,四年多時間過咗,玲瓏輪胎嘅「7+5」戰略唔僅冇再進一步,而且有可能「破產」。

2021 年 6 月,玲瓏輪胎公告顯示,銅川年產 1520 萬條高性能子午線輪胎同 50 萬條翻新胎項目總投資達 60.66 億元。
其中:建設投資 54.60 億元,建設期利息 5.17 億元,鋪底流動資金 8869.29 萬元。資金籌措方面,企業自籌 24.66 億元,銀行貸款 36 億元。
不過,2025 年年中,玲瓏輪胎介紹,陝西銅川投資建設項目已經完成咗前期審批工作、土地招拍掛以及廠房設計工作,目前項目因外部負責嘅「七通一平」工作未達到工程建設要求,項目尚未正式開工。
2026 年 5 月 22 日晚間,玲瓏輪胎收到警示函顯示,2025 年 10 月,銅川投資項目發生重大變化,公司未及時披露,違反咗《上市公司信息披露管理辦法》相關規定。
監管部門表示,王鋒作為玲瓏輪胎董事長、時任總經理,孫松濤作為董事會秘書對公司上述行為承擔主要責任。
根據相關規定,決定對王鋒、孫松濤採取出具警示函嘅行政監管措施,並記入證券期貨市場誠信檔案數據庫。
玲瓏輪胎表示,針對上述問題,公司已採取相關措施予以整改,已於 2026 年 5 月 11 日召開董事會審議通過《關於終止前期陝西省銅川市投資設廠項目嘅議案》,該議案尚需提交公司股東會審議。
玲瓏輪胎表示,因項目前期準備工作進展緩慢,相關配套措施未能如期落地,導致項目實施嘅制度保障同預期收益存在較大不確定性。
為優化資源配置,經公司充分論證同審慎研判,決定唔再推進上述對外投資項目。

巴西項目終止
僅僅 5 日後,玲瓏輪胎海外新建項目都出咗問題。

5 月 27 日晚間,玲瓏輪胎發布公告顯示,因與擬合作方喺持股比例、合作條件等核心條款上未能達成一致,巴西投資建設項目已唔具備按期推進嘅條件。
經綜合評估,公司決定終止上述對外投資項目。目前,雙方已就終止合作事宜形成一致意見,後續將按各自內部程序完成相關審議後推進終止工作。
玲瓏輪胎表示,本次終止投資事項係公司基於市場環境變化、公司戰略調整及實際經營情況所作出嘅審慎決策,項目尚未進入實質性建設投入,唔會對公司業務發展同日常經營產生不利影響。
2025 年 5 月 15 日,玲瓏輪胎召開 2024 年年度股東會,審議通過咗《關於公司開展境外 (巴西) 投資建設項目同累計對外投資嘅議案》,公司擬同 SUNSET S.A. COMERCIAL INDUSTRIAL Y DE SERVICIOS 共同投資建設境外(巴西)投資建設項目(「年產各類高性能子午線輪胎 1470 萬條」同「35MW 光伏發電站」)。項目總投資為 11.93 億美元(折合人民幣 87.1 億元)。
一個要注意嘅細節係,彼時,玲瓏輪胎介紹,根據本項目嘅建設內容、規模同建設主體嘅實際情況,本項目計劃建設工期預計為 7 年,分三期進行建設,計劃於 2025 年第三季度開工,至 2032 年 12 月底結束投入使用。
顯然,巴西建設項目未能夠喺 2025 年第三季度開工,但玲瓏輪胎並未對此項目進展進行披露。
公司僅喺 2025 年年報中表示,巴西投資建設項目目前正處於規劃設計階段,同時就持股比例同其他事項同合作方開展商務洽談,尚未進入實質建設投入階段。
玲瓏輪胎喺披露巴西建設項目時也存在違規?一間上市公司董秘辦相關人員表示,玲瓏輪胎冇講假話,但講得太少、太模糊,令投資者喺唔知項目已經「實際上黃咗」嘅情況下睇咗一整套年報。
「喺呢個信披合規層面上,係站唔住嘅。」綜合睇落,玲瓏輪胎海內外兩大合計擬投資 147.76 億元項目均以失敗告終,公司「7+5」戰略實際上已名存實亡。

營收增速放緩
唔止上述兩個項目,玲瓏輪胎喺安徽嘅項目都唔順利。
2026 年 5 月,玲瓏輪胎仲公告稱,公司喺安徽省嘅年產 1460 萬條超高性能自癒合同智能子午線輪胎項目,因能耗指標不足已解除投資協議,轉而喺安徽六安高新技術產業開發區建設兩個新項目,而家已投入約 1.4 億元,但只完成咗生活區同部分生產配套設施建設,主體車間仍處於規劃設計階段,項目建設週期無法按原計劃執行。
喺新建項目唔如預期嘅時候,玲瓏輪胎 2030 年願景目標恐怕都難以實現。
2023 年,玲瓏輪胎營業收入同比增長 18.58%,首次突破 200 億元達 201.62 億元。2024 年同 2025 年,公司營業收入分別為 220.58 億元同 246.42 億元,同比分別增長 9.39% 同 11.72%。
由 246.42 億元增長至 800 億元,玲瓏輪胎未來 5 年營業收入年均要增長約 111 億元,喺無新嘅產能釋放情況下,公司無法企及呢個目標。
2026 年一季度,玲瓏輪胎營業收入達 60.57 億元,同比增長 6.33%,已進入緩慢增收期。
2025 年,玲瓏輪胎嘅輪胎產品生產量達 9429.81 萬條,銷售量達 9134.68 萬條,庫存量達 1649.31 萬條。
截至 2025 年底,玲瓏輪胎設計產能達 1.26 億條,達產產能達 1.14 億條,產能利用率為 82.43%。
顯然,玲瓏輪胎產銷量達到 1.6 億條仲存在唔少距離。接二連三嘅「打擊」之下,玲瓏輪胎股價持續下探,而家喺 12 元/股左右震盪。
為此,5 月 21 日,玲瓏輪胎公告稱,公司控股股東擬增持公司股份,增持金額唔少於人民幣 1.8 億元(含),唔高於人民幣 2.3 億元(含)。


【CNMO 科技消息】5 月 25 日,泰國工業聯合會發布最新數據,受中東戰事拖累出口及能源價格飆升嘅雙重打擊,該國 4 月汽車產量降至五年來最低水平。數據顯示,4 月泰國汽車產量共計103794 輛,同比下降0.44%,扭轉咗 3 月同比上漲 2.69% 嘅增長勢頭。當月汽車出口量為60190 輛,同比大幅下滑8.43%;而受曼谷車展訂單帶動,國內汽車銷量逆市增長 2.54%,達 48394 輛。

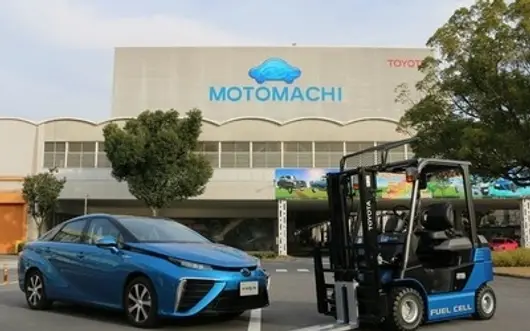
豐田產品
CNMO 科技了解到,「雙軌壓制」係此次產量驟降嘅核心原因。一方面,中東衝突導致霍爾木茲海峽物流嚴重受阻,使得以中東為主要目的地嘅汽車出口鏈條近乎斷裂。作為泰國汽車嘅三大海外市場之一,泰國 2025 年向中東出口咗200001 輛汽車,佔其總出口量嘅21.17%。
另一方面,國際油價持續高企推高咗泰國本土嘅能源與生產成本。面對日漸加劇嘅經營壓力,大批車廠被迫延緩生產計劃。作為東南亞最大嘅汽車生產基地,泰國聚集咗豐田、本田及比亞迪、長城汽車等多家國際車廠嘅製造工廠。

豐田
值得一提嘅係,泰國工業聯合會汽車分會會長素拉蓬·派西塔帕納蓬喺新聞發布會表示,儘管 4 月數據疲弱,聯合會依然維持對2026 年全年產量增長 3% 至 150 萬輛嘅預測,前提係下半年海運物流恢復通暢、能源價格趨於穩定。
May 28, SAIC Motor completed delivery of its 100 millionth new vehicle, becoming the first domestic automotive group to exceed 100 million in cumulative production and sales, resetting the production and sales record of Chinese automakers.

The vehicle model delivered this time is the IM LS9 Hyper, the top-spec version of the IM LS9. It features a full wire-controlled four-wheel steering system, equipped with a 520-line ultra-vision LiDAR, Nvidia Thor chip, and the Momenta intelligent driving large model.
Regarding power, the vehicle is built on an all-domain 800V high-voltage platform, equipped with the Star Super Range Extender System, and features the Gold Badge Hurricane Three-Motor System. The peak power of the motors reaches 160kW (Front), 195kW (Rear Left), and 195kW (Rear Right) respectively. The comprehensive range exceeds 1400 kilometers.

In 1955, the Shanghai Internal Combustion Engine Parts Manufacturing Company was established, marking the formal start of the Shanghai automotive industry; in 1958, the first "Phoenix" sedan went off the line, achieving a zero breakthrough in Shanghai sedan manufacturing. In the 1980s, SAIC introduced the Santana model through joint ventures and cooperation, promoting the scaled development of China's sedan industry. In 1997, Shanghai GM was established, setting a record of 23 months from factory construction to vehicle delivery. The Roewe brand was born in 2006, and the first Internet car, Roewe RX5, was launched in 2016. In 2020, IM Motors was established, positioning itself in the high-end intelligent electric vehicle track.
In terms of overseas markets, SAIC Motor has already established over 100 parts production bases and a dealer network of more than 3000, with products and services covering more than 170 countries and regions globally. Additionally, 3 major R&D and innovation centers, including London, have been built, along with 4 production and manufacturing centers in Thailand, Indonesia, India, and Pakistan. The owned Anji Logistics operates 42 various Ro-ro ships, with 8 international routes covering Southeast Asia, Europe, and the Americas.
车见万宜讯—6月18日,红旗品牌亮相香港国际汽车及供应链博览会,三款右舵纯电车型集体登场。其中,E-HS9右舵版正式在香港上市,意向价99.88万港元起——这个价格门槛意味着它直接进入了香港豪华纯电SUV的顶端战场,与奔驰EQS SUV、宝马iX等车型正面竞争。

但E-HS9右舵版的上市,实际上是一次多重意义的叠加。它是红旗“右舵元年”的开篇之作,也是中国高端品牌首次以接近七位数的价格在香港市场叫板传统豪华品牌。在此之前,香港豪华电动车市场已被充分教育——2026年1至5月,极氪以40.7%的市场份额稳居香港豪华车品牌销量榜首。红旗选择在这个时间节点进入,面对的并非一片空白,而是一个已有成熟玩家、消费者已建立品牌认知的市场。这注定不是一场轻松的仗。
从产品本身来看,E-HS9的底子并不弱。搭载120kWh电池组与双电机四驱系统,综合输出637马力和710牛·米扭矩,WLTP续航548公里。车身尺寸5209×2010×1731毫米,轴距3110毫米。9H笼式车身结构和IP68级防水电池构成安全层面的硬指标。这些数字放在香港市场,至少不输给同价位的竞品。
但真正值得讨论的,或许不是参数本身,而是红旗给香港消费者提供了一套怎样的价值叙事。E-HS9承袭太和比例设计理念与东方礼制美学,直瀑式封闭格栅、贯穿式旗标、分体式大灯构成了极具辨识度的前脸语言。车内贯通式三联屏加中央通道触摸屏组成四联屏交互系统,配合天然实木、Nappa真皮等材质,在科技感与豪华感之间寻求平衡。这套设计语言在内地市场已经经受了检验——有人认同它的气场,也有人对其智能化表现提出过质疑。但在香港市场,它面对的是一个更关键的问题:消费者是否愿意用接近100万港元,为“东方豪华”的设计哲学投票?

一个细节值得留意。本次车展现场同步展出了参与东南亚丝路之旅的E-HS9功勋原型车——该车历经35天、穿越6个国家和地区、累计跋涉一万公里。红旗用这场长距离实测来为E-HS9右舵版的品质背书。这种用真实路测而非实验室数据说话的方式,对于看重可靠性的香港消费者来说,可能比任何参数都更有说服力。

服务体系是另一个看点。红旗香港体验中心定于7月1日在港岛太古城正式开业,落地“红旗CARE 365”服务,覆盖看车、试驾、交付、售后等全生命周期。对于一个新进入香港市场的品牌而言,渠道和服务的本地化程度决定了第一批用户的口碑走向。太古城的选址也值得琢磨——港岛东区核心商圈,客群画像与E-HS9的目标用户高度重合。
当然,E-HS9在香港市场面临的挑战同样清晰。99.88万港元起售价意味着它需要和已经深耕多年的豪华品牌争夺同一批客户。这些品牌在香港积累了成熟的渠道和服务体系,消费者的信任成本相对较低。而红旗需要让香港消费者相信:一台来自内地的高端电动车,值得用接近七位数的价格去拥有。

未来三年,红旗计划以香港为基点,向全球右舵市场投放不少于六款全新新能源产品。E-HS9是这场右舵远征的第一站,它的市场表现将在很大程度上决定后续节奏。对于正在考虑大型豪华纯电SUV的香港消费者来说,E-HS9提供了一个不同于欧美品牌的选择——它携带的是一套完整的东方设计语言和价值体系,而非仅仅是参数表上的数字。这台车能不能在香港站稳脚跟,最终要看交付后的实际表现能否配得上它的定价和承诺。

In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.


作者:宋家婷
曹晖、张正萍、张正源、淦家阅……从“创一代”开疆拓土的草莽英雄,到“创二代”运筹帷幄的体系将帅。
2026年5月,在特朗普访华国宴上,马斯克身边的一个”新“面孔引发关注——不少人查询后才知道:他就是去年10月接过福耀权杖的曹晖。
这位“玻璃大王”之子坐在全球科技偶像身旁的画面,也正是当下中国汽车业的隐喻:中国制造业的下一代,正从父辈的车间走向世界的餐桌。

过去两年,一场横跨民营家族、国有集团的代际权力交接在静默中上演:60后“创一代”逐步退居二线,两类新生代掌舵者站上舞台——民企血缘“创二代”、国企体系内成长的职业新生代。
这不是一次简单的权力交替。它是产业从燃油增量时代,彻底转向智能电动存量时代的生存抉择。
两代掌舵人
三十年前,中国民营造车的初代玩家集体登场:李书福、王传福、张兴海、魏建军……
毫不夸张地说,这批60后创业者堪称中国汽车业的“草莽英雄”。他们身上,刻着增量市场的时代烙印。
那时候,国内汽车供给短缺、市场广袤,李书福放言“汽车就是四个轮子加两个沙发”,带着吉利从冰箱配件跨界造车;张兴海拿着8000元办弹簧厂,一路做到微车前三;王传福押注电池赛道切入新能源;魏建军以长城皮卡起家,最终抓住SUV红利。

“创一代”们的底色是胆识、韧性与赌性——在产业空白处开荒,在政策缝隙里突围,凭个人意志驱动整个组织。
他们擅长抓住蓝海机遇,依靠草根实干、长线重资产投入,搭建起中国自主汽车产业的基本底盘,管理模式偏向人治、决策高度集中,核心目标是“把车造出来、把规模做起来”。
由是我们也就看到了,王传福执掌比亚迪二十多年,魏建军至今在长城内部仍保持高度集权。这种模式在增量时代简单高效,但当企业从几十人变成几十万人、从单一产品变成品牌矩阵,创始人的精力半径,就成了企业的天花板。
这在2024年到2026年的行业裂变中,体现得尤其彻底。截至2025年末,中国汽车保有量已达3.66亿辆,市场进一步饱和,叠加电动化、智能化、全球化三重变革,价格战持续侵蚀利润,奇瑞、一汽等老牌车企销量承压,日产、福特等跨国品牌丢失品牌溢价。
2026年产业环境进一步恶化。一季度汽车行业利润率仅3.2%,前五个月乘用车零售量同比下滑近两成,蔚来李斌悲观判断全年跌幅将达15%-20%——增量时代真的结束了。

这意味着,存量时代需要的车企掌门人,不再是吃苦耐劳的“开荒牛”,而是更具综合实力的“体系操盘手”——精通汽车技术迭代、懂得用户运营、能够平衡短期盈利与长期投入,有能力搭建全球化本地化体系、并敢于建立现代化职业治理架构,摆脱单一创始人依赖。
更关键的是,得能打赢一场没有退路的持久战。
两条接班主线
家族“创二代”的交班,并非简单的“子承父业”,而是呈现出两条清晰的路线:
一是实战接班,全面掌舵。
赛力斯张正萍,是目前走得最远的一个。今年6月,36岁的他正式出任赛力斯汽车董事长,全面执掌问界品牌的整车业务,父亲张兴海退居集团层面掌舵战略。

虽然是父子传承,但并非空降。根据公开资料,十年前张正萍就远赴硅谷创立SF Motors,回国后主导了赛力斯与华为合作的几乎所有重大节点。
可以说,从硅谷拓荒到问界爆款诞生,他一直在“前线”而非“温室”。媒体曾评价他“不是靠血缘获得了信任,而是靠实打实的战功赢回了帅印”。
福耀曹晖的接班,则是一场持续近20年的长跑。去年10月,曹德旺正式卸任董事长,由曹晖接棒。彼时曹德旺就公开评价其管理能力优于自己。
现年56岁的曹晖,同样是从车间基层做起,历经香港、美国市场以及独立创业历练,走过了一条“长时间、多岗位、高强度”的成长路径。

二是职业经理人“代际更替”。
与张兴海同龄的李书福,在二代接班上尚处于“渐进式”阶段。
一方面,他十多年前就开始着力培养其子李星星,包括后者从吉利摩托车事业部起步,相继掌舵领克亚太、收购ST澄星打通上游锂电产业链,通过轮岗培养对汽车业的“手感”并蓄力;
另一方面,李书福也在吉利内外提拔职业经理人,包括吉利控股集团轮值总裁戴庆、吉利汽车集团CEO淦家阅等80后将领。
特别是淦家阅,不久前其在一周之内同步接任极氪、领克两大高端品牌董事长,统筹集团新能源核心赛道。

通过搭建职业经理人治理体系,吉利形成“老帅定战略、新帅管经营”分工,与家族二代分管产业链投资形成互补,由此奠定坚实基础。
相对而言,比亚迪目前走的仍是职业经理人路线。一方面,王传福近年密集卸任四十余家子公司董事长,全业务线交由内部成长高管运营,完全依靠制度化职业团队驱动转型。
另一方面,今年以来,比亚迪五网总经理有升有降,体现了比亚迪的管理效率,也说明了内部竞争的激烈和外部市场的残酷。五网赛马最重要的意义,就是用内部竞争,再度激发原创力。

两条接班主线,看似路径迥异,实则指向同一内核。
家族“创二代”这边,张正萍十年硅谷淬火、凭战功赢回帅印,曹晖从车间到海外、用二十年长跑接住权杖——他们证明了一个朴素的道理:血缘只能打开门,守住门靠的是真本事。
职业经理人那边,吉利以“老帅定战略、新帅管经营”搭建双轨制,形成家族二代管产业链投资、80后职业经理人统兵打仗的互补格局;比亚迪则彻底放手,以五网赛马机制倒逼内部竞争,依赖制度化团队驱动转型。
两条路径各有逻辑,但殊途同归:无论血缘传承还是职业晋升,中国汽车业的权力交接早已跳出了“谁坐那把椅子”的简单命题。它本质上是一场从“个人英雄主义”向“体系作战能力”的范式转换——创一代靠胆识开疆拓土,新生代则必须靠体系赢得持久战。正如张正萍在硅谷的拓荒经历教会他的那样:造车从来不是一个人的战斗,而是一群人的长跑。

当张正萍们不再需要父辈的羽翼、当淦家阅们已能独当一面——中国汽车业正在用一场静默而深刻的代际交替,回答一个时代之问:离开了那些传奇的创始人,中国车企还能不能继续赢下去?
答案是,不仅能,而且正在以更系统、更专业、更可持续的方式,接过这场百年变局中最沉重的接力棒。
新世代如何破局?
无论"创二代"还是职业经理人,新掌舵者们都面临着同一道考题:存量寒冬里,如何破局?
第一,以软件、AI、用户运营重构核心竞争力。赛豆科技董事长张正源推动AIVA全面布局AI原生车型,打通与字节、宁德时代的协同生态。工厂和供应链曾是护城河,如今护城河变成了软件与用户。

第二,以本地化深耕替代简单出口走量。曹晖持续扩张福耀海外产能,适配各国新能源车型需求——新世代的全球化,不再是"把车卖出去",而是"把体系建出去"。
第三,以现代化治理弱化创始人依赖。吉利以"老帅定战略、新帅管经营"的双轨制,让淦家阅等80后职业经理人统兵打仗;福耀以"三步走"交接方案,让曹晖在实战中逐步接棒。新旧权力清晰分割,避免创始人退而不休的老问题。
第四,以盈利质量平衡规模扩张。淦家阅整合极氪、领克研发后台降本增效;曹晖聚焦高附加值智能玻璃;张正萍从"走量"转向"走质"——收缩低效战线,集中资源打造高溢价爆款,是新生代的共识。

破局的方向已经清晰——从制造到智造、从出口到深耕、从人治到法治、从规模到盈利。这四道考题,创二代正在交出新答案。
结语:
从国宴上的新面孔,到车间里走出的新掌门——曹晖坐在马斯克身旁的那个瞬间,恰如其分地定格了这个时代的深意:一个中国制造业新老交替的故事,被放置在全球最瞩目的餐桌上。
这场静默而深刻的代际交替,远非"谁坐那把椅子"那么简单。它是一场从"人治"到"法治"、从"规模"到"质量"、从"制造"到"智造"的系统性跃迁。
创一代用三十年时间,在一片荒芜中打造了底盘。现在,接力棒交到了新世代手中,他们面临的考题比父辈更复杂。但恰恰是这种复杂性,倒逼出了一批更系统、更专业、更国际化的掌舵者。
他们从车间走来,走向世界的餐桌。他们的成败,将决定中国汽车业能否真正跨越周期,成为全球产业变局中那个不可替代的答案。


你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。
然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。
要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。
高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。
《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。
如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
June 4, Jiangsu General Share Technology Co., Ltd. (hereinafter referred to as "General Share") issued a favorable announcement. The company recently received government subsidies totaling 37.608 million RMB, accounting for 0.60% of the latest audited net assets. The aforementioned subsidies belong to government subsidies related to assets and will be recognized as deferred revenue, further strengthening the company's asset foundation for subsequent development. During the critical period when General Share is striving hard to meet performance commitments and accelerating the release of overseas capacity, the arrival of this subsidy undoubtedly injected a shot of confidence into the company's positive development.

First Year of State Ownership Takes Test, Strong First Quarter Rebound Shows Resilience
In 2025, General Share completed a major leap from a private enterprise to state-owned capital control. In April of that year, the original controlling shareholder Hongdou Group signed an agreement with Suhao Holding Group. Suhao Holding acquired 24.50% equity for 2.118 billion RMB. After the transfer was completed in June, the company's actual controller was officially changed to the Jiangsu Provincial State-owned Assets Supervision and Administration Commission.
Accompanying the change in control rights was a performance commitment agreement demonstrating confidence in development: net profit attributable to shareholders for 2025-2027 shall not be less than 440 million RMB, 480 million RMB, and 530 million RMB respectively, totaling not less than 1.45 billion RMB over the three years. Affected by the superposition of multiple short-term factors such as increased international trade barriers, declining product unit prices, exchange rate fluctuations, and provision for impairment, General Share encountered "revenue growth without profit growth" in 2025. Revenue reached 8.497 billion RMB (a year-on-year increase of 22.11%), with net profit attributable to shareholders of 201 million RMB, putting pressure on the first-year commitment.

However, entering 2026, General Share quickly showed a strong recovery momentum. First-quarter financial reports show the company achieved revenue of 2.137 billion RMB, with net profit attributable to shareholders of 127 million RMB, a year-on-year growth of 23.24%; deducted non-recurring net profit was 125 million RMB, a significant increase of 32.42%. Particularly striking is that net cash flow from operating activities soared by 2605.19% to 339 million RMB, with profitability quality and operational resilience achieving a simultaneous significant leap.
Overseas Capacity Continues to Gain Momentum, Positive Cycle Accelerates
The stabilization and recovery of performance are primarily driven by the "overseas dual bases" strategically planned by General Share bearing fruit. The company stated that benefiting from the accelerated release of advantageous capacity in the Thailand and Cambodia bases, combined with the steady progress of the domestic semi-steel tire technical transformation project, tire product sales continued to climb, providing solid support for performance growth.

Currently, General Share is at a strategic new starting point empowered by state-owned assets. The realization of government subsidies, the surge in operating cash flow, and the strong overseas production and sales are converging into positive potential to push the company forward. In the future, whether General Share can ride the trend, accelerate the conversion of overseas capacity under the resource support of the state-owned asset platform, gradually bridge the performance commitment gap, and achieve a fundamental leap in operational quality and efficiency, is worth continued expectation from the market.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.


From its birth in 1955 to 2026, Shanghai's automotive industry has evolved from nothing to something, from weak to strong. Guided by the "Understanding Cars, Understanding You Better" philosophy, it has formed a flourishing scenario with independent and joint ventures, passenger and commercial vehicles, and domestic and overseas markets.
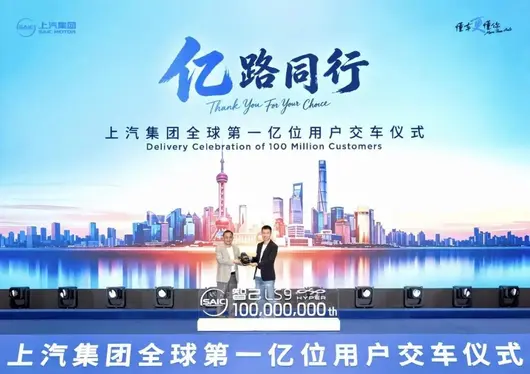
On May 28, 2026, the "Global 100 Millionth User Delivery Ceremony" of SAIC Group was held at the Shanghai North Bund World Living Room. Over ten vehicle brands and nineteen models under SAIC coordinated globally through "Global Relay Delivery." SAIC Group thereby became the first Chinese automotive enterprise to accumulate production and sales exceeding 100 million vehicles, creating a new milestone.

In 1955, the Shanghai Internal Combustion Engine Parts Manufacturing Company was established, marking the start of Shanghai's automotive industry. In 1958, workers hammered out the first "Phoenix" sedan, achieving a "zero breakthrough" in Shanghai sedan manufacturing. For over seventy years, SAIC has witnessed and promoted the entire process of China's automotive industry evolving from nothing to something, from weak to strong: In 1983, the Santana rolled off the line, opening joint venture cooperation; In 1997, Shanghai GM was established, creating the "Shanghai Speed" of building a factory and producing cars in 23 months; In 2006, the independent brand Roewe was born, and in 2016, the world's first internet car, Roewe RX5, was launched; In 2020, the intelligent electric brand IM Motors was established.

Running through this journey is the "Understanding Cars, Understanding You Better" user philosophy that SAIC has always upheld. From the Santana localization community to Joint Venture 2.0 technology co-creation, from internet cars to full wire-controlled chassis, solid/semi-solid batteries, and AI large models in cars—every leap forward is an upgrade in "Understanding Cars" capabilities and an inheritance of the original intention of "Understanding You".

SAIC Group Global 100,000,000th User Delivery, IM LS9 Hyper
The 100 millionth vehicle delivered by SAIC Group is the IM LS9 Hyper, a masterpiece consolidating over 70 years of SAIC's technical accumulation: It is equipped with next-generation chassis technology, featuring the first-in-class full wire-controlled four-wheel steering system; next-generation intelligent driving hardware, including 520-line ultra-view LiDAR and NVIDIA Thor chips; next-generation powertrain system—global 800V high-voltage platform and Star Super Range Extender. This car also fully reserves the capability for continuous evolution towards L3 and above advanced intelligent driving. At the same time, the IM LS9 Hyper adopts the SAIC Gold Label Hurricane Three-Motor for the first time, joining the 3-second 0-100km/h club; it also jointly launched the "Intrinsic Security" technology with Purple Mountain Laboratory globally for the first time, expanding automotive safety boundaries from "Physical Security" to "Information and System Security," serving as an essential safety cornerstone for the AI era.

Behind the 100 million vehicles is SAIC's full value-chain closed loop covering six major sectors: complete vehicles, parts, mobility and services, finance, international operations, and innovative technology. From January to April 2026, SAIC accumulated sales of 1.302 million vehicles, ranking first in sales among Chinese automakers for four consecutive months. Among them, independent brand sales were 910,000, accounting for nearly 70%; new energy vehicles sold 412,000; overseas market sales were 459,000, a year-on-year surge of 50.2%.

At the delivery ceremony site, SAIC's full brand and product matrix collaborated. Independent brands went all out, covering multiple scenarios such as personal mobility, family life, commercial operations, and logistics transportation. Joint venture brands showcased "Joint Venture 2.0" results: Volkswagen ID. ERA 9X will globally debut with the Momenta R7 Reinforcement Learning World Model; AUDI E7X plans to become Audi's first global model to achieve L3 autonomous driving landing; Buick Zhijing E7 is built based on the "Xiaoyao" Super Fusion Architecture, achieving over 10,000 deliveries one month after launch.

Starting from the main venue in Shanghai, the delivery scene lit up successively in multiple domestic cities such as Nanjing, Liuzhou, Taiyuan, and countries including the UK, Indonesia, and Singapore. Behind this lies SAIC's deep foundation for global layout. SAIC is a pioneer in Chinese automotive enterprises "Going Global": It owns over 100 parts production bases and over 3,000 dealer networks overseas, has built 3 major R&D innovation centers including London, and 4 manufacturing centers in Thailand, Indonesia, India, and Pakistan; Anji Logistics owns 42 Ro-Ro ships of various types, with 8 international routes covering Southeast Asia, Europe, and the Americas. Today, SAIC's products and services are distributed in over 170 countries and regions, with cumulative overseas sales exceeding 7 million vehicles. SAIC MG has retained the title of the European sales champion among Chinese brands for 11 consecutive years; in 2025, European annual sales surpassed 300,000 units, becoming the first Chinese automotive brand to break one million in cumulative sales in Europe and the UK. In March this year, MG held a Tech Day in Frankfurt, Germany, globally debuting semi-solid state batteries and Hybrid+ hybrid technology, with the Hybrid+ family's overseas monthly sales already exceeding 20,000 units. In 2025, SAIC released the overseas "Glocal Strategy" (Global + Local), accelerating from "Product Going Global" to "Value Chain Going Global," allowing "Chinese Smart Manufacturing" to go further into the world.

100 million vehicles is a phased answer sheet for SAIC's over 70 years of development, and even more so, a new starting line for SAIC's "second entrepreneurial journey" towards the future of intelligent electric vehicles. In 2014, SAIC actively implemented the important instruction that "developing new energy vehicles is the only path for China to move from a car major power to a car strong power," leading the way in comprehensive transformation. Twelve years later, from the "leading the way" of intelligent electric transformation to a "flourishing boom" in independent/joint ventures, passenger/commercial, and domestic/overseas, SAIC will continuously take "Understanding Cars, Understanding You Better" as the user philosophy, letting technological innovation truly benefit every user.
The author of this article is A Lai from TiCheBang
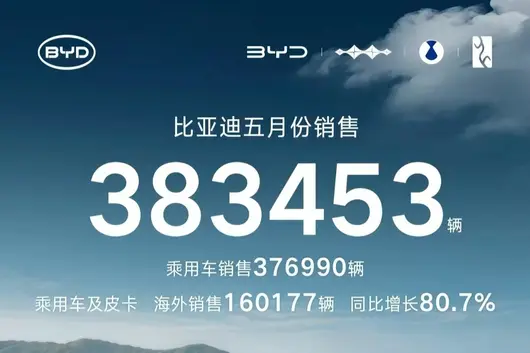
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.

The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.

Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.

The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.

Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.

In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.
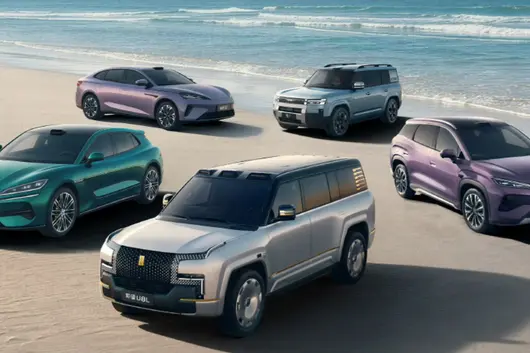
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.
The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.
Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.
The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.
Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.
In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.

北方车市
6月18日,红旗亮相香港汽车博览会,携三款全新右舵纯电车型登台,全球化布局迈上新台阶。作为中国历史最为悠久的高端汽车品牌,红旗坚守“为全球用户造好车”的使命,攻克1500余项核心技术,搭建出天工纯电、鸿鹄混动、九章智能三大技术平台,凭借扎实的自主研发技术实力,向世界传递中国高端智造、创新科技与东方美学的独特魅力。

未来三年,红旗将以香港为基点,持续向全球右舵市场投放不少于六款全新新能源产品,不断丰富海外产品线,深化全球化战略布局。
亮相三款右舵重磅车型,适配全球多元化出行需求
本次三款右舵车型定位清晰,构建起完善的海外产品阵容,精准匹配不同用户群体的出行需求。

红旗 Global SUV定位全球美学智享纯电SUV,融会东西方设计美学精髓,璀璨星辰大灯、专属雪拉同青瓷绿车漆辨识度拉满;座舱采用中置平衡对称布局,适配城市通勤、全家出游等多元用车场景,整车严苛遵循全球安全规范,新车计划于2026年第四季度登陆香港市场。

红旗 EHS5作为高性能纯电SUV,搭载智能四驱系统,零百加速性能优异,叠加专业级底盘调校,操控体验出众。车型斩获 CNCAP、ENCAP 双五星安全认证,强劲驾趣与全域安全防护兼备,专为看重驾驶质感的消费者打造。

红旗 E-HS9 右舵版作为旗舰豪华纯电SUV,承袭太和比例设计理念与东方礼制美学,内饰甄选奢华材质,影音与舒适配置一应俱全。搭载120kWh电池组与双电机动力总成,实现持久续航,从容驾驭全路况出行;9H笼式车身、IP68级防水电池等硬核安全加持,筑牢顶级出行保障。这份承载着东方豪华与极致科技的诚意之作,于本次车博会正式登陆香港市场,也必将为香港用户带来从容、可靠、超越期待的尊崇出行体验。

现场同步展出的E-HS9功勋原型车历经35天、穿越6个国家和地区、累计跋涉一万公里丝路征程,用长距离实测充分验证整车可靠品质,更为该车型进军香港市场夯实品质背书。

启幕香港专属体验中心,打造豪华汽车领域新标杆
红旗香港体验中心定于7月1日在港岛太古城正式开业,该体验中心将落地“红旗CARE 365”服务,完整覆盖看车、试驾、车辆交付、售后保养等用户用车全生命周期,以卓越产品和贴心服务树立民族汽车品牌国际新形象、全球豪华汽车领域新标杆。

从古丝绸之路的文明交融,到香江之畔的全新启航,红旗始终坚守以“和谐共生的东方文化理念,重新定义世界豪华汽车新标准”的品牌愿景。步履所至,东方风雅一路随行;驾乘之间,至诚礼遇恒久相伴。红旗携手全球伙伴同心同行,共启东方豪华出行崭新华章。

In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
今日聊聊小鵬。
5 月 28 日,小鵬都發咗一季度財報。
直接進入正題。
小鵬第一季度交付量為62683 架。

對照之下,蔚來係 83465 架,理想係 95142 架。
無論係對照自己定係對比蔚來小鵬,都唔係一個好成績。
因為第一季度蔚來同理想都冇新車或者改動補位,純靠現有產品矩陣。
小鵬唔同,小鵬投放咗好唔多改動車型:
1 月,一次性上市 4 款主力車型:2026 款 P7+、2026 款 G7、2026 款 G6 純電版、2026 款 G9 純電版。
3 月,X9 純電版、G6 超級增程版、P7 新車型上市。
第一季度完成咗六款車型嘅新與改動。
完全係下餃子嘅打法。
但係即便呢樣,銷量都一般。
直到 4 月,26 款 MONA M03 上市交付,銷量先又迎來上揚。
小鵬給嘅說法係:第一季度係受國內新能源市場波動影響,公司唔只關注規模,更注重銷量同經營質量嘅平衡。

第一季度小鵬汽車毛利率 12.1%,相比之下,2025 年同期為 10.5%,而 2025 年第四季度為 13.0%。
對於汽車毛利,理想董事長李想有一個觀點:產品穩定毛利應該穩定喺 15%-25%,最長都唔會低於 15% 嘅毛利率。
雖然理想第一季度都唔好,整車毛利只有 6.1%。
但係而家嚟講,小鵬整車毛利唔高,都同佢銷量唔高有關,規模效應發揮唔到作用。
所以,汽車銷量嘅主業務提供嘅造血能力就比較有限。
唔過,小鵬第一季度毛利率係 20.6%,相比之下,2025 年同期為 15.6%,而 2025 年第四季度為 21.3%。
這係因為小鵬服務同其他業務(技術研發服務,軟件授權)毛利非常高,達到 66.5%。
雖然收入只有 20.3 億元,遠唔及汽車銷售嘅 110 億元,都係拉升咗整體毛利。

去年四季度小鵬實現咗單季度盈利(淨利潤超 3.8 億元),但遺憾冇保持落來。
今年第一季度,小鵬淨虧損為 17.8 億元(2.6 億美元),相比之下,2025 年同期為虧損 6.6 億元,而 2025 年第四季度為收益 3.8 億元。
經營虧損為 18.7 億元(2.7 億美元),相比之下,2025 年同期為 10.4 億元,而 2025 年第四季度為 0.4 億元。
第一季度研發開支為 29.1 億元(4.2 億美元),較 2025 年同期嘅 19.8 億元增加 46.8%,並較 2025 年第四季度嘅 28.7 億元增加 1.1%。
按年增加主要由於公司擴充產品組合以支持未來增長,新車型及 AI 相關技術開發對應嘅開支有所增加。
第一季度銷售、一般同行政開支為 18.8 億元(2.7 億美元),較 2025 年同期嘅 19.5 億元下降 3.2%,並較 2025 年第四季度嘅 27.9 億元下降 32.5%。按年及按季下降主要由於向特許經營店支付嘅佣金減少。
至於現金儲備,仲有 420.9 億元,彈藥充足。
唔過,從第二季度開始,小鵬嘅情況會開始慢慢好轉。
原因在於,有新品爆款車型嘅補充:小鵬 M03 同小鵬 GX。
首先係 4 月 26 款 M03 上市,唔負眾望,依然穩定保持爆款表現,37 分鐘大訂破萬,4 月零售 13595 輛,帶來新嘅銷量增量。
除咗呢架車,小鵬全尺寸高端旗艦小鵬 GX 喺 5 月 20 日上市,限時權益價26.98-34.98 萬元(純電 + 增程共 8 個配置)。
已經妥妥大爆款,尤其係頂配車型,已經火到一塌糊塗:

尤其係小鵬 GX 純電版,5 月 23 日嗰陣交付週期係 20-24 週,而家已經變到 30-34 週。
而家已知嘅係:初始訂單中旗艦版佔比超 80%,而家仍係主力。Max 版佔比低於 5%,低於預期。
增程版起初需求唔如純電,但正逐步接近,尤其係加強咗喺北區、西區嘅營銷後。
「我哋希望 GX 能夠成為 30 萬以上高端大六座市場嘅前三甚至頭部爆款。」
「GX 作為旗艦車型,毛利率唔錯,大部分 SKU 嘅毛利率表現都高於預期。」
所以,隨著呢架車嘅大批量交付,今年 6 月、乃至接下來,呢架車將貢獻唔少嘅銷量收入,同時都會帶動小鵬整車毛利嘅提升。

唔過,必須講嘅係雖然有咗小鵬 GX 高毛利車型改善產品結構,但係原材料上漲嘅壓力(內存芯片同電池),呢啲壓力仲會繼續持續到隨後季度。
第二季度小鵬預期交付量為 100000 至 106000 輛,較第一季度增加約 59.54% 至 69.11%。
總收入將喺 196.0 億元至 208.0 億元,較第一季度增加約 50.38% 至 59.59%。
至於總毛利,預計會同第一季度大致持平。
鑒於小鵬全新高端旗艦小鵬 GX 開咗一個好頭。
接下來,小鵬表現非常值得期待。
首先係新車型。
今年下半年小鵬仲有 3 款新車型將會上市交付。
小鵬 G9L:小鵬 G9 嘅加長版。
G9L 嘅定位會喺 G9 同 GX 之間,中大型 6 座豪華家用 SUV。
小鵬 G9:4891×1937×1670mm,軸距 2998mm
小鵬 G9L:5120×1999×1782/1788/1795
小鵬 GX:5265×1999×1800mm,軸距 3115mm,
小鵬 G9L 喺 G9 嘅基礎上面做咗加長,同樣純電/增程雙動力,至於其他方面嘅配置,我個人感覺會向 GX 看齐,俗稱套娃。

所以,呢架車嘅配置、空間等多項產品競爭力必定唔差。
而家嘅新車企想要喺內捲之下獲得勝出,核心仲係《科技叢林》多次強調嘅策略:降維打擊 + 錯位競爭。
這也是而家新車企越做越大嘅原因。
那麼,G9L 隨後應該會取代 G9 嘅位置,所以最關鍵嘅就係定價,小鵬 G9 嘅價格係 24.88 萬 -27.88 萬。
G9L 想要走量,定價同 SKU 就需要好好掂量一下。
如果定得好,那就又係爆款預訂。
除咗 G9L,小鵬 MONA 序列嘅 SUV 車型都終於要嚟,將補齊小鵬喺 15 萬 SUV 車型嘅缺失。
MONA L03:
L03 定位緊湊型轎跑 SUV,4650 /1920/1600mm,軸距 2850mm(軸距越級),同樣純電 + 增程雙能,83kW(249 馬力)永磁同步單電機。

純電版提供 505km(56kWh)、650km(69kWh)兩個續航規格。
增程版 37.2kWh 磷酸鋰鐵;CLTC 純電續航 257km,綜合續航 > 1000km。
如果能畀一個唔錯嘅價格,那基本能延續而家 M03 嘅爆款勢頭。
至於上市發布時間,有用戶喺小鵬汽車副總裁于濤評論區問 7 月是否能夠提到車,佢嘅回應係:冇問題,當晚落單無壓力。
所以 L03 大概率 7 月就會上市。
L05:5 座中型家用 SUV
某種程度上可以睇做大一號嘅 L03。

L05 長闊高:4870/1930/1636mm,軸距 2940mm。
對比一下小鵬品牌嘅 G6。
小鵬 G6:4758/1920/1650mm,軸距 2890mm。
所以,L05 無論是坐乘還是裝載表現,都會優於 G6。
G6 售價係 17.68–18.68。
考慮到 MONA 系列更平價嘅定位,L05 要比 G6 便宜,同時也會吃掉唔少 G6 嘅市場份額。
(如果出現倒掛,那我肯定呢架車最後銷量肯定翻車)
對於 MONA 呢兩台 SUV,我還係好期待。
不過都係嗰句話,無論係 G9L、L03 定係 L05,最終決定可唔可以大賣嘅核心因素都係定價、配置,小鵬必須謹慎對待。
如果呢一塊唔出錯,那麼下半年小鵬銷量表現就非常值得期待。
小鵬第二代 VLA 進展都非常值得期待。
首先技術方面,第二代 VLA 帶來咗兩個新能力:
1、第二代 VLA 無導航園區/地庫漫遊,實現智駕從「有路可走」到「無路都能走」
2、國內首個全場景原地起步(公開道路、園區、地庫,P 檔狀態可原地起步),邊度都能開,大幅度提升智駕使用率
呢兩個功能嘅搭載唔單單係智駕功能嘅補全,意味著小鵬將全場景 0 速啟動、無導航漫遊通行、城區 NOA、高速 NOA、車位到車位嘅環節徹底打通,形成一個完整無縫嘅端到端體驗閉環。
實現智駕從「有路可走」到「無路都能走」,而且將會帶來智駕體驗連續性嘅質變,真正做到邊度都能開。
呢個能力形態已經同特斯拉喺北美實現嘅全場景 FSD 非常接近。

而且,第二代 VLA 推送首月,智駕里程佔比行業首破 50%,成為行業首個跨越呢一節點嘅智駕系統,標誌高級智駕從"極客嘗鮮"正式邁入大眾日常、高頻使用階段。
關於智駕里程,國內智駕頭部公司地平線創辦人&CEO 余凱有一個觀點:智駕里程佔比突破 50% 後,用戶對智駕嘅依賴將變得不可逆。
那麼,隨著更大量車型嘅交付以及更多智駕里程嘅使用,小鵬智駕將會得到唔少嘅進步同成長。
這仲未完。
今年 Q3(8 月),小鵬 VLA 將會迎嚟一波更新,極大程度提高模型能力上限,更聰明、泛化能力更強、大幅降低接管率。
今年年底,小鵬將實現首次實現VLA+VLM 融合,除自動駕駛外具備語言溝通能力,為未來「汽車管家」(L5 級別)能力打下基礎。
「當自動駕駛能基於 L2 級別硬件實現完美嘅 L4 軟件能力時,整個業務形態同商業模式將產生巨變。」
可以預見嘅係,小鵬喺智駕方面嘅競爭能力將得到進一步增強,而呢個反過來都會促進小鵬產品銷量增長,形成一種正向循環。

至於 Robotaxi,而家小鵬係喺廣州拿到牌照並運營。
小鵬嘅規劃係喺廣州把技術、產品、商業模式跑通後,再同國內外嘅更多合作夥伴開展本地化運營。
小鵬嘅 Robotaxi 策略有兩點:第一,只做產品並抽佣,唔直接做運營,因此會有很多合作夥伴;第二,小鵬認為全球化嘅 Robotaxi 有巨大嘅商業價值。
何小鵬表示:國內近期嘅自動駕駛監管收緊並未影響我哋嘅節奏,我哋認為 2028 年之後將係 Robotaxi 嘅巨大商業機會,而家正按步驟喺海内外準備。
小鵬當前嘅計劃係利用現有車型喺國內同國際市場大力部署同試驗 V2.0。

正用當前車型進行快速研發同實驗,並會喺 2027 年推出經濟型車型來做好 Robotaxi 嘅示範同商業驗證,Robotaxi 商業化能力會持續提高。
「針對 Robotaxi 嘅測試同研發對 C 端業務都會帶來正面影響(反哺),因為 V2.0 可以衍生出多種智能駕駛策略(如極速模式、少接管模式)。
未來,當政策逐步放開,Robotaxi 進入規模化商業運營時,佢可能會同 C 端市場逐步分離,成為第二個車輛賽道,成為一種新型工具。」
至於技術授權服務,今年第二季度開始,小鵬已經開始向合作夥伴大眾汽車大規模交付圖靈芯片,2026 年來自技術、服務同 IP 授權嘅總收入將同 2025 年相當。
海外市場一直係小鵬核心戰略之一。
從最新月份嘅數據看,小鵬國際業務收入貢獻已接近 20%(去年全年約 10%),佔比顯著提升。
儘管有關稅等成本壓力,但國際業務帶來嘅毛利同淨利潤貢獻仍然非常可觀。
今年下半年,隨著今年下半年 4 款全球化車型推出,2027-2028 年小鵬嘅全球化速度將大幅提高,增長勢頭會持續,全年國際收入貢獻將穩定喺 20% 左右。
當然考慮到國際動蕩,小鵬都喺增加本地投資生產(如喺奧地利同麥格納合作),以確保有能力滿足歐洲及全球市場嘅增長預期。

「而家我哋喺東南亞(印尼、馬來西亞)有兩間工廠,主要滿足當地市場;喺奧地利同麥格納合作生產供應歐洲。呢三處產能今年都會提升,並生產新車型。對於東南亞國家,生產主要面向本地市場;奧地利工廠則服務於歐洲。預計我哋喺歐洲銷售嘅大部分車輛將實現本地化生產。喺尚無生產設施嘅其他地區,我哋將維持當前出口模式。隨著喺某些大市場嘅銷量同份額增長,我哋正積極尋求提升產能同本地化率嘅方法,以滿足當地化含量規則。」
何小鵬對於海外市場嘅預期係:希望未來 5 年內,海外市場嘅銷量佔一半,收入同利潤超過一半。
最後,嚟總結一下啦。
雖然小鵬第一季度表現平淡,但都係嗰句話,睇車企點樣要睇嘅唔單單係過去,仲要睇長期嘅潛力。
而家,隨著 GX、G9L 及 MONA 系列新車嘅陸續登場,小鵬已擺出咗最強產品矩陣。
此外,VLA 智駕進入大眾普及階段、海外業務都慢慢成長為新嘅業務增長極。
小鵬已經初步形成「爆款車型 + 智能化 + 全球化」嘅三輪驅動新格局。

接下來嘅半年,密集嘅新車投放將係檢驗呢一格局成色嘅試金石。
對於小鵬而言,接下來嘅課題係:點樣用好技術呢把利刃,喺更廣闊嘅全球市場中,贏得與之匹配嘅商業成果(即規模同利潤)?
下半年,市場將用訂單同毛利嚟投票,靜待小鵬逆轉戰局。
完。
BYD, the English abbreviation for BYD originally means "Build Your Dream", implying the construction of travel dreams, and in the capital market, it has also won the favor of many investors with its strong development potential. After listing on the A-share market in 2011, BYD's stock price fluctuated multiple times. In 2022, it surged to 350 to 360 yuan at one point, and the company's total market value successfully broke through the trillion yuan threshold. Affected by the continuous price war in the domestic car market and the decline in market demand in the first quarter of this year, currently BYD's A-share stock price fluctuates around 90 yuan, and the total market value is maintained in the range of 831.4 billion to 850 billion yuan. Now BYD ranks firmly in the top three globally among automakers by market value, standing shoulder to shoulder with Tesla and Toyota, but compared to Tesla's market value of over 1.5 trillion US dollars, there is still a considerable gap between the two sides. On June 9, BYD held its 2025 Annual General Meeting. Facing shareholders' doubts, Chairman Wang Chuanfu stated that the company's performance would continue to improve, the enterprise will adhere to technology innovation-driven development, advance steadily with forward-looking layout, and strive to create more considerable returns for shareholders.

At the annual general meeting, many investors were very concerned about the upper limit of BYD's market value, frequently asking if the company could aim for a market value of 10 trillion and narrow the gap with Tesla. In response, Wang Chuanfu has always regarded technology as the core confidence for enterprise progress. He stated that solid technology is the foundation for long-term development of enterprises. BYD possesses a large-scale, top-tier engineering team. The enterprise adheres to a long-term development route and relies on solid technological accumulation to expand steadily. Unlike some enterprises that rely on capital stories to boost market value, BYD deepens the essence of manufacturing, and a steady technological layout also makes the company's market value development more resilient. Reviewing the development history, it is not hard to discover that a series of core technologies such as Blade Battery, DM-i hybrid, Yi Si Fang, and Global Kilovolt High-Voltage Architecture. Every implementation drives a simultaneous rise in BYD's sales and market value.
Since the beginning of this year, BYD has continued to exert strength in the technology field, successively launching the second-generation Blade Battery, Flash Charge technology, and the industry's first 4-nanometer Xuanji A3 intelligent driving chip, continuously solidifying the technological barrier. In the field of intelligent driving, BYD's achievements are equally bright. Currently, the number of vehicles under the brand equipped with assisted driving functions has exceeded 3.15 million units, with daily intelligent driving travel data exceeding 200 million kilometers, and the intelligent driving R&D team size exceeds 5,000 people. Relying on the computing power cluster composed of three Xuanji A3 chips, the total vehicle computing power can reach 2,100 trillion operations per second, sufficient to support the operation of L3, L4 level high-order autonomous driving. Wang Chuanfu judged that with the help of artificial intelligence technology, the implementation speed of high-order autonomous driving will be faster than expected. BYD has completed full-chain technology reserves. Once relevant regulations are officially issued, it will launch compliant new cars immediately and promote global implementation synchronously. On the path of brand premiumization, BYD also insists on speaking with technology and products, abandoning flashy marketing, and winning the recognition of high-end consumers with hardcore strength. The increase in high-end model sales will also gradually solve the enterprise gross profit and single vehicle profit issues.

Faced with the status quo of sluggish growth in the domestic market, BYD chose to deepen internally and expand externally; the overseas market has already become a new growth pole. In May this year, BYD ended the trend of declining sales, with overall sales breaking through 380,000 units. Among them, overseas sales exceeded 160,000 units, a year-on-year surge of 80%. The high customer unit price in the overseas market effectively alleviated the profit pressure brought by the domestic price war. Currently, BYD's global production layout has been fully rolled out. Thailand and Indonesia factories take root in Southeast Asia, Brazil base deepens the Latin American market, Hungary factory lands in Europe, and Mexico base is also preparing intensively. The global map is gradually perfecting. Regarding charging support, BYD plans to build 20,000 Flash Charging Piles domestically this year, while launching European charging pile network construction, paving the way for the popularization of Flash Charge technology. The Denza Z9GT equipped with second-generation Blade Battery and Flash Charge technology landing in Europe has also further established the brand's high-end reputation.
Previously, BYD set a goal of 1.5 million overseas sales in 2026. Combining with the current market performance, Wang Chuanfu believes this goal is expected to be exceeded. Looking forward to the next three to five years, BYD is expected to maintain stable growth, relying on iteratively upgraded core technologies to achieve dual-wheel drive for domestic and international markets. According to the plan, by 2030, BYD is expected to become the world's largest automotive enterprise by scale. Adhering to the original intention of technology, exerting effort in the global market, this Chinese automotive enterprise is steadily moving towards the goal of "becoming the best company in the world".