


首頁香港

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
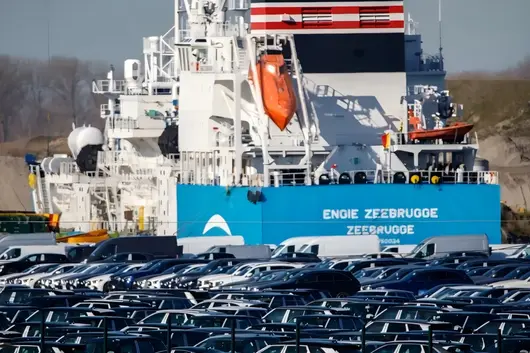

Another Japanese automaker is on the brink of a collapse.
On May 20, Subaru officially released its fiscal 2025 (April 2025 – March 2026) financial report.
Data shows Subaru's operating profit plunged 90.1% — from 405.3 billion yen in the previous fiscal year to 40.1 billion yen. Net profit also fell from 338.1 billion yen to 90.8 billion yen, a drop of 73.1%.

Despite a slight revenue increase of 2.1% for the year, the operating margin contracted cliff-like: plummeting from 8.6% to 0.8%. This means for every 100 yen of revenue Subaru generates, the final profit left is less than 1 yen, completely a case of 'losing money just to drum up business'.
Additionally, in fiscal 2025, global production fell 7% year-on-year to 880,000 units; global sales declined 4.3% to 896,000 units.
Profits, production, and sales all declined comprehensively, trapping Subaru in a 'triple kill'. For a brand selling less than a million units annually, it is walking on the 'edge of life and death'.
However, Subaru's profit avalanche is far from an isolated case; it sounds more like an alarm for the entire Japanese automaker camp losing speed during the global industry shift, also predicting that the past profit models of Japanese automakers face severe and profound reshaping.

In the internal combustion engine era, Subaru built a unique brand identity with its boxer engine and all-wheel-drive system. 'Buy Toyota if you don't know cars, buy Subaru if you do' once became a famous saying in the car circle. Models such as Forester (Forester) and Outback (Outback) accumulated a large number of loyal users in the North American and Asian markets.

Among them, the Forester launched in 1997 has accumulated over 5 million units in global sales to date. It remains Subaru's sales powerhouse to this day.
However, with the advent of the new energy era, Subaru's global sales peak was fixed in 2019.
That year, Subaru's global sales reached 1.042 million units. Among them, the North American market contributed about 700,000 units, accounting for over two-thirds.
This deep 'bond' continued to this day — in fiscal 2025, of Subaru's 896,000 global sales, the North American market alone accounted for 708,000 units, nearly 7 times that of the Japanese domestic market.
It is worth knowing that in 2011, Subaru's best-selling year in the Chinese market, it only sold 57,000 units. As a niche Japanese brand, this sales volume was outstanding, but clearly, compared to the North American market, Subaru's presence in China was still too weak.
It is precisely this heavy reliance on the North American market that led to the current suffering for Subaru.
Regarding the huge losses in fiscal 2025, Subaru stated it was mainly due to the impact of additional tariffs imposed by the United States and investments in pure electric vehicles.
Last April, the tariff rate on Japanese imports imposed by the United States rose sharply to 27.5%. Subsequently, in September, although tariffs were lowered to 15%, they were still 6 times the original 2.5% tariff rate for Japanese automakers.
Subaru was directly impacted; just tariffs caused a profit loss of nearly 240 billion yen.
At the same time, steel, aluminum, and logistics shipping prices continued to rise, further squeezing Subaru's profit margins. In response, Subaru President Atsushi Osaki admitted that profit changes were the result of tariffs, exchange rates, raw materials, sales decline, and electrification expenses acting together.
Additionally, Subaru accrued a 57.8 billion yen impairment loss related to pure electric vehicles, mainly due to initial electrification investments not meeting expectations. Previously, Subaru planned to invest about 150 billion yen for electrification transformation, but currently only disbursed about 30 billion yen. However, because its new energy products did not meet market expectations, considering this, it postponed its self-developed pure electric vehicle plan originally scheduled for 2028, and at the same time, completely transferred R&D resources back to the internal combustion engine product line.
It is worth mentioning that Subaru once hoped the pure electric SUV 'Solterra' built on the same platform as Toyota bZ4X — the vehicle was introduced to China in 2023, the 2026 model was released at the 2025 New York Auto Show, but market performance never met expectations.

This strategic turn was also the main reason for Subaru's production decline — to promote pure electric production line renovation, a production line at Subaru Japan's Yajima Factory temporarily halted.
Now, Subaru's pure electric vehicle sales target is completely lost, and related investments are basically gone.

The reason behind it is also highly similar to Honda — electrification demand in markets such as North America cooled off significantly, while North America is also one of Subaru's most important markets.
Previously, Ford CEO Jim Farley had issued a warning — the U.S. federal government's $7,500 electric vehicle tax credit policy expired on September 30, 2025, and the market share of pure electric vehicles in the United States could see 'halving'.
Facts proved him right. In the fourth quarter of 2025, EV sales in the United States fell 36% year-on-year, the lowest level for the same period since the third quarter of 2022. Among them, Tesla's U.S. market sales in November 2025 were only 39,800 units, a 23% year-on-year decline, setting a new low in nearly 4 years.
Slightly comforting for Subaru is that this policy also caused heavy losses for American traditional automakers — Ford Motor announced in December 2025 to shift focus comprehensively from pure electric cars to hybrid and extended range, accounting for impairment expenditures of up to $19.5 billion. General Motors also transferred all equity in its Lansing Battery Plant in Michigan to its partner LG Energy.
However, looking at the entire Japanese automaker camp, Subaru's profit collapse is not an isolated case.
Honda mentioned earlier, its fiscal 2025 net loss was 414.3 billion yen, setting a first annual loss in nearly 70 years since listing. The main reason was electrification business losses exceeding 1.5 trillion yen, directly dragging down the annual performance.
Nissan Motor also posted huge net losses for two consecutive fiscal years. Fiscal 2025 loss was 533.1 billion yen, forced to cut jobs and shut down factories globally.
Toyota is the only enterprise in the Japanese category that maintained profit resilience, but its fiscal 2025 net profit also dropped 19.2% year-on-year, and fiscal 2026 is expected to drop another 22%.
And according to 'Nikkei Asia Review', mainly impacted by Middle East geopolitical conflict, 7 major Japanese automakers including Toyota, Honda, Nissan, Suzuki, Mazda, Subaru and Mitsubishi Motors are expected to see profits plummet in fiscal 2026 — in the fiscal year from April 2026 to March 2027, these automakers will realize a combined net profit of 3.9 trillion yen, this data dropped 48% from the historical record high of 7.54 trillion yen in fiscal 2023, nearly halved.
It is reported that the Middle East situation led to shipping blockades in the Strait of Hormuz, pushing up prices of steel, aluminum, petrochemical plastics and precious metals, directly raising costs for automotive steel sheets, interiors, bumpers, tires, etc.
Previously, Toyota stated in the financial report release that, calculated with the USD to JPY exchange rate at 1 to 150, Middle East-related factors will collectively drag operating profit down by 670 billion yen. Nissan Motor also listed the rise in petroleum derivative material costs as one of the reasons for its expected profit decline of 15 billion yen.

Additionally, S&P Global Corporation's analysis report said that in 2025, Japanese automakers' new car sales in 10 Middle Eastern countries such as the UAE and Iran broke through 870,000 units, accounting for about 30% of the market share in the region. Obstructed passage in the Strait of Hormuz also directly affected Japanese automakers' sales in the Middle Eastern market.
At the same time, Japanese automakers' overall market share in the Chinese market and Southeast Asian market also declined.
In the Chinese market, Nissan sales have declined for 7 consecutive years, Honda for 5 consecutive years, even Toyota, sales in China have also declined for 3 consecutive years, to date sales remain lower than in 2020.
In the Southeast Asian market, among the six major ASEAN countries including Indonesia, Malaysia, Thailand, Vietnam, Philippines, and Singapore, Japanese car new sales in 2025 declined by 22% overall compared to 2019.
And in the Australian market, in the first 4 months of this year, Australia's imports of cars from China reached 107,200 units, a 60% surge year-on-year; while imports of Japanese cars were only 94,500 units, a 23% plunge year-on-year.
It is worth mentioning that Japan lost the status of the largest car import source country in Australia for the first time since 1998.

The Japanese brand falling behind in the new energy era reflects the electrification landscape of ice and fire under global differentiation.
In 2025, global new energy vehicle sales reached 22.71 million units, a 27% year-on-year increase, penetration rate rose to 23.5%.
Among them, China has become the undisputed leader. New energy vehicle sales in 2025 reached 15.8 million units, penetration rate broke through 48%. Even BYD surpassed Tesla with 2.2567 million pure electric sales, topping the global pure electric sales champion.
However, although China is almost pulling new energy popularity with its own strength, for Japanese automakers, to hold core markets, they still need to rely on internal combustion engines and traditional markets such as Europe and the US in the short term, where pure electricity is not the mainstream.
Referencing peak data from 2022, the basic platform of Japanese automakers' traditional internal combustion engines highly relies on the North American market (sales share 38%, far higher than China's 17%), combined with 13% contribution from the European market, European and American markets combined share exceeded half, becoming their important overseas pillar.
But the reality is, driven by strict carbon emission policies, Europe's new energy penetration rate is still less than 30%; while the US market is even lower, only 17%. Policy fluctuations and weak demand further amplified Japanese automakers' passivity and risk during the comprehensive industry shift period, and also became the main driver for Subaru, Honda, and other automakers to temporarily abandon pure electricity.
In fact, not only Japanese cars, multiple global automakers are also slowing down the pace of pure electricity — Volkswagen delayed pure electric capacity expansion, BMW and Mercedes also contracted their lines, retreating to defend the higher profit high-end pure electric market; Toyota insists on 'Hybrid + Hydrogen + Pure Electric', not letting any go.
The core contradiction behind this lies in: R&D and production line renovation costs that often run into billions, encountering the global price involution led by Chinese automakers, in the situation where pure electric business is generally loss-making, blind radicalism will only drag down financial reports.
Therefore, automakers can only temporarily set aside long-term layouts, prioritizing guaranteed short-term profitability.
However, if the perspective is lowered, the Japanese dilemma has its unique structural problems: As a car power, why has Japan never been able to wait for a disruptive new car power?
The answer is actually in the mystery — Toyota, Honda and other automakers, with supply chain giants like Aisin, Denso, etc., after decades of global layout, have formed a highly closed monopoly system from supply chain to sales channels.
This huge and solidified vested interest structure leads to its capital logic being extremely conservative — in electrification transformation, traditional transmission, engine technologies are replaced by batteries, motors, control systems, traditional technology advantages instead become a burden for transformation.
Therefore, capital prefers to maintain the existing giant basic platform, rather than risking bets on startups with unclear prospects.
Excessive maintenance of stock interests has solidified the innovation soil of the Japanese automotive industry, making it difficult for new forces to grow and break out.

Additionally, since the 1970s, Japan has begun researching hydrogen fuel cells, leading to a lack of support for the pure electric route in both policy and consumer end, and Japanese consumers prefer K-Car (Mini Cars) and mature hybrid technology, combined with high battery costs, low adoption rate of charging facilities, pure electric models insufficient attraction to consumers.
As of February 2026, the proportion of Japanese pure electric vehicle new car registrations in the overall passenger car market is only 1.4%. Almost negligible.
Overall, Japanese automakers have not completely lost technical depth, their hesitation and falling behind in the new energy era, the root lies in the lack of motivation for self-disruption.
Joint factors such as giant vested interests, government hydrogen energy policy orientation, low market acceptance of pure electricity, plus capital's natural avoidance of risk, jointly led to the 'New Force Model' being difficult to survive in Japan.
Currently Toyota, Nissan, etc. also fill the short board by importing Chinese pure electric models, but under the background of monopoly system not broken, market electrification transformation slow, Japanese survival by defense path is still difficult.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。
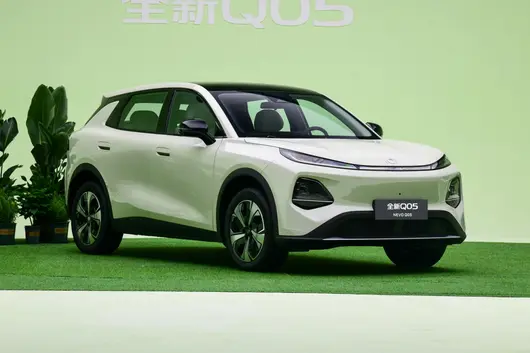
唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。

(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
 (零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
 (長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
 (零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
 (長安啟源全新 Q05)
 (零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
 (長安啟源全新 Q05)
 (零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
 (長安啟源全新 Q05)
 (零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
 (長安啟源全新 Q05)

(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。

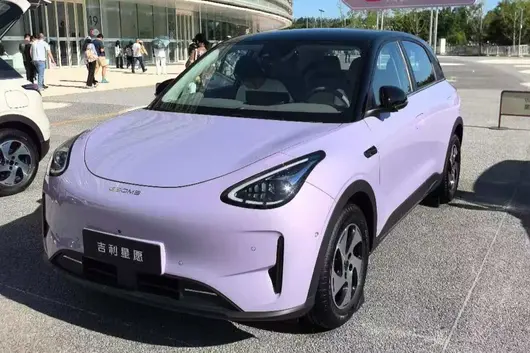
先睇一個情況:2025 年中國車市銷量最高嘅單一車型,唔係 Model Y,都唔係比亞迪秦,而係一輛起售價唔到 7 萬元嘅 A0 級純電細車——吉利星願。全年 465,775 輛,全品類銷冠。將燃油車、SUV、MPV 全計上,佢排第一。等於每分鐘賣出一台,573 日累積交付突破 70 萬輛,係全行業最快達成呢個目標嘅車型。
2026 年第一季度,呢部車再進一步,殺入全球新能源車型銷量前三,僅次於 Model Y 同 Model 3,係唯一進入呢個榜單嘅中國品牌車型。
而 5 月 28 日,佢又加碼咗。全新吉利星願正式上市,推出 410km 嚮往版、410km 乘風版、480km 探索版、480km 探索 + 版四款車型,限時權益價 6.18 萬至 9.18 萬元,打出「五大冠軍實力進階」嘅旗號。
問題出現咗:已經拿到國內銷冠嘅選手,點解仲要大興師動眾咁換代加碼?我嘅看法係答案只得一個——吉利嘅野心早已唔係國內第一,而係全球新能源車銷量第一。

一、由「國內銷冠」到「全球前三」,星願憑咩?
理解「點解吉利敢諗全球第一」,先睇舊款星願嘅成績單:
數據層面,由 2024 年 10 月上市至 2026 年 5 月換代,573 日累積交付 70 萬輛。2025 年以 46.58 萬輛拿下年度全品類銷冠,A0 級純電轎車全年總銷量 132.3 萬輛,星願一款車就佔咗超過 35%。每賣三台 A0 級純電,就有一台係佢。
海外層面,星願以 EX2 之名已經進入全球 30 多個國家同地區。巴西上市兩個月銷量突破 2300 台,泰國車展單週訂單 3300 台,仲奪得「巴西年度最佳緊湊型電動車」同「印尼車展最受喜愛電動車」兩項國際大獎。喺埃及,每賣出 3 輛電動車就有 1 輛係星願;墨西哥預售訂單超 4100 個;英國單月上牌量破千。
產品力層面,舊款星願能破圈,靠嘅唔係某個單項參數嘅領先,而係一套「錯位競爭」:全系標配後置後驅同多連桿獨立懸掛,同級第一個採用原生架構、第一個標配後驅獨懸、第一個經過全球化調校;軸距 2650 毫米,跨入 A 級車空間門檻;全系寧德時代電芯,奠定咗續航同電池安全嘅信任基礎。
呢套組合策略背後係「三拳合擊」——用 A0 級嘅價格、準 A 級嘅空間、15 萬級車先常見嘅底盤素質,同時向上搶家庭用戶、向下壓代步剛需群體。殺傷力從銷量走勢就能睇得出:2025 年 5 月星願月銷接近 3.9 萬輛,8 月拉大到 4.6 萬輛,2026 年 4 月仍以 41,938 輛穩居榜首,競爭對手同佢嘅差距依然好大。

二、全新星願加咗啲咩碼?
1. 駕控進階:此次針對唔同極端路況進行全維驗證,喺「行駛、轉向、煞車」三大核心體驗上全面升級。G-TCS 2.0 全天候防滑系統保留後驅靈活樂趣嘅同時,確保平路、坡道、彎道唔打滑、唔甩尾、唔溜車;全新無刷轉向系統響應快 1 倍,支援三種轉向模式及轉向中位自學習;G-CST 2.0 全場景舒適制動系統模擬老司機腳感,煞車唔點頭、行車唔暈車。
2. 三電進階:舊款 310 公里版本升級為 410 公里,410 公里版本升級為 480 公里,全系續航升級。電池依然採用寧德時代專屬定制全新一代電芯,能量密度 190Wh/kg,係同級唯一全系標配寧德時代電芯、液冷溫控及 11 合一高集成電驅嘅純電細車。補能方面,30%-80% 快充仅需 19 分鐘,液冷系統同全新 BMS 保障天冷天熱都能滿速充電,且唔以犧牲電池壽命為代價。

3. AI 智艙進階:搭載銀河 Flyme Auto 2 智能座艙系統,基於 7 納米車規級龍鷹 1 號芯片,16G 運存加 128G 儲存。14.6 吋中控屏支援 CarPlay、華為 HiCar、Carlink 全域互聯。語音助手 Hi Eva 支援模糊指令理解及上下文記憶,講一句「我要回家」即可以自動調用最新高德 850 版選擇最優路線。
4. 輔助駕駛進階:呢係最核心嘅變化——搭載與高端車型同源嘅千里浩瀚輔助駕駛 H3 方案。高速高架 NOA 唔受道路同雨霧天氣限制,支援語音變道、多場景避讓及自動上下匝道,全場景 MPI 接管率超 200 公里。泊車能做到全場景適配,APA 泊車輔助支援一鍵泊入、指尖泊車、遙控泊車,覆蓋 300 多種場景。HPA 記憶泊車支援 2 公里超長記憶、厘米級精準定位,學習一次路線後即可全程自動泊入,具備智能跟車、自主找位、遇障繞行功能,臨時改道唔需要重新學習。

三、市場對比
2026 年嘅 A0 級純電市場,競爭烈度比前兩年高咗唔止一個層級:
產品力維度,A0 級純電已經由「有冇」進入「好唔好」階段。星願嘅優勢係底盤素質同空間表現喺同級中處於頭部水準,2650 毫米軸距帶嚟嘅越級空間、後驅獨懸嘅底盤佈局,係呢個價位段極為稀缺嘅組合。千里浩瀚 H3 智駕方案同 Flyme Auto 2 座艙系統屬於吉利生態能力嘅下放,智能化嘅完整性同易用性喺同級中具備明顯代差優勢。19 分鐘快充令補能便利性得到實質提升。
市場格局維度,2025 年 A0 級轎車零售量達 113 萬輛,同比增長 59%,係增長最快嘅細分市場之一。參與者加速湧入,五菱繽果 S 續航拉到 525 公里,MG4 定價下探形成跨界競爭。但轉折出現喺 2026 年——購置稅補貼由全額免徵調整為減半徵收,對價格敏感度極高嘅 A0 級用戶群體形成直接衝擊。第一季小型電動車市場增速明顯放緩,部分競爭對手車型 4 月銷量同比下滑超過 50%,市場正經歷劇烈嘅結構性調整。

四、結語
回到開頭嘅問題:全新吉利星願再加碼,呢係想拿下全球新能源車銷量第一咩?我嘅判斷係:係嘅,但路線唔係靠單一爆款,而係靠全球化嘅系統能力。而全新星願嘅呢次換代,可以話係「冠軍嘅再佈局」。佢唔係被動應戰,而係喺對手仲未追上就再加碼主動去拉開新差距。對於佢嚟講,而家技術路線揀對咗,市場趨勢都站喺佢邊度。剩下嘅,就看執行力啦。
The 2026 North American World Cup is less than two weeks away.
As usual, the core of the discussion is whether Mbappé can defend the title, whether Messi is still playing, and who is the new king of football. But if you glance away from the pitch, you might find the supporting cast of this World Cup is the most outrageous in history.

Image source: World Cup Organizing Committee
660 official designated vehicles, a Robotaxi network covering multiple stadiums, 42 electric buses from Shandong, China, humanoid robot Atlas, quadruped robot dog Spot.....
These "supporting characters" are all car companies.
Hyundai Kia's 27-Year Marathon: Money Spent, But Not Worth ItWhen discussing the relationship between car companies and the World Cup, Hyundai Kia cannot be avoided.
In 1999, Hyundai partnered with FIFA for the first time. At the 2002 Korea-Japan World Cup, they invested about 1.5 billion euros to secure official sponsorship, resulting in a 40% surge in sales in the US market that year, and brand awareness jumping from 32% to 67%. The calculation was too attractive, so Hyundai never considered withdrawing for over 20 years since then, renewing the partnership all the way to 2030.
This World Cup, Kia provides 660 official designated vehicles to handle athlete and official transport. The Korean automotive industry estimates that just from in-stadium advertising exposure, the Hyundai Motor Group's cumulative commercial value exceeds 10 trillion won.

Image source: Hyundai Kia
But can World Cup sponsorship really convert to sales?
Hyundai's own experience gives an uncertain answer. The 2002 bonus was real, but the story since then hasn't looked so good. Beijing Hyundai's sales peaked at 1.14 million units in 2016, declining ever since. By 2021, it dropped to only 382,000 units, a decline of over 66%. Nowadays, it's even worse; Hyundai Kia's sales for January to April were only over 30,000 units, less than what new EV players achieve in a month.
Throwing money at the World Cup cannot save Hyundai Kia's decline in China. Interestingly, Hyundai also seems to have realized this issue.
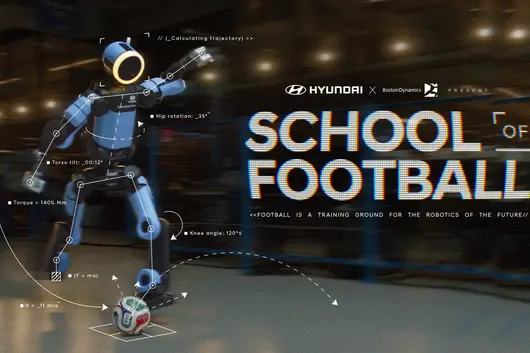
For the 2026 World Cup, Hyundai made a key adjustment: Expanding the sponsorship scope from traditional fuel vehicles to autonomous driving, robotics, and future mobility technology. Hyundai partnered with its subsidiary Boston Dynamics to deploy humanoid robot Atlas and quadruped robot Spot in designated venues, responsible for event operations and security.

Image source: Hyundai Kia
A somewhat awkward question is, are the cool-looking Atlas and Spot in the arena event operation infrastructure, or is it just an extremely expensive brand show?
Electric Vehicle Channel (ID: dianchetong233) judges it's both, but leans towards the former.
Hyundai needs to use the World Cup, the largest traffic pool globally, to send a signal to investors and consumers: We have transformed into a "Future Mobility Tech Company". Boston Dynamics' robots are the best prop to convey this signal. As for whether they can really make money, that's for the next step.
However, this World Cup is indeed a good time for Hyundai. The North American market accounts for over 20% of its global sales. The joint hosting by the US, Canada, and Mexico equals holding a press conference facing 3.5 billion viewers in one's own backyard.
The 27-year marathon has found a new narrative direction at this moment.

Image source: Boston Dynamics
Chinese Car Makers Don't Pursue Sponsorships, This World Cup Plays "Borrowing the Road"The relationship between the Chinese men's national football team and the 2026 World Cup can be summarized in one word — None. Last year, they lost away to Indonesia in the World Cup qualifiers' 18-team round and were eliminated a round early. Chinese fans don't have to worry about the time difference again.
But the relationship between Chinese car makers and this World Cup is very close. And the path they take is completely different from Hyundai Kia.
Changan is the most typical example.

Image source: Changan Automobile
On May 22, Changan signed an agreement in Lisbon with the Portuguese Football Federation, becoming the Portuguese National Team's Global Official Partner. The cooperation covers the 2026 and 2030 World Cups and the Women's World Cup cycle, with an investment of over 500 million yuan.
The logic behind choosing Portugal is very smart. This is not generalized World Cup sponsorship; Changan did not compete for the FIFA official sponsor position, but rather precisely bound with one team.
This team has Cristiano Ronaldo. Over 1 billion fans globally, 660 million Instagram followers, and the fan distribution highly overlaps with Changan's core overseas markets: Europe, Southeast Asia, South and Central America, Middle East Africa. Concentrate resources to do big things.

Image source: Changan Automobile
Using the scarcity of Cristiano Ronaldo's last World Cup as a lever to leverage brand awareness breakthrough in overseas markets. The supporting actions include the co-branded film "Sounds like Changan", the first European delivery of Deepal S05 in Italy, the European 1,000-kilometer long-distance test, and joint activities by global dealers. Every step is correct, but every step has uncertainty.
European consumers' stereotypical impression of Chinese car brands was not formed in one day, and it won't dissipate due to one sports marketing campaign. Korean and Japanese car makers opened the European market back then by relying on decades of quality accumulation and in-depth localization. Changan wants to shorten this process with a 500 million yuan cooperation with a team; results need time to verify.
Another case is Zhongtong Bus.
42 N12 dual-source trolleyless electric buses were shipped from Liaocheng, Shandong to Mexico City, undertaking public transport during the World Cup. Completely different from Changan's brand marketing route, Zhongtong follows product as marketing. The buses running in Mexico City are themselves a moving billboard.

Image source: Zhongtong Bus
In 2025, China exported 625,200 vehicles to Mexico, with Mexico surpassing Russia for the first time as China's largest automotive export destination. In the first quarter of 2026, China exported 2.226 million vehicles, up 56.7% year-on-year; new energy vehicles exported 954,000 units, up over 120% year-on-year.
Zhongtong's electric buses appearing in Mexico City is also a microcosm of the systematic penetration of China's automotive industry in the Latin American market.
What about BYD? Although they did not directly sponsor this World Cup, their sports marketing map is already the most complete Chinese car maker — 2024 Euro Cup, 2024 Copa America, 2025 European U21, plus a five-year 75 million yuan sponsorship contract with the Chinese Football Association, covering almost all mainstream football IPs. Now, BYD's single-month export in April exceeded 130,000 units, with cumulative overseas sales exceeding 450,000 units.

Image source: BYD
Nowadays, BYD no longer needs to spend a huge sum to grab a logo spot on the World Cup.
Three paths, one consensus — Chinese car makers going global have passed the stage of whether to participate in global marketing, entering the stage of how to participate more smartly. Hyundai Kia used 27 years to figure out sports marketing experience; Chinese car makers are rapidly catching up with shorter cycles and more diversified strategies.
Robotaxi and Robots: The Most Expensive Practical ExamThis World Cup saw a large number of autonomous driving and robot elements.
Let's talk about a timeline first.
In January this year, a Waymo autonomous taxi hit and injured a child near a primary school in Santa Monica. In the same month, another Waymo drove past a stopped school bus with warning lights on in Texas and was investigated by the US National Transportation Safety Board (NTSB).
On May 12, Waymo announced the recall of 3,791 Robotaxis — the autonomous driving software had perception defects on waterlogged roads, potentially causing vehicles to drive into roads submerged by water.
But it was also this month that Waymo expanded its Houston service area to nearly 50 square miles, directly covering NRG Stadium — one of the 2026 World Cup venues.

Image source: Waymo
Recalling on one side, expanding on the other. Looks contradictory, but this contradiction explains a real state — Robotaxi commercialization is experiencing a stage of fixing while running. Not perfect, but participants cannot wait for it to be perfect anymore.
It's not just Waymo. Atlanta, Dallas, Los Angeles, Miami, multiple World Cup host cities have already started Robotaxi commercial operations or pilots. In April, Tesla invested 573 vehicles at once in Dallas and Houston to launch fully unmonitored services, directly skipping the safety officer stage — but safety data for these 573 vehicles has not been disclosed so far.
Why are these companies rushing to expand densely before the World Cup?
The reason is simple: The World Cup is a global high-exposure stress test. Millions of fans flood into the city, traffic demand surges, perfectly verifying the autonomous driving system's performance under extreme load. Success is the best advertising; if problems occur, they are at least exposed in real scenarios — much more valuable than closed-door testing.

Image source: Hyundai Kia
And there is a common feature — These Robotaxi networks will not be withdrawn as the World Cup ends.
Waymo's Houston service area was not designated temporarily; it is permanent urban traffic infrastructure. Tesla's 573 vehicles in Dallas will also not stop operation after the event. The World Cup is just a node, not the end.
Back to Boston Dynamics' robots, why did Hyundai want to put them into the arena?
Because robots are the most scarce visual asset in the current automotive industry narrative. Autonomous driving is hard to perceive with the naked eye — sitting in a Waymo feels about the same as riding in an Uber. But a two-meter tall humanoid robot patrolling the arena corridor has a completely different visual impact.
What Hyundai needs is an image that can be remembered at a glance.

Image source: Boston Dynamics
The number Hyundai gave itself is: Planning to deploy 25,000 Atlas units inside factories by 2028. If this plan can land, the few on the World Cup are small-scale verification. If it can't land, then they are purely marketing props.
For now, both possibilities exist.
After the Final WhistlePutting together the automotive map of this World Cup, several lines are very clear.
Hyundai Kia used the 27 years of FIFA relationships accumulated to upgrade sponsorship scope from sticking logos to showing technology. But how much actual revenue World Cup sponsorship can bring, even Hyundai might not be able to say clearly — its defeat in the Chinese market is a warning for the future.
Looking the other way, Chinese car makers chose a smarter curved path — Changan binds the Portuguese team for branding, Zhongtong does products in Mexico City, BYD uses multi-IP coverage for the system. Three different paths, but all answer: How to make overseas consumers believe in Chinese cars.
And Robotaxi and robots are the freshest elements of this edition, and also the riskiest. Waymo recalls while expanding, Boston Dynamics' robot costs remain high — they still have a distance from truly reliable infrastructure, but car companies cannot wait anymore.


港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。

喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。

天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。

截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。

喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。

2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。

喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。

截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。

營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。

更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。

此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。

天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。
"In the past, selling Toyotas, the first thing customers would say upon entering was: When can I pick up the car? Now the first thing is: Whose intelligent driving system does this car use?" This is what a Toyota 4S shop salesperson told me recently.
He entered the industry in 2018. At that time, the Camry had price markups, people queued for the Highlander, and the Alphard was like a financial product. The hardest part of selling Japanese cars was not selling the cars, but calming the customers' emotions.

But now, the one thing he does most every day is explain: 'Our cars actually use a lot of Chinese supply chains.' When he said this, his tone even sounded a bit proud.
Indeed, ten years ago, Chinese automakers were still figuring out how to make door gaps even; five years ago, Chinese new energy vehicles were completely overshadowed by the industry; and now, if Japanese cars want to do new energy well, the first thing has become: Connect to the Chinese supply chain first.
You will find that when an era truly ends, it is often not because someone fell.
Instead, people who were once high and mighty start to actively learn from you.

Recently, sales of Toyota's pure electric SUV broke ten thousand again. Many people interpret this as a 'Japanese counterattack'. But if you take this car apart to look, you will find things are not that simple.
Momenta Intelligent Driving, Hesai LiDAR, Desay SV Domain Control, FinDream Battery, CALB, Zhengli New Energy...
To put it bluntly, many so-called 'Japanese new energy vehicles' now look more and more like 'Japanese shells assembled by the Chinese supply chain'. But the issue is, this precisely shows that China's automotive industry has truly won. Because true industrial victory is never about crushing others, but even your rivals are forced to use you.
This is actually more terrifying than sales overtaking.
In the past, everyone always said Chinese automakers were 'overtaking on a curve'. Looking back now, this statement was actually too conservative. China's automotive industry isn't about overtaking at all; it's about changing the track entirely.

In the internal combustion engine era, why was the Japanese supply chain strong? Because that era competed on precision manufacturing, stable quality control, long-cycle iteration, and a closed supply system. To put it simply, it was 'slow work yields fine results'. Toyota's system was essentially the highest level of order in the industrial era.
The problem is, the new energy era is different.
Now it competes on iteration speed, software capability, cost control, supply chain collaboration, and large-scale rapid trial and error. In the past, a car model was replaced every five years; now there is an OTA update every half year; in the past, suppliers took three months to change a mold; now Chinese manufacturers take three weeks.

In the past, the strongest point of Japanese manufacturing was 'not making mistakes'. Now the strongest point of Chinese manufacturing is allowing rapid mistakes, then rapid evolution. These are two completely different industrial philosophies. So many people actually misunderstand Chinese new energy vehicles. Everyone always thinks Chinese automakers win because they are cheap. But what is truly terrifying is never the low price. It is that China now possesses 'cheap', 'good enough', and 'fast' all at once.
This is the most scary part. Because the most unsolvable thing in the industrial world is that you are cheaper than me and iterate faster than me. This is also why, today, more and more Japanese suppliers are starting to collapse. Many people see Japanese parts companies going bankrupt and think it is just a sales issue.
Actually, it's not. The real problem is that the industrial logic upon which the entire Japanese supply chain relies is starting to fail. In the past, the biggest moat for Japanese suppliers was the Keiretsu system. Toyota only used the Toyota system; Honda only supported the Honda supply chain. Denso, Aisin, Jtekt, Yazaki... the whole system was like a closed empire.
But in the new energy era, there is a particularly cruel thing: closed systems mean slow. And being slow is almost a mortal sin today.
So you will see a particularly absurd phenomenon. In the past, Chinese suppliers desperately wanted to get into the Japanese system; now Japanese automakers are coming to Chinese suppliers. Because without using the Chinese supply chain, cars simply cannot compete.
This is particularly obvious in Southeast Asia. Two years ago, many people were still discussing: 'Will Chinese cars fight fiercely with Japanese cars in Thailand?' But now it is found that it is not a 'head-to-head match'. Instead, the Chinese supply chain directly penetrated into Japanese car factories.

This is more ruthless than grabbing the market. Because grabbing the market is just grabbing sales. Grabbing the supply chain is equivalent to grabbing the industrial lifeline. In the past, one of the scariest points of Japanese manufacturing was that it controlled the Asian industrial system. Now this control is shifting. And it is shifting very quickly.
The most interesting thing is that the Japanese themselves actually realized the problem first. The Nikkei has started to frequently use words like 'Keiretsu Dissolution'. Translated, it is actually just one sentence: The core thing of the Japanese automotive industry is collapsing.
So today the most painful are no longer Japanese brands, but that group of Japanese suppliers. Because vehicle manufacturers can at least 'surrender'. The supply chain is not that easy to turn around.
Toyota can still use Chinese intelligent driving; Nissan can still accept Chinese batteries; Honda can still learn new EV brands to do cockpits. But what about those traditional suppliers?

All advantages established in the internal combustion engine era suddenly became useless. More cruelly, the most important things in the new energy era, batteries, intelligence, software, intelligent driving, China has almost occupied all of them.
So you will see a particularly darkly humorous picture. On one side, Japanese media are heartbroken over 'Japanese car soul handed over to China'; on the other side, Japanese suppliers are taking BYD orders again to stay alive. This is actually very much like dynastic transitions in history.
People of the old era will not disappear suddenly. They will first be shocked, then deny, then angry, and finally join.
Many people still think China's automotive industry is just 'new energy leading'. But I think the real change is far more than cars. Cars are just the most obvious open exam for China's manufacturing upgrade. Because cars are the crown of industry. Behind it are connected chips, materials, software, batteries, machinery, manufacturing, AI, automation, and supply chain collaboration.

Whoever wins the car has the qualification to reconstruct the next generation industrial order. And what is truly terrifying about China today is that a 'supply chain black hole effect' is starting to appear.
What is a black hole? It means all industries will eventually be sucked into it.
You make cars, you have to connect to Chinese batteries; you do intelligent driving, you have to connect to Chinese computing power; you do supply chains, you have to accept Chinese speed; you do manufacturing, you have to adapt to Chinese costs.
It is highly likely that a very realistic situation will appear in the future. Manufacturing industries that do not join the Chinese supply chain will find it harder and harder to stay at the table. This is not some nationalistic emotion. This is industrial law.
Because at the end of manufacturing development, it is no longer about single-point technology, but about who can compress the entire supply chain into 'one machine'.
And the strongest ability China has now is this. From batteries to intelligent driving, from parts to whole vehicles, from R&D to mass production, China's industry has truly formed a complete closed loop, super-large scale, super-high-speed iteration, and super-strong cost control for the first time.
This thing is what is truly making the whole world anxious today. So look back at those news of 'Japanese cars using Chinese supply chains'.
You will find that its true meaning is not 'Chinese parts entered the Japanese system'. It is that Chinese manufacturing has begun to become the global industrial system itself for the first time.
隨著電動化、智能化全面深化,汽車主流供應鏈企業開始從幕後走上台前,喺汽車產業大變局同汽車產業生態重構過程中實現角色躍遷,而不係侷限於往昔車企嘅配套者。其「上位」嘅底層邏輯係,借力電動化、智能化新賽道,實現技術範式轉換,達成技術溢價,同車企成為新汽車底層技術棧嘅共同定義者同平等參與者,進而實現品牌溢價,影響力直接觸達消費端。汽車供應鏈企業迎來全面進階嘅戰略性發展機遇。
圍繞供應鏈企業進階,《汽車縱橫》特作本期「封面故事」專題報道。

而家,新能源產業正站喺新嘅歷史節點。喺呢場能源革命同科技革命交匯、現實同未來疊加嘅歷史進程中,寧德時代始終以行動回答一個問題:點樣喺不確定嘅世界入面,構建確定性嘅長期價值?
寧德時代財報顯示,其 2025 年營業額高達 4237.02 億元,純利為 722.01 億元,全球市場份額達 39.2%,連續 9 年動力電池裝車量排名全球第一。值得關注嘅係,呢家處於整車製造上游嘅供應鏈企業,去年純利超過咗 13 家主流整車上市公司嘅利潤總和。「車企俾寧王打工」嘅調侃,似乎已照進咗現實。
呢一現象背後,係寧德時代對全球主流車企嘅影響力。而一切嘅起點,正係動力電池喺新能源汽車產業中嘅核心地位——動力電池約佔整車 40% 成本,係新能源汽車毋庸置疑嘅「心臟」。對整車企業嚟講,穩定可靠嘅電池供應,早已從基礎保障性需求,升維為關乎產品競爭力同長期發展嘅核心戰略需求;對寧德時代嚟講,點樣將「頭部客戶」轉化爲「戰略盟友」,同樣係決定其商業版圖天花板嘅關鍵課題。
咁,寧德時代究竟係點樣憑一己之力「綁定」近半個汽車圈呢?究其原因,從動力電池供應商到全域能源生態服務商,寧德時代用十幾年時間構建起一套覆蓋資本、產能、研發、保供、生態等全方位嘅深度綁定體系。正係呢套體系,將全球主流整車企業牢牢納入自身產業版圖,實現咗從「賣電池」到「定標準、建生態」嘅躍遷,亦徹底重塑咗供應鏈企業同整車企業之間嘅「整零」關係。
資本綁定
喺電動化重構汽車工業嘅浪潮中,寧德時代跳出傳統供應商「供貨收錢」嘅單一模式,以直接投資、戰略入股、合資控股等多元資本手段,深度滲透整車企業股權結構,將供需關係升級為利益共同體、戰略共生體,從資金、話語權、資源層面實現全方位綁定,筑牢產業話語權根基。
據不完全統計,截至 2026 年 5 月底,寧德時代通過直接或者間接方式投資入股嘅新能源整車企業超過 10 家。最新嘅動作係,2026 年 5 月 25 日,賽力斯集團发布公告,其旗下子公司重慶藍電科技有限公司獲得五家投資方合計 66.71 億元增資,喺投資方名單中,寧波梅山保稅港區問鼎投資有限公司(以下簡稱「問鼎投資」)以 9.84 億元嘅出資額位列第三,持股比例 9.878%。而呢家問鼎投資正係寧德時代 100% 持股嘅子公司。
稍早前嘅 2026 年 5 月 12 日,廣汽集團同華為乾崑聯合打造嘅高端智能新能源汽車品牌啟境汽車宣布,已完成總額超 10 億元嘅戰略增資,由寧德時代、博世旗下嘅投資平台以及多家央國企資本投資。據了解,寧德時代此次投資亦係通過全資控股嘅問鼎投資實繳出資 3 億元,為單一最大投資方。
事實上,寧德時代嘅投資版圖遠遠唔止呢些。喺新能源江湖入面,「寧王」唔只係個賣電池嘅,仲好似一個拿著資本地圖到處「組局」嘅超級玩家。2021 年,寧德時代豪擲 7.7 億元,以 23.99% 嘅持股比例成為阿維塔嘅第二大股東,當時形成咗獨有嘅 CHN(即長安 + 華為 + 寧德時代)模式。作為回報,阿維塔唔只全系標配寧德時代電池,仲全球首發咗寧德時代嘅磐石滑板底盤。

此外,寧德時代仲係極氪汽車嘅早期投資人,參與咗極氪嘅 Pre-A 輪融資。寧德時代唔只通過問鼎投資持有奇瑞約 2.97% 嘅股份,雙方仲成立咗註冊資本 20 億元嘅「時代奇瑞」合資公司。上汽同寧德時代其實早係老搭檔,寧德時代持有上汽旗下智己汽車約 0.48% 嘅股份。喺北汽新能源 2024 年底嘅超 80 億元大融資中,寧德時代出資 2 億元入股。
喺商用車領域,2026 年 3 月,寧德時代旗下嘅溥泉資本參與領投咗零一汽車 12 億元嘅融資。2025 年 11 月,一汽解放公告對合資公司「解放時代」增資 1.91 億元,寧德時代同步增資,三方合計增資 4.12 億元,呢家成立於 2023 年、由一汽解放同寧德時代各持股 50% 嘅合資企業,唔過係寧德時代近年來通過資本紐帶深度綁定整車廠嘅縮影而已。
喺海外市場,寧德時代同樣採用合資參股邏輯。2024 年 12 月 10 日,寧德時代同 Stellantis 各持股 50%,投資 41 億歐元喺西班牙薩拉戈薩建設一座大型磷酸鋰鐵電池工廠,產品專供 Stellantis 歐洲車型,資本綁定助力寧德時代深度滲透海外主流車企。
當然,寧德時代喺投資車企方面亦踩過坑。比如,寧德時代曾持有哪吒汽車約 2.67% 嘅股份,早期仲投資過愛馳汽車。不過呢兩家造車新勢力從目前嘅情況睇,已基本退出市場。
寧德時代嘅資本綁定,絕非簡單嘅財務投資,而係重構整零關係、掌控產業話語權嘅戰略佈局。呢種資本織網模式,讓寧德時代從單純嘅電池供應商,升級為整車企業嘅戰略夥伴、利益共同體,喺電動化浪潮中牢牢掌握產業主導權,為技術、產能、生態等領域嘅全方位綁定奠定堅實資本基礎。
產能鎖定
如果話資本係紐帶嘅骨架,那產能就係血肉。喺電池供需週期性緊張、原材料價格波動加劇嘅行業環境中,穩定產能就係核心競爭力。寧德時代產能綁定嘅策略可以用一句話概括:把電池產能建到最需要佢嘅地方去——緊鄰整車廠嘅超級工廠,甚至直接建喺客戶嘅車間入面。寧德時代通過專屬產線、廠中廠、區域基地三種模式,為合作車企提供確定性產能保障,以「產能鎖定」實現深度綁定。
2025 年 6 月 30 日,寧德時代喺賽力斯超級工廠嘅兩條 CTP 2.0 高端電池包產線正式投產,係寧德時代首次同整車廠採用「廠中廠」模式進行合作,為問界系列車型本地化生產供應動力電池系統。「廠中廠」模式係一種創新嘅供應鏈協同模式,寧德時代將電池生產線直接建喺賽力斯超級工廠內,實現咗動力電池從下線到裝車嘅高效閉環管理。電池實現「即產即裝」,省去包裝、運輸、倉儲等中間環節,供應鏈響應速度縮短至 20 分鐘級。

如果話「廠中廠」只係一種創新模式嘅試水,那麼寧德時代廣泛同上汽、廣汽、一汽、東風、吉利、長安等主流車企設立嘅動力電池合資公司,如時代上汽、時代廣汽、時代吉利、時代長安等,佢哋通常以 51% 嘅持股,牢牢掌握控股权。早在 2017 年,寧德時代就同上汽集團合資成立咗「時代上汽動力電池有限公司」,總投資額高達上百億元。呢種前瞻性嘅佈局,讓上汽喺隨後嘅新能源轉型浪潮中吃足紅利。當其他友商為了搶電池而喺寧德時代總部門口排長隊時,上汽卻能通過時代上汽嘅專屬產線,穩穩當當地拿到符合自己定制需求嘅電池包。
2026 年 2 月 13 日,時代奇瑞(合肥)新能源科技有限公司正式成立,註冊資本高達 20 億元,由寧德時代、奇瑞汽車、奇瑞商用車(安徽)有限公司共同持股,其中寧德時代持股 51%,後兩者合計持股 49%。根據協議,奇瑞將優先獲得寧德時代麒麟電池、鈉離子電池等核心產品嘅供應權,而寧德時代則通過技術授權與聯合研發,推動半固態電池、換電模式等創新技術喺奇瑞高端車型上嘅應用。
喺海外佈局嘅德國、匈牙利、印尼等工廠,寧德時代同樣都實現咗「整車喺邊,電池產能就喺邊」。對特斯拉、大眾、寶馬等國際車企,歐洲基地就近配套;對奇瑞、吉利、零跑等出海車企,東南亞基地同步跟進。區域化產能佈局有效規避貿易壁壘、物流風險同匯率波動,讓整車企業喺全球市場擴張中始終擁有穩定電池保障。
產能鎖定嘅底層邏輯,係用確定性供應對抗不確定性週期。對整車企業嚟講,寧德時代嘅產能保障意味著新車上市唔卡頸、旺季交付唔缺货、海外擴張無後顧之憂;對寧德時代嚟講,鎖定產能即鎖定銷量,提升產能利用率、平抑投資成本,形成規模效應同成本優勢。
研發前置
如果話產能鎖定綁定嘅係當下,那麼研發前置綁定嘅就係未來。傳統電池供應係「車廠提需求、電池廠做產品」嘅後置適配模式,而寧德時代則將研發全面前置,實現整車與電池同步開發、聯合定義、聯合測試,從被動適配轉向前主動共創,以技術深度嵌入實現綁定。
2025 年 12 月 17 日,寧德時代同嵐圖汽車簽署 10 年深化合作協議。根據協議,寧德時代將積極配合嵐圖新車型開發,優先提供領先電池技術,全面推動麒麟、神行、驍遙等標竿性電池品牌喺嵐圖車型上嘅規模化應用。這意味著,嵐圖嘅產品規劃將同電池領域嘅前沿創新保持同步。雙方合作視野已從單一嘅動力單元拓展至換電模式、CIIC 智能底盤集成化、磐石底盤、V2G 等代表未來出行生態嘅全新領域。

當然,寧德時代嘅研發前置邏輯遠唔止於呢一間車企。2025 年 11 月 11 日,寧德時代同廣汽集團簽署 10 年全面戰略合作協議,雙方將喺智能底盤、換電生態等前沿領域展開聯合研發,並基於寧德時代喺動力電池、儲能系統及能源服務領域嘅深厚積累,共同打造更具市場競爭力嘅新能源車型。針對廣汽傳奇嘅車型規劃,雙方正積極推進磐石底盤技術嘅搭載應用。
2025 年以來,寧德時代已同多家車企達成合作——不僅係廣汽集團、江淮集團,更包括理想汽車、賽力斯等核心客戶。電池廠商同整車廠正共同越過傳統嘅買賣博弈,全面邁向深度綁定與價值共創嘅新階段。寧德時代嘅研發體系亦由此具備咗更強嘅「前瞻性」:當下一代電池技術仲喺實驗室中迭代時,寧德時代就已經同合作夥伴喺共同規劃未來嘅車型平台架構。
研發前置嘅深層意義喺於,它讓寧德時代從一個被動回應需求嘅供應商,轉變為主動定義未來技術路線嘅標準制定者。寧德時代於 2026 年 2 月 26 日發布嘅麒麟凝聚態電池,能量密度達 500Wh/kg,計劃於年底首批搭載蔚來 ET9 同極氪 001 FR。呢啲喺行業內尚屬前列嘅技術探索,而家成為寧德時代綁定高端客戶嘅最強黏合劑。
生態共建
事實上,寧德時代嘅業務領域遠唔止於電池,佢正將電動化目標延伸至低空、船舶、數據中心等更廣闊嘅領域,快速拓展換電網絡及服務,推進零碳生態建設,完善產業生態並延伸價值鏈條。圍繞整車企業,寧德時代正緊密構建換電、儲能、充電、綠電、回收全域生態,以生態壁壘實現不可替代嘅綁定。
喺換電領域,寧德時代以巧克力換電、驥驥重卡換電為核心,聯合長安、奇瑞、廣汽、賽力斯、上汽通用五菱、北汽等組建超換共享網絡,共建換電站、共享換電塊、統一接口標準。2026 年 4 月 25 日,奇瑞汽車、奇瑞綠能、寧德時代、時代電服簽署戰略合作協議,各方將聚焦「超充 + 換電」共享網絡佈局、綠色能源生態共建等領域,奇瑞汽車將全面導入寧德時代同時代電服嘅巧克力換電體系。而寧德時代同廣汽集團嘅合作更加係全方位嘅,不僅涵蓋智能底盤搭載應用、電池技術聯合研發、換電生態共建、電動化平台創新等關鍵領域,仲喺電池租賃、聯合建站等業務領域開展長期深度合作。

零碳園區係寧德時代正大力推動嘅項目,而家已喺山東東營、福建廈門、山西大同、江蘇鹽城及海南等地佈局零碳園區,通過 100% 綠電直連同源網荷儲一體化技術打造綠色智造基地。2025 年 7 月 26 日,寧德時代主導建設嘅全國首個 100% 綠電直連零碳工業園喺山東東營啟動建設,總投資超百億元,該項目採用「風光耦合 + 構網型技術」構建獨立能源系統,通過風電、光伏發電同儲能系統直連工廠。寧德時代嘅終極目標係打造綠電直供、零碳園區、源網荷儲、構網型儲能等全景式、一體化嘅零碳解決方案。
廢舊電池回收,係電池全生命週期管理實現閉環嘅最後一塊拼圖。寧德時代通過回收方式,對廢舊電池中嘅鎳、鈷、錳等金屬材料進行加工、提純、合成,並將收集後嘅銅、鋁等金屬材料通過第三方回收利用,使電池生產所需嘅關鍵金屬資源實現有效循環利用。寧德時代構建咗「生產—使用—梯次—回收」嘅完整閉環,為合作車企提供電池回收、梯次利用、再生材料閉環服務。通過規模化回收與再生,降低原材料成本,反哺整車電池價格競爭力,形成全鏈條價值共享。
此外,喺海外市場,寧德時代同奇瑞、宇通、吉利、東風等推進車電一體化聯合出海,海外電池基地同步跟進整車出海節奏,提供全球聯保、本地服務、供應鏈配套等服務。整車企業出海唔再面臨電池適配、認證、供應難題,寧德時代則跟隨整車出海擴大全球份額,形成全球化生態綁定。
生態共建嘅戰略意義遠超商業合作本身。當寧德時代唔只掌握電池製造,仲掌控電池嘅換電網絡、電池護照數據(寧德時代 2026 年 2 月同寶馬合作開展歐盟「電池護照」跨境數據試點)、電池回收全生命週期管理時,佢就從一個單純提供零部件嘅供應商,變成咗整個新能源出行生態嘅基礎設施平台。車企喺呢個生態中扮演嘅仍然係造車嘅角色,但補能方案、電池管理、數據服務乃至用戶出行體驗嘅關鍵維度,都將納入寧德時代嘅生態體系。呢種生態級綁定,已遠遠超出產品與價格層面,形成真正嘅「命運共同體」。

港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。
喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。
天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。
截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。
喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。
2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。
喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。
截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。
營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。
更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。
此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。
天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.

The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.

Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.

The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.

Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.

In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.
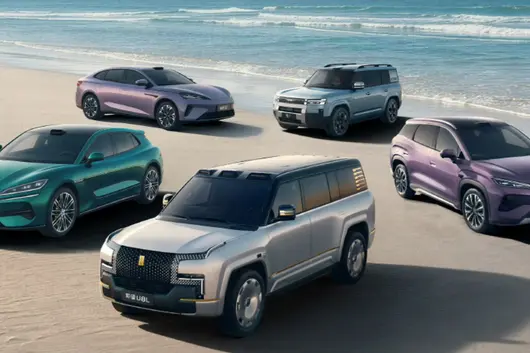
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.
The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.
Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.
The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.
Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.
In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.

Written by | AUTO Xinqiu
Author | AUTO Xinqiu Team
Just now, the new Onvo L60 was launched.
There are two things worth looking at together around this launch event. Counting back one day, NIO participated in the formulation of Singapore's battery swapping standards. On the day of the launch, an autonomous driving video of Onvo L60 crossing an extremely narrow karst cave was released to the outside world, causing quite a discussion on overseas social media.
But what truly made the industry notice this was the price. The Shenji NX9031 self-developed chip, full-domain 900V high-voltage platform, SkyOS Tianxu operating system — these three things appeared simultaneously on a car with a starting price of just over 200,000 (CNY). And these three technologies were positioned as flagship-level on previous NIO brand models.
This cannot be explained by a product iteration alone.
In the new energy vehicle industry these past two years, everyone is shouting "independent R&D". Battery, motor, and control system self-research, chip self-research, system self-research, intelligent driving self-research — this term has become somewhat inflated. But even with the same "self-research", some is a light asset approach of "defining specifications, outsourcing design", while others is a heavy asset route of "doing the entire process from architecture to tape-out themselves". The difference between the two is not visible in the short term, but vastly different in the long term.
The emergence of the new Onvo L60 basically brings this problem to the table: after the independent R&D system is truly proven, what exactly does it bring?
The True Divide of Independent R&D, Starting with a Chip
To figure out what makes NIO's independent R&D different from others, the best entry point is the intelligent driving chip.
Shenji NX9031, the team behind this project has over 600 people. Li Bin specifically emphasized one sentence at the media communication meeting: "It is a complete design capability from front-end to back-end." This is not said off the cuff.
There are two paths for making intelligent driving chips in the industry: one is to define parameters well, find a design company to do it for you, saving money and fast, but the disadvantage is subsequent iterations are constrained by others. The other is to build a team yourself, pressing the entire process from architecture design to back-end tape-out in your own hands, burning money, slow, but chips, algorithms, sensors, and operating systems can be coupled end-to-end.
This chip is not that chip. Just like building cars, outsourcing to an engineering design company and doing full-stack self-research yourself both result in something called "car", but the foundation is completely different.

Li Bin mentioned three specific comparison dimensions at the communication meeting.
The first is memory bandwidth, the Shenji NX9031's memory bandwidth is "basically 2 times that of industry peers" — this indicator determines how large a model can run on the car and how the inference speed is.
The second is multi-modal signal processing capability, also known as ISP. Li Bin mentioned that the good performance in crossing karst caves has something to do with this, because image processing capability is key in extremely dark environments.
The third is dual-chip millisecond-level hot switching. Li Bin said this is very important for L3, L4 level intelligent driving.
These three indicators alone are technical parameters, but together they point to the same thing: only when chips, algorithms, and operating systems are all your own does the initiative of product definition truly lie in your hands.Otherwise, you are just making choices on a supplier's quote sheet.
But the dividends of chip independent R&D extend beyond single-point indicators. Because the chip is your own, and sensor layout was planned uniformly in advance, like NIO decided on a hardware baseline of "7 8-megapixel cameras + 7 surround cameras" starting from the ET7 era, continuing all the way to Onvo L60, so the hardware architecture is naturally reusable.
Hardware reusability means data reusability; data reusability means toolchain reusability. Here, Li Bin revealed a detail: all intelligent driving versions of NIO's second-generation platform models can achieve "simultaneous release within a time window of no more than a few weeks plus or minus". Behind this rhythm, after the underlying architecture is unified, one set of code can cover multiple car models.
Assume there are 5 cars under the brand, if the intelligent driving software for each needs to be developed, tested, and iterated separately, maintenance costs are multiplicative. After the underlying architecture is unified, adding one more car to share R&D costs, the marginal cost is so low it can be ignored.
The new Onvo L60 can use flagship intelligent driving, not because NIO is generous, but because the cost structure changed itself after hardware unification.
The Moat of Independent R&D Has Already Been Dug Open
If the chip story explains what independent R&D can bring, then lightweighting and battery swapping explain that some things cannot be done at all without independent R&D.
Let's talk about lightweighting first.
Li Bin spent a large portion of the launch event speaking about lightweighting, which is uncommon in the industry. Lightweighting is a "invisible" indicator. Users do not pay for a low body-in-white lightweighting coefficient, and car companies usually do not take it as a selling point.
But Li Bin broke it down very finely.
The new Onvo L60 achieved a body-in-white lightweighting coefficient of 2.22. So, how was this done? There are four keys, mostly requiring independent R&D support.
The first is the battery. The battery is the heaviest component of the whole vehicle. If you focus on stacking range, stacking large-capacity LFP batteries, the weight goes up. Onvo's strategy is restrained: 85 kWh uses ternary lithium batteries, which is over 100 kg lighter than LFP of the same capacity. But ternary lithium is expensive. Li Bin's original words were: "This is a large sum of money."
The second is systemic reconstruction. Onvo L60's "smart fuse", which sounds like just changing a part, actually requires the entire vehicle's high-voltage and low-voltage architecture to be redesigned. Using traditional fuses, circuit design is standard parts; switching to smart fuses, everything from distribution logic to harness routing must be redone. Integrated design is the same, packing more functions into fewer modules, saving not just weight but also space and BOM costs. But each is an independent R&D project; without independent chassis and independent electronic/electrical architecture teams, you can't do it alone.
The third is full-domain 900V. Many people haven't noticed the contribution of high-voltage platforms to lightweighting — the higher the voltage, the smaller the current under the same power; the smaller the current, the thinner the harness; the thinner the harness, the lighter the whole vehicle. This loop sounds simple, but the threshold of 900V itself is extremely high. From power semiconductors to insulation design to thermal management, all are tough challenges.
Finally is engineering capability. A lightweighting coefficient of 2.22 tests the ability to "achieve the best structure with the least material while ensuring crash safety". Li Bin made an analogy: "Sometimes overusing materials yields no safety benefit, just like some houses look very thick walls, it does not mean they are structurally solid." This capability cannot rely on suppliers; it relies on the data, simulation, testing, and trial-and-error accumulated by the whole vehicle engineering team over the years.
After going through these four things, the lightweighting matter is clear: it is not a single-point technical indicator, but the comprehensive result of several independent R&D systems working collaboratively: chassis, core electric systems, electronic/electrical architecture, and engineering simulation.

Let's talk about battery swapping next.
On the same day the new Onvo L60 launched, NIO participated in the formulation of Singapore's battery swapping standards. Adding to this, over 60 battery swapping stations already operational in Europe, this model which was repeatedly questioned in the past is turning from a corporate choice into an industry option.
But the battery swapping matter is independent R&D from start to finish. Currently, among Onvo L60 users, the penetration rate of the battery leasing scheme is over 90%.
Obviously, once users accept "separation of vehicle and battery", the risks of battery life, anxiety about resale value, and concerns about charging convenience are all transferred to the operator, which is NIO itself.
And NIO dares to take this responsibility, there is only one reason: the battery swapping network is part of the entire independent R&D system. Battery charging/discharging strategies, life management algorithms, residual value assessment models are all run by their own team. If you outsource battery swapping to third-party operators, you simply dare not promise users "battery rental covers lifetime warranty" because you cannot control the real health status of the battery.
Chip independent R&D lets you modify, lightweighting lets you save, battery swapping lets you guarantee — these three things put together form a complete independent R&D puzzle. And the new Onvo L60 is the first time these three things are fulfilled simultaneously on a car in the 200,000 level.

The Most Difficult Path, Highest Barrier Instead
Speaking of here, there is an unavoidable question: Independent R&D is so money-burning, who is paying the bill?
In 2026, the supply chain pressure is quite real. Automotive-grade memory prices are rising sharply, and lithium prices are also rebounding. For one Onvo L60, just the cost end increased by over 10,000 yuan. If converted to the final selling price including taxes, the impact is about 15,000.
Here, Li Bin spoke a big truth: "Onvo L60 still has gross profit, but it's quite miserable."
But under this pressure, the Onvo L60 starting price was still placed just over 200,000. However, 90% of orders selected the high-spec version with Shenji chips and LiDAR. Average selling price for the whole brand in the first quarter was 240,000 — this is higher than many traditional luxury brands. From January to May, NIO overall growth was 68%, higher than internal targets.
Looking at these two sets of numbers together, the conclusion might be somewhat counter-intuitive — Independent R&D burns money, but Independent R&D is exactly the way to digest costs.
The logic here is not complex. The same technical system covers three brands: NIO, Onvo, Firefly; R&D expenses are spread across more cars; the same hardware architecture serves multiple models, and after procurement volume goes up, negotiation power also increases. After hardware unification, data reuse, and toolchain sharing are proven, for every additional car, marginal costs will drop significantly.
The new Onvo L60 presses flagship technology down to the 200,000 level, not because NIO is doing charity, but because this economic model is operating on its own.
But if you stretch the timeline, the real account of independent R&D is not calculated by quarter.
If you look at a quarter — others are competing in sales volume, he is repairing battery swapping stations. Others buy chips to compete in computing power, he builds a team from scratch for tape-out. Others stack big batteries to compete in range, he calculates lightweighting coefficients. Every move seen individually looks like engaging in an unprofessional business.
But looking at 3 to 5 years, you will find 3,900 battery swapping stations have been laid out, chips have run through end-to-end coupling, lightweighting coefficients reached 2.22 — these single points begin to link into a system.
Looking at ten years, you will find this company built a complete set of infrastructure on core electric systems, intelligent driving, energy replenishment, and electronic/electrical architecture that others cannot bypass. This is the core barrier brought by independent R&D, and also the key reason why consumers are increasingly paying for NIO.
Written at the End
Back to the new Onvo L60.
The significance of this car is not that it is 50,000-60,000 cheaper than Model Y, nor is it about using flagship chips and LiDAR, let alone how much it sold for.
Its significance lies in a 200,000 level car paired with a technical combination that only a full-stack independent R&D system can support. China's new energy vehicle independent R&D has entered the stage of "can it work well, is it worth the account" from the stage of "can it be made".
In the table of China's new energy vehicles, players willing to build infrastructure for ten years, trade time for space, trade deep plowing for barriers can be counted on one hand. The emergence of the new Onvo L60 is simply saying one thing: the investments that everyone thought were quite silly back then are now beginning to be redeemed line by line on reports, products, and industry standards.
The marathon is not yet finished. But those running ahead are always the ones who dug the deepest foundation before the starting line.
* All images in this article are from the internet
Focusing on intelligent cars, assisting key decisions.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
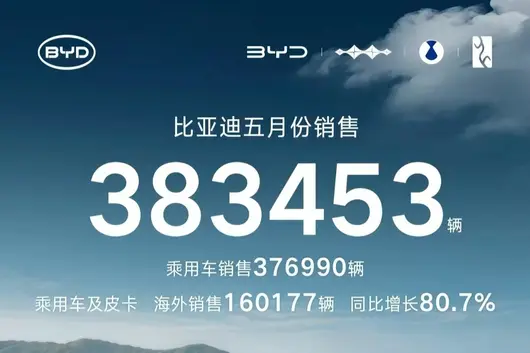
你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。
然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。
要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。
高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。
《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。
如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
當一家車企與一億個家庭嘅故事交匯,中國汽車工業將迎來歷史上首個「億級車企」。
上汽集團將於 5 月 28 日,以一場前所未有「全球接力交付」儀式,將第一億輛車嘅車匙交到用戶手中。呢次唔係一次簡單嘅交付,而係中國汽車工業七十余年從跟跑變領先嘅歷史註腳,更加係一家「用戶型高科技公司」對「識車更識你」呢個承諾嘅終極演繹。

但係一個問題更加值得追問:喺中國汽車工業嘅版圖上,合資品牌、自主車企群雄並起,點解係上汽集團率先叩開「億萬輛時代」嘅大門?答案就藏喺佢七十多年發展過程中,每一步都蘊含上汽獨有精神嘅「印記」入面。
一部中國汽車工業嘅濃縮史
1958 年 9 月 28 日,上海汽車裝配廠嘅工人喺弄堂小廠入面,用鐵錘一錘一錘敲出第一輛鳳凰牌轎車。當時,車身翼子板同車頂完全靠人手成型,工人嘅手臂腫到抬唔起。這就係上汽嘅起點——「草窩飛出金鳳凰」。

七十余年之後,上汽集團即將成為中國首個累計產銷量突破 1 億輛嘅汽車集團。呢個唔只係一個數字嘅跨越:一億輛背後,係中國汽車工業從無到有、由弱到強嘅完整縮影。上汽嘅每一步,都踏喺關鍵節點度。
由上個世紀五十年代鳳凰牌轎車嘅手工敲打,到八十年代桑塔納開啟合資合作先河,再而係 2014 年率先全面向新能源轉型。上汽嘅歷史幾近與中國汽車工業嘅每一個重要時刻同頻共振。

1985 年,當第一輛桑塔納裝配線下嘅時候,國產化率僅係 2.7%,能夠配套嘅只有輪胎、收音機、喇叭、天線同標牌 5 種零件。而到 1993 年,桑塔納國產化率已經突破 80%,德國媒體讚佢係「德國大眾海外最成功嘅合資企業」。
1998 年,上海通用項目僅用 23 個月建成投產,令美國通用汽車高管嘆為觀止:「我哋將美國通用嘅管理同技術帶咗去上海通用,我哋仲要將上海通用嘅建設速度帶返美國。」呢種「上海速度」,成為上汽基因入面「敢為人之先」嘅最佳註腳。
2006 年,上汽發佈首個自主品牌「榮威」,宣佈由「合資經營」轉型「合資同自主並重」嘅戰略轉折點。2012 年,中國首款量產純電動轎車榮威 E50 批量上市。此時距離國家明確提出「新能源汽車彎道超車」仲有幾年,上汽又一次走喺政策曲線之前。
2016 年,上汽同阿里跨界合作推出全球首款互聯網汽車榮威 RX5。創新落地需要嘅推動力好大,但係上汽敢於邁出呢一步,令汽車由機械工具進化為智能終端。
2022 年,上汽 MG MULAN 喺中國同近 20 個歐洲國家同步上市,成為中國汽車工業史上首個真正意義上嘅「全球車」。同年,上汽海外銷量突破百萬輛,成為首個海外年銷破百萬嘅中國車企。

上汽始終以技術突破回應「點樣更識用戶」嘅時代命題。而家,由率先量產半固態電池,將電池安全同能量密度提升咗去新高度,到線控轉向技術落地,由行業唯一一家收獲 L4 雙牌到 AI 大型模型上車。
上汽每個關鍵節點都創造咗「行業第一」或「中國第一」。上汽每一次「第一」,都係為咗令用戶享受更高品質嘅好車同更美好嘅用車生活。一億輛,正係呢啲「第一」累積出嘅必然結果。
由「識車」到「識你」嘅七十年傳承
「識車更識你」唔係一句口號,而係貫穿上汽七十年嘅造車史嘅行為準則。上汽嘅文化基因可以凝練做三個關鍵字:突破、合作、品質。佢哋共同指向一個理念——令技術由實驗室走向駕駛座,令每一輛上汽車都成為最識你嘅出行夥伴。

首先係突破文化:敢為人之先,將「識車」推向新高度。上汽每一次嘅跨越,都係喺「冇條件创造条件」。一位長期跟蹤中國汽車產業嘅分析師指出:「上汽最難得嘅係,佢總能喺行業變革嘅前夜率先佈局。」當國家提出發展新能源汽車係我哋由汽車大國邁向汽車強國嘅必由之路時,上汽此後十年喺新能源領域嘅持續投入,恰恰印證咗呢種戰略定力。
其次係合作文化:無邊界,匯聚全球智慧只為更識你。1980 年代,桑塔納國產化「共同體」集全市之力攻克零部件技術。德國專家教技術,中國工人學工藝,中外地員工互相尊重、共同進步,呢種開放合作嘅基因延續至今。

由同大眾、通用、奧迪嘅合資合作升級做「合資 2.0」,為中國用戶訂製開發 ID. ERA 9X、奧迪 E7X;到同華為乾崑全面協同,令高階智駕走進 15 萬級家庭;同 Momenta 深度共創,智駕方案賦能上汽大眾旗下多個品牌。上汽從未做過生態孤島,因為真正嘅「識你」,需要匯聚全球智慧。
更值得關注係品質文化:精益求精,令「識你」有底線。
1987 年,桑塔納國產化會議上定下鐵律:「絕對唔搞瓜菜代」。由嗰時起,「精益求精」就成為上汽質量工作嘅誓言。1998 年,延鋒公司為上海通用配套生產保險桿,首批產品已經達標,但因為客戶提出更高要求,當場鋸掉合格產品,並透過持續技術攻關,僅三個月就制定出更先進工藝。

呢種近乎苛刻嘅品質理念,最終化用家口口相傳「10 年唔褪色嘅漆面」、「零自燃嘅電池」、「30 萬公里無大修」。正如一位上汽車主所言:「我唔識技術參數,但我識呢車用住放心。」
只有上汽先做得到嘅「大團圓」
5 月 28 日,上汽會喺上海北外灘世界會客廳,以一場「全球接力交付」儀式迎接第一億位用戶。這將係中國汽車品牌從未嘗試過嘅表達方式。
據悉,儀式全程將會面向全球直播,連接國內多城及英國、印尼、新加坡等海外交付現場,跨越歐亞大陸、多個時區接續交付。旗下 15 個品牌將悉數登場——榮威、MG、智己、尚界等自主品牌,大眾、奧迪、別克、凱迪拉克等合資品牌;乘用車同商用車同台;由 A0 級代步車到 50 萬級豪華旗艦,由家庭出行到城市物流、基建運輸,覆蓋全場景。

「呢種儀式,需要企業具備全品牌矩陣、全品類產品、全球化佈局、全產業鏈體系——缺一不可。」一位行業觀察家指出:「上汽七十年深耕,先造就呢份獨一無二『全家福』能力。佢唔僅係交付,更加係上汽體系競爭力嘅集中亮相。」

更值得關注嘅係,呢場儀式將以「用戶為主角」,讓全球一億份信賴喺鏡頭前完成接力。呢種係全新嘅品牌敘事方式,佢傳遞嘅訊號係:一億輛唔只係企業輝煌成就,更加係一億次用戶用腳投票嘅結果。
一億輛係新起點,上汽嘅「上行」邏輯
一億輛背後,係近十年超 1500 億元研發投入、近 26000 項有效專利構築嘅技術護城河。但係同好多企業唔同嘅係,上汽嘅技術從來都唔係「櫥窗展品」。由智己 LS8 嘅線控轉向 + 後輪轉向、MG 嘅半固態電池,到榮威嘅 AI 原生架構、尚界嘅華為全棧智能......每一項硬核科技,喺上市數月內由研發中心走向駕駛座,由高端選配變成全系標配。
呢種「技術量產化」能力,先係上汽幾十年一直維持「上行」嘅核心同關鍵。佢背後係上汽獨有嘅「全域競爭力」:自主同合資雙輪驅動、乘用車同商用車並重、國內同海外協同、純電/增程/插混全技術路線覆蓋。

對於經歷風雨嘅上汽而言,無論係面對而家新能源轉型嚴峻挑戰,定係未來汽車行業發展新變局,從不低頭嘅上汽集團只會更加昂揚。面向未來,上汽集團已鎖定「產品魅力、科技實力、機制活力」新目標,加速向用戶型高科技公司轉型。
由識車到識你,由規模冠軍到行業引領。當第一億輛車駛出生產線,呢唔僅係上汽集團同中國汽車嘅榮耀時刻,更加係上汽集團走向全球化、開啟更大用戶量級嘅新篇章!

唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。
(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
(零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
(長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
(零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
(長安啟源全新 Q05)
(零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
(長安啟源全新 Q05)
(零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
(長安啟源全新 Q05)
(零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
(長安啟源全新 Q05)
(零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
(長安啟源全新 Q05)
(零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
(長安啟源全新 Q05)
(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。


