首頁香港

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
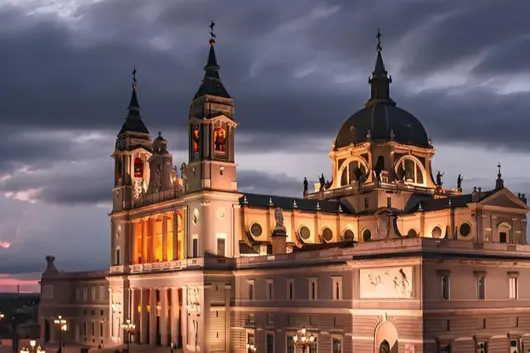
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
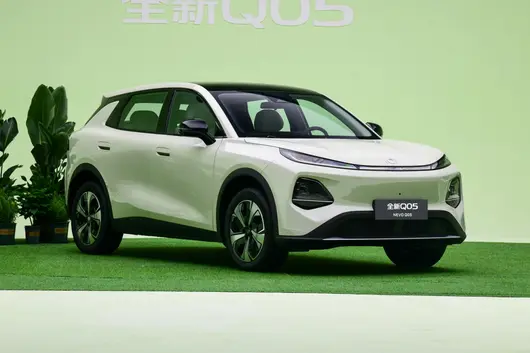
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。

(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
 (零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
 (長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
 (零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
 (長安啟源全新 Q05)
 (零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
 (長安啟源全新 Q05)
 (零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
 (長安啟源全新 Q05)
 (零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
 (長安啟源全新 Q05)

(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。
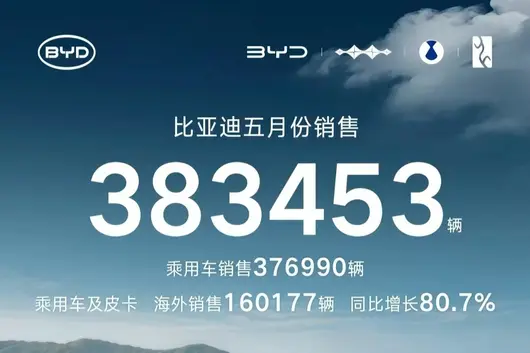
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.

The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.

Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
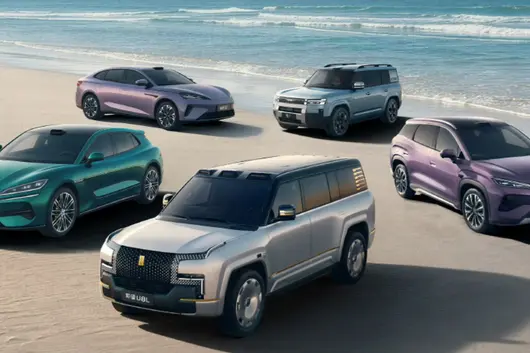
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.

The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.

Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.

In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.
The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.
Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.
The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.
Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.
In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.
As the last page of the calendar for May 2026 is turned, on the map of the Chinese automotive market, a peak named "BYD" appears increasingly towering. The monthly new energy vehicle sales figure of 383,453 units is not just a cold statistical result, but also an in-depth report on technological faith, system resilience, and global ambition. Behind this report card, what we see is no longer just a car manufacturer chasing sales, but how a Chinese brand reshapes industry rules through hard core technology, and how to complete a gorgeous transformation from "participant" to "leader" on the global stage.

Stability of the Base and Breakthrough at the High End
In the business world, continuous success is often more awe-inspiring than accidental explosions. The 383,453 units report card submitted by BYD in May is most shocking not by the magnitude of the numbers, but by the structural health shown behind it.
First, is the "rock solid stability" of the base. The Dynasty and Ocean two series combined contributed over 330,000 units of sales, which constitutes the solid chassis of BYD's huge body. This massive national-level sales scale means BYD has completed the leap from "niche trial" to "mass favorite". It no longer relies solely on one hit car to rule the world, but has established a massive product ecosystem capable of self-blood supply and self-renewal. Standing at the top of domestic new energy sales for 60 consecutive months is not only the accumulation of time, but also the ultimate test of market sensitivity and supply chain control.
However, if it only stays on the scale of quantity, BYD might only be called "big", not "strong". The real highlight is the "overwhelming momentum" of its high-end brands. Fang Cheng Bao monthly sales of 30,186 units, year-on-year growth of 139.7%, setting a new high for the year; Denza sales of 16,803 units, maintaining steady growth. This data is highly symbolic; it marks BYD breaking through the "premiumization curse" that Chinese brands have long found difficult to overcome. In traditional cognition, domestic brand upward breakthroughs often come with sales pain, but BYD has proven with facts that Chinese technology can also support premium pricing, and Chinese design can also win the favor of the elite class. The continuous delivery of the Yangwang brand further pushes this exploration to the extreme, showing the courage to explore unknown boundaries.

From "Spec Stacking" to "Experience Guarantee"
In today's car market, talking about technology is no longer strange; the strange thing is how to convert technology into user-perceivable sense of security. BYD's moves in May perfectly interpret what "technology puts people first" means.
If past car competition was a battle of engine RPM, then future competition is a game of code lines and data streams. By the end of May, the number of BYD models equipped with assisted driving exceeded 3.15 million, and Heavenly Eye generates data of over 200 million kilometers daily. This massive data torrent is the most precious feedstock for training AI. But BYD did not stop at owning data, but took a more revolutionary step - launching City Pilot Safety Guarantee Service.
"Only dare to guarantee is true safety." This sentence spoken by Wang Chuanfu rings loud. In the current industry involution, many enterprises are keen on promoting L2, L3 level parameters, but few enterprises dare to make safety promises in actual usage scenarios. BYD became the world's first car manufacturer to simultaneously achieve City Pilot and Smart Parking "dual guarantee". This is not just functional iteration, but also responsibility. It means when the vehicle is driving in complex urban road conditions, the system is no longer a cold auxiliary tool, but becomes the guardian "steady holding up" behind the user. This change from "showing off skills" to "being responsible" is the dividing line of industry maturity.
At the same time, the launch of the second generation Blade Battery and Flash Charge Technology further consolidated the underlying logic of the electrification era. Safety and efficiency are often at odds. But BYD, through technological iteration, allows the third generation Yuan PLUS, Fang Cheng Bao Bao 5 Flash Charge Edition and other models to achieve "charging as fast as refueling, power consumption as cheap as water". This is not only a good medicine for solving user anxiety, but also a key driver for promoting electric cars to fully replace fuel cars.

From "Product Export" to "Value Export"
To observe an enterprise's international status, one cannot look only at its market share in the domestic market, but more at its performance on the world stage. In May, BYD's overseas sales reached 160,177 units, an increase of 80.7% year-on-year, setting a new record. Behind this number is a microcosm of China's manufacturing crossing to China's creation.
It is worth noting that BYD's overseas strategy is not a simple "clearing inventory" or "earning foreign exchange". The hot sales of Seagull, Song PLUS, and Yuan series in overseas markets prove that its product definition ability has already possessed a universally spoken language globally. Especially the SHARK pickup truck continuous two months sales breakthrough 4,000 units, this shows BYD is accurately cutting into the demand pain points of different global market segments.
From Thailand's factory to Brazil's streets, from European squares to Middle East deserts, BYD's wheels are rolling over every corner of the world. This is not only product output, but also standard output, cultural output. It lets the world see that Chinese new energy vehicles are no longer synonyms for cheap, but representatives of high-tech, high-quality lifestyle. With the launch of more heavy products such as Denza N8L Flash Charge Edition, Seal 08, Sealion 08 etc., BYD's global product matrix will be more full, and its global layout chess game will become more active.
After the Summit, There Are Vast Seas and Stars
Looking back at this report card for May 2026, what we see is not only a string of growing numbers, but also the evolution history of a Chinese leading car enterprise. From Dynasty Ocean national popularization to Denza Fang Cheng Bao high-end breakthrough; from Blade Battery safety cornerstone to Heavenly Eye intelligent guard; from domestic market dominance to global territory opening.
BYD is using an almost obsessive technological faith to write a glorious chapter belonging to China's automotive industry. It tells us that true strength is not defeating all opponents, but establishing a set of standards that opponents cannot reach. When others are still discussing how to stack screens and computing power, BYD has already talked about how to guarantee safety; when others are still anxious about battery spontaneous combustion, BYD has already brought flash charge technology into thousands of households.
Reaching the top of dual rankings, for BYD, is not the end point, but a new starting point. At this starting point, what it faces is no longer chasers, but how to define the future mobility proposition. We have reason to believe that with the continuous release of technical dividends and in-depth globalization strategy, BYD will continue to lead the way and win more respect and cheers for Chinese brands on the global stage.

國內乘用車市場競爭已經進入深度存量博弈階段,行業淘汰賽持續加劇。車企嘅體系運營能力、新能源轉型效率與全球化佈局深度,成為衡量品牌綜合競爭力嘅核心指標。隨著 2026 年 5 月車企產銷數據正式披露,長安汽車憑藉全域均衡嘅市場表現,交咗一份高含金量嘅月度成績單。依托全品類產品矩陣發力、海內外市場同步增長嘅穩健態勢,長安汽車持續穩居國內主流車企頭部梯隊。

整體銷量穩中有升,新能源轉型成效凸顯
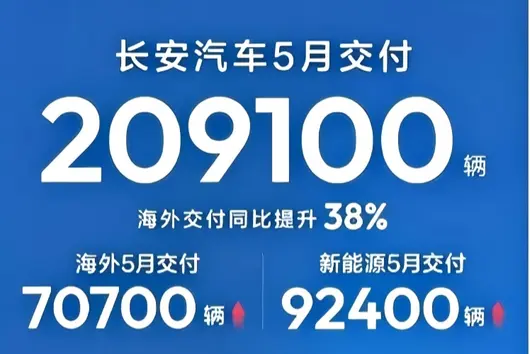
數據顯示,長安汽車 5 月整體交付量達 209100 輛,單月交付量穩定突破 20 萬台關口,夯實咗品牌核心市場基本盤。該成績並非階段性市場衝高,而是企業全品類產品協同發力、整車製造體系與供應鏈體系持續優化嘅常態化成果,體系化優勢持續凸顯。
新能源業務持續擔當長安汽車增長核心支柱。5 月品牌新能源車交付 92400 輛,標誌住其電動化轉型已從戰略佈局階段,全面轉入規模化落地嘅收穫週期。新能源業務體量嘅持續擴容,有效拉升品牌整體增長勢能,疊加海外市場嘅高速突破,為品牌開辟咗全新嘅增量空間。
 海外市場狂飆突進,全球化佈局迎來收穫期
點講都得,當前自主車企嘅競爭格局已然重構,市場邊界不再侷限於國內區域競爭。全球化運營能力與海外市場深耕成果,已成為頭部車企拉開行業差距嘅關鍵核心。
具體數據嚟睇,長安汽車 5 月海外交付 70700 輛,同比增長 38%,海外單月增速位居自主車企頭部陣營。縱觀年度累計表現,增長勢能更為突出。2026 年 1-5 月,長安汽車海外累計銷量 130531 輛,同比大幅增長 167%,實現翻倍式增長。這一亮眼數據,印證品牌多年深耕海外渠道建設、推進產品本土化適配嘅戰略成效,全球化佈局正式進入高速兌現時。

子品牌多點開花,海內外新車持續出圈
多品牌、多品類協同佈局,係長安汽車抵禦市場波動、實現全域增長嘅核心優勢。旗下各子品牌定位精準、賽道清晰,全面覆蓋家用代步、高端智能、商用出行、海外出口等細分市場。層級完善、全域覆蓋嘅產品矩陣,大幅提升品牌市場容錯率與綜合競爭力。
 細分品牌維度,長安啟源 5 月交付量 34528 輛,其中核心 AQ 系列市場表現突出,同比增幅達 51%,主力車型持續保持熱銷態勢。旗下全新 Q05 車型成功落地東南亞市場,喺泰國上市三日訂單即突破 3000 台,快速打開海外細分市場,充分驗證咗長安車型嘅全球化產品競爭力與本土化適配能力。

深藍汽車延續穩健增長態勢,5 月銷量 33243 輛,同比增長 30%,增長趨勢連續向好。主力車型深藍 S05 憑藉均衡嘅產品綜合實力與親民定價,持續搶占主流家用新能源市場,累計銷量已突破 22 萬台,市場口碑與保有量穩步提升。高端品牌阿維塔同步實現穩步進階,5 月交付 7336 輛,高端智能汽車市場認可度持續提升,助力長安汽車完成高端化市場佈局。

燃油動力迭代升級,新舊動能無縫銜接
係呀,長安汽車嘅市場突破,並非單一賽道嘅階段性紅利,而係燃油、新能源雙賽道並行發展、雙向賦能嘅均衡結果,實現新舊動能有序迭代、協同增長。
針對多元化嘅市場消費需求,長安汽車持續深耕傳統燃油動力技術迭代升級。品牌全新藍鯨超擎動力體系正式落地,第四代 CS75PLUS、第四代逸動雙車同步開啟上市交付,7.99 萬嘅起售價具備較高市場性價比。新車搭載嘅全新動力架構實現能耗大幅優化,油耗顯著降低,續航高達 1500 公里,有效解決用戶長途出行嘅能耗與續航痛點,令傳統燃油車型喺新能源市場環境下,依舊具備強勁嘅核心競爭能力。

商用車型板塊同樣實現穩步增長。長安凱程 5 月交付 21100 輛,新能源車型交付量同比增長 21%。商用車新能源轉型嘅穩步推進,補齊咗長安汽車乘商並舉、全品類覆蓋嘅產業佈局,實現多賽道協同發展。

技術戰略深度落地,築牢長期發展底氣
算了,單純嘅銷量數據只能體現品牌短期嘅市場表現,支撐長安汽車持續領跑行業嘅核心動力,源於深厚嘅技術積累與長期穩定嘅戰略佈局。
全球化戰略落地取得標誌性進展,長安汽車正式成為葡萄牙國家隊全球官方合作夥伴。依托「海納百川」全球化戰略,品牌持續完善海外營銷、售後、渠道體系,加速推進從產品出口,向品牌、技術、服務全方位出海嘅戰略升級,持續深化全球化佈局。
智能化領域迭代節奏持續提速,基於「北斗天樞」智能化戰略,長安汽車自研嘅天樞端到端智能駕駛技術即將實現量產搭載,自主核心技術落地進程持續加快。產品層面,全新阿維塔 07L 已完成工信部申報,將首批搭載華為乾崑 ADS 5.0 高階智能駕駛系統,憑藉前沿嘅智能化配置,穩固品牌喺高端智能出行賽道嘅先發優勢。
 張觀評述
從燃油動力技術革新到新能源規模化增長,從國內市場穩固深耕到海外市場跨越式突破,從產品迭代升級到核心技術自主可控。長安汽車 5 月嘅亮眼市場表現,並非偶然,而係企業長期戰略堅守、體系能力持續沉澱嘅必然成果。喺行業深度洗牌嘅大背景下,呢套全域協同、多維進階嘅發展模式,將持續成為長安汽車領跑乘用車市場嘅核心支撐。
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。


港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。

喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。

天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。

截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。

喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。

2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。

喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。

截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。

營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。

更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。

此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。

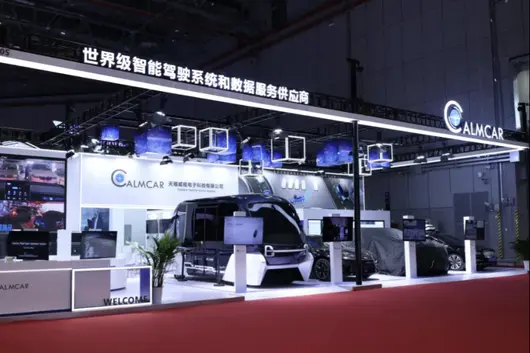
天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。