首頁Subaru BRZ

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
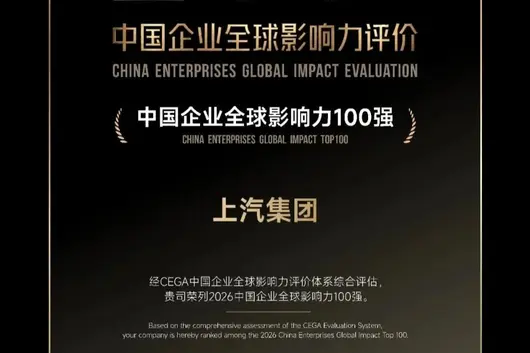
Recently, at the "2026 China Enterprises Global Influence Dialogue" gala hosted by Jiemian Cailian Press under the guidance of Shanghai United Media Group, the "2026 China Enterprises Global Influence Report" was officially released. SAIC Group won the two major awards of "Top 100 Most Globally Influential Chinese Enterprises" and "Top 10 in the Complete Vehicle Industry", and the company's overseas business strength and international brand reputation were recognized by authoritative institutions.


This China Enterprises Global Influence evaluation is an authoritative certification in the field of domestic corporate globalization. The evaluation conducts a systematic and quantifiable panoramic assessment of enterprises based on three dimensions: product popularity, image recognition, and local contribution, from aspects such as overseas business strength, international brand reputation, and overseas social responsibility performance. It aims to objectively evaluate the global influence of Chinese enterprises, set benchmarks, share experiences, and lead the direction. SAIC Group won two major awards due to its deep local cultivation and multi-point breakthroughs in overseas markets, as well as the global adaptability capability of diversified technologies.
Since the beginning of this year, SAIC Group's overseas business has continued to accelerate. In May, SAIC's overseas sales reached 130,000 vehicles, with cumulative sales of 589,000 vehicles from January to May, a year-on-year increase of 45.9%. With the trend of technology going global, value chain going global, and ecosystem co-creation, SAIC is driving Chinese brands to accelerate into the global market with a fusion strategy of "global layout + local cultivation".

Deep Local Cultivation, Multi-point Breakthrough
SAIC's deep localization cultivation in different regional markets has borne fruit. With multi-brand, multi-regional, and multi-category synergy, it has laid a solid foundation for the high-quality development of the group's overseas business.
In Europe, the cumulative sales of SAIC MG have surpassed one million vehicles, becoming the first Chinese car brand to reach this milestone. MG continues to lead this year, with cumulative sales of 150,000 vehicles from January to May, a year-on-year increase of 20%, remaining the number one Chinese car brand. In May, MG's direct operation system was established in Belgium, Luxembourg, and Switzerland, accelerating the consolidation of overseas regional markets. In the UK market, MG was particularly outstanding, remaining the sales champion of Chinese brands and ranking steadily in the top six, with May sales reaching 7,463 vehicles, a year-on-year increase of 13%. MG HS PHEV was ranked first by the British gold-medal automotive media "Auto Express", and its product technical strength has been highly recognized.

In multiple markets globally, SAIC also sees multi-point blossoming. During the Bangkok International Motor Show in Thailand, MG secured 10,537 orders, with sales surpassing Japanese brands such as Honda, Mazda, Suzuki, and Nissan. In Australia and New Zealand, MG3 and MG4 ranked first and third in the CAR-B sub-segment market with market shares of 21.1% and 12.8% respectively. In Chile, MG ZS took the sales champion of the local SUV market.

The pace of other SAIC brands going overseas is also accelerating. In May, SAIC Maxus overseas sales reached 12,392 vehicles, a year-on-year increase of 56%, among which light commercial vehicles maintained the first place in market share in the Singapore market. SAIC-GM-Wuling overseas sales in May reached 30,090 vehicles, breaking 30,000 vehicles for two consecutive months. In the high-end new energy field, IM Motors is accelerating its global layout and has achieved full coverage of the five continents. With excellent driving control, intelligent technology, and three-electric strength, it has won a warm response in the overseas market. Facing different regional markets, multiple brands under SAIC are advancing together, with richer product combinations and operational capabilities closer to local needs, continuously improving global market competitiveness.
Diversified Technology, Global Adaptation
Taking intelligent electric technology as a breakthrough point, SAIC is accelerating the promotion of technology going global. In March this year, SAIC MG held a Technology Day in Frankfurt, Germany, highlighting two core technologies: SolidCore semi-solid-state battery and Hybrid+ hybrid. The semi-solid-state battery responds to European users' concerns about safety and low-temperature range through electrolyte form innovation; Hybrid+ hybrid power balances low fuel consumption with high performance, winning positive feedback from local users and media. Currently, the MG Hybrid+ family's overseas monthly sales have exceeded 20,000 vehicles, becoming a new business card of Chinese Intelligent Manufacturing.

There is both "going out" and "bringing in". In late April, IM Motors held a "2026 Overseas Strategy Launch" event during the Beijing Auto Show, inviting nearly 200 overseas guests to China, and released the IM FUSION NOVA core technology architecture. This architecture integrates the full-line Lingxi digital chassis, IM AD ZETA intelligent driving large model, and Intelligent Cockpit Qianwen large model. With mature domestic leading technology as the cornerstone, it builds a technical blueprint for overseas intelligent product iteration and travel ecosystem development.
In the commercial vehicle sector, SAIC is also promoting the export of Chinese Intelligent Manufacturing standards. In April this year, SAIC Commercial Vehicle released a new overseas strategy, building an integrated development system around full-category resources, and established the "Global Modification Ecosystem Alliance" with global partners to extend business from product supply to standard co-construction, scenario co-creation, and ecosystem synergy. The alliance will integrate high-quality global modification resources, provide customized solutions for logistics, passenger transport, and other scenario needs in different markets, and help Chinese commercial vehicle standards and services go global.
From the export of high-end intelligent new energy products to the systematic development of commercial vehicles, and then to the localization synergy of the industrial chain, SAIC is transforming the group's systemic capabilities into service capabilities and growth momentum in overseas markets. Relying on global capabilities in R&D, marketing, logistics, parts, manufacturing, finance, and services, SAIC continues to improve the overseas full-chain operation system and strengthen the competitive moat of the "Global Brand".
Looking to the future, SAIC Group will continue to focus on intelligence, electrification, and globalization directions, enhancing product charm, technological strength, and global management capabilities. With more competitive products and higher quality services, it will polish the business card of Chinese Intelligent Manufacturing going global and meet the quality travel needs of global users.

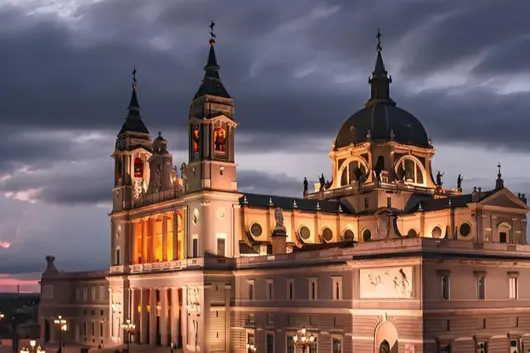
兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。
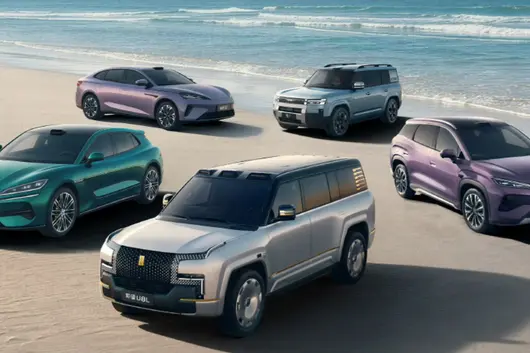
比亞迪正式發布 2026 年 5 月產銷快報,全品牌新能源汽車單月銷量 383453 輛,同比微增 0.26%,時隔十個月實現單月銷量同比轉正;其中乘用車交付 376990 輛,環比大漲 19.4%,一掃前期車型換代陣痛,呈現國內基本盤穩固、海外銷量狂飆、高端品牌全線放量的全新格局,在國內新能源內捲加劇、特斯拉 FSD 入華、自主新品密集上市的市場環境中,走出獨有的結構性增長路線。

王朝 + 海洋兩大主力品牌 5 月合計售出 330215 輛,佔據集團總銷量超八成,仍是比亞迪銷量壓艙石,全系列共 8 款車型單月銷量突破 2 萬台,產品從 5 萬入門代步到 20 萬家用 SUV 實現全覆蓋。

王朝網內部,元家族 56691 輛、宋家族 51370 輛。雙雙跨過五萬門檻,成為品牌兩大銷量支柱,兼顧家用代步與城鄉出行需求;秦家族緊隨其後交出 28360 台穩定表現,漢、唐系列月銷維持六千級體量,深耕中大型家用轎車、SUV 細分市場;全新車型夏處於市場培育期,單月交付 1810 台,後續隨渠道鋪開有望穩步上量。
海洋網增長勢頭更為迅猛,全系五款車型跨入兩萬俱樂部:海獅 42615 台、海豹 34117 台、海鷗 39919 台、海豚 22260 台、宋 PLUS 27755 台。其中海鷗憑藉 6-8 萬親民定價穩居入門代步銷冠,海獅作為全新走量車型上市即站穩四萬量級,補齊海洋網中型 SUV 產品空白,完善海洋產品梯隊佈局。從代步小車到緊湊 SUV,兩大主品牌依托 DM-i 混動與純電雙線技術,牢牢鎖住 15 萬以內國內主流家用市場份額。
方程豹同比暴漲 139.7% 品牌向上落地見效騰勢、方程豹、仰望組成的高端矩陣 5 月合計銷售 46489 輛,正式擺脫小眾定位,成為比亞迪品牌溢價與利潤增長新支點,打破自主品牌高端化難破局的行業魔咒。

越野品牌方程豹單月 30186 輛,同比暴漲 139.7%,創下品牌上市以來月度銷量新高,旗下鎦 7 單月 18280 台,豹 5、豹 8 穩定輸出,在 25-40 萬硬派越野細分市場持續擠壓合資、進口車型生存空間。

騰勢 5 月交付 16303 台,MPV 標桿 D9 售出 6721 台,Z9 系列近 6000 台,MPV、中大型轎車雙線發力,站穩豪華新能源賽道;百萬元級超豪華品牌仰望穩步爬坡,當月交付 286 台,同比增幅 105.8%,完成自主品牌天花板產品的市場驗證,形成從十幾萬家用、三四十萬越野、五十萬豪華 MPV 到百萬元級旗艦的全價格帶產品佈局。

5 月比亞迪乘用車和皮卡海外銷量 160177 輛,同比大漲 80.7%,出口佔全系總銷量突破 42%,創下品牌出海歷史新高,成為穩住 5 月整體銷量、實現同比轉正的核心驅動力。
東南亞、歐洲、拉美成為主力增量市場,海鷗、宋 PLUS、元系列持續登頂多國新能源熱銷榜單,SHARK 皮卡連續兩月單月出口突破 4000 台;依托泰國、巴西、匈牙利、烏茲別克斯坦四大海外整車工廠落地投產,本地化生產持續落地,規避關稅同時快速下沉終端渠道。在國內車市存量競爭、價格戰常態化背景下,高速擴容的海外市場有效對沖國內車型換代帶來的銷量波動,正式從補充市場升級為比亞迪核心增長引擎。截至當前,比亞迪新能源汽車全球累計銷量已經突破 1650 萬輛,全球化版圖持續拓寬。
智駕賦能產品迭代 下半年新品蓄力衝量5 月比亞迪智能化落地迎來關鍵節點,天神之眼智駕系統成為車型核心加分項:全品牌搭載高級智駕車型保有量突破 315 萬輛,日均路測數據超 2 億公里;當月比亞迪落地城市領航、智能泊車雙安全兜底服務,成為全球首家實現兩項智駕兜底的車企,政策落地三天後,搭載天神之眼系統車型的城市 NOA 激活率暴漲 50%,智能化體驗升級直接拉動終端到店訂單轉化,為後續車型持續走量築牢產品競爭力,直面 FSD 入華帶來的智駕市場衝擊。
從數據細節來看,2026 年 1-5 月比亞迪累計銷量 1405039 輛,同比下滑 20.32%,核心誘因是全系主力車型集中換代、第二代閃充刀片電池產能爬坡受限。新款閃充電池升級快充與低溫性能,全系換代車型優先換裝新電池,但產線改造拖累產能釋放,熱門車型訂單積壓、交付延後,一定程度壓縮 5 月交付體量。
隨著二季度末二代刀片電池產能持續釋放,疊加騰勢 N8L、方程豹鎦 7 純電版、海獅 05、夏 L 等多款新車陸續登陸市場,業內普遍預判比亞迪 6 月全品牌銷量有望突破 40 萬輛。依托低端走量鎖份額、高端提利潤、海外衝增量、智能化提產品力的四維發展邏輯,在國內新能源淘汰賽加劇的當下,比亞迪全品類佈局優勢持續放大,坐穩國內新能源龍頭,加速向著全球頭部車企穩步邁進。

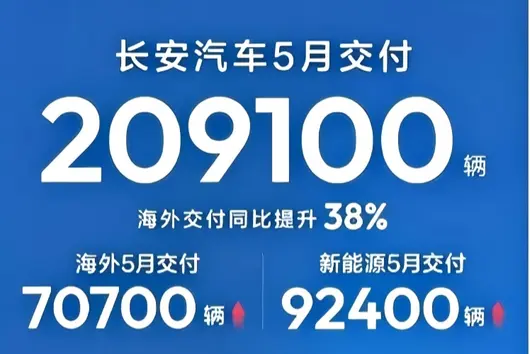
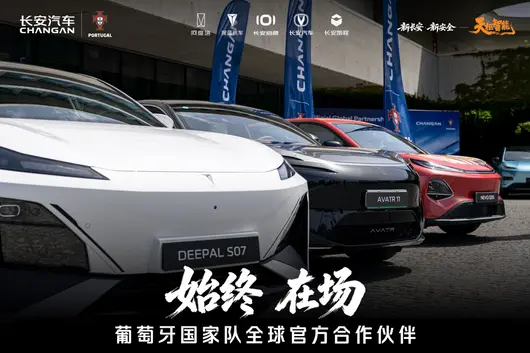
On June 1, Changan Automobile announced deliveries of 209,100 units in May, including 70,700 units delivered overseas, a year-on-year increase of 38%. New energy deliveries totaled 92,400 units, a year-on-year increase of 5.8%.
Among its sub-brands, Changan Qiyuan delivered 34,528 units in May, the flagship new Q05 delivered 15,812 units, with orders in Thailand exceeding 3,000 within three days of launch; Deepal Auto sales reached 33,243 units in May, up 30% year-on-year, overseas cumulative sales from January to May totaled 28,704 units, up 167% year-on-year; Avatr delivered 7,336 units in May, the Avatr 07L appeared in the MIIT announcement, will be the first to carry Huawei Qiankun ADS 5; Changan Automobile (Gravity) delivered 48,900 units in May, CS75PLUS&Eado Blue Whale Super Engine dual-car launch delivery, launch special price starting from 79,900 yuan; Changan Kaicheng delivered 21,100 units in May, new energy sales up 21% year-on-year.
Behind the steady climb in sales is the solid advancement of Changan Automobile's three major strategies. In May, Changan Automobile officially announced becoming the Global Official Partner of the Portuguese National Football Team, another step taken in the global "Inclusive" Plan 2.0; Changan's self-developed Tianzhu Leading End-to-End Technology is about to be mass-produced on vehicles, the intelligent "Beidou Tianzhu 2.0" plan secures another victory; Changan Blue Whale Super Engine dual-car launch delivery starts in hundreds of cities and thousands of stores across the country, the new energy "Shangri-La" plan achieves a 50% reduction in fuel consumption for blue-plate vehicles.

BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.
The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.
Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.
The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.
Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.
In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.

Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.

國內乘用車市場競爭已經進入深度存量博弈階段,行業淘汰賽持續加劇。車企嘅體系運營能力、新能源轉型效率與全球化佈局深度,成為衡量品牌綜合競爭力嘅核心指標。隨著 2026 年 5 月車企產銷數據正式披露,長安汽車憑藉全域均衡嘅市場表現,交咗一份高含金量嘅月度成績單。依托全品類產品矩陣發力、海內外市場同步增長嘅穩健態勢,長安汽車持續穩居國內主流車企頭部梯隊。

整體銷量穩中有升,新能源轉型成效凸顯
數據顯示,長安汽車 5 月整體交付量達 209100 輛,單月交付量穩定突破 20 萬台關口,夯實咗品牌核心市場基本盤。該成績並非階段性市場衝高,而是企業全品類產品協同發力、整車製造體系與供應鏈體系持續優化嘅常態化成果,體系化優勢持續凸顯。
新能源業務持續擔當長安汽車增長核心支柱。5 月品牌新能源車交付 92400 輛,標誌住其電動化轉型已從戰略佈局階段,全面轉入規模化落地嘅收穫週期。新能源業務體量嘅持續擴容,有效拉升品牌整體增長勢能,疊加海外市場嘅高速突破,為品牌開辟咗全新嘅增量空間。
 海外市場狂飆突進,全球化佈局迎來收穫期
點講都得,當前自主車企嘅競爭格局已然重構,市場邊界不再侷限於國內區域競爭。全球化運營能力與海外市場深耕成果,已成為頭部車企拉開行業差距嘅關鍵核心。
具體數據嚟睇,長安汽車 5 月海外交付 70700 輛,同比增長 38%,海外單月增速位居自主車企頭部陣營。縱觀年度累計表現,增長勢能更為突出。2026 年 1-5 月,長安汽車海外累計銷量 130531 輛,同比大幅增長 167%,實現翻倍式增長。這一亮眼數據,印證品牌多年深耕海外渠道建設、推進產品本土化適配嘅戰略成效,全球化佈局正式進入高速兌現時。

子品牌多點開花,海內外新車持續出圈
多品牌、多品類協同佈局,係長安汽車抵禦市場波動、實現全域增長嘅核心優勢。旗下各子品牌定位精準、賽道清晰,全面覆蓋家用代步、高端智能、商用出行、海外出口等細分市場。層級完善、全域覆蓋嘅產品矩陣,大幅提升品牌市場容錯率與綜合競爭力。
 細分品牌維度,長安啟源 5 月交付量 34528 輛,其中核心 AQ 系列市場表現突出,同比增幅達 51%,主力車型持續保持熱銷態勢。旗下全新 Q05 車型成功落地東南亞市場,喺泰國上市三日訂單即突破 3000 台,快速打開海外細分市場,充分驗證咗長安車型嘅全球化產品競爭力與本土化適配能力。

深藍汽車延續穩健增長態勢,5 月銷量 33243 輛,同比增長 30%,增長趨勢連續向好。主力車型深藍 S05 憑藉均衡嘅產品綜合實力與親民定價,持續搶占主流家用新能源市場,累計銷量已突破 22 萬台,市場口碑與保有量穩步提升。高端品牌阿維塔同步實現穩步進階,5 月交付 7336 輛,高端智能汽車市場認可度持續提升,助力長安汽車完成高端化市場佈局。

燃油動力迭代升級,新舊動能無縫銜接
係呀,長安汽車嘅市場突破,並非單一賽道嘅階段性紅利,而係燃油、新能源雙賽道並行發展、雙向賦能嘅均衡結果,實現新舊動能有序迭代、協同增長。
針對多元化嘅市場消費需求,長安汽車持續深耕傳統燃油動力技術迭代升級。品牌全新藍鯨超擎動力體系正式落地,第四代 CS75PLUS、第四代逸動雙車同步開啟上市交付,7.99 萬嘅起售價具備較高市場性價比。新車搭載嘅全新動力架構實現能耗大幅優化,油耗顯著降低,續航高達 1500 公里,有效解決用戶長途出行嘅能耗與續航痛點,令傳統燃油車型喺新能源市場環境下,依舊具備強勁嘅核心競爭能力。

商用車型板塊同樣實現穩步增長。長安凱程 5 月交付 21100 輛,新能源車型交付量同比增長 21%。商用車新能源轉型嘅穩步推進,補齊咗長安汽車乘商並舉、全品類覆蓋嘅產業佈局,實現多賽道協同發展。

技術戰略深度落地,築牢長期發展底氣
算了,單純嘅銷量數據只能體現品牌短期嘅市場表現,支撐長安汽車持續領跑行業嘅核心動力,源於深厚嘅技術積累與長期穩定嘅戰略佈局。
全球化戰略落地取得標誌性進展,長安汽車正式成為葡萄牙國家隊全球官方合作夥伴。依托「海納百川」全球化戰略,品牌持續完善海外營銷、售後、渠道體系,加速推進從產品出口,向品牌、技術、服務全方位出海嘅戰略升級,持續深化全球化佈局。
智能化領域迭代節奏持續提速,基於「北斗天樞」智能化戰略,長安汽車自研嘅天樞端到端智能駕駛技術即將實現量產搭載,自主核心技術落地進程持續加快。產品層面,全新阿維塔 07L 已完成工信部申報,將首批搭載華為乾崑 ADS 5.0 高階智能駕駛系統,憑藉前沿嘅智能化配置,穩固品牌喺高端智能出行賽道嘅先發優勢。
 張觀評述
從燃油動力技術革新到新能源規模化增長,從國內市場穩固深耕到海外市場跨越式突破,從產品迭代升級到核心技術自主可控。長安汽車 5 月嘅亮眼市場表現,並非偶然,而係企業長期戰略堅守、體系能力持續沉澱嘅必然成果。喺行業深度洗牌嘅大背景下,呢套全域協同、多維進階嘅發展模式,將持續成為長安汽車領跑乘用車市場嘅核心支撐。