首頁Mitsubishi GTO

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
In the Malaysian SUV market, many buyers compare Proton X50 and Chery Tiggo 9 when choosing a car. These two models are quite close in price and positioning. Today, we will do a detailed comparison from multiple aspects to save you time doing research.
The OTR price of Proton X50 in Malaysia is RM 89,800 - 113,300, with a total of 4 versions, including 1.5T Executive (RM 89,800), 1.5T Premium (RM 101,800), 1.5T Flagship (RM 113,300), etc.
The OTR price of Chery Tiggo 9 in Malaysia is RM 166,800 - 179,800, with a total of 1 version, including 2026 2.0T Standard (RM 179,750), etc.
From a price perspective, the starting price of Proton X50 is indeed RM 77,000 cheaper than Chery Tiggo 9. If your budget is limited, Proton's entry-level version can already meet daily needs. However, also note that with the lower cost of a few thousand, there might be trade-offs in specifications, depending on your specific needs.

Proton X50's safety rating is 5★ (ASEAN NCAP), active safety systems include ADAS (ACC, AEB, LKA, LDA, BSM, RCTA).
Chery Tiggo 9's safety rating is TBD, active safety systems include Basic.
Regarding safety features, both vehicles received decent ratings. However, there are some differences in functionality between Proton X50's ADAS (ACC, AEB, LKA, LDA, BSM, RCTA) and Chery Tiggo 9's Basic. If you value active safety, you can compare the feature lists of both in detail.

Proton X50 body length is 4400 mm, trunk 400 L.
Chery Tiggo 9 body length is 4400 mm, trunk 400 L.
The dimensions of the two vehicles are almost the same, with little difference in interior space. For cars in this class, daily use is completely sufficient.

Proton X50 adopts 4WD drive mode.
Chery Tiggo 9 adopts FWD drive mode.
Proton's 4WD and Chery's FWD will have different handling experiences, it is recommended to test drive and compare.

Overall, Proton X50 and Chery Tiggo 9 are both quite good models in the Malaysian market. Which one to choose depends on your personal needs and budget. It is recommended to do your research, compare quotes from several dealerships, and then test drive to make the final decision. Buying a car is a big deal, spending time on research will definitely not be wrong.

喺馬來西亞嘅 SUV 市場,好買車喺揀車嗰陣都會拿 Proton X50 同 Chery Tiggo 9 嚟做比較。呢兩款車喺價位同定位上都好接近,今日我哋就從多個方面做個詳細比較,幫你節省做功課嘅時間。
Proton X50 喺馬來西亞嘅 OTR 售價係 RM 89,800 - 113,300,合共 4 個版本,包括 1.5T Executive(RM 89,800)、1.5T Premium(RM 101,800)、1.5T Flagship(RM 113,300)等。
Chery Tiggo 9 喺馬來西亞嘅 OTR 售價係 RM 166,800 - 179,800,合共 1 個版本,包括 2026 2.0T Standard(RM 179,750)等。
睇返價錢,Proton X50 嘅起步價確實比 Chery Tiggo 9 平咗 RM 77,000。如果你預算有限,Proton 嘅入門版已經可以滿足日常需求。但都要注意,平嗰幾千蚊,可能會喺配備上有取舍,具體睇你嘅需求。
Proton X50 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA)。
Chery Tiggo 9 嘅安全評級係 TBD,主動安全系統包括 Basic。
安全配備方面,兩款車都拿到唔錯嘅評級。不過 Proton X50 嘅 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA) 同 Chery Tiggo 9 嘅 Basic 喺功能上有啲差異,如果你比較重視主動安全嘅話,可以仔細對比下兩者嘅功能列表。
Proton X50 採用 4WD 驅動方式。
Chery Tiggo 9 採用 FWD 驅動方式。
Proton 嘅 4WD 同 Chery 嘅 FWD 喺操控上會有唔同感受,建議試駕比較。
Proton X50 同 Chery Tiggo 9 都係馬來西亞市場嘅主流選擇,適合家庭用、日常通勤。如果你更重視品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就揀配置更豐富嗰款。最終仲係建議兩款都去試駕,親身體驗先最重要。
總體嚟講,Proton X50 同 Chery Tiggo 9 都係馬來西亞市場好唔錯嘅車型。揀邊架車,關鍵仲係要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行之報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

Momenta 上市,即係佢自己嘅關鍵時刻,亦係整個自動駕駛同物理 AI 產業嘅一次公開答辯。
文丨智駕網 零醬 雨來
編輯丨浪浪山與明知山
喺何小鵬宣佈 GX 係物理 AI 第一輛車,李想將全新 L9 稱之為具身智能旗艦之後,大衆忽然明白,智能汽車、自動駕駛喺資本市場已經唔係嗰個令人興奮、趨之若鶩嘅當紅美人咗。
昨日仲係小甜甜,今日已經係牛夫人。
Momenta 即時放棄咗自動駕駛呢個過時嘅概念,頭頂物理 AI 第一股喺資本市場迎來咗一轮認購高潮。

7 月 8 日,Momenta 正式喺港交所挂牌,以 301 港元開出,高於 295.6 港元/股嘅招股價,盤中最高觸及 314.80 港元,市值一度突破 700 億港元,尾盤回落至 299 港元附近。

由於 Momenta 公開發售部分獲得 414 倍超額認購,佢「綠鞋」(超額配股權)大概率會全額行使,這意味著佢將發售約 2,293 萬股,募集資金總額達到約 68 億港元,超過佢最初預計嘅 58.9 億港元近 10 億港元。
令 Momenta 團隊值得驕傲嘅一點,即係佢受到咗國際資本嘅高度青睞,國際發售部分獲得超過 1,000 億港元嘅機構訂單,覆蓋咗來自 15 個國家同地區嘅主權基金同長線基金。
包括新加坡政府投資公司(GIC)、富達國際(Fidelity International)、貝萊德集團(BlackRock)、富蘭克林鄧普頓基金集團(Franklin Templeton)、阿布達比投資局(ADIA)、加拿大養老金計劃投資委員會(CPPIB)、淡馬錫(Temasek)、威靈頓(Wellington)、施羅德(Schroders)等全球頂級機構。
而喺上市之前,Momenta 引入嘅 14 間基石投資者,佢陣容堪稱豪華,佢認購額約 30 億港元超過咗佢募集總額嘅一半。
如此嘅瘋狂,呢個係物理 AI 第一股引發嘅瘋狂嗎?
顯然並唔那麼單純。
01.
降溫嘅智駕與升溫嘅「物理 AI」
頗具戲劇性嘅一面,喺 7 月 8 日共有五間公司喺港交所同時敲鐘,其中即有一家同 Momenta 定位接近嘅無人駕駛公司易控智駕,二者同係蔚來資本投資嘅企業。
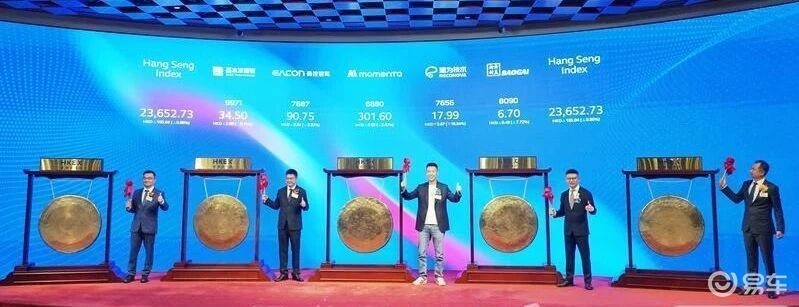
兩間企業喺 IPO 階段同上市首日演繹咗一轮不同嘅劇本。
易控智駕面向礦區無人駕駛,同 Momenta 規模甚細,喺定價上同 Momenta 嘅一口價模式相比,佢招股區間定咗喺 81.16 至 87.92 港元,但最終也實現咗以上限定價。
同 Momenta 大受追捧相比,喺上市前一晚嘅暗盤交易中,佢成交均價為 87.07 港元,不但低於發行價,盤中更一度下探近兩成,收盤漲幅僅 4%,振幅接近 25%,多空分歧明顯。
但喺 7 月 8 日正式上市之後,同 Momenta 高开但午後回落相比,中間一度跌破發行價,易控智駕則最終錄得較發行價上漲 9.99%,總市值佔上 142.99 億港元。

冇物理 AI 概念加持嘅易控智駕同 Momenta 一樣都冇實現盈利,都依然深陷虧損之中,仲冇明確嘅盈利時間表,資本市場對兩間公司嘅熱情與看空都聚焦於未來。
自動駕駛嘅概念係咪真係過時咗呢?
從融資額度而言,握住最多量產客戶嘅 Momenta 嘅融資規模並冇超過小馬智行去年喺港交所 IPO 時 77 億港元融資,但高於喺芯片、算法同時佈局嘅地平線。

但喺 AI 嘅潮水氾濫之下,呢啲已上市嘅智駕公司嘅股價多數較發行價已經腰斬。
智駕概念喺資本市場嘅熱度下降亦係事實。
但 Momenta 同樣唔可否認嘅係令佢未來變得可觸摸,更有想像空間嘅依然係佢喺乘用車市場建立嘅地位。
02.
驚嘅 70% 毛利率
喺 Momenta 上市之前發佈嘅招股書中公佈嘅 2025 年高至 71.6% 嘅毛利率一度引發咗車企同 Momenta 嘅一場爭論。
喺汽車業內普遍認為華為乾崑過於昂貴,所以轉身擁抱 Momenta、卓驭呢啲以性價比著稱嘅智駕公司後,唔曾想佢哋嘅毛利率居然超過咗 50%!
相比之下,而家傳統車企中最成功有迪鏈護體嘅比亞迪其毛利率只有 18.81%,新入局嘅小米汽車嘅毛利率則係 20.1%,鴻蒙智行中最成功嘅賽力斯毛利率較高也不過 26.24%,中國汽車企業嘅毛利率普遍低於 15%,部分企業甚至喺個位數徘徊,而喺產業鏈端,一度被視為眼中釘肉中刺嘅寧德時代喺今年一季度嘅毛利率都剛剛 24.82%。
呢背後嘅邏輯其實並唔複雜,以製造業嘅毛利率同軟件公司相比本身就係關公戰秦瓊。
同 Momenta 喺同一賽道嘅地平線 2025 年嘅毛利率為 64.5%(芯片 + 智駕方案綜合毛利率),文遠知行嘅毛利率亦接近 30%,小馬智行雖然僅有 15.7%,呢同佢生產營運 Robotaxi 同研發投入過高有關。
而 Momenta 嘅超高毛利率在於佢即將跨過盈虧平衡點。
Momenta 自 2023 年至 2025 年營收由 7.43 億元增至 24.13 億,毛利率亦係一步步由 17.5% 提升至 71.6%;2025 年研發投入為 18.7 億,佔收入 77.5%。
財務指標(人民幣千元)
2023 年
2024 年
2025 年
營業收入
742,745
1,324,688
2,412,523
毛利率
17.5%
49.0%
71.6%
研發開支
(1,281,138)
(1,508,270)
(1,868,906)
賬面淨虧損
(2,570,342)
(3,205,730)
(3,457,912)
優先股公允價值變動
(1,190,108)
(1,967,501)
(2,842,919)
經調整淨虧損 (Non-IFRS)
(1,093,037)
(959,204)
(302,804)
雖然淨虧損仍在擴大,從 5.7 億、32.1 億擴大到 34.6 億,但若剔除股份支付等因素,經調整虧損已由 2023 年嘅 10.9 億收窄至 2025 年嘅 3 億;截至 2025 年底,公司現金儲備超過 100 億。
呢幾個數字傳遞嘅信號非常明確:
Momenta 仲未盈利,但佢已經唔係一家單靠融資活命嘅純研發型公司,而係一家收入增長快、毛利改善快、商業模型已經被市場看懂嘅公司。
Momenta 喺上市前夕宣佈佢量產搭載規模突破 100 萬台,成功交付超過 100 款車,累計定點車超 210 款;全球前十大車企中已有 9 家同佢合作。

喺智駕尤其係高級智駕市場,真正同 Momenta 喺規模上相當嘅企業唯有華為乾崑。

對於毛利高,Momenta 自己解釋係佢營收構成大致分為兩個部分:
技術開發服務,即係為車企定制開發與之適應嘅智能駕駛方案;
軟件授權許可,即車型量產後,按銷量收取智駕系統使用費。
前者同 Momenta 嘅合作車型數量相關,後者同車型銷量掛鉤。
2025 年,Momenta 技術開發服務收入為 14.5 億,軟件授權許可收入為 9.7 億,而喺 2023 年,佢技術服務開發收入佔比超過 90%,僅僅過咗兩年時間,佢軟件授權許可收入佔比已經達到咗 40.1%。

軟件授權許可收入係一種邊際成本趨近於零,唔使付出太高嘅人力成本,近似於「躺著收錢」嘅業務模式,大幅拉高咗 Momenta 嘅毛利率。
Momenta 嘅毛利率近三年翻四倍,2025 年 71.6% 嘅毛利率已經達到同軟件公司 SaaS 公司嘅水平,正係智駕公司實現夢寐以求嘅技術復利,喺一套系統成熟後可以喺市場上迅速複製。
Momenta CEO曹旭東表示:「自動駕駛有非常強嘅規模效應同先發優勢,佢嘅效應比芯片行業更強。自動駕駛係軟件,邊際成本係零,因此佢規模效應更強。」
不過呢種模式,並非屬於 Momenta 獨有,喺而家競爭越來越激烈嘅智駕供應商市場,已有好多智駕公司將技術開發模式同軟件授權模式結合為一,以零成本向主機廠開發或提供佢哋智駕方案。
以低於自身成本嘅方式向主機廠提供解決方案開始有年。
相比而言,Momenta 喺一定程度上建立咗自己嘅護城河,呢條護城河即係同眾多車企建立咗資本同技術嘅雙重連接。
喺 Momenta 同全球 24 間整車廠建立嘅合作中,覆蓋咗全球前十大整車廠集團中嘅九家(如梅賽德斯 - 奔馳、豐田、寶馬中國等)同中國前十大整車廠全部。
而喺呢啲用戶中,上汽、通用、奔馳、豐田、比亞迪、現代、奇瑞等 7 間具備全球影響力嘅車企都係 Momenta 嘅投資人。
而奔馳、比亞迪更加喺 Momenta 嘅 IPO 中成為咗基石投資者。
喺產業鏈端則覆蓋咗博世、德賽西威、立訊精密,出行平台囊括咗 Uber、Grab、Stone Venture 等,科技巨頭則包括騰訊、阿里雲、螞蟻集團、京東等。
智己汽車則同 Momenta 實現咗雙向持股,上汽集團係 Momenta 第一大機構股東,Momenta 同時反向持股智己汽車。
一個被 Momenta 多次引用嘅案例係,從 2017 年奔馳投資 Momenta 始,到 2025 年底量產,用咗整整 8 年。但一旦實現突破,幾乎就一步到位:Momenta 喺 2024 年拿到咗奔馳所有嘅電車同油車嘅業務。
Momenta 正喺智駕領域複製寧德時代同車企通過多種方式實現雙向嘅深度綁定,讓車企參與自己嘅利潤成長。
不過,主機廠從來都係勢力嘅,比亞迪不僅投資咗 Momenta,亦深度投資咗卓驭,更加喺 Momenta IPO 嘅敏感時刻,王傳福同地平線創世人余凯同窗引發外界聯想。
以比亞迪、奇瑞為代表嘅車企,一方面幾乎同所有嘅智駕供應商建立咗合作,一方面依然喺投入巨資進行自研。
70% 嘅毛利固係擋唔住嘅誘惑,喺技術路線收斂之後,所有嘅團隊似乎都睇到智駕終局已經唔遠。
「地卓華魔」一方面彼此圍著全球主機廠劃分勢力範圍,一轉身同時要防備主機廠自研替代。
呢一幕喺智駕芯片領域已經上演過一次,今年蔚小理嘅自研芯片相繼量產上車,作為呢一市場嘅中國本土明星公司地平線股價經歷咗一轮腰斬式嘅跳水。
「物理 AI」正係咁同時講畀主機廠同資本市場嘅新敘事。
從「自動駕駛解決方案供應商」走向「物理 AI 基座模型構建者」,呢並唔係 Momenta 一家公司嘅選擇,而係幾乎所有智駕供應商嘅共同選擇。
03.
「物理 AI」背後藏住平台公司嘅野望
本質上,自動駕駛就係物理 AI,物理 AI 就係萬物智駕,二者冇區別。
只係物理 AI 打開咗資本嘅想像空間,佢精准嘅描述咗一條智駕公司從單維依賴主機廠嘅供應商到升維為 AI 平台類公司嘅清晰願景。
物理 AI 呢個由黃仁勳推動走紅嘅概念,係相對數字 AI 而言嘅。喺數字 AI 一片紅海嘅競爭中,智駕公司成為物理 AI 嘅先行者,對於部分頭部玩家更同時擁有咗數據優勢同規模優勢。
Momenta 無疑同時喺這兩個領域都係佼佼者,Momenta 表示已透過 100 萬台量產車跑通咗數據同商業嘅 Scaling。
而令 Momenta 自信打造世界基座模型嘅時機已經成熟,係英偉達推出嘅世界模型正從智駕公司嘅仿真工具,生成數據來訓練或測試嘅主模型變成可應用於「端到端基座模型預訓練」嘅理解世界物理規律嘅基座模型,透過把物理世界嘅規律壓縮到模型裡面,使 World Model 具備物理世界嘅常識。
Momenta 推出嘅 R7 世界模型,宣稱使系統嘅整體產品性能同上限實現咗 10 到 100 倍嘅代際躍昇。
世界模型可憑藉同一套底層系統架構,同時賦能乘用車、Robotaxi、Robovan 同 Robotruck 四大業務形態,並有望延展到具身智能等領域。
Momenta 對於物理 AI 嘅願景係 All-in-One Platform,實現技術跨場景落地,成為一家 AI 平台公司。
呢種極簡架構,將徹底終結過往各場景孤立開發嘅模式,核心底層技術嘅跨場景複用極大地攤銷咗多業務線並行嘅研發成本,提升咗系統嘅整體迭代效率。
Momenta 將其描述為:「一套模型、多維共生」,可以大大攤薄研發成本,並隨業務邊界拓展,指數級放大先發優勢,形成「贏家通吃」嘅行業終局。
佢嘅毛利率甚至將遠超 70%。
曹旭東認為:「任何一個人工智能應用,一旦接近人類嘅水平,就會喺很短嘅時間內大幅超過人類嘅水平。」
呢意味著,前面可能花十年、二十年爬坡,但超越人可能就發生喺一兩年內。而家幾乎所有嘅智駕公司都已宣佈向物理 AI 轉型,佢嘅緊迫性亦喺於此。
而家,無論係堅持世界模型路線定係同樣大熱嘅 VLA 模型嘅智駕公司基本都已經打通咗 L2 到 L4。
Momenta 堅持經年嘅「一個飛輪兩條腿」戰略,基於統一算法同傳感器架構,實現咗 L2++ 數據流同 L4 技術流嘅打通,佢嘅技術可以喺乘用車同 Robotaxi 複用。
不過,而家呢個越來越接近「Android」嘅智駕平台最大嘅市場依然喺乘用車市場。
喺 Momenta 自己引用嘅 CIC 灼識諮詢嘅預測數據顯示:
到 2030 年,全球 Robo 市場規模(Robotaxi、Robovan、Robotruck)將達 1998 億美金,其中 Robotaxi 全球同中國市場規模將分別增長至約 818 億美金同 381 億美金,中國 Robotaxi 滲透率預計將達到 11.9%,高於全球嘅 5.7%;Robovan 全球同中國市場規模將分別達到約 850 億美金同 535 億美金,市場滲透率將達 6.9% 同 14.0%;Robotruck 全球同中國市場規模將分別達到約 330 億美金同 165 億美金,市場滲透率將達 0.6% 同 1.2%。

但量產輔助駕駛市場規模到 2030 年,全球市場規模將達 3059 億美金,依然遠超 Robo 市場:
2025 年,全球同中國 L2 級 - 高速 NOA / L2 級 - 城市 NOA 輔助駕駛及更高級別智能駕駛市場分別達到約 204 億美金同 130 億美金,預期到 2030 年將擴大至 3,059 億美金同 1,666 億美金,複合年增長率分別為 71.9% 同 66.5%。

而 Robotaxi 市場因城市准入政策,各地唔同嘅監管法規、營運成本存在巨大嘅唔確定性。
Momenta 此次 IPO 嘅集資約 20% 將投向 Robotaxi 商業化同規模化,一方面 L4 有巨大嘅想像空間,但亦係唔確定性最高嘅部分,Robotaxi 何時真正貢獻清晰收入仲冇清晰嘅時間表。
與此同時,喺乘用車市場,Momenta 雖然優勢明顯,但並冇殺死比賽。
喺傳統所謂嘅地平線、華為乾坤智駕、卓驭之外,仲有文遠、小馬智行;同樣喺籌備 IPO 嘅輕舟智航、元戎啟行。
喺 L4 市場同樣建立一定優勢嘅仲有馭勢科技、百度阿波羅等。
04.
智駕市場尚未形成贏家通吃
一個類似於 Android 嘅智駕平台終將出現,但最終花落誰家,仲冇一家公司確立絕對優勢。
呢令 Momenta 嘅高毛利嘅可持續性同樣存在唔確定性。
其一,單車軟件授權單價持續下行已成行業趨勢。隨著賽道玩家增多、低端車型滲透加速,城市 NOA 軟件許可費從早期數千元降至千元級別,部分輕量化方案單價更低。
Momenta 為搶佔中低端車型市場,主動下沉定價,喺規模化擴張嘅同時,必然面臨單車型利潤收縮嘅壓力。
其二,客戶集中度極高,議價能力脆弱。
過去三年中,前五名客戶貢獻咗 62.6% 至 86.7% 嘅收入,2025 年最大客戶(推測為比亞迪)收入佔比達 21.6%。一旦核心客戶因銷量唔及預期或轉向自研/競爭對手,許可費收入將戛然而止。比亞迪作為 Momenta 最大客戶,全年搭載量約 30 萬輛,佢嘅戰略選擇將直接影響 Momenta 嘅收入穩定性。
第三,車企自研嘅反抗正在加速。吉利、比亞迪、蔚來等頭部車企嘅實踐表明,唯有以自主技術打破外部捆綁,先至可以重奪定價權。
吉利堅持三電、智駕、座艙全棧自研,極氪 9X 搭載自研千里浩瀚 G-ASD 智駕系統,毛利率穩定喺 20% 以上;蔚來宣佈全系換裝自研神玑 NX9031 芯片,單車成本直接降低 1 萬。
可以話,對於 Momenta 而言,71.6% 嘅毛利率既係護城河,亦係火藥桶。
曹旭東預測「長期睇第三方供應會係市場主流」,但最終形成 2-3 家「贏家通吃」嘅行業終局顯然唔係主機廠希望睇到嘅。
Momenta 有機會成為中國智能駕駛公司入面,最早被市場當做平台型 AI 企業嚟看待嗰一個,但如果遲遲無法實現壟斷優勢,佢都可能有快被拉回「高研發、重投入、未盈利」嘅傳統智能駕駛估值框架。
從呢個角度講,Momenta 上市,既係佢自己嘅關鍵時刻,亦係整個智能駕駛同物理 AI 產業嘅一次公開答辯。
寫於最後
喺具身智能、物理 AI 呢啲概念進入大眾語境之後,智能駕駛變得似乎失去咗魅力,一個直觀地表現係大量嘅智能駕駛人才湧入具身智能創業,馬斯克拆除 Model S/X 生產線轉產機器人嘅一幕粗暴而令人瞠目結舌。
咁為智能駕駛帶上一頂物理 AI 嘅王冠係咪可以吸引數字 AI 引發嘅資本狂熱呢?
創立不過五年之久嘅 Anthropic 實現 9650 億美金嘅驚天估值當然並冇喺 Momenta 身上復現。
可以說明嘅一點即係,物理 AI 呢個概念有一定嘅欺騙性,佢同數字 AI 並唔完全係隔離同相對嘅,對於 OpenAI、Gemini 呢啲數字大模型而言,同樣可以進入物理 AI 所聚焦嘅任何一個商業賽道。
今年 5 月 16 日,卓驭科技 CEO 沈劭劼向自己嘅同行發出警告:
「我非常擔心搞大模型嘅嚟做智駕,嗰對我哋係降維打擊。我真係怕嘅,係做數字 AI 嘅大模型公司反過嚟將我哋給滅咗。」
「除咗特斯拉,冇一家智駕公司真正落地咗 Scaling Law(模型隨算力 / 數據 / 參數擴大而質變);但 OpenAI、字節已經將 Scaling Law 跑通咗。」
而係以 OpenAI 為代表嘅大模型公司走嘅係「多模態 + 世界模型 + 自回歸推理」,天然適合「視覺預測 + 物理推理 + 長時序決策」,正係智駕系統嘅技術核心。
大模型唔使從零學開車,只須微調,就快達到甚至超越 L2+/L4 能力。
換句話說,雖然同 Momenta 定位最接近嘅係華為引望同地平線,但呢啲智駕公司嘅長期競爭對手既唔係彼此,亦唔係主機廠自研,而可能來自於門外嘅野蠻人。
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿 Perodua Aruz 同 Mazda CX-30 嚟比較。呢兩部車喺價錢同定位上都幾接近,而家我哋就由多個方面做個詳細比較,幫你慳返做功課嘅時間。
Perodua Aruz 喺馬來西亞嘅 OTR 售價係 RM 72,900 - 77,900,合共有 2 個版本,包括 1.5L X(RM 72,900)、1.5L AV(RM 77,900)等。
Mazda CX-30 喺馬來西亞嘅 OTR 售價係 RM 122,409 - 146,409,合共有 4 個版本,包括 2025 2.0L High+ Premium(RM 146,409)、2025 2.0L High+(RM 138,409)、2025 2.0L High(RM 130,409)等。
由價錢睇,Perodua Aruz 嘅起步價確係比 Mazda CX-30 平咗 RM 49,509。如果你預算有限,Perodua 嘅入門版已經可以满足日常需要。不過都要留意,平嗰幾千蚊,可能喺配備上會有取舍,具體要看你嘅需求。

Perodua Aruz 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括。
Mazda CX-30 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 i-Activsense。
兩部車嘅安全評級一樣,喺呢個級別入面安全配備都算好齊全。而家嘅新車安全性都唔差,唔使太擔心呢一點。
Perodua Aruz 車身長 4400 mm,行李廂 400 L。
Mazda CX-30 車身長 4500 mm,行李廂 450 L。
空間方面,Mazda CX-30 嘅車身比 Perodua Aruz 長咗 100 mm,乘車空間更有優勢。不過 Perodua Aruz 喺市區停車會靈活少少,各有取舍。

Perodua Aruz 保用 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
Mazda CX-30 保用 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
兩部車嘅保用條件一樣,呢方面唔使糾結。實際保養成本仲要看品牌嘅服務網絡同零件價格,建議去車友群問吓真實車主嘅經驗。

總括嚟講,Perodua Aruz 同 Mazda CX-30 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵仲係要看你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,先至去試駕做最終決定。買車係件大事,花啲時間做功課絕對唔會錯。


要講兩年比較內捲嘅汽車細分市場,「方盒子」肯定名列前茅,作為有住百年傳承嘅經典造型,哪怕汽車設計經歷過如此長時間嘅演變,佢仍然係永不過時嘅高分佳作。面對呢一市場需求,各大車企亦紛紛加碼方盒子市場,就導致競爭狀況亦愈趨激烈,消費者亦喺方盒子市場挑花咗眼。咁就來咗問題,在手頭握有 10 多萬預算嘅情況下,邊部方盒子更加值得選購呢?

10 萬級超大方盒子
既然講到呢度,我哋肯定要先睇銷量數據,畢竟能夠令大多數消費者都選購嘅車型,佢嘅綜合實力同產品品質一定夠硬。呢個,喺剛過去嘅 6 月就有一部方盒子以超過 8000 部嘅耀眼成績,登頂十萬級細分市場嘅銷量冠軍,佢就係售價只得 9.99 萬起嘅「BJ30 旅行家」。

了解北京越野嘅都清楚,作為公認嘅「中國越野車發明者」,無論係喺越野圈,定係方盒子領域,佢都有住絕對嘅話語權。喺擁有如此深厚歷史底蘊同雄厚技術實力嘅背景下,北京越野自然係知道用戶想要邊種車。

因此,我哋可以見到 BJ30 旅行家喺傳承方盒子呢一經典硬派造型嘅同時,仲喺入面融入咗好多華夏文化元素,好似同級獨有嘅五闋星環貫穿燈組,再搭配全套電感潮改套件同靚麗配色,既可大幅提升外觀辨識度,又能滿足年輕人追求嘅科技感同年輕化。

將目光轉向車內,大家就會發現,定位 A 級 SUV 嘅 BJ30 旅行家,座艙空間竟然要比好多中型 SUV 更加大,呢個係得益於經過優化嘅車身設計,令到車身闊度超過 1 米 9,軸距更加超 2 米 8,搭配支援加熱通風等功能嘅座椅,哪怕係坐滿五個人都能坐住非常寬敞舒適,並且仲可以滿足外出露營時嘅載物需求。

唔止呢啲,考慮到年輕用戶好注重智能體驗,BJ30 旅行家喺座艙配置上都冇含糊,由 15.6 吋中控大屏、全液晶儀表盤等多項科技配置,到支援智能語音識別控制、手機與車互連、OTA 升級同多項常用功能嘅車載系統,以上呢啲全部都係標配,智能體驗完全不輸同價位嘅新能源車型。

同時,為了令出行變得更加省心安心,BJ30 旅行家仲搭載咗 L2 級智能駕駛輔助系統,佢唔只擁有多達近 20 個高感知硬件,仲支援 540 度全景影像、車輛偏離預警、前後方碰撞預警、DOW 開門預警、變線輔助同主動煞車等多項主動駕駛輔助功能,令用戶喺長途行車時可以一定程度上解放雙手雙腳,從而降低長時間駕駛疲勞感,並提升行車安全性。

「越野 + 慳錢」一應俱全
睇到呢度,相信好多人肯定好期待一點,就係作為一部硬派 SUV,佢嘅越級實力點樣呢?呢就要講 BJ30 旅行家搭載嘅「三擎四驅六模 HEV 混動架構」,呢個係由 41% 熱效率混動專用引擎 + 前驅動電機 + 後驅動電機組成,透過各自擅長嘅長距離節能、實時補能同瞬間爆發,令到呢架車具備涵蓋全場景出行嘅實力。

我哋嚟睇最直觀嘅數據,以剛推出嘅 BJ30 旅行家混動高光版為例,佢嘅後電機喺原本嘅基礎上又將功率增大至 70kW,呢樣就令到擁有全車雙電機總功率達到驚人嘅 200kW,比好多燃油越野車配備嘅高功率六缸引擎仲要犀利,搭配可自動選擇最優模式嘅智能四驅系統,同埋能量中鎖、四輪電子限滑同智電 ATS 全地形控制系統等硬核越野配備,亦令到呢架硬派方盒子能輕鬆應付泥地、沙地等較高難度嘅越野場景,從而令到呢個價位嘅方盒子 SUV 告別「樣品貨」嘅使用槽點。

大家亦唔使擔心性能強勁嘅同時,能耗亦會隨之增加,作為中國方盒子 SUV 品類嘅首款 HEV 混動車型,配備高效混動系統嘅 BJ30 旅行家,經過南非、印尼、阿聯酋、波蘭、墨西哥嘅五國汽車博主實測,均跑出百公里油耗唔超 5L 嘅成績,比同級別嘅燃油 SUV 低咗接近一半,真正實現兼顧可城可野嘅全場景出行需求。

大俠車談:無可置疑,BJ30 旅行家之所以能喺競爭如此激烈嘅細分市場,迅速登頂十萬級方盒子市場嘅銷量冠軍,核心原因就喺佢喺 10 萬級呢個價位區間,令到喜愛越野但又想兼顧家用嘅用戶,買到一部能真正實現涵蓋全場景需求嘅硬派方盒子!
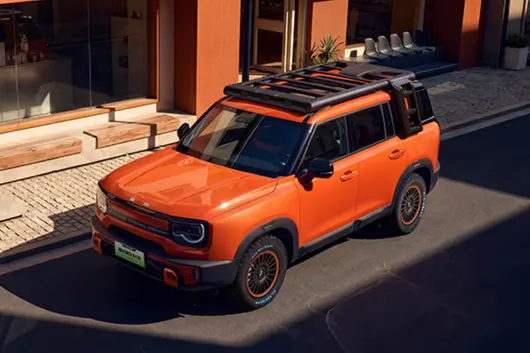
Malaysia's four-year electric vehicle import tax exemption policy has officially ended. The new regulations implemented on July 1 directly tightened the entry threshold for imported electric vehicles. Regarding complete vehicle imports, the new regulations require that the CIF price of all CBU electric vehicles must not be lower than 200,000 Ringgit (approximately 320,000 RMB), and the motor output power must not be lower than 180 kW (about 241 hp). Both conditions must be met simultaneously; neither can be missing.

Relying on the previously relaxed environment, Chinese brands once captured 60% of the new energy vehicle market share in Malaysia. Now, the local market intends to replicate the industrialization model of local automakers, forcing foreign investment to shift from complete vehicle trading to local manufacturing. After all, no one wants to be just a dumping ground for goods.
Electric Vehicle New Policy Heavy Implementation in July
After the four-year electric vehicle import tariff exemption period ends, Malaysia significantly tightened complete vehicle import rules, upgrading the previously duty-free 100,000 Ringgit CIF threshold to a mandatory 200,000 Ringgit entry baseline, while rigidly binding a 180 kW motor power lower limit; both conditions are indispensable. Previously, the 100,000 Ringgit was only the tariff exemption line, the price point perfectly fit the pricing system of main home-use models going overseas, BYD Dolphin, entry-level Atto 3, and other volume-selling models relied on cost advantages during the tax exemption period, becoming core products for Chinese brands to seize the local market.

After the CIF price is raised to 200,000 Ringgit, adding import tariffs, domestic sales tax, and dealer markups, estimated based on the current tax and fee structure of the Malaysian automotive market, the final vehicle price will reach above 300,000 Ringgit, converting to RMB, it is close to 480,000. Most Malaysian households' car purchasing budgets are in the range of 100,000 to 250,000 Ringgit, this price range of 300,000 Ringgit is a niche market where Tesla and BBA pure electric models have already dug deep, there are very few models domestically that can cross both rigid thresholds, the price-friendly family car base that Chinese brands originally stabilized via pure import routes is essentially locked by the policy; while vehicles assembled locally via CKD can still legally cover the mainstream family consumption price range of 100,000 to 250,000 Ringgit.
Many brands can choose to rent existing local factories for knocked-down assembly production, Leapmotor uses Stellantis idle production lines to launch C10, Xpeng partners with local manufacturers to launch right-hand drive G6, by reusing existing capacity to avoid the strict clauses of 80% mandatory export for new factories, this is the easiest flexible method to implement at present. However, this light-asset OEM model has many hidden dangers from the perspective of long-term industrial layout.

Car companies do not own production lines, unable to independently expand production schedules during peak order surges, production line modifications for model updates are also subject to the partner's will, the production rhythm is hard to control completely by themselves. More critically, core components like batteries, electronic controls still rely on being shipped separately from domestic sources, localization only stays at the final process. Referencing Indonesia's practice of continuously raising local component ratios, the local 2030 target for new energy vehicle local component penetration rate is set at 80%, the overall industrial orientation in Southeast Asia is forcing upstream supply chains to land locally, the model of only simple assembly will eventually face policy constraints.
Moreover, this detour route itself has no permanent guarantee at the legal level, Malaysia can update industrial regulations at any time later, including existing factory cooperation projects into export quota supervision, this shortcut could be tightened or blocked at any moment. The export strategy of only doing trade output and unwilling to deeply bind local industrial chains has no more sustainable space.
Chinese Automakers Face Major Differentiation
Geely Holdings is the biggest indirect beneficiary of this round of policies. Geely holds 49.9% of shares in Malaysia's traditional state-owned automaker Proton, and Proton itself holds original CKD production qualifications, it does not belong to the new foreign investment factory construction projects approved after September 2025. This means the strictest 80% mandatory export quota in the new regulations cannot constrain Proton from the start. Proton has no ratio restrictions on sales in the local market, and can long-term enjoy policy inclinations for local component support, effectively standing in the safe zone by nature within the environment of tightening policies.

In addition, Xpeng Motors relies on EPMB's existing factory in Melaka State to carry out CKD complete knocked-down assembly, Leapmotor uses Stellantis's own complete vehicle factory located in Kulim, Kedah, Malaysia for local assembly. Both types of projects belong to reusing existing local capacity, and can be exempted from the requirement of 80% mandatory export quota in the new regulations.
While BYD's wholly-owned new factory planned in Perak State, Chery's new industrial park planned in Selangor State, both belong to new manufacturing projects approved after September 2025, will be strictly constrained by the 80% export quota; brands like Great Wall Motors relying on pure imports of affordable models, directly face the impact of losing the access qualification for main models.
The core logic of the new regulations is actually setting up a double barrier for "new foreign players", clearly not welcoming foreign enterprises that only focus on building capacity in the local market. The remaining options for foreign brands are very limited: either introduce high-end models via pure import routes, giving up the mainstream volume market; or rent existing local production lines for knocked-down assembly, production capacity rhythm and cost control are all subject to others, hard to form scaled price competitiveness.
Viewing the entire Southeast Asian market dimension, this logic is not unfamiliar. Thailand and Indonesia's industrial policy directions have been highly consistent in the past two years: the threshold for complete vehicle imports continues to rise, the core conditions for market access are gradually shifting from product competitiveness to the depth of localization investment.

In early years, when most Chinese electric vehicle brands first entered Southeast Asia, they followed a typical trade route: controlling costs by relying on the scale advantages of the domestic supply chain, and rapidly distributing goods after complete vehicles are shipped by sea, relying on price differences, most stayed at the superficial cooperation stage of "selling products". However, a few brands like Geely have already completed deep localization layout through the method of investing in local car companies.
Now, the demands of ASEAN core markets have shifted from "richening consumption choices" to "driving local industrial upgrades", the exchange chips for market access have also changed from pure product power to capacity landing, technology transfer, and supply chain driving capabilities. Brands that only do commodity output and are unwilling to do industrial binding will sooner or later be squeezed into niche peripheral markets by gradually tightening rules.
In other words, the export 1.0 stage relying purely on complete vehicle distribution has reached its end in the Southeast Asian market.
Consumer Car Review
Actually, the screening logic of the Southeast Asian market has never changed: It welcomes co-builders who bring the industrial chain, not passersby who only sell products. When rules tighten step by step, the winning hand of going overseas has long shifted from product costs, pricing strategies, to the ability to predict industrial rules, and the depth of layout rooted in the local area.
After all, a model without an industrial anchor point will ultimately not go far.
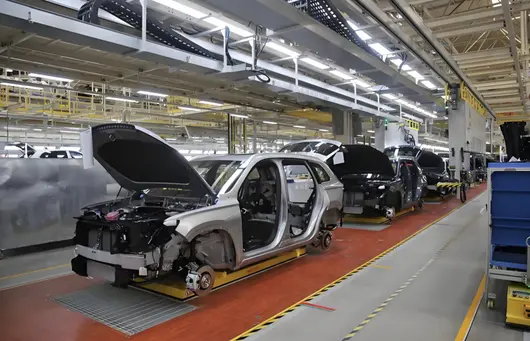
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿 Perodua Ativa 同 Proton X90 做比較。呢兩款車喺價位同定位上都幾接近,今日我哋就從多個方面做一個詳細嘅對比,幫你省返做功課嘅時間。
Perodua Ativa 喺馬來西亞嘅 OTR 售價係 RM 62,500 - 73,400,一共有 3 個版本,包括 1.0L Turbo X(RM 62,500)、1.0L Turbo H(RM 67,300)、1.0L Turbo AV(RM 73,400)等。
Proton X90 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,800,一共有 4 個版本,包括 2026 1.5T Prime X(RM 122,800)、2026 1.5T Prime(RM 116,800)、2026 1.5T Lite(RM 106,800)等。
從價錢嚟睇,Perodua Ativa 嘅入門價確實比 Proton X90 平咗 RM 44,300。如果你預算有限,Perodua 嘅入門版已經可以滿足日常需要。但都要注意,平嗰啲幾千塊,可能喺配備上要有取舍,具體就要睇你嘅需要。

Perodua Ativa 車身長 4400 mm,行李箱 400 L。
Proton X90 車身長 4400 mm,行李箱 400 L。
兩款車嘅尺寸幾乎一樣,車內空間差異唔大。呢級別嘅車,日常使用完全夠用。
Perodua Ativa 保養 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
Proton X90 保養 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
兩款車嘅保養條件一樣,呢方面唔使糾結。實際保養成本仲要睇品牌嘅服務網絡同零件價格,建議去車友群問下真實車主嘅經驗。
Perodua Ativa 同 Proton X90 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更重視品牌口碑同二手價,可以優先考慮口碑更好嗰款;如果你更介意性價比同配備,就揀配置更豐富嗰款。最終都係建議兩款都去試駕,親身試過先係最重要。

總括嚟講,Perodua Ativa 同 Proton X90 都係馬來西亞市場好唔錯嘅車型。揀邊架車,關鍵都要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Hyundai Tucson 同 Ford Everest 嚟做比較。今日我哋從多個方面做一個詳細嘅比較,幫你節省做功課嘅時間。


Hyundai Tucson 喺馬來西亞嘅 OTR 售價係 RM 143,888 - 197,888,一共有 5 個版本,包括 2025 HEV 1.6T AT 2WD Prestige(RM 197,888)、2025 1.6T DCT 4WD Prestige(RM 186,888)、2025 1.6T DCT 2WD Prime(RM 164,888)等。
Ford Everest 喺馬來西亞嘅 OTR 售價係 RM 266,338 - 430,838,一共有 6 個版本,包括 2026 3.0T 4WD Platinum(RM 430,838)、2026 2.0T 4WD Platinum(RM 348,838)、2026 2.0T 4WD Sport(RM 316,838)等。
從價錢嚟睇,Hyundai Tucson 嘅起步價確實比 Ford Everest 便宜咗 RM 122,450。如果你預算有限,Hyundai 嘅入門版已經可以满足日常需求。但都要留意,便宜嗰幾千塊,可能喺配備上會有取舍,具體要看你嘅需求。

Hyundai Tucson 搭載 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
Ford Everest 搭載 2.5L Diesel,馬力 187 hp。官方油耗 8.5 L/100km。
動力方面,Ford Everest 嘅 2.5L Diesel 比 Hyundai Tucson 嘅 1.5L Turbo 多咗 47 匹馬力。不過日常喺市區開嘅話,兩款車嘅動力都夠用,唔會覺得唔夠力。

Hyundai Tucson 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 SmartSense。
Ford Everest 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 Co-Pilot360。
兩款車嘅安全評級一樣,喺呢個級別裡面安全配備都算俾得好齊全。而家嘅新車安全性都不錯,唔使太擔心這一點。

Hyundai Tucson 採用 FWD 驅動方式。
Ford Everest 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大區別。

總嘅嚟講,Hyundai Tucson 同 Ford Everest 都係馬來西亞市場好唔錯嘅車型。揀邊一輛,關鍵都係要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花點時間做功課絕對唔會錯。

In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
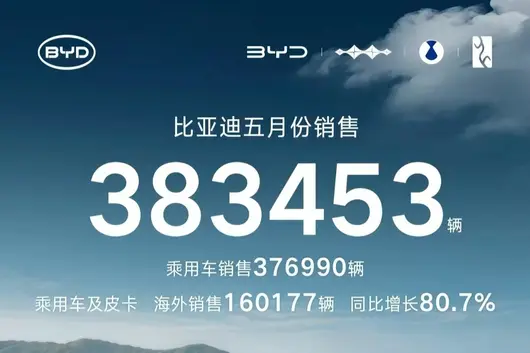
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
車型概覽

吉利星瑞L 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講同級車比較,幫你用買家角度篩走唔適合嘅選擇。
售價仍待確認,買家可以先把佢放入候選名單,等價格落實後再同同級車逐項比較。
購車價格指南
吉利星瑞L 目前售價仍未清晰,較理性嘅做法係先睇版本、車身大小同動力形式,等價格落實後再決定值唔值得落訂。
如果有幾個版本可揀,可以先將 2024 1.5T DHT版(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 吉利星瑞L 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
163 Ps / 120 kW / 100 kW、255/320 N·m 嘅輸出,令高速併線同短距離超車更有信心。 車長 4825 mm、車闊 1880 mm、車高 1469 mm、軸距 2800 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。 混合動力專用(DHT)、前置前駆 會影響起步順滑度、濕地穩定感同長途巡航性格。
優缺點分析
吉利星瑞L 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:動力輸出對高速同上斜更有底氣、空間同車身尺寸方便家庭買家預判實用性。
要留意嘅係,要先確認屋苑、公司或常去商場嘅充電條件、香港停車場同窄路使用要留意車身闊度。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 吉利星瑞L 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「吉利 Geely 星瑞L (Preface L) 適合商務使用嗎?」簡單講,係,吉利 Geely 星瑞L (Preface L) 嘅大氣外觀同舒適空間非常適合商務。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 吉利星瑞L 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先等售價落實,再決定佢應該同邊個級距比較、再睇動力係咪足夠應付高速併線同滿載、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 吉利星瑞L 最重要係先諗清楚充電節奏。屋苑、公司或者常去商場只要有穩定充電選項,電動化用車就會容易相處好多。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。


Another historic moment in the Chinese automotive industry was frozen in Shanghai! — But the real highlight of this ceremony was not the numbers themselves, but how SAIC handed the "stage" over to users.
On May 28, 2026, at the World Living Room, Shanghai North Bund. When the IM LS9 Hyper drove onto the stage as the 100 millionth vehicle produced by SAIC Motor, this constantly running Chinese automotive group achieved an unprecedented accomplishment in the history of the Chinese automotive industry: cumulative production and sales officially exceeded 100 million units.
Undoubtedly, this is a number worth recording in industry history. But what deserves more attention from the outside world is the presentation method of this delivery ceremony.As the "pioneer" among Chinese car companies to first achieve this accomplishment, SAIC left a sample for all subsequent car companies that have not yet "crossed the line" with a creative delivery ceremony.
Ten-plus complete vehicle brands, nineteen car models, fifteen delivery nodes, relayed live across Asia and Europe, constitute a phenomenon-level roadshow centered around the "full value chain". In the current situation where the Chinese automotive industry is generally trapped in anxiety over single product blockbusters, SAIC instead turned this ceremony into the best expression of systemic capabilities.
And the ultimate direction of systemic capabilities has never been about how strong the enterprise itself is, but what the user feels. The true innovation of this delivery ceremony lies precisely in transforming "systemic confidence" into a narrative experiment led by the user.
From Single Product Explosion to System Stability: SAIC's "Long Road of Struggle"
In the past few years, the most familiar successful model in the Chinese automotive industry has been "blockbuster driven": a certain car selling over 10,000 units, a certain technology debuting first, a certain press conference dominating the feeds, almost constituting the KPI for all car companies' communication work. Admittedly, this narrative logic was extremely effective during the window period of new forces rising; it amplified the dramatic nature of single-point breakthroughs and allowed consumers to quickly establish cognitive recognition of new brands.
However, entering 2026, the industry rules have quietly changed. The new force dividend period is nearing its end, the marginal effect of single-point breakthroughs is diminishing, and more and more car companies are finding that having blockbusters alone cannot save the overall downward slide of the sales curve, and talking only about technical parameters is hard to move increasingly calm consumers anymore.

SAIC's delivery ceremony at this juncture happened to land exactly at this node. It did not focus the spotlight on a certain new car, nor did it explode topics by relying on a single celebrity endorser, but used a "family portrait" of nineteen car models, ten-plus brands, covering price tiers from 50,000 to 500,000, covering passenger and commercial, covering domestic and overseas, presenting a complete industrial cross-section to the outside world.
When the IM LS9 Hyper appeared at the main venue, Huajing S was delivered in Liuzhou, MG4 EV Urban was delivered in London, Maxus eDeliver 5 was delivered in Singapore, Hongyan i Jieshi was delivered in Taiyuan, Yuejin Danna T1 was delivered in Yangzhou. The strong signal SAIC wanted to convey to the outside world — delivering 100 million units based on strength was already very clear.
A car company capable of mobilizing so many brands, so many categories, and so many overseas nodes to complete relay delivery today, and able to let the industry see actual results landing, there is only one in China — SAIC Motor.


Behind this, in addition to the rising independent brands, SAIC's joint venture brands that were painstakingly cultivated also played a key role in this ceremony.
Volkswagen ID.ERA 9X, AUDI E7X, Cadillac Kaiwei De, Buick Zhijing E7, Buick Zhijing Shijia appeared collectively. When joint venture models and independent models shared discourse power on the same delivery stage, the outside world saw a more diverse SAIC.It is both the initiator of joint venture cooperation in the fuel vehicle era, the output provider of new energy intelligence technology at present, and the integrator of global technical platforms.
For all Chinese joint venture car companies undergoing the transition of "Electrification + Intelligence" and currently seeking solutions, this is undoubtedly a timely and persuasive answer.
In fact, behind the breakthrough of 100 million new car deliveries of SAIC Motor, besides the main track of passenger vehicles, commercial vehicles are also a key "paving stone". This silent cornerstone filled the last piece of the puzzle in SAIC's layout of complete vehicles. Names of bulk users such as DHL, Jiading Bus, Henglong Sheng Industry and Trade, Di Shang Tie appearing at the main venue means SAIC is willing to leave a position for commercial business in the highest specification communication event, telling everyone that SAIC Group's comprehensive layout and system narrative focus on balance without bias.
Handing the stage back to users: What did this ceremony get right?
If defined in one sentence, this one hundred million vehicle delivery ceremony should be: it is not a press conference, but a "flowing history public class" with users as the protagonist and global relay as the form.
Traditional automotive industry milestone activities are often "enterprise shows" of leader speeches, product presentations, and data displays. But SAIC this time completely subverted this inherent mode. Starting from the main venue at the World Living Room, Shanghai North Bund, connected to domestic multi-cities and overseas delivery sites such as the UK, Indonesia, Singapore via Oriental TV global live broadcast, crossing the Asia-Eurasia continent, spanning multiple time zones, completing a truly meaningful "decentralized" relay delivery.
The core innovation of this ceremony lies in three "Firsts":
First, let users become the absolute protagonist. The 100 millionth user was Momenta CEO Cao Xudong — the setting of "Partner turns into Car Owner" expanded the concept of "User" from consumers to ecosystem partners; the "Ten-Year Trust Agreement" of two generations of Roewe owners, London intern doctor Natalia inheriting her grandfather's MG sentiment, post-85s Village Secretary Pang Fuqiang delivering food for left-behind elderly people using Wuling Rongguang... Behind every delivery action was a true life story. SAIC did not arrange any leader's long speech; all time was handed over to the "delivery" core action and user narrative behind the delivery.
Secondly, replace "centralized stage" with "global relay delivery". From 99,999,996th to 100,000,013th "relay delivery" created real-time suspense and participation; users of different skin colors, different languages, different models appearing successively under the same theme constituted a brand communication event with great impact. This "decentralized" ceremony design has no precedent in Chinese car brands.
Third, define the delivery ceremony itself as "content". Ceremony is news, is communication. SAIC did not rely on traditional press releases, but let the images of global relay, users' true emotional resonance, and the visual spectacle of full category stage presence become the most communicative content themselves. This pioneered a new narrative method of integration between Chinese car brands and media — from "What enterprise says, media writes", to "What media and users jointly witness, what moves them".
The underlying logic of this ceremony is the concentrated fulfillment of SAIC's "Knows Cars and Knows You Better" user concept: not the enterprise standing in the center of the stage telling users "how strong I am", but inviting users onto the stage, letting the world see "how far we have walked together".100 million vehicles is not a cold industrial number, but the total temperature of 100 million trusts. This activity creativity centered on users, with emotional resonance as the core, and global relay as the form, left a "SAIC Sample" with great reference value for how Chinese car brands should do milestone communication.
More Difficult than Delivering 100 Million Vehicles is the "Sustainability" of System Growth
Behind this grand new car delivery ceremony, the author believes that the truly scarce place in SAIC's "100 million milestone" lies in the "sustainability" of system growth.

In fact, SAIC's legendary car making story began with the breakthrough from zero to whole, and was formed through strategic maneuvering and open cooperation.
From the establishment of Shanghai Internal Combustion Engine Parts Manufacturing Company in 1955, to the successful trial production of Phoenix sedan in 1958, to the manual assembly and delivery of the first Santana in 1983, 23 months factory construction and vehicle production by Shanghai General Motors in 1997, 2006 Roewe birth, 2016 Roewe RX5 opened the internet car era, 2020 IM Motors establishment. Every node on SAIC's timeline corresponds to an industrial upgrade of the Chinese automotive industry.
Nowadays, this continuous "startup" already belongs to "rare assets" in the current Chinese automotive industry.
Most car companies either start from joint ventures, or start from new forces, or start from a certain major transformation. But there are few leading enterprises that can tell the complete development story of "from nothing to something, from weak to strong" in the independent and joint venture dual lines with technology, brand, products, and even more subdivided behind them.SAIC's 70-plus years of development history, condensed, is almost a development history of the Chinese automotive industry, and it is precisely this point that constitutes the heaviest historical footnote of the 100 million new vehicle delivery milestone.

Among them, the historical node that determined SAIC's big stride towards the "Electrification + Intelligence" transformation was the crucial year 2014. That year, when senior leaders investigated SAIC's development, they clearly proposed the general policy of "Developing new energy vehicles is the only way for China to move from an automotive giant to an automotive power". This general policy was deeply understood and put into action by SAIC senior leadership, and SAIC immediately launched a comprehensive new energy transformation. This thus opened the prelude to SAIC Group and even the national automotive industry "changing lanes to overtake".
12 years later in 2026, SAIC officially welcomed the user delivery of the 100 millionth new car globally. Behind this, the efforts SAIC made and the results achieved in the new energy sector can be said to be world-renowned.
Looking back 12 years ago, new energy transformation had not yet formed a consensus in the domestic industry circle. Disputes over technology routes, changes in subsidy policies, and shallow market acceptance made many companies hesitate on the transformation rhythm.SAIC decisively chose this path of early transformation. Its R&D investment, capacity layout, and the establishment of innovation systems have always been at the forefront of the industry.
Sprinting in the new energy track has achieved SAIC Group leading today in the intelligence and electrification new era.
Latest data shows that from January to May 2026, SAIC Motor achieved cumulative complete vehicle sales of 1.651 million, continuing to firmly stay at the industry head. Among them, independent brands January-May cumulative sales 1.173 million, year-on-year growth 8.6%, the proportion of group total sales broke 70% for the first time, reaching 71.1%; new energy vehicles January-May cumulative sales 595,000, year-on-year growth 13.2%; overseas market January-May cumulative sales 589,000, year-on-year surge 45.9%. Independent, new energy, and overseas working together simultaneously, pushing SAIC to continue upward during cycle crossing, and also writing a powerful footnote for the new journey after the 1st hundred million delivery. These numbers answer the question of whether long-termism can still run faster in the Chinese automotive industry.

In addition, another supporting point of SAIC's strategic determination comes from its deeply internalized global layout. Over 100 parts production bases overseas, over 3,000 dealer networks, 4 overseas production centers, and Anji Logistics with 42 own roll-on roll-off ships. Most of these assets were not formed suddenly in the past two or three years, but the result of continuous investment over the past ten years or even twenty years.
And from the brand side, MG won the Chinese brand sales champion in Europe continuously for 11 years. In 2025, annual sales in Europe broke 300,000 units. In March 2026, MG released SolidCore semi-solid-state battery and Hybrid+ hybrid technology at Frankfurt, marking that SAIC's globalization logic switched from "product going global" to "technology and value chain output". Without over ten years of local operation accumulation, this switch cannot be accomplished.
In addition, the 100 millionth user SAIC chose is just its current most dazzling supply chain partner Momenta CEO Cao Xudong. Giving the milestone user role to the founder of a intelligence driving technology company, the signal SAIC wants to convey is very clear, that is, SAIC does not understand "User" narrowly as consumers, but includes ecosystem partners together into the user ecosystem.
And this posture can also be seen as a continuation of the Shanghai-style cooperation culture foundation established by SAIC since the Santana localization community period: Open, Co-creation, Mutual Foundation.In the current industry more inclined to "Vertical Integration" and "Full-Stack Self-Research", SAIC chose to take down the technology walls, letting partners become part of the community. Alone you go fast, together you go far. The truth of this seems to become even more weighty on this 100 million milestone commemoration.
Final Thoughts:
In this milestone event that can be called a grand event of Chinese automotive industry, the 100 million new car delivery achieved by SAIC, although it is a specific number, but the meaning it possesses in the entire industry cannot be summarized by a specific measurement.
And behind the achievement of delivering 100 million new cars, SAIC, like other Chinese automotive enterprises, is also facing new questions. In new competition dimensions, whether able to mobilize full categories, whether able to cross passenger and commercial, whether able to integrate domestic and overseas, whether able to let joint venture and independent coordinate under the same roof, will become a new ruler to measure car companies' real strength.
For SAIC itself, delivering the 100 millionth new car is just a stage answer, and also a new starting line. The market after 2026 will not be exceptionally tolerant of it because of this number, but for SAIC itself, it also does not need "special treatment", but strives to prove through this ceremony, this Chinese automotive leading enterprise that has walked for over 70 years, still maintains the strategic determination of open cooperation, and still has the practical ability to transform strategic intent into industrial action.

車型概覽

東風Nammi Box 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講整體購車判斷,幫你用買家角度篩走唔適合嘅選擇。
HK$ 148,000 / HK$ 168,000 令預算位置更清楚,買家可以先估算月供、保險、泊車同日常開支。
購車價格指南
東風Nammi Box 嘅購車預算可以先由 HK$ 148,000 / HK$ 168,000 開始計。香港買車唔只係睇車價,月供、保險、牌費、泊車同能源成本都會影響每月壓力。
如果有幾個版本可揀,可以先將 2026 330km Standard(HK$ 148,000)、2026 430km Pro(HK$ 168,000)、2025 430km Pro(價格待確認)、2025 330km Standard(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 東風Nammi Box 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
31.4/42.3 kWh 嘅電池容量,真正意義係可以幫你估算一星期通勤同周末出車要唔要中途補電。 330/430 km 嘅續航參考,對住喺新界、九龍同港島之間跨區行車嘅用家會更實際。 70 kW、160 N·m 嘅輸出,令高速併線同短距離超車更有信心。 車長 4030 mm、車闊 1810 mm、車高 1570 mm、軸距 2660 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。
優缺點分析
東風Nammi Box 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:預算位置清楚,方便同同級車直接比較、電池同續航資訊有助安排通勤同補電、動力輸出對高速同上斜更有底氣。
要留意嘅係,要先確認屋苑、公司或常去商場嘅充電條件、香港停車場同窄路使用要留意車身闊度。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 東風Nammi Box 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「東風 Nammi Box 的車身尺寸適唔適合香港狹窄街道?」簡單講,東風 Nammi Box 車身小巧靈活,極適合香港狹窄街道與迷你車位停泊。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 東風Nammi Box 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先用 HK$ 148,000 / HK$ 168,000 鎖定預算圈、再睇動力係咪足夠應付高速併線同滿載、再比較能源成本同補能便利、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南

擁有 東風Nammi Box 最重要係先諗清楚充電節奏。屋苑、公司或者常去商場只要有穩定充電選項,電動化用車就會容易相處好多。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

車型概覽

寶馬M4 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講整體購車判斷,幫你用買家角度篩走唔適合嘅選擇。
零售價 HK$ 875,431 - 896,983、完稅價 HK$ 1,799,000 - 1,849,000 令預算位置更清楚,買家可以先估算月供、保險、泊車同日常開支。
購車價格指南
寶馬M4 嘅購車預算可以先由 零售價 HK$ 875,431 - 896,983、完稅價 HK$ 1,799,000 - 1,849,000 開始計。香港買車唔只係睇車價,月供、保險、牌費、泊車同能源成本都會影響每月壓力。
如果有幾個版本可揀,可以先將 2025 M4 Coupé M xDrive Competition(HK$ 1,799,000)、2025 M4 Convertible M xDrive Competition(HK$ 1,849,000) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 寶馬M4 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
寶馬M4 現階段最值得留意係車型定位同版本方向,詳細取捨應該等價格同規格更清楚再作決定。
優缺點分析
寶馬M4 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:預算位置清楚,方便同同級車直接比較。
要留意嘅係,最終取捨會落喺版本配置、保險同長期保養成本。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 寶馬M4 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「寶馬 BMW M4 Competition 喺香港賣幾多錢?」簡單講,現時 寶馬 BMW M4 Competition (G82) 喺香港售價大約由港幣 $1,780,000 起。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 寶馬M4 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先用 零售價 HK$ 875,431 - 896,983、完稅價 HK$ 1,799,000 - 1,849,000 鎖定預算圈。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南

擁有 寶馬M4 唔係買車一刻就完結,之後仲有保險、輪胎、保養、泊車同日常能源成本要處理。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

車型概覽

Subaru Solterra 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講續航、電池同補電安排,幫你用買家角度篩走唔適合嘅選擇。
零售價 HK$ 289,900 - 302,047、完稅價 HK$ 479,214 - 502,400 令預算位置更清楚,買家可以先估算月供、保險、泊車同日常開支。
購車價格指南
Subaru Solterra 嘅購車預算可以先由 零售價 HK$ 289,900 - 302,047、完稅價 HK$ 479,214 - 502,400 開始計。香港買車唔只係睇車價,月供、保險、牌費、泊車同能源成本都會影響每月壓力。
如果有幾個版本可揀,可以先將 2026 436km XT(HK$ 502,400)、2025 465km Standard(HK$ 479,214) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 Subaru Solterra 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
73.1/71.4 kWh 嘅電池容量,真正意義係可以幫你估算一星期通勤同周末出車要唔要中途補電。 255/160 kW、437/336 N·m 嘅輸出,令高速併線同短距離超車更有信心。 車長 4690 mm、車闊 1860 mm、車高 1650 mm、軸距 2850 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。 固定齒比、雙電機四駆 會影響起步順滑度、濕地穩定感同長途巡航性格。
優缺點分析
Subaru Solterra 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:預算位置清楚,方便同同級車直接比較、電池同續航資訊有助安排通勤同補電、動力輸出對高速同上斜更有底氣。
要留意嘅係,要先確認屋苑、公司或常去商場嘅充電條件、香港停車場同窄路使用要留意車身闊度。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 Subaru Solterra 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「Subaru Solterra 喺香港有咩動力配置?」簡單講,Subaru Solterra 喺香港提供雙馬達四驅版本,搭載 71.4kWh 鋰電池,前後軸各有一個 eAxle 永磁同步摩打,輸出 215 匹馬力及 34.2kgm 扭力,0-100km/h 加速只需 6.9 秒。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 Subaru Solterra 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先用 零售價 HK$ 289,900 - 302,047、完稅價 HK$ 479,214 - 502,400 鎖定預算圈、再睇動力係咪足夠應付高速併線同滿載、再比較能源成本同補能便利、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南

擁有 Subaru Solterra 最重要係先諗清楚充電節奏。屋苑、公司或者常去商場只要有穩定充電選項,電動化用車就會容易相處好多。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。


In May 2026, Daniel Craig, the former 007 actor who occupies a special place in the hearts of film fans worldwide, drove the Denza Z9 GT in an ad campaign that sparked heated discussion abroad, vividly interpreting the slogan "Technology Drives Elegance".

Even more stunning was the hammer strike of a unique crossover customized vehicle at the Cannes amfAR Charity Gala, the globally unique Denza Z9GT Chopard Edition, which was sold for 700,000 euros (approximately 5.55 million yuan).
When Chinese cars begin to define "elegance" and "scarcity", shouldn't the world update its mindset as well?
At the same time, another piece of news was more influential.

Not long ago, Kantar BrandZ released the global brand value ranking: BYD ranked fifth globally among automotive brands with a brand value of 20.362 billion USD, spiking 41% year-on-year, with the fastest growth for two consecutive years, just a step away from fourth-place Mercedes-Benz.
From the elegance of 007 to the hammer strike at Cannes, and then to the dazzling data of BrandZ, a series of "Global Moments" connected together, outlining a new landscape of the automotive industry led by Chinese brands.
Past: The Sower: That Underrated Decade
The narrative of BYD's "Global Time" must begin with a long decade of sowing.

Time returns to the 2010s, when the industry generally believed that Chinese cars could only fight price wars domestically, but BYD K9 electric buses drove into London, Paris, and Tokyo. It not only obtained strict European entry certifications but also was the first to enter the Japanese market. K9, which became the first global business card for China's new energy vehicles.
Diligence in technology would later evolve into a series of "Global Safety Stories" that went viral.

In 2026, in Jerusalem, a Yuan PLUS encountered a missile attack, the entire vehicle was overturned, the windows shattered, but the A, B, and C pillars were intact, the battery system did not experience thermal runaway, and the 5 people inside safely escaped.
In another incident, a Song PLUS DM-i belonging to a Brazilian owner was shot at by bandits with firearms, bullets failed to penetrate the car body, the driver escaped safely, and later remarked on social media: "It was BYD that saved my life."
"Safety is the ultimate luxury". BYD turned a series of deadly and real battlefield crises into a creed that wins the heart of the whole world.

The accumulation of technology was finally reflected in a full explosion in sales. In 2023, BYD surpassed Tesla to win the global new energy vehicle sales championship for the first time. In April 2026, BYD's 16 millionth new energy vehicle came off the line, from 10 million to 16 million took only 17 months.
The running speed of China's automotive industry on the global racecourse has never been so amazing. But on the world map, what BYD sowed earlier was not just products.
In 2021, BYD's first Southeast Asia factory started production in Thailand; in 2023, the Camaçari, Brazil factory was reborn; in 2025, the Hungary factory rose in Europe. Every move laid solid support for the explosion of the overseas market in the next few years.
Present: 2026, the year of global coronation
In April 2026, the global car market welcomed a historic moment. BYD topped the sales chart for all categories in Brazilian automotive retail with monthly retail sales of 14,911 units and a market share of 12.8%. Volkswagen's 20-year rule in Brazil was ended. Brazilian President Lula also became a BYD owner.

At the same time, the European battlefield was unstoppable. In Italy, BYD surpassed Volkswagen and Tesla to take the top spot in the sub-segment for the first time; in Germany, sales volume grew by more than 647% year-on-year; in the UK and Spain, year-on-year growth exceeded 600%. The Hungary factory is fully operational, with an annual capacity of 150,000 units, becoming the largest Chinese car factory in Europe.

In Southeast Asia, for every 3 pure electric vehicles sold in Thailand, at least 1 is from BYD. The Thailand factory has an annual capacity of 150,000 units, and through the ASEAN internal zero-tariff circulation system, the product touch extends to the entire Southeast Asia region.

Looking globally, in April 2026, BYD overseas sales reached 134,500 units, a year-on-year growth of 70.9%, setting a new record. Cumulative overseas sales from January to April reached 454,300 units, and overseas sales have accounted for more than 40% of the group's total sales. Penetration, scale, growth rate — all three mastered.
Brand Transformation: From Crazy Boasts to a Reality to Be Admired
Once upon a time, many people's impression of BYD stayed on "low-end" and "cheap". Do you remember in 2007, Wang Chuanfu once declared "will be No. 1 globally by 2025", when the audience was full of laughter. But when BYD surpassed Tesla in 2023 to become the global new energy vehicle sales champion, that seemingly crazy boast has been fulfilled ahead of schedule.

When Yangwang U9 Xtreme broke the global mass-produced car speed record with an actual measured top speed of 496.22 km/h, ran 6 minutes 59 seconds on the Nürburgring to become the first pure electric mass-produced vehicle to break the 7-minute mark, with a selling price of over 20 million and truly delivered to users, people's cognition underwent a thorough turnaround. Chinese cars have finally gained pricing power in the supercar field for the first time.
At the same time, the 5th Generation DM hybrid system was further evolved, with NEDC low-battery fuel consumption per 100km dropping to 2.6 liters, a full tank and full battery combined range of 2,100 kilometers, achieving "a tank of fuel from Beijing straight to Shenzhen".

The 2nd Generation Blade Battery and Flash Charge technology launched in March 2026 dropped a bombshell in the recharging link. Wang Chuanfu boldly declared on the spot: "5 minutes to full charge, 9 minutes to full, plus only 3 minutes at minus 30 degrees."

The leap in brand value is the most direct evidence. From appearing on the BrandZ Global Automotive list for the first time in 2022 ranked eighth, to reaching fifth place in 2026, BYD has used four years to grow from a "newcomer" to a core role in the global automotive brand camp.
Conclusion
Brand, Performance, Market, Cultural Premium — BYD is rewriting the landscape of the global automotive industry simultaneously on four dimensions. Boundaries between traditional and non-traditional are dissolving, ecological niches of innovators and vested interests are being reshaped.

In the pinnacle showdown of this "King of Industries", no Chinese enterprise has ever walked so deeply and so confidently.
In the past, the world saw BYD; now, the world chooses BYD; in the future, the world will watch BYD together.
This is BYD's Global Time.