首頁Ford Escort RS

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。

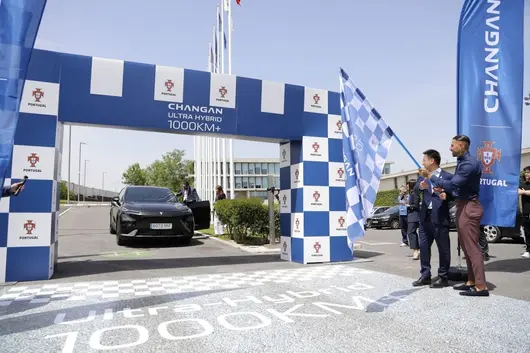
On May 22, Deepal Auto announced in Lisbon, the capital of Portugal, that it has officially become the global official partner of the Portuguese national team. On site, Deepal Auto delivered its compact pure electric SUV Deepal S05 to the team and simultaneously launched a 1000-kilometer European long-distance test for the model.

According to official information, the Deepal S05 recently won the April compact SUV sales championship in the domestic market and topped the compact pure electric SUV registration for two consecutive months in Spain. The vehicle also won first place in the J.D. Power 2026 China New Energy Vehicle New Car Quality Research Compact Pure Electric SUV category and the German iF Design Award.

Deepal Auto stated that its cumulative global deliveries have surpassed 800,000 units. Regarding technology, the company holds patents such as Hyper Integrated Electric Drive and Golden Bell Battery, and claims to achieve "million-level electric drive zero overheating" and "battery zero spontaneous combustion" records. In addition, Deepal Auto received the first domestic L3-level autonomous driving test license plate.

As part of Changan Auto's "Open and Inclusive" overseas expansion plan, Deepal Auto has currently entered five major regions and about 100 countries and regions. The Deepal S05 has started production at the Thailand factory, while the Deepal S07 has received dual five-star safety ratings in Europe and Australia.
This collaboration with the Portuguese national team is regarded by Deepal Auto as a key step to accelerate the European market layout. In the future, the brand will continue to promote the transformation from product export to brand and industrial chain output.

國際能源局勢持續波動,油價不斷走高,令歐洲人開始接受電動汽車,亦令中國新能源汽車品牌在歐洲見到新希望。據外媒報道,2026 年 4 月中國車企在歐洲市場整體銷量同比大增 114%,上汽集團、比亞迪和奇瑞成為大贏家。
產品熱銷同時,面對歐盟貿易壁壘與全球產能過剩現狀,中國頭部新老車企亦正在加速佈局海外生產基地,透過收購、改造歐美傳統車企閒置產能落地本地化生產。
從出口到銷售再到生產,中國新能源汽車品牌出海正在加速進階,有望進入改寫歐洲汽車產業格局的全新階段。
上汽穩、奇瑞猛,中國汽車在歐洲大賣
2026 年 5 月 22 日,歐洲汽車媒體援引當地市場研究機構 Dataforce 最新數據,4 月歐洲新車整體銷量持續復甦,同比增長 6.4%,區域車市整體保持穩步復甦態勢。
由於中東地區持續衝突,歐洲油價自 2026 年以來已上漲約 20%,因此,新能源車型成為拉動歐洲車市 4 月份增長的核心驅動力。其中,純電動汽車表現最為突出,4 月銷量同比增長 38%,創下 2026 年以來最高單月增速;插電式混動車型銷量增長 21%,油電混動車型銷量增幅亦達到 15%。
歐洲汽車用戶加速轉向新能源汽車,同樣為中國汽車品牌加速擴大歐洲市場銷量創造了絕佳增長契機。

數據顯示,2026 年 4 月中國車企在歐洲市場整體銷量翻番,同比大增 114%。其中,上汽集團 4 月份銷量為 30074 輛,穩居中國車企銷量榜首,比亞迪單月銷量為 28186 輛排名第二,奇瑞 4 月份銷量為 25656 輛,位列第三。從單月表現看,三家中國車企在歐洲市場的銷量差距亦在持續縮小。
在銷量增速方面,4 月歐洲車市增速榜單幾乎被中國品牌霸榜,零跑汽車增速高達 423%,奇瑞、比亞迪分別以 344%、125% 的同比增速緊隨其後,整體增長勢頭強勁。
其中,奇瑞則成為 4 月歐洲市場增長爆發力最猛的中國車企,相比 2025 年 4 月,奇瑞銷量增加接近 2 萬輛。Dataforce 數據顯示,奇瑞品牌 2025 年 4 月在歐洲銷量僅有 4 輛,今年 4 月已達到 5446 輛;此外,奇瑞旗下 Omoda、Jaecoo 兩個子品牌均同步發力,悉數躋身歐洲市場銷量增幅前列,其中 Omoda 增速位列歐洲第三,Jaecoo 位居第六。終端市場的表現說明,奇瑞在歐洲的佈局已進入全面發力階段。
因為與中國品牌的高速增長形成鮮明反差的是,部分歐洲本土車企及傳統汽車巨頭在 4 月遭遇銷量下滑。比如,豐田同比微跌 1%,雷諾下滑 3%,福特下跌 11%,現代降幅達 12%,高端品牌保時捷竟然也同比下滑達到 17%,三菱跌幅最為突出,達到 51%。
與中國車企零跑、東風保持密切關係的歐洲本土巨頭 Stellantis,4 月銷量雖實現 4.3% 的同比增長,但增速低於歐洲車市整體表現。該集團內部品牌表現分化顯著,零跑、菲亞特、歐寶 / 沃克斯豪爾、雪鐵龍保持銷量正增長,而寶獅、阿爾法·羅密歐則出現明顯銷量回落。
如果中國新能源汽車新老品牌能夠延續這股上升勢頭,將有望重塑歐洲市場競爭格局。
中國車企瘋狂「買買買」,但仍要過工會關
一方面,油價上漲、新能源汽車市場轉型等多重因素疊加,導致傳統汽車巨頭在歐洲市場銷量疲軟。另一方面燃油車時代遺留的製造體系亦正逐步陷入閒置或產能過剩的困境。
有諮詢機構預判,歐美大量低利用率汽車工廠未來將面臨關停或轉讓,而歐盟針對中國電動車加徵進口關稅的舉措,則進一步推動中國車企加速佈局歐洲本地化生產。
在這樣的背景下,承接、改造傳統車企工廠,已成為不少中國車企佈局海外本地化生產的核心方式。這一現象亦引發外媒關注,近日有歐洲汽車媒體就爆料稱,比亞迪正與 Stellantis 及其他歐洲車企洽談接管該地區閒置工廠。實際上,比亞迪早在 2023 年底就已宣布在匈牙利建廠,成為首個在歐盟自建乘用車工廠的中國車企。
比亞迪匈牙利工廠規劃年產能 30 萬輛,2025 年比亞迪在歐洲市場的銷量已超過 18.7 萬輛,比 2024 年同比增長超 260%。按照增速來預測,比亞迪僅靠一座匈牙利工廠將難以滿足在歐洲的汽車銷售需求,因此傳出與本土車企洽談購廠合情合理。
對歐洲市場充滿進取心的中國車企不止比亞迪。僅 2026 年 5 月一個月,就已傳出多個中國車企洽談歐洲產能合作項目的消息。比如,5 月 20 日,Stellantis 集團官宣與東風集團展開合作洽談,計劃依托法國雷恩工廠實現東風新能源車型的本地化生產。此外,零跑汽車亦透露,與 Stellantis 合資成立的零跑國際,有望收購 Stellantis 位於西班牙馬德里的工廠,快速搭建歐洲本土生產基地。
還有消息稱,吉利亦正積極推進收購福特西班牙瓦倫西亞工廠部分裝配產線;小鵬亦被曝出與大眾集團洽談,尋求收購其歐洲閒置產能。還有奇瑞與西班牙 Ebro 集團合作盤活前日產舊工廠,目前已恢復生產,奇瑞車型即將導入落地。
接手改造歐洲車企閒置產能,好處係能夠避免行業重複建設,增加歐洲當地就業機會,符合產業政策導向,同時亦能夠比完全自建工廠更節省時間提升效率。
然而,需要給中國車企提個醒係,買買買並不代表一勞永逸,背後同樣暗藏極大風險。

同樣在近日,在傳出大眾汽車集團與小鵬汽車洽談閒置產能出售消息後,大眾汽車集團工會負責人丹妮拉·卡瓦洛卡瓦洛(Daniela Cavallo)當著數萬名工人的面,炮轟集團管理層,並且強烈反對管理層與中國車企等第三方磋商讓出閒置產能。
在此壓力下,大眾汽車集團的 CEO 奧博穆(Oliver Blume)則公開表示,目前,大眾沒有與中國製造商進行任何關於使用歐洲工廠產能的談判,未來也完全沒有相關的合作計劃。
相比東南亞、中東、非洲等新興市場對中國車企的高包容度,成熟的歐洲汽車市場法規、工會、環保、就業承諾等約束條件更為嚴苛,中國車企透過收購工廠的方式落地本土化,除了要改造產線、適配供應鏈之外,更需適配當地規則、適配當地文化才能更好地生存。
當然,自建工廠可完全貼合車企自身製造標準、供應鏈體系與生產理念,自主可控性更強,但亦這更適合資金充裕、佈局節奏可控的車企去長期佈局。從這個層面來說,目前比亞迪在歐洲的產能佈局更符合長期 + 短期的配合,全球範圍內,比亞迪除了在各大主要市場洽談符合條件的舊工廠加以改造之外,已在泰國、匈牙利、土耳其等地落地至少 4 座自建整車工廠。
歐洲新能源汽車銷量大幅提升,給渴望出海的中國車企帶來發展契機,然而歐洲對中國車企收購工廠的複雜情緒,又令中國車企的歐洲之路困難重重。實際上,中國車企主導的本輪全球汽車產能重組,反映出新能源汽車時代行業話語權的結構性轉移。
燃油車時代,歐美日韓車企主導著全球汽車技術路線、產能配置與產業規則,在智能電動化浪潮下,憑藉完整的新能源供應鏈、成熟的三電與智能化技術、高效的產能體系,中國車企正在從產品出口升級為產能、技術、標準的全方位出海,有望重塑歐洲乃至全球的汽車產業格局。
(消息來源:autonews.com,reuters.com,bloomberg.com)
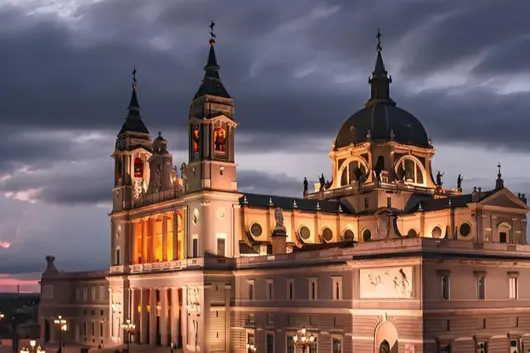
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
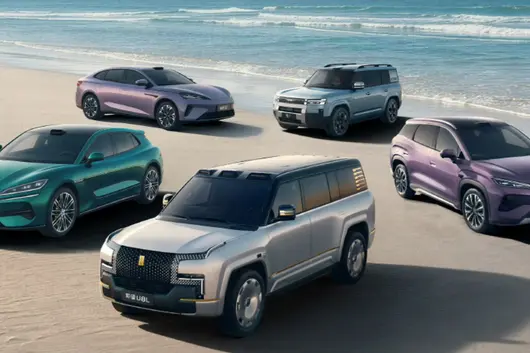
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.

The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.

Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.

The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.

Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.

In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.
更舒適、更從容🟰更多人嘅選擇
中國智造🦾開往全球🌏