首頁Automakers

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

Author | Hao Wen
Editor | Qujie Business News Group
In this round of car manufacturers developing batteries in-house, what might be rewritten is not just the supplier list, but also CATL's profit model relying on a complete battery system to obtain premiums.
On the evening of September 18, after the Xpeng G9L launch event, Xpeng founder He Xiaopeng stated in response to media inquiries about whether they would develop batteries in-house, "Starting this year, Xpeng will handle batteries entirely in-house;" previously, Li Auto also announced that self-developed batteries will gradually cover all models.
Car manufacturers' accelerated commitment to developing batteries quickly formed a response in the capital market. On September 18, CATL's A-share closed at 301.95 yuan/share, a drop of more than 35% from the year's high of 467.34 yuan on May 7. The HK share closed at 507 HKD/share, a new intraday low since March 10. The total market capitalization of A+H shares evaporated by more than 700 billion yuan from the peak.

Image Source: Baidu Screenshot
The market generally views car manufacturers developing batteries in-house as two things: saving costs and ensuring supply. But the changes happening in the industry are far more than just replacing suppliers. Car manufacturers are seeking to regain product definition rights over batteries. CATL's past profit path relying on complete battery system solutions to obtain premiums is being impacted, and the original business model is facing structural adjustments.
1. Definition Rights Shift Down, Manufacturing Rights Remain CentralFirst, clearly see what car manufacturers are actually doing. They are not fully building battery cell factories themselves, but are keeping product definition rights such as battery formulas, fast-charging logic, BMS strategies, and vehicle integration standards in their own hands, while handing over the battery cell manufacturing process to battery suppliers.
For example, Xiaomi's "Longjia Battery" involves Xiaomi responsible for product definition and battery pack design and development, with CALB and Sunwoda customizing battery cells according to Xiaomi standards; Li Auto's battery self-research involves self-developed and self-made battery packs, with cells produced by Sunwoda and CALB; Xpeng has taken back the entire battery pack chain, retaining only the procurement of battery cells.
This exactly hits CATL's core source of high gross margins. In the past, it delivered a complete set of "battery solutions + exclusive designated supply", obtaining technology, system solutions, and pricing dividends from exclusive supply in one order. Nowadays, car manufacturers hold formulas, structures, vehicle integration, and other links in their own hands, only purchasing customized battery cells from battery manufacturers. CATL's business space for obtaining premiums relying on complete battery packs is facing obvious squeezing.
Changes are also reflected in financial report data. In the first half of 2026, CATL's largest revenue source - power battery system gross margin dropped to 20.63%, a year-on-year decline of 1.78 percentage points.

Image Source: Semi-Annual Report Screenshot
The rising logic of second-tier battery factories has also become clear. In addition to their own technology iterations, the key lies in being willing to adapt to car manufacturers' product definitions and undertake deep customization development. Li Auto injected 2.65 billion yuan to increase capital in Sunwoda, becoming its second-largest shareholder. CALB has also grown into Xpeng's main supplier. Under the current industry chain pattern, manufacturers capable of implementing car manufacturer customized battery cell solutions are expected to capture the incremental share released by CATL.
2. "Know How to Build Cars, Not Necessarily How to Build Batteries"Car manufacturers regaining definition rights is essentially a redistribution of profits.
In the past few years, profits in the new energy vehicle industry chain have concentrated heavily on the battery segment. In the first half of 2026, CATL's net profit attributable to parent company was 43.284 billion yuan, while according to statistics, the combined net profit of 15 mainstream listed car manufacturers such as BYD, SAIC, Geely, Chery, etc., was 21.048 billion yuan, less than half of CATL alone. As early as 2022, GAC Group's then Chairman Zeng Qinghong openly complained: "Batteries account for 60% of the vehicle cost, aren't I just working for CATL?"

Image Source: Semi-Annual Report Screenshot
In this round, car manufacturers developing batteries in-house combined with multiple suppliers running in parallel, the goal is to squeeze excess profits in the battery segment and promote profits to flow back to the vehicle end. The lithium battery industry may return from past phased high returns to a relatively fair profit level of manufacturing.
But inferring "CATL will be replaced" based on this is still premature. Car manufacturers' battery self-research has a natural ceiling. He Xiaopeng explicitly stated in an interview that Xpeng does not intend to enter the production of battery cells itself; investing in battery cells is ultimately for others.
Car manufacturers are good at vehicle product definition and system integration, but face high thresholds in yield, consistency, and cost control of mass production of battery cells; battery cell manufacturing belongs to capital-intensive industries, only sufficient scale can dilute costs. Once sales fluctuate, capital-intensive capacity will drag down the car manufacturer's balance sheet. CATL's Chief Manufacturing Officer Ni Jun once openly stated: "Knowing how to build cars doesn't mean knowing how to build batteries, professionals should do professional things."
Definition rights can be contested, but barriers to mass production are difficult to migrate quickly. In the first half of this year, CATL's battery system capacity utilization rate reached 94.86%, with 764 GWh of capacity under construction; the German plant has already achieved profitability, and bases in Hungary, Spain, and Indonesia are landing successively. According to data released by Korean market research firm SNE Research, from January to May 2026, CATL's global power battery market share broke through 40% for the first time, reaching 40.2%.

Image Source: Semi-Annual Report Screenshot
CATL has even started to fight back for definition rights. It launched the 75# standardized battery swapping block for heavy trucks, laid out passenger car integrated smart chassis, packaged "battery + chassis" into a standardized solution that vehicle manufacturers can procure, trying to turn itself back into the "person who sets standards". On high-end models above 300,000 yuan, Qilin and Shenxing supercharging remain the mainstream technical solutions in terms of performance and safety. Although car manufacturers generally introduce second and third suppliers and carry out diversified supply chain layouts, for main-selling high-end flagship models, most will still keep CATL in the supplier list.
Therefore, the industry is unlikely to move towards simple substitution. In the domestic power battery track, a two-way check and balance pattern is more likely to form: car manufacturers strive for product definition rights, promoting more industry chain profits to flow back to the vehicle end; CATL guards the core capabilities of high-end manufacturing.
However, challenges still objectively exist. If more high-end models deeply dominate battery definitions later, the product performance advantages of leading battery enterprises gradually turn into industry general capabilities, and CATL's existing product premiums still have the possibility of being continuously compressed.
Facing the gaming pressure of the domestic market, CATL has not bet all its chips on domestic car manufacturers' power battery businesses. Overseas markets and energy storage businesses have become important growth pillars. In the first half of the year, the energy storage business achieved revenue of 53.261 billion yuan, a year-on-year increase of 87.54%; overseas revenue was 87.129 billion yuan, a year-on-year increase of 42.35%, with overseas business gross margin at 29.97%, significantly higher than the domestic business's 21.16%.
For CATL, the real risk does not lie in being completely replaced by car manufacturers, but in whether it can adapt to the gross margin in the domestic market that is tending to thin out, relying on manufacturing advantages, global layout, and energy storage business to continuously obtain reasonable returns.
Since 2026, the Chinese automotive market has seen a dense launch of new vehicles, with hundreds of new models flooding in, drastically expanding consumer choice. However, as more new models emerge, the industry needs to answer a core question: after the initial launch buzz fades, can sales sustain? Compared to short-term explosions, sustained high sales are becoming a more important benchmark for product quality.

Under this benchmark, SAIC's MG4, MG 07, Shangjie Z7/Z7T, Huajing S and other intelligent new energy products have seen hot sales spanning launch and steady periods, forming more valuable hit samples: MG4 sold 150,000 units in the first year after launch, achieving steady monthly sales exceeding 10,000 for 11 consecutive months; MG 07 locked 42,000 orders in 20 days after launch; Shangjie Z7/Z7T delivered over 20,000 units in two months, topping the reputation of mid-to-large pure electric coupes with top Net Promoter Score (NPS); Huajing S had monthly sales increase for four consecutive months, with cumulative delivery of 25,000 units, ranking first tier in NPS for new energy SUVs within 250,000 yuan.
These products belong to different brands, categories, and price points, yet share the same methodology: demand-oriented, seeking blue oceans in the red ocean. Breaking it down, this methodology has one premise and three pillars—the premise is mastering core technologies, the pillars are Parts and Assembly Integration, Scaling, and Internationalization.
Core Technology: The Premise of Accurately Understanding User Needs
The underlying logic of tech inclusivity is to make leading technology available to a wider audience at a more sincere price.
SAIC's confidence comes from nearly 190 billion yuan of R&D investment and over 24,000 valid patents in electrification and intelligence over the past decade. This formed a technical foundation of "Smart Brain, Robust Body, Powerful Heart", with a batch of core technologies gradually commercialized, building a solid moat: Semi-solid-state batteries achieved mass production and vehicle integration first, DMH hybrid thermal efficiency reached 46.3%, wire-controlled chassis saw mass production application first, and it holds passenger/commercial vehicle
L4 dual licenses.

Thanks to these reserves, inclusivity is not a slogan, but a list of items that can be redeemed: 60,000-level Roewe i6 standard equipped with 8155 chip and DouBao Large Model; 90,000-level MG4X fully standard equipped with semi-solid-state batteries and rear-drive five-link suspension; 150,000-level market MG 07 brings 800V high-voltage platform, 5C supercharging, 845km range and Momenta R7 advanced intelligent driving into the mix; Jiayue 07 brings AI-native cockpits into the mainstream family SUV market; 200,000-level market, new generation IM L6 standard equipped with SAIC new generation NEO three-electric architecture, full wire-controlled chassis, IM Claw Lobster Intelligent Agent, allowing users to enjoy next-gen tech for the next three years first; Shangjie Z7/Z7T series standard equipped with Huawei Qiankun Intelligent Driving and 896-line LiDAR, bringing "entry-level full-spec" intelligent travel experience to users.

Precise understanding of user needs and usage scenarios is the premise for tech inclusivity and precise product definition. Taking Shangjie Z7/Z7T as an example, according to the first batch of user surveys by Jielan Road, Shangjie Z7 series owners show a younger, highly educated characteristic, mainly urban young users, with female users accounting for 42.3%, far higher than the industry average. Among them, Z7 attracts younger unmarried female users more, being urban players who like fitness, parties, and urban socializing; Z7T is more favored by urban high-knowledge families, owners are keen on traveling, camping, fishing and climbing, shooting brake styling, large space and car fridge therefore accommodate a larger travel radius. Huajing S then understood another group: nearly nine out of ten first batch of owners are families with children, six out of ten come from joint venture replacement, they need not fresh gimmicks, but large six-seat space, full-series Huawei Qiankun Intelligent Driving and "Certainty" within budget. Product definition precision determines sales duration.
Parts and Assembly Integration: Realizing User Needs through Industry Chain Collaboration
After precise insight into needs, how to realize at scale quickly? SAIC's answer is the vertically integrated full industry chain system established over more than 70 years.
Relying on industry-leading parts companies within the system such as Huayu, Yanfeng, Qingtao, SAIC Passenger Vehicles and Parts System established a Parts and Assembly integration relationship with pre-binding and joint development. Suppliers are deeply bound in the early project stage, jointly defining products and user needs, jointly assessing competitiveness, jointly optimizing design and cost. This is the first cornerstone of SAIC's hit methodology and also the advantage of traditional automakers that is hardest to be replicated by new forces.

Collaboration radius also extends outward. Cooperation with Huawei made Qiankun Intelligent Driving and Harmony Cockpit standard equipment for all Shangjie and Huajing S models; Cooperation with Momenta is deeper, forming cross-shareholding and strategic embedding: SAIC is Momenta's largest institutional shareholder, Momenta cross-shareholds IM, data, scenarios and R&D rhythm kept in sync. More importantly, Momenta advanced intelligent driving solution has landed on Roewe, MG, Volkswagen, AUDI, Buick, Cadillac and other independent and joint venture brands, forming cross-brand, cross-system scaled application. For SAIC system brands, this collaboration can accelerate intelligent technology mass production landing and form differentiated market competition advantage; For Momenta, the solution applied on multiple vehicle models can rapidly amplify scale, accelerate data closed loop, promote technology iteration, build technology moat, and improve revenue and profit levels, thereby forming a virtuous positive cycle. This "Capital + Industry + Data" mutual rush guarantees the most advanced driving models land on SAIC products first time in mass production.
The essence of Parts and Assembly Integration is to make the entire industry chain a demand translator: a user's complaint can be converted into the next OTA upgrade in the shortest path, or a standard spec on the next generation product.
Scaling: Making Tech Equity a Sustainable Business
Making high-spec into standard spec, the most easily attracting doubt lies in whether profit can keep up.

SAIC's solution is to make predictions at the million-level volume, let core modules be shared across models, use scale to dilute R&D and manufacturing costs, achieve high-spec price without removing specs. The same Momenta intelligent driving model, from IM to MG, Roewe, to Buick Zhijing, Volkswagen ID.ERA, Audi, as scale expands, cost amortization gets lower; The same semi-solid-state battery technology, from domestic MG4 family spread to overseas hybrid models, scale effect makes frontier technology quickly mass production application.
User reputation proves, business model established and healthy: 85% users chose Huajing S high-spec version, truly not low price that makes users pay, but value; Its new car NPS reached 86 points, reputation spread became the core driving sales four consecutive months increase. More importantly, tech inclusivity did not come at the cost of sacrificing business quality.

First half year, SAIC core net profit attributable to parent company increased by 72% YoY, gross margin improved 3 percentage points, operating cash flow net amount increased 158% dramatically. In the background of industry competition intensifying and domestic demand under pressure, this group of core business indicators outlines a steady and resilient enterprise. While high-spec becomes standard spec, SAIC business basic platform is also solid. This is an insurance given to tech equity by scaling: tech inclusivity is not a one-time price concession, but a sustainable business model.
Internationalization: Verifying and Feeding Back Product Iteration in Global Markets
Blue oceans not only domestic, SAIC also found breakthrough in overseas.
MG retained the China brand Europe sales champion for 11 consecutive years, Europe cumulative delivery exceeded 1 million vehicles; Jan-Aug SAIC overseas sales 1.016 million vehicles, YoY surged 52.9%. More important than numbers is the posture change: July, MG took Tech Conference to brand origin London, took concept cars to Goodwood Speed Festival, upgraded from selling cars overseas to "Walk in" of technology, capacity, service ecosystem, from product output upgraded to standard output.

1 million vehicle overseas scale, competing is no longer whether a single car can sell, but whether a system can run long-term. SAIC for this paved system network: Anji Logistics 42 self-operated RoRo ships, 8 international routes, Ocean year transport capacity 600,000 vehicles, hold transport power initiative in own hands; Thailand, Indonesia, India three vehicle manufacturing bases and Pakistan KD factory, plus Frankfurt Europe Engineering Center, three overseas R&D centers and three design centers, let R&D manufacturing capability close to local market; 3000+ overseas marketing service outlets and Indonesia financial service company, let sales, after-sales, finance land together. From selling to global to operating global, rely on this system behind support running.

Products to truly take root in local market, cannot do without local adaptation and development. SAIC for India market develop local voice assistant, for Brazil version MG ZS EV tropical climate specially optimize battery thermal management system. These details behind, is R&D system and market between distance shortened, also "Global + Local" Glocal 3.0 strategy most concrete appearance. Currently, SAIC formed Europe one 300,000 vehicle level and Americas, Middle East, Aus/NZ, ASEAN, South Asia five 50,000 vehicle level regional markets, products and services spread in 170+ countries and regions.
Internationalization to hit methodology feedback hidden and key: Global 170+ countries and regions complex road conditions, strict regulations and differentiated user needs, constitute strictest product verification field; Overseas cumulative sales exceeded 7 million vehicle user base, again for product definition provide larger sample demand insight. One car that can stand in European street, participate domestic market competition, naturally get extra calm.
From Understanding Cars to Understanding You: Redefining Value Standards
Looking back "SAIC Hit Methodology", logic closed loop clear: Frontier technology makes inclusivity possible, Parts-Assembly Integration makes needs land quickly, Scaling makes "Good quality and good price" sustainable, Internationalization makes products accept test in larger coordinate system, and all this starting point, is precise insight into user needs.
Past, automotive industry competition core is "Understand Car", make power, chassis, safety do to extreme; Today, decisive key is "Understand You better", make every frontier technology land as user perceivable good travel. Current frontier technology no longer just exclusive to million luxury cars, segmented market value standards are being redefined.

If shift gaze from one enterprise business performance to China Auto Industry overall leap, tech equity meaning truly appears. This May, SAIC became China's first cumulative production/sales exceeded 100 million vehicle auto group. 100 million vehicles behind, is 100 million real users to good travel longing and choice. SAIC through tech inclusivity answered a era proposition: Tech progress dividend, should belong to minority, or belong to more broad mainstream group? China Auto Industry used decades to walk from make car to make good car's road, now is answering third question—make good car everyone can enjoy affordably.
From Santana era market for technology, to take Tech Conference back to century-old auto brand origin, to today take semi-solid-state battery, wire-controlled chassis, advanced intelligent driving make mainstream market standard spec, China Auto role from technology follower became standard definers, with tech inclusivity reshape global competition pattern, just SAIC represented China brand's era mission and responsibility.
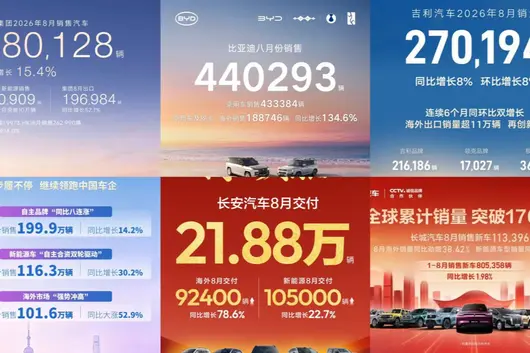
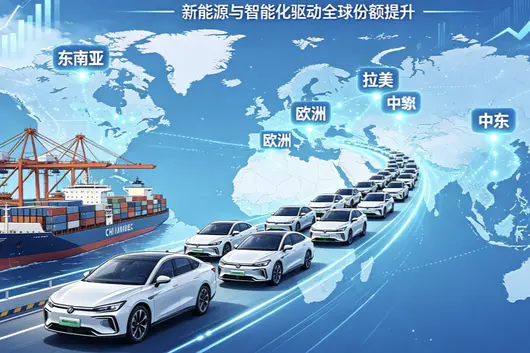
On September 1st, over a dozen mainstream domestic automakers successively announced their August sales reports. Judging from the data and the focus of each automaker's sales posters, a clear signal is emerging: the overseas market is upgrading from a former second battlefield to a main battlefield. Chinese automakers' global layout has finally turned from hardships to sweetness, entering a new phase of new-round "qualitative change".

Break out of the zero-sum game, overseas carries the banner of growth
Looking at sales data, in August, the signs of Chinese automakers breaking out of the domestic market's "zero-sum game" are becoming increasingly obvious.
Among them, Chery, known as the "Chinese Automaker Export Champion", stands out the most.
In August, Chery Group's total sales reached 280,000 vehicles, while the overseas market contributed 197,000 vehicles, a year-on-year increase of 52.1%. The export ratio once again exceeded 70%, meaning for every 10 cars sold, 7 were sold overseas. As of August, Chery's cumulative exports have exceeded 7 million vehicles, making it the first Chinese automaker to reach this milestone.
BYD's overseas sales are closing in on Chery. In August, BYD's total volume reached 440,000, making it the only automaker with monthly sales exceeding 400,000. The growth of the overseas market is the biggest driver. BYD's August overseas sales reached 188,700, a surge of 134.6% year-on-year, setting a new historical high for the brand's single-month overseas sales. In comparison, two years ago, BYD's overseas monthly sales basically hovered around just over 30,000 units.

Similar to BYD, Geely Automobile also created a new historical record again. In August, Geely Automobile's total sales were 270,000, with 110,000 overseas, a surge of 205% year-on-year. This is already Geely breaking through 100,000 for three consecutive months. Among these 110,000 units, new energy exports exceeded 70,000, quadrupling year-on-year, reaching 64% of the overseas exports.
Thanks to creating achievements in the overseas market repeatedly this year, Geely had previously adjusted its full-year overseas sales target from 640,000 to 920,000, and will strive for 1,000,000.
Except for the aforementioned automakers, SAIC Motor's August overseas sales reached 139,000, a year-on-year increase of 57.67%, accounting for nearly 40% of total sales. Changan Automobile's August overseas delivery was 92,400, a year-on-year increase of 78.6%, with overseas markets achieving year-on-year growth for seven consecutive months. Great Wall Motor's August overseas sales exceeded 60,000, a year-on-year increase of 38.42%, accounting for 55.1%...

Against the backdrop of increasingly fierce "zero-sum game" in the domestic market and increasingly weak terminal consumption, "export-driven" growth is becoming the most significant and commendable sales feature and highlight for mainstream automakers.
New Grip on Performance, System Layout "Hardships Turn to Sweetness"
More than sales figures, it is the performance that fills Chinese mainstream automakers with the fighting spirit of "setting sail overseas".
If sales are just the process, then performance is the result. The first-half financial report performance of multiple mainstream automakers has shown a historical reversal of revenue structure. Among them, BYD's overseas revenue exceeded domestic revenue for the first time in the first half of the year, with 181.268 billion yuan of overseas revenue accounting for 52.57% of the group's total revenue.
That is to say, the money BYD earned in the first half of the year came more from the overseas market. It is worth noting that although the overseas market failed to completely offset the domestic decline, due to higher pricing in the overseas market and relatively more stable prices, the higher profit space directly promoted the increase in BYD's net profit and gross margin.

Currently, with the continuous release of local overseas capacity and the continuous improvement of the channel system, BYD's overseas market is in a period of significant growth. That is to say, overseas will further become the key grip for BYD's performance growth.
Of course, driven by the combined high profits and scale growth in the overseas market, BYD is not the only one whose performance structure underwent a historical turn. Great Wall Motor's total revenue exceeded 100 billion in the first half of the year for the first time, with overseas market revenue accounting for 55.13% of total revenue, reaching 56.288 billion yuan. This is also the first time overseas revenue exceeded domestic revenue.
Regarding Chery, total revenue in the first half of the year was 143.28 billion yuan, with overseas revenue of 98.968 billion yuan, a year-on-year increase of 51.0%, accounting for a high 69.07% of total revenue. This ratio ranks first among mainstream Chinese automakers, and thanks to the high gross margin of overseas sales, Chery's overall gross margin in the first half of the year also saw an increase, with a net profit margin of 6.3% in the first half of the year.
Changan Automobile's revenue in the first half of the year was 65.634 billion yuan, with overseas revenue of 21.942 billion yuan, a year-on-year increase of 78.77%, with the proportion of total revenue rising to 33.43%, while overseas gross margin remained above 20%. Geely Automobile directly stated in the financial report meeting that the two core driving factors for performance growth in the first half of the year were premiumization and globalization.

Regarding new forces, Leapmotor's operating revenue in the first half of the year reached 38.11 billion yuan, of which the European market contributed 8.875 billion yuan... These data and cases continuously prove: the overseas market is not only a "second growth curve" for Chinese automakers, but also a substantial "performance engine". When scale expansion resonates with high gross margin, going overseas undoubtedly becomes a "must-answer question".
Gold Digging in Overseas Markets, But Challenges Remain
From the data, it is very clear that the overseas market is not only becoming a "hedging instrument" to counter the domestic downward cycle, but is also becoming a gold mine for Chinese automakers.
And this round of gold digging is not just about selling products out. The globalization of mainstream automakers such as Chery, BYD, Geely, Changan, and Great Wall has moved from the 1.0 era to the new stage of system overseas and ecological overseas of the 2.0 era. BYD factories in Thailand, Brazil, Hungary, and other places have been put into production successively; Geely accelerates the promotion of overseas localization projects such as Brazil and Spain; Chery plans to establish more than 10 production bases globally by 2025; Changan plans to expand Thailand factory capacity to 200,000 units...
These overseas factories are becoming the accelerator for Chinese automakers to impact global goals.
Of particular note, in this wave of going overseas, the proportion of new energy is getting higher. BYD exceeds 180,000 units, Geely's new energy export ratio reached 64%, Chery's new energy exports in August approached 40,000 units... And in terms of intelligence, XPeng Motors officially announced in August that it is advancing the global deployment of the second-generation VLA, planning to deliver the second-generation VLA to overseas users successively in the first half of next year.

Under the global wave of electrification transformation, the first-mover advantage of Chinese automakers in new energy and intelligence dimensions also determines that this round of going overseas for Chinese automakers not only has a first-mover advantage but also possesses sustainability.
The outlook is clear, but challenges also accompany it. The net profits of multiple automakers declined in the first half of the year, all mentioning exchange rate gains and losses. That is to say, when the proportion of overseas business changes from "supplement" to "half the landscape", exchange rate fluctuations are no longer an irrelevant detail in financial reports, but a systemic variable that directly affects the actual value of hundreds of billions in revenue.
The risk of exchange rate fluctuations also, to some extent, increases the uncertainty of automakers "gold digging". Besides exchange rate fluctuations, the huge investment in localization construction, financial expenses such as overseas brand building and marketing, will also bring considerable pressure to automakers' financial performance. How to build a stable and healthy input-output ratio will obviously become an inevitable thought for Chinese automakers in the globalization process.
Red Dot Observation:
Of course, no matter what, the data of August and the financial reports of the first half of the year point to a conclusion together: Chinese automakers are entering the "harvest period" of global layout. And within this harvest period, Chinese automakers are proving to the global market with a collective posture that Chinese automobiles have the strength and confidence to compete in the global market.
Officially singled out "frequent price cuts", warning against excessive price competition in overseas markets. Behind this lies not just the profit account, but the image account of China's automotive industry overseas.
Specifically regarding policy implementation, on September 1, 2026, the Ministry of Commerce, Ministry of Industry and Information Technology, and State Administration for Market Regulation jointly issued the "Guidelines for Overseas Competition Behavior and Compliance Construction in the Automotive Industry". The content regarding pricing is worth noting. The document points out that when enterprises formulate suggested retail prices overseas, they should set clear price gradients for different vehicle configurations, avoiding "affecting the interests and brand image of overseas consumers due to frequent and significant price fluctuations".
The "knock" meaning in this sentence is obvious, referring to the "price cut actions" that everyone is very familiar with in recent years. As for why the official needs to single out such behavior so seriously, perhaps we can see a clue from relevant data. Relevant data shows that in 2025, China's automobile exports reached 8.32 million units, sold to more than 200 countries and regions, and remained first in the world for consecutive years. In the first seven months of this year, the export volume reported by the General Administration of Customs reached 6.399 million units, a year-on-year increase of 53.7%, and breaking through 10 million units for the whole year seems to be inevitable.

The ceiling of scale is visibly rising, but the profit situation is like a bucket of cold water. According to Wind data, the total net profit attributable to owners of 289 listed automotive manufacturing companies in the first half of the year was 56.531 billion yuan, a year-on-year decrease of 25.74%, with the profit margin of complete vehicle manufacturing falling to 1.5%, a record low in nearly 10 years.
When the industry begins to show a situation where more sold means less earned, it indicates that something has deviated from the normal track. In other words, this is no longer a situation that can be explained by simple exchange rates and tariff factors. The three departments singled out "frequent price cuts", indicating that the official side has seen the bookkeeping problems; in essence, it is still a guide for the long-term survival of Chinese automakers overseas.
The "Profit Account" of Overseas Price Cuts, Calculated Clearly by Three Departments
The three departments singled out "frequent price cuts", most likely having calculated a financial account clearly, that is, sales volume and profits are moving further and further apart. Even BYD, a top representative with relatively thick profits among independent brands, also has such a situation. Let's look at a set of data. In the first half of 2026, BYD sold 789,400 units overseas, a year-on-year surge of 67.9%, and the proportion of overseas sales rose from about 24% year-on-year last year to 44%. According to Orient Securities' calculation, BYD's overseas business gross margin in the first half of the year was 28.4%, while domestic was only 17%. As a sample automaker going overseas, BYD's sales and profit calculation data are both quite good.

But another layer of reality is that BYD's single car revenue is also declining. According to the same Orient Securities statistics, compared with the first half of 2025, BYD's overseas single car revenue decreased by 16,000 yuan. These two sets of data seem contradictory, but there is actually a certain "logical rationality". Why say this?
The "involution" of the Chinese automotive market has not disappeared because of going overseas. This has led to a phenomenon: on one hand, the proportion of overseas sales has surged; on the other hand, the single car revenue is declining. Some developing well automakers went overseas, propping up gross margins with high-value models. But the more and more low-price models were pushed overseas, also leading to the situation of the average price going down. When the main force of exports expands from Dolphin, Yuan Plus such medium-to-high-end models to more low-price product lines, the premium that the overseas market should belong to the brand is being thinned step by step.

Of course, this is not a problem faced by a certain automaker. Looking through the first half-year financial reports, many automakers that are heavily going overseas are experiencing such a situation. Chery's net foreign exchange loss was 2.092 billion yuan; Geely's net foreign exchange gain from the same period last year of 2.64 billion yuan was directly turned into this year's 550 million yuan net loss; Great Wall Motor had a net foreign exchange gain of 1.493 billion yuan in the first half of last year, but this year after deducting hedging locks, it actually lost 266 million yuan; Leapmotor delivered 356,000 units for half a year, a year-on-year increase of 60.8%, sitting at the top of the new force sales list, but calculated down, the single car net profit was less than 600 yuan, and the annual profit guidance was down from 5 billion yuan to 3 billion yuan.
These data mean that overseas market competition problems have begun to show. Those overseas shares won by price are being transferred in the form of profits. The selling price goes down, the gross margin goes down, and stacked with exchange rate fluctuations, the book profit will eventually become a big problem. "Avoid affecting overseas consumer interests and brand image due to frequent and significant price fluctuations" reflects the concerns of relevant departments.
The Impact Behind Price Cuts, The Whole Industry Has to Pay For It
Thinking deeper, the concerns of the three departments might not only because they calculated the profit account. If looking at it from the perspective of long-term industry development, the coverage of "frequent price cuts" and "overseas involution" is far wider than we imagine. Automobiles are different from ordinary consumer goods. Sun Xiaohong, former Secretary-General of the Automotive Internationalization Professional Committee of the China Machinery Industry Import and Export Chamber of Commerce, explained it clearly: "Overseas markets attach great importance to vehicle residual value and the usage cost of the vehicle's full lifecycle. Frequent and excessive price cuts will make consumers worried about the future residual value preservation of the vehicle, bringing a series of negative effects."

Users who just picked up the car, the next foot sees the official hanging lower prices, value retention shrinks accordingly, this is very easy to trigger users' negative emotions. If it evolves into complaints, rights protection and bad reviews, it may eventually backfire on the brand. This is not groundless worries, currently there have already been some negative cases. For example, in the Thailand market, some domestic automakers continued to cut prices in Thailand, making the dissatisfaction of car-buying users rise, and Thai public institutions also launched investigations on this.
This is just the backlash at the public opinion level; if dissatisfaction intensifies, this may cause worse results. Now, Thailand, Indonesia, and Malaysia are tightening electric vehicle import thresholds synchronously on their own, with localized production and technology transfer as conditions. Clearly, this chain reaction will not affect just a certain automaker. Dissatisfaction from users who have purchased, fermentation of local public opinion, investigation by public institutions, government tightening of import policies, will lead to the entire industry's entry threshold rising. In the end, for this one enterprise's price cut, it is all Chinese brands operating locally who have to pay.
As Shi Yonghong, Vice President of the China Machinery Industry Import and Export Chamber of Commerce said: "Overseas market regulations are scattered, involving safety, environmental protection, data, carbon emissions, supply chain due diligence, etc. The issuance of the 'Guidelines' will help guide enterprises to rationally choose target markets, avoid low-price competition, channel conflict, gray operations, and maintain the overall image of China's automobiles."

The person in charge of the Department of Outbound Investment and Economic Cooperation of the Ministry of Commerce, when interpreting, summarized the intention of this guidance into three points: highlight public service attributes, highlight practical application orientation, highlight win-win cooperation concepts. Falling into policy intentions, what the three ministries truly worry about is not whether a certain enterprise sells expensive or cheap, but whether disorderly price competition will make the four words "China Automobile" become a "negative label" internationally. How to make competition no longer disorderly? Of course, this question still has to be answered with the three words "high quality".
Great Wall Motor Chairman Wei Jianjun said, "Going out of quality is part of high-quality opening up, to bring long-term stable, reliable products and services to overseas consumers". He believes that enterprises going out should respect other countries' legal cultures, bringing taxes and employment to local areas. Talking about price, in the People's Daily Client "Ask the Way" column, he once spoke directly: "If I keep reducing costs, I cannot guarantee the quality of the car."
Now the development of China's automotive industry has changed from past to present. When export scale surges to 10 million units, any individual disorder will be amplified multiple times, the official must set the rules before credit is damaged.
No Price Floor, Cannot Obtain Real Share
Of course, we do not want to convey the viewpoint that "price cuts are wrong". Objectively speaking, price cuts themselves are not wrong, but if price cuts are taken as the only means of competition, then the overseas road will not go far, and real share cannot be obtained. To put it more simply, for Chinese automakers going overseas to last long, having pricing power is very important. How to have this ability? It depends on whose products have something special.

To stabilize prices, win by things outside of price, there are three dimensions of performance that are very key. One is technical differences. Technology is a barrier that can be directly perceived by users. If we can pull gaps in terms of range, safety, intelligence, etc., with powerful technical strength, we can maintain the price floor, rather than rolling down together with opponents.
Two is price stability. This is also a credit impression overseas. Chinese automakers going overseas need to open up the situation with "contract spirit" and "long-termism". Falling into operations, it is stable prices, stable products, stable services, stable expectations. A brand that frequently adjusts prices, users dare not buy now, dealers dare not stock up now, this uncertainty itself is a cost.

Three is local service network. This determines whether overseas users can be assured about the brand, and is also the decisive factor for whether automakers can maintain the price floor. If we can do well in maintenance, parts, residual value, second-hand circulation after selling cars, people's stickiness to the brand will be higher. When the after-sales system is laid out dense enough, price will not be the only selling point.
The "muscle memory" formed in intense involution in the domestic market, when it comes to overseas, will eventually have to relearn the rules. After all, there are no subsidies to support the bottom, nor infinite price war space there. In overseas, possessing the determination to establish prices is the core strategy for long-term survival.
Conclusion
Markets won by low prices are actually not stable. The four words "Made in China" cannot be labeled with "dumping" and "cheap". The purpose of the three departments' guidance is not to ban price cuts, nor to halt going overseas. It only puts a long-ignored fact on the table. Now, policies have drawn clear boundaries for Chinese automakers. Automakers used to "price involution", it is also time to make choices that conform to the guidance.
Have you ever calculated this: For a new energy vehicle selling at 200,000, how much money can the car manufacturer keep in their pocket at the end?
The answer is possibly less than 10,000. And how much can the battery supplier take from these 200,000? More than 60,000. This isn't the most heartbreaking part. What truly makes the industry restless is that CATL earned 20.7 billion in the first quarter of this year, while the combined earnings of several top domestic car manufacturers are less than a fraction of that. Some joke that building cars nowadays isn't working for CATL, it's working for free for CATL. This sounds exaggerated, but looking at the freshly released Q1 report, most car manufacturers probably can't smile.
Car manufacturing profits all ran into the battery factory's pocketCATL's numbers for Q1 2026 are truly eye-catching, achieving 129.131 billion yuan in revenue, with a net profit attributable to shareholders of the listed company at 20.738 billion yuan, a year-on-year increase of 48.52%, earning a net profit of 230 million yuan daily. What does this concept mean? Just look at the report cards submitted by car manufacturers in the first quarter to understand.

In Q1, BYD achieved revenue of 150.225 billion yuan, with net profit attributable to shareholders of 4.085 billion yuan. Geely Automotive's Q1 revenue was 83.776 billion yuan, with net profit attributable only 4.166 billion yuan. Great Wall Motor's situation is similar, Q1 revenue 45.109 billion yuan, but net profit attributable is only 945 million yuan. Looking at Changan Automobile, Q1 revenue is about 32.706 billion yuan, net profit attributable to shareholders is only 351 million yuan.
That is to say, BYD's profit in three months is less than 4.1 billion, Geely less than 4.2 billion, Great Wall less than 1 billion, and Changan is only 351 million. CATL's single-quarter net profit is five times that of BYD, more than twice that of Geely and Great Wall combined, and Changan is left behind by an order of magnitude.
Putting these numbers into perspective, a more intuitive comparison comes from the industry as a whole. Cui Dongshu, Secretary General of CPCA, previously gave data showing that in Q1 2026, China's automotive industry revenue was 2.4128 trillion yuan, profit was 78.4 billion yuan, down 18% year-on-year, sales profit margin further dropped to 3.2%. And a year ago, the profit margin for the entire domestic automotive industry in the first half of the year had already been compressed to around 4.8%. Now it's not only not improved but worse.

According to industry data, the proportion of power batteries in the total cost of a vehicle has reached 30% to 40%. If the price of lithium is high, this proportion could be even higher. Considering the fierce price war in the new energy vehicle market price today, with an average drop of 38,000 yuan, the profit space for car manufacturers has been compressed to the extreme.
This is why many consumers find that new energy vehicles of the same level have small price differences, but configurations are getting more competitive. Because the only thing that can make a difference is remaining in intelligence and cockpit experience, while the most valuable batteries, everyone basically gets goods from the same supplier. A single quarter's profit of a battery supplier is higher than the combined profit of several top car manufacturers. Is this really a healthy industry ecosystem?
A car holds batteries, but more importantly, others' profitsZeng Qinghong of GAC Group said at the 2022 World Power Battery Conference that power battery costs account for 40% to 60% of the total vehicle cost. He joked saying "Am I not working for CATL now?". Fast forward nearly 4 years, this sentence remains a true portrayal of the entire industry.
When an ordinary car owner buys a car, they of course care most about range and reliability, and CATL's reputation in these two matters is indeed solid. But the greater the reputation, the harder it is for car manufacturers to break free from dependence. When a supplier accounts for over 43% of the power battery installation share in China, any car manufacturer wanting to switch supply plans has to consider whether consumers will approve. At the same time, battery companies have also unknowingly grasped pricing power and discourse power. Car manufacturers not only have to pay money but also queue up to pay prepayments to lock capacity. This kind of supply chain relationship was almost unimaginable in the traditional automobile industry era.

If we compare CATL with an engine-making enterprise, this contrast becomes clearer. Taking Weichai Power as an example, as the leading enterprise in the domestic engine field, 2025 full-year revenue was 231.8 billion yuan, net profit attributable to 10.9 billion yuan. While CATL's single-quarter net profit in 2026 alone exceeded 20 billion yuan, close to twice Weichai's full-year profit.

If Weichai represents the traditional internal combustion engine era still maintaining balance between vehicle manufacturers and parts suppliers, then in the power battery field, this balance has been completely broken. An owner might rarely ask what brand of engine is in the car when buying, but more and more people will actively check if this car uses CATL's battery. This is the power of consumer-end cognition, and this power in turn gives battery manufacturers greater bargaining confidence.
When battery manufacturers grasp the "steering wheel" of the industry, what do consumers feel?For ordinary consumers, changes in the profit structure of the industry upstream will eventually fall on the reality of car selection and driving experience. The most direct manifestation is the "breaking out" of battery brands. A few years ago, few people would care which company's cells an electric vehicle used, but now many potential car buyers will actively check which company is the battery supplier of a certain car when browsing forums or watching car reviews, or even take "CATL" as an important car purchasing decision factor. This cognitive migration objectively gives CATL greater market appeal and makes car manufacturers more cautious in supplier selection.

From a more realistic driving scenario, this trend of upstream profit centralization is also affecting product definition and pricing strategies. Batteries account for over 30% of the total vehicle cost, meaning that for car manufacturers to launch an affordable model, they must make trade-offs in battery capacity. This is why there are some entry-level models in the market with shorter range but guaranteed battery brands. It's not that car manufacturers don't want to give big batteries, but the batteries themselves are too expensive. For budget-limited family users, this sometimes becomes a dilemma: if you want long range, you have to accept a higher car price; if you want it cheap, range and battery brand may have to compromise.
Another noteworthy phenomenon is that car manufacturers, in order to cope with battery cost pressure, are ganging up to build their own battery production lines. Whether it is a car manufacturer like BYD which already has battery self-supply capability, or other car manufacturers that have entered or are entering the field, they are all trying to master the battery business themselves. But whether this practice can fundamentally change the profit distribution pattern is still hard to say. After all, building a complete battery production line requires throwing billions in, technology accumulation and yield ramp-up also require a long cycle, not every car manufacturer can afford it. And in this process, car manufacturers' R&D expenses continue to rise, while terminal prices drop again and again, and profits are squeezed even thinner.

This phenomenon of profit inversion between battery manufacturers and car manufacturers is unlikely to reverse in the short term. CATL's domestic installation share has risen to 47.7% in Q1 2026, increasing by another 3.4 percentage points year-on-year, and market concentration is further improving. For consumers who want to buy new energy vehicles, this means that battery brands will remain a realistic proposition that must be faced when selecting cars for a long time. And when the most cost item of a car is in the hands of one supplier, the discourse power of the entire industrial chain is also transferring quietly. This transfer will eventually reflect in the choices of every car buyer in terms of price, configuration, driving experience, etc.
To put it simply, the growth of the domestic new energy vehicle market now is not as crazy as the previous two years, the growth rate of new car registration volume is slowing down, the penetration rate in first and second-tier cities is gradually hitting the ceiling, and the consumer power of third and fourth-tier markets needs time to cultivate. In this situation, whether car manufacturers or battery manufacturers, they have to fight for meat in the stock market, and price wars will inevitably get fiercer, and profits will naturally become thinner. Although CATL's Q1 net profit of 20.7 billion yuan is eye-catching, this is behind the squeezed survival space of small and medium battery enterprises and vehicle manufacturers. If we only look at this domestic cake, sooner or later everyone will be unable to fight for it.

So, going overseas is the solution. Europe, Southeast Asia, the Middle East, South America, the penetration rate of new energy vehicles in these places is still very low, and the market space is much larger than in China. CATL has already built factories in Germany and Hungary, and recently there are reports that they intend to further layout in Spain or Indonesia. On the car manufacturer side, BYD, SAIC, Geely, etc., are also accelerating the landing of overseas factories and sales networks. Selling products and technology to the global market, making the global market capacity larger, only then will the entire industrial chain have the opportunity to move from "rolling profits" to "sharing increments".
If Chinese new energy vehicles and batteries can stand firm overseas, scale effects will further reduce costs, and domestic car prices are expected to become more reasonable. At the same time, the competitive environment of the overseas market forces enterprises to improve product quality and service standards, and the ultimate beneficiary is still the ordinary car buyer. Instead of consuming each other in the domestic red ocean, why not work together to make the cake bigger. The pattern of battery manufacturers eating meat and car manufacturers drinking soup will not change in a day, but when everyone turns their eyes to a wider world, at least the meat in this pot of soup will be much more than now.
August 19, Chery Executive Vice President, General Manager of International Business Group and General Manager of MoJia Robotics Zhang Guibing revealed during the 2026 World Robot Conference that MoJia Robotics (AiMOGA Robotics) under Chery has launched IPO preparations, is currently negotiating with multiple listing venues, and the timetable is yet to be determined. He stated that listing can raise financing for technical investment and also help improve governance transparency.

MoJia's starting point was not building robots, but the digital virtual avatar Mornine (Mornine). Around 2023, Chery's overseas brand OMODA heated up the C5 model, creating virtual human Mornine that resonates with Gen Z, active on promotional animations, brand live streaming platforms, and more.
The turning point began with operational pain points encountered in Chery's overseas stores. Zhang Guibing revealed that overseas sales are affected by peak and off-peak seasons, staff turnover is frequent, recruitment is difficult, and even if hired, multi-language training is a high threshold. The team thus conceived the idea of "letting Mornine walk into reality", which became the origin of the AiMOGA Robot project.
At the end of 2023, Mornine's first prototype went off the line, and in early 2024, it made its first public appearance at Chery's Global Dealer Conference. After more than two years of technical accumulation, on January 7, 2025, Chery officially invested to establish "Anhui MoJia Smart Innovation Robotics Technology Co., Ltd.", with registered capital of 100 million yuan, legal representative Zhang Guibing, MoJia transformed from an internal project to an independent legal entity.

In February of the same year, Mornine completed its first overseas commercial debut at the Kuala Lumpur store in Malaysia; in April, it appeared at the Shanghai Auto Show, demonstrating multi-modal perception and dexterous operation capabilities; in October, at the Chery Global Innovation Conference, it gave an autonomous speech in seven languages, becoming the focus of the whole event.

From December 2025 to January 2026, MoJia completed the first round of capital increase and strategic investment, registered capital increased to about 104 million yuan. After capital increase, the latest equity structure shows Chery Motors holds 96%, Bethel 1.40%, Fuchun Dyeing 1.20%, Hexie Chaoyue Fund 0.40%, Zhiyuan Innovation 0.20%, Wuhu Economic Development Zone Weida Venture Capital 0.40%, Wuhu Sci-Tech Investment Fund 0.40%.
In terms of performance, MoJia's cumulative global deliveries have exceeded 3,000 units, approximately 2,000 sold overseas, business covers 60 countries and regions, it is the world's first humanoid robot to complete dual EU software and hardware certification. On April 27, 2026 press conference, signed an order for 1,000 intelligent police robots at once and delivered 110 units on-site, product line thus expanded from "4S store sales associates" to the public security field.
Key customers cover Chery's overseas dealer network and public security departments of multiple cities.
Zhang Guibing revealed plans to increase global delivery volume to 10,000 units in 2027, join the industry's first tier, and proposed "three specific actions: improving reliability and cost-effectiveness of large-scale applications, iterating in over 50 countries and 100+ scenarios, achieving 100 unit deliveries to trigger 1,000 unit intent signings."
Industrialization advances in three stages according to "scenario-driven technology", first make child companion scenario robots, then expand to public service and enterprise service scenarios, finally promote robots entering homes.
In terms of supporting construction, 31 innovation labs have been set up, "AiMOGA Academy" established, signed with 100 universities to train talent, quadruped robot production line annual capacity reaches 15,000 units.

At Chery AI Night in January of this year, Chery Chairman Yin Tongyue proposed a "One Bottom Line, Three Directions" strategy, using cars as the cornerstone to promote AI extension to the physical world, covering humanoid robots, Robotaxi, smart agricultural machinery and other scenarios, "putting the car brain into the bodies of other industries". He revealed Chery's R&D budget for 2026 exceeds 32 billion yuan, the "2R Technology" composed of Robotaxi and MoJia is one of the four key focuses, and stated that the original intention of the layout is a rethinking of the "second growth point after the total number of future cars decreases".
At the April 27 MoJia press conference, he once again stated: "We most do not want to be defined as a car company, but as a high-tech, embodied, innovative company facing the future."
He proposed "intelligent cars are mobile robots", robots and intelligent cars have highly homogeneous underlying technologies in perception, planning, control, etc., technology modules and supply chains can be transferred.
2026 is regarded by the industry as the year of concentrated release of automakers' embodied intelligence layouts, globally over 20 mainstream automakers have entered the game through self-research, incubation, investment, etc., the industry is shifting from technology exploration to mass production racing.
MIIT data shows, China's quadruped robots already account for nearly 70% share of global sales. The industry generally judges that 2026 to 2028 will be the key verification window for humanoid robots to go from "prototypes" to "mass production of 10,000 units", but commercialization loop is still in early "strategic loss" stage, bottlenecks such as limited application scenarios and high costs remain to be broken. Against the background of the automotive industry profit margin falling below 3%, embodied intelligence has been regarded by many automakers as a "second growth curve" to hedge against the slowdown of the main business growth.
Source: Car Observer

Written by | Wu Jing
Edited by | Huang Dalu
Designed by | Zhen Youmei
On July 10, 2026, on the eve of the tenth anniversary of the South China Sea Arbitration Ruling, China Daily released an AI-generated video: a monkey wearing traditional Filipino attire was thrown into the sea, operated by hands representing the United States and Japan, and sprayed with water cannons from a suspected Chinese Coast Guard ship.
The Philippine government characterized this as derogatory and racist expression; President Marcos summoned the Chinese ambassador; the Chinese Ministry of Foreign Affairs responded that the video does not represent the official stance, but reiterated non-recognition of the arbitration ruling.
Nineteen days later, on July 29, Marcos signed Executive Order No. 121, launching the Electric Vehicle Incentive Strategy (EVIS) with a total scale of 60 billion pesos (about 1 billion US dollars), aiming to transform the Philippines into a regional automotive manufacturing center.

On the list of investors this policy most hopes to attract, Chinese automakers appear exactly — In March this year, the Philippines' trade and economic institution in China held a Philippines-China business cooperation meeting, publicly inviting Chinese electric vehicle, power battery, and component companies to invest in the Philippines.
EVIS provides matching funds for corporate capital expenditures, covering R&D and worker training: Pure electric vehicles and parts up to 40% subsidy, hybrid, plug-in hybrid, fuel cell models up to 30%. Entry threshold: choose one, minimum capital 5 billion pesos (about 81 million US dollars), or electric vehicle annual capacity 10,000 units. Single model subsidy cap 1.5 billion pesos, each automaker can declare up to two models, issued as tax credit, deductible for corporate income tax, consumption tax, VAT, and import tariffs.
The Philippines hopes to use this money to convert electric vehicle consumption into local capacity. But as of now, no Chinese vehicle manufacturer has publicly announced participation in EVIS.
The first to respond was Mitsubishi Motors, which has produced vehicles in the Philippines for decades.
From CARS to EVIS
EVIS did not appear out of thin air. Its policy source can be traced back to the 2022 Electric Vehicle Industry Development Act (EVIDA) — In that year, the Philippines had already reduced import tariffs on complete electric vehicles and core parts to zero to stimulate consumption, after which an incentive framework for EV manufacturing was brewing for about four years, EO 121 is the implementation of this clue.
In contrast, there was a contraction in fuel vehicle era policies. In January this year, Marcos signed the 2026 national budget of 6.793 trillion pesos, simultaneously vetoing 92.5 billion pesos in unstarted reserve appropriation, including 4.32 billion pesos of fiscal support funds under the CARS plan. The Philippine Association of Parts Manufacturers stated that CARS and RACE are the 'lifeline' of local manufacturing; this veto made automakers and suppliers immediately nervous.

CARS landed in 2015, budget 27 billion pesos, aiming to rebuild the Philippines' status as a regional complete vehicle manufacturing center: Automakers promise filed models (Toyota Vios, Mitsubishi Mirage) to achieve at least 200,000 units of local mass production, can receive subsidies according to production capacity and investment promises. RACE is its follow-up, originally to further enhance local competitiveness.
The government quickly clarified: CARS was not abolished, only the 2026 disbursement channel was vetoed. On January 19, the Budget Management Department, Department of Trade and Industry, and Ministry of Finance jointly announced that all payable subsidy amounts with issued verification tax payment certificates will be paid as scheduled — Among the plan's 5.43 billion pesos total appropriation, 1.44 billion pesos had been allocated previously. RACE was announced by the Ministry of Trade and Industry in April not to proceed, but in July the government expressed consideration to restore the plan, to be implemented in parallel with EVIS, fate not yet finally decided.
The center of policy is clear: Old debts paid as usual, new resources directed to electrification. The Philippine Ministry of Finance's statement on this is, the national thinking has shifted from 'how to maintain fuel vehicle capacity' to 'how to keep the manufacturing link of the next generation new energy vehicle in the country'.
This shift has its inevitability. Global automotive electrification is the trend, the value of pure assembly fuel vehicle bases is shrinking, high-value-added opportunities concentrate on drive motors, power batteries, power semiconductors, in-vehicle software and chips, thermal management systems, hybrid technology, battery recycling, and other fields. Continuing to subsidize backward fuel vehicle capacity is just maintaining a structure that is losing competitiveness.
This doesn't mean CARS was wrong back then. It solved a real dilemma: With large production bases like Thailand, Indonesia nearby, how to enable automakers to achieve mass production scale in the Philippines? CARS broke the deadlock to some extent by binding capacity and investment promises with subsidies.
It's just that this scheme designed in 2015 cannot adapt to the electrification and intelligence wave sweeping the globe in recent years.
Why Chinese Automakers Will Not Build Factories
Chinese automakers are at the forefront of the global electrification and intelligence wave, but they basically will not accept invitations like the Philippines.
First is market scale. Philippines 2025 new car sales about 493,000 units, far smaller than Indonesia, Thailand's million-unit level markets, relying solely on domestic demand cannot support a large new energy vehicle factory.

Second is industrial foundation. Thailand has a complete complete vehicle, parts, and export system, Chinese automakers entering Thailand is expanding on the existing automotive ecosystem. Indonesia relies on nickel resources and battery material industry chain to attract CATL, BYD, etc. Although Philippines also has nickel mines, it has not yet formed a new energy material and parts industry chain of the same scale.
Third is import substitution. BYD, Geely, Chery, Great Wall, and SAIC and other Chinese brands have entered the Philippines, but mainly rely on complete vehicle import. Enterprises can supply directly from China, or set production in Thailand or Indonesia, export to the Philippines after satisfying ASEAN rules of origin. As long as the combined cost of these two plans is lower than local production, building factories in the Philippines is not the optimal choice.
Finally is China-Philippines relations. The video trouble at the beginning cannot directly explain why Chinese automakers did not go to the Philippines to build factories, and currently no enterprise publicly stated investment decisions were affected by the event. But automotive manufacturing has a long recovery cycle, assets are difficult to migrate, China-Philippines relations are still a risk that Chinese enterprises must consider additionally. Smart electric vehicles also involve maps, cameras, data storage and remote upgrades, easier to enter data compliance and security review scope than traditional fuel vehicles.
OCTA Research survey in July 2026 showed that 64% of Philippine adult respondents do not trust China, up 9 percentage points from the first quarter of that year. Philippine Statistics Authority data shows 2025 Chinese investment commitments accounted for 3.76% of all foreign investment commitments. These data cannot prove the South China Sea dispute stopped Chinese investment, but can indicate the Philippines has not yet become a priority layout for Chinese capital.
The Philippines also finds it hard to force enterprises to build factories by greatly raising tariffs. Toyota and Mitsubishi local factories combined annual capacity about 110,000 units, far below national demand. Before local capacity is established restricting imports, first may bring car price rise, consumer choice reduction, and market shrinkage.
60 billion pesos can help existing automakers like Mitsubishi upgrade production lines, but not enough to change the regional layout of Chinese automakers. Therefore, in the foreseeable future, the possibility of Chinese automakers building complete vehicle factories in the Philippines is very low.
Why Toyota, Mitsubishi Can Produce in the Philippines
Automotive Business Review believes the goal that EVIS truly likely to achieve is not to exchange for Chinese automakers building factories, but to help existing enterprises like Toyota, Mitsubishi complete electrification renovation, avoid the Philippines existing automotive manufacturing capacity continue to loss.
Toyota and Mitsubishi's manufacturing history in the Philippines both exceed half a century: Toyota traces back to 1962 Philippine enterprise Delta Motors assembling Toyota cars, current Toyota Philippines company established 1988, Bicutan factory started 1989, Santa Rosa factory opened 1997; Mitsubishi Philippines predecessor established 1963, production started 1964.

Their rooting is the product of specific historical conditions. After WWII Philippines long lacked foreign exchange, 1949 starting foreign exchange control forced automakers to import parts local assembly; 1973 phased automotive manufacturing plan (PCMP) further restricted complete vehicle import, mandatory increase localization rate.
Institutional signal is clear: To long term enter the Philippines market, must assemble locally, gradually localise. At that time ASEAN had no regional production network, Thailand also at beginning.
After 1990s control lifted, ASEAN tariffs dropped, Thailand, Indonesia developed larger scale industry clusters, automakers no longer need to set up factories in every country. Philippines factory scale small, supply chain incomplete, market not big enough, Ford, Honda, Nissan gradually withdrew from local production.
Toyota, Mitsubishi stayed, first sunk cost of factory, equipment, workers and suppliers, second enough large market share. What CARS plan did was actually stabilize these two's existing capacity.
This also explains why Mitsubishi is EVIS's first responder: Santa Rosa factory annual capacity about 50,000 units, produces Mirage, Mirage G4, L300 and other models, adding hybrid production lines need not push down rebuild, workers can be retrained, local suppliers can enter new energy supply chain.
For Mitsubishi, importing hybrid models is transforming existing production lines, not building a production system from scratch. This is the key why it was able to express participation intention before EVIS officially issued.
The 2026 first-half global automaker sales rankings are out: BYD (4.8%), Geely (4.6%), and Chery (4.1%) ranked sixth, seventh, and ninth respectively, the three combined account for 13.5%, surpassing VW in second place for the first time—this marks the first time three Chinese automakers appear simultaneously in the global top ten. If counted by group, SAIC ranks fourth with 2.045 million units, making four Chinese automakers actually present in the top ten. From "market for technology" to "technology for market", Chinese autos have achieved a leap from zero to the global forefront through changing lanes to overtake. So, will the future global automotive industry landscape be rewritten again?

From Zero to Top Ten: The Differentiated Path of Changing Lanes to Overtake
In the fuel vehicle era, patent barriers for engines and transmissions were long held by Europe, America, and Japan, while Chinese automakers trailed behind.
The wave of new energy and intelligence gave China a chance to "redraw the track": in core areas such as power batteries, electric drives, and intelligent driving, China achieved a paradigm shift in technology from trailing to leading, bypassing the moat of traditional internal combustion engines.

It is this differentiated track that allowed Chinese automakers to complete a path that traditional giants took half a century in ten years—not directly confronting internal combustion engines, but starting a new table with electrification and intelligence, pulling competition into the opponent's weak areas.
Five Levels of Global Auto Landscape Restructuring
This historic breakthrough implies major changes on five levels (see table below), rather than a single enterprise's victory:

The core growth pole of the global automotive industry is shifting; Chinese automakers have won the initiative in the division of new technologies; at the same time, through the localization of "overseas factories + supply chain", they export capacity, technology, and standards, building an integrated ecosystem of "cars + chargers + services", significantly enhancing risk resistance. The clustering effect of the super-large market and the most complete industrial chain continues to amplify R&D cycles and cost advantages.
Multi-point Bloom of Chinese Cars in Five Major Global Regions
Southeast Asia:
Already an absolute leader in new energy. Thai brand share for pure electric is over 75%, EV market share in Indonesia 91.7%; in January 2026, Thai brand share reached 47.34%, historically surpassing Japanese brands (47.338%) for the first time, ending the 60-year Japanese monopoly.
Europe:
In May, top five Chinese brands registered 138,000 units with 12% share, surpassing Japanese automakers (130,000 units/11.3%) for the first time in history, expanding further in June; facing EU tariffs, accelerating deep localization through joint ventures and technology exports.

Chery Automobile First-Half Monthly Export Details
Latin America:
Brazilian pure electric Chinese share once exceeded 92%, BYD Dolphin Mini topped the Brazilian retail list in February 2026; Mexico exported 625,000 units in 2025, surpassing Russia for the first time to become China's largest export destination; Chile's light vehicle share exceeded half (51.6%).
Middle East:
Upgrading from "low price" to "high-end". Saudi brand sales broke 100,000, market share over 15%; UAE import volume in first two months 103,900 units, +53% YoY. Thermal management upgrades for high temperatures and dust, premium brands like Zeekr, Voyah, Nio won over the wealthy.

BYD First-Half Monthly Export Details
Russia:
Europe, America, Japan, Korea withdrew leaving space, Chinese brand share reached 54.6% (peak 54.9% in June); Chery, Great Wall, Geely rank at the forefront, using technology licensing + local assembly (e.g., TENET, XCITE) to avoid scrappage tax and 22% VAT.
End-of-Year Global Auto Market Top 10 Forecast
First half China exports 5.307 million units, +53% YoY, June single month 1.069 million units; New energy exports +68.7% (360.68 billion yuan). July continues volume and value growth—first 5 months exports volume +48.7%, value +45.5%, ports like Ningbo doubled new energy vehicle export volume and value. Annual exports expected to break 10 million for the first time, providing ammunition for more Chinese groups to break into the top ten.
Who will break through again at year-end? Based on BYD, Geely, Chery (independent brand basis) already on the list, the strongest new entrants are Changan and Great Wall: Changan releases in multiple points including Brazil, Mexico, Thailand, Russia; Great Wall digs deep in Russia, Thailand, Brazil and stays at the forefront locally, both export growth rates in the top tier.

Geely Automobile First-Half Monthly Export Details
Need to note statistical basis differences: In the user context, "three" focuses on independent brands, while under group basis SAIC has long been firmly fourth—this means the expansion of the "Chinese formation" at year-end is more considerable than surface numbers. As for Leapmotor, Xiaomi, etc., new energy dark horses growth is fierce (Leapmotor first half 260,000 units, +29% YoY), full year group total still has distance to top ten for all categories, more likely to first challenge new energy sub-lists.

Conclusion
From zero to squeezing into global top ten, Chinese autos took twenty years; from one exclusive show to three joining hands, only three years were needed. But the real challenge has just begun—from "sales champion" to "brand champion" and "technology champion", from "price war" to "value war", Chinese automakers need to establish emotional connection surpassing price-performance ratio in the hearts of global consumers. The power shift in the global automotive industry has already occurred, and the next story will be written by how Chinese automakers write it.
Recently, South Korean automaker KG Mobility (KGM) announced a strategic investment agreement with Chery Automobile. According to the agreement, Chery will invest 75 million US dollars into KGM and carry out or expand cooperation in areas such as accelerating new vehicle development, autonomous driving, and advanced electronic and electrical architecture.
If the transaction is completed and all bonds are converted to equity, Chery is expected to hold approximately 10% of KGM's shares and is expected to become its second-largest shareholder.

Chery's partnership with a South Korean automaker this time easily brings to mind the recent cooperation between Geely and Ford. Geely acquired 34% equity in the joint venture for 221 million euros and shares Ford's factory resources located in Valencia, Spain.
On the surface, in both collaborations, Chinese enterprises did not obtain absolute controlling equity, nor did they directly control daily operation management, but this precisely embodies the strategic wisdom of China's deep cultivation in the global market.
In the past, Chinese automakers going global relied more on product exports; however, nowadays, with changing competitive environments, Chinese automobiles are moving from pure "product output" to "global operation" covering technology, supply chain, manufacturing capabilities, brand value, and industrial ecosystems. For Chinese automakers, carrying out deep cooperation with local enterprises can faster utilize existing manufacturing, channels, and industrial resources to enter overseas markets with lower cost thresholds and achieve long-term rooting.
Currently, the globalization of Chinese automakers is entering a brand new stage. According to data from the General Administration of Customs, China's auto exports reached 5.31 million units in the first half of this year, a year-on-year increase of 53%, achieving continuous growth for 5 years. At the same time, consulting firms predict that China's auto export volume in 2026 will approach 10 million units, and China is expected to become the first country in the world to break through the 10 million unit auto export scale.
However, it needs to be seen that export volume growth does not equal the formation of globalization capabilities. For Chinese automakers, going global still faces multiple challenges such as trade barriers, policy differences, local operations, and brand awareness. How to move from "selling out" to "staying in" is the proposition that must be answered in the next stage.
True globalization still requires automakers to answer three core questions: Why are locals willing to accept the enterprise staying? Why are partners willing to walk alongside the enterprise for the long term? Can the enterprise achieve sustainable profitability locally?
These three questions correspond to industrial value, cooperation value, and commercial value respectively. Only when the three form a closed loop does going global become not just a short-term sales growth, but a long-term business capable of crossing cycles and continuously creating value.
"Behind the 'Global Expansion Fever', Chinese Automakers Still Need to Find Long-term Growth Solutions"
In recent years, "going global" has become a mandatory course that Chinese automakers cannot bypass. Besides Chery, enterprises such as Geely, Changan, Leapmotor, and Xpeng are also accelerating the promotion of global layout.
On the surface, this is a natural spillover after the improvement of Chinese automobile technology, product strength, and complete industrial chain capabilities; but from a more realistic perspective, it is also a strategic choice forced by market competition.

In the past few years, China's new energy vehicle market grew rapidly, with new brands, new models, and a large amount of capacity flooding in, and market competition gradually moved from incremental competition to stock game phase. Against the backdrop of domestic market "involution to death", many automakers face the dilemma of "increasing revenue but not profit". Therefore, the overseas market has become an important direction for enterprises to digest capacity, expand scale, and improve profit space.
However, when more and more enterprises regard going global as the answer for growth, a new question also appears: Will the overseas market become the next competitive red sea?
From the demand side, the global new energy vehicle market indeed still exists a large growth space. In the first half of 2026, the cumulative sales of new energy vehicles in the European market were about 2.378 million units, a year-on-year increase of 32.7%, penetration rate reached 29.2%, an increase of about 6 percentage points compared to the same period last year, accounting for 20.3% of global new energy vehicle sales. At the same time, new energy sales in emerging markets such as India and the Philippines also grew rapidly, among which India increased by 83.8% year-on-year, and the Philippines increased by 149.6% year-on-year.
However, it needs to be seen that different countries exist huge differences in consumption habits, regulatory standards, infrastructure, channel systems, and brand awareness, etc. The overseas market is not simply copying the Chinese market's "second battlefield", nor is it as simple as moving domestic mature models overseas for sales.
In fact, the export growth in the first half of this year not only comes from the improvement of the competitiveness of Chinese automakers themselves, but is also affected by multiple factors such as changes in international energy prices and adjustment of the electrification rhythm of overseas traditional automakers. With more Chinese brands entering the overseas market, competition is also gradually upgrading, and the dividends of going global are also gradually decreasing.
If enterprises only rely on price advantages, short-term sales, and channel deployment for expansion, then Chinese automobiles overseas may also fall into the cycle of "low-price competition" and "scale involution".
"Overseas is not a 'Safe Haven', Chinese Automakers Welcome Higher Cost Battlefields"
As is well known, the selling price of many Chinese automobile brands in the overseas market is often higher than the domestic market. Taking Chery Tiggo 8 as an example, the market price in China is around 100,000 yuan, but after entering the Russian market, the starting price is converted to about 220,000 yuan RMB, and in some markets in the Middle East, the landed price of the top configuration model is even close to 400,000 yuan.

This also makes many people in the past believe: going global means "China production, overseas sales", utilizing China's mature supply chain system and cost advantages to obtain higher premiums in the overseas market. But in fact, as Chinese automakers' globalization enters the deep water zone, this simple sales model is facing more and more challenges.
Even, a higher overseas selling price does not necessarily mean higher overseas profits. And a series of factors such as tariff barriers, local production requirements, environmental policies, distribution networks, after-sales service, etc., will directly affect the enterprise's final profitability.
Especially against the background of intensified competition in the global automobile industry, the overseas market is raising entry barriers. For example, the EU "Industrial Accelerator Act" proposes to implement "conditional market access" for countries with global key industry manufacturing capacity share exceeding 40%; the EU "New Battery Act" stipulates that starting from February 2027, power batteries must provide full life cycle carbon footprint data.
At the same time, European local automakers are also strengthening defense. Volkswagen, Stellantis, Renault and other European automotive enterprises have called for the EU to take more measures to protect the local electric vehicle industry; some European enterprises and unions also have concerns about cooperating with Chinese automakers, and even some overseas media described Chinese new energy vehicles as "Trojan horses".
It can be seen that Chinese automobile going global is experiencing a change in underlying logic, the past relied on product quality-price ratio, the future competes on system capabilities. Whoever can transform complex costs in global operations into brand, technology and industrial chain advantages, can truly realize the leap from "exporting products" to "global operations".
"Going Global is Not a Zero-Sum Game, But a Competitive Cooperation Game"
Chinese automakers' going global has never been standing on the opposite side of overseas enterprises.
Previously, Chairman Yin Tongyue of Chery Automobile Co., Ltd. pointed out: "Going to a (emerging) market is not just about pushing Chinese products out, must comply with local regulations, fit local user habits, at the same time we cannot keep all for themselves." He further emphasized that Chery going global is not to "grab" others' territory. "Do not be a plunderer, but be a fertilizer provider, increase fertility; do not go to their (place) to plunder markets, plunder talent."
Because true sustainable globalization is not about selling a car to the overseas market, but forming industrial connections locally, truly rooting in the local market.
Nowadays, the overseas layout methods of Chinese automakers have become more and more diversified, covering whole vehicle exports, CKD assembly, local production, dealer cooperation, technology licensing, platform output, capital cooperation, and joint operation and other models. And different models are essentially all for improving the enterprise's adaptability to the global market.

For example, SAIC-GM-Wuling planned production bases in Indonesia through the industrial chain synergy mode, built 120,000 units of whole vehicle capacity, while leading 16 domestic three-electric enterprises to go out together, and cultivated more than 100 local suppliers, achieving transition from product entry to industrial chain integration; Great Wall Motors through acquiring and transforming Brazil Daimler factory, officially started production in August 2025, created about 2,000 direct employment positions, and drove local supply chain system development; Chery and Spain EV MOTORS established a joint venture company, took over the Nissan closed Barcelona factory, with "Chery Technology + EBRO Brand" method to re-activate local manufacturing capability
In addition, Changan Thailand Rayong Factory welcomed the 20,000th whole vehicle off the line in June 2026, the factory total investment about 2.2 billion yuan, phase one annual capacity 100,000 units, key quality control workstation automation rate reached 90%; Geely relied on Proton brand deep plowing in Malaysia market, its Tanjung Malim electric vehicle factory has started production, phase one annual capacity reached 20,000 units.
It is worth noting that new power brands are also accelerating the output of technical systems and infrastructure capabilities. For example, Nio has deployed 93 battery swap stations overseas, and participated in research and formulation of Singapore electric vehicle charging and swapping standards "Singapore Standard SS 722"; Leapmotor, through establishing a joint venture company with Stellantis, promotes internationalization with the help of global channel resources, its main model C10 has also started local assembly production at Kulim Factory, Kedah, Malaysia; Xpeng not only has strategic cooperation with Volkswagen, but also acquired 90.1% equity of Indonesian listed company EIDO, planning its first overseas production base, and adopted CKD model to promote localized manufacturing.
From the perspective of industry insiders, different going global paths do not exist absolute superiority or inferiority, the key lies in whether it matches the enterprise's own capabilities and development stages. Whole vehicle export speed is fast, investment is relatively light, but easy to be affected by trade policy changes; local factory construction can enhance industrial integration, but needs continuous capital investment and scale support; channel cooperation can quickly open the market, but user relationships and brand assets may be constrained by partners; technology licensing and capital cooperation are lighter, but test whether the enterprise can transform technical advantages into long-term commercial value.
And judging whether an enterprise's going global is successful, cannot look only at export volume, how many countries and regions entered, or even cannot look only at overseas sales growth, but need to see whether it can answer several more core questions.
First, can it make money. Whether overseas business can form stable and sustainable profit-making ability, rather than relying on domestic market blood transfusion, financing support or short-term price advantages.
Secondly, can it take root. Whether it establishes local R&D, manufacturing, channel, service and supply chain systems, rather than staying at one-time product sales.
Thirdly, can it achieve win-win. Whether it can create employment, tax and industrial value for the locality, making government, partners, suppliers and consumers all become beneficiaries in the globalization process.
In addition, it also needs to see if the enterprise can resist risks. Facing tariff changes, policy adjustments, exchange rate fluctuations and geopolitical uncertainties, whether overseas business has sufficient resilience.
More importantly, whether the enterprise can build true brand value. What consumers buy, is it just a lower price Chinese automobile product, or recognize a global automobile brand that can exist for a long time and continuously provide value.
From the perspective of industry insiders, the highest standard of going global is not how much Chinese automakers took away from the overseas market, but how much value was left for the local while obtaining commercial returns. The overseas market does not reject Chinese automobiles, but no market will long-term welcome an "outsider" who only sells products, fights for share, but does not bear industrial responsibility and does not create local value.
Truly viable globalization is not a short-term surprise battle won relying on cost advantages, but finding the greatest common divisor of enterprise interests and local interests in different markets. Only from "entering overseas market" to "integrating into local industry", Chinese automobiles can truly complete the transformation from export powerhouse to important participant in the global automobile industry.
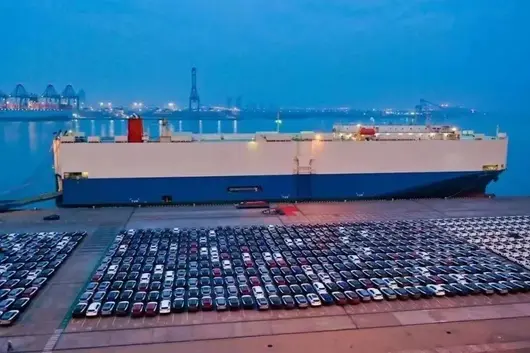
By 2025, China's energy-saving and new energy vehicle talent gap reached one million. The supply-demand ratio for intelligent driving engineers is only 0.38, with fewer than one qualified candidate corresponding to one position on average.
More troubling is that even if double salaries are offered, it is difficult to poach a suitable intelligent system engineer from the market. Power batteries, intelligent driving, and three-electric systems, every emerging field is calling for more people, while graduates in traditional mechanics and processes face fierce competition in the job market. The old recruitment logic of "filling gaps where they exist" is failing.
How to solve this? At the Talent Sub-forum of the 2026 China Automotive Forum, guests gave the same answer: stop hoping to poach ready-made people from the market, but instead start training them internally.
Automotive Engineers Are Being Redefined
Why do HRs need to understand business more today? Because talent demand has changed.
In the past, what talent an automaker lacked, the answer was relatively clear. Engines, chassis, bodywork, processes, almost every position corresponded to a specific type of professional talent. HRs mostly handled matching positions and finding talent.
Today, companies discuss more about intelligent driving, large models, embodied intelligence, globalization... These changes ultimately affect the talent, and give the profession of automotive engineer a new profile.

Image Source: 2026 China Automotive Forum
Li Zhele, Secretary-General of the Automotive Talent Professional Committee of the China Talent Research Association, outlined the changes in automotive talent competency models in recent years. In the past, problem-solving ability was emphasized; now, complex problem-solving ability is emphasized more; in the past, learning ability was emphasized; now, rapid learning is required; in the past, it was more about imitative innovation; now, pioneering innovation is valued more and more. Among the six core competencies, almost every one has changed.
The changes appeared first in R&D teams. A set of survey data shared by Li Zhele shows that in 2025, software algorithm engineers at an eastern coastal automaker accounted for up to 70% of intelligent connected R&D personnel. Software developers in some top enterprises accounted for more than 50% of the R&D team.
This data does not negate the importance of mechanical engineering, but it shows the R&D team is changing. The knowledge system involved in automotive R&D is constantly expanding, extending from mechanical design to electronic electrical, software development, artificial intelligence, control engineering, and other fields. A single major is still important, but more and more positions start requiring interdisciplinary collaboration.
The growth pace has also quickened. In the past, it often took five to ten years for an automotive engineer from joining the company to independently undertake R&D work. Today, automotive R&D campus recruits can independently handle positions in an average of 19 months, in some intelligent connected components fields, it is even shortened to 15 months.
Research by Li Zhele's team on nearly 500 leading automotive talents also shows that talent with over 10 years of work experience accounts for 78%, the average age of leading talents is 37. The overall growth cycle of domestic leading talents has been shortened by 5 to 10 years compared to international peers.
The speed increased, requirements also improved. Li Zhele believes that in the future, more and more simple, certain, predictable tasks will be handed over to AI. Engineers will face more complex, uncertain, non-standard answer problems. That is to say, the automotive industry will not eliminate a certain major, but will eliminate people who stop evolving.

Image Source: 2026 China Automotive Forum
Similar judgments are also confirmed on the enterprise side. Geng Yi, General Manager of Changan Automobile's Industry-Education Integration Division, mentioned that today, the problems engineers face daily have gradually extended from component design to algorithm iteration, user experience optimization, and technology route selection. These problems are hard to complete relying on a single discipline, and standard answers rarely exist.
When the job profile of automotive engineers changes, those responsible for recruitment must perceive this change first. Li Zhele said a sentence: "HRs today need to know astronomy above and geography below, and also understand history. At least when meeting with business departments, you shouldn't be completely unable to understand what others are saying."
At first glance, this sounds like a requirement for HRs. But as the forum progressed, this statement received more specific annotations. The few automaker HR heads sharing next, almost none talked only about recruitment.
NIO Automobile HR Director Ding Wuxia concurrently introduced NIO's three brands, battery swapping system, and global R&D layout. XPeng Automobile Global Recruitment Director Dong Hanyu also first spoke about company positioning: besides cars, XPeng is also laying out ahead areas like flying cars, humanoid robots, with the goal of becoming a global embodied intelligence company. Afterwards, he elaborated on his thinking regarding recruitment talents.
This is not a coincidence in the sharing order. In the intelligent car era, what a company will do in the future, what kind of people it needs, and what capabilities these people must possess, can increasingly no longer be answered solely by job descriptions. The starting point of recruitment work has changed accordingly.
Recruitment standards are also adjusting accordingly. More and more companies are starting to seek composite talents who understand mechanics and are familiar with software, electronic electrical, algorithm fields, etc. Compared to a single professional capability, systems thinking and cross-domain collaboration capabilities are being mentioned more frequently.
Going Global, Another Talent War Battlefield
The domestic market is still adapting to this round of talent changes, globalization has pushed corporate talent demands to a new dimension. At the forum, multiple guests talked about going global, and the focus of the discussion was what kind of people enterprises need after 'going out'.
Li Kang, a member of the Committee for National Automotive Vocational Education Guidance of the Ministry of Education, divided Chinese car going global into three stages: product going global, brand and technology deep going global, and global ecosystem co-construction. Corresponding to different development stages, enterprise talent demands are also constantly changing.
Initially, enterprises relied more on expatriate teams, copying mature products, technologies, and management experience overseas. As business deepened, companies started establishing local R&D, manufacturing, and supply chain systems, with increasing demand for localized talent. Upon reaching the global operation stage, enterprises need to both establish unified talent standards and form cross-cultural collaboration and global management capabilities.

Image Source: Chery
Many enterprises have reached the second step, and some are even starting to move towards the third step.
Taking Chery as an example, it reactivated the local car brand Ebro in Spain, and participated in local industrial development through local production, brand operations, etc. Chery Chairman Yin Tongyue once proposed the concept of 'In somewhere, For somewhere, Be somewhere', hoping the enterprise can truly integrate locally, rather than simply selling products overseas.
In recent years, more and more Chinese automakers are starting to layout overseas factories, R&D centers, and supply chain systems. Products can enter the market, production lines can be replicated, what truly needs time to build is often people and organizations.
This point was reflected more concretely in Changan Automobile's sharing. Geng Yi mentioned that after the company entered the Thai market, there were labor disputes between Chinese and local employees regarding overtime culture. Compared to technology and products, these differences often have no unified answer.
From this, it can be seen that as Chinese automakers continue to enter new markets, enterprises need to face not only product certification and supply chain construction, but also a series of new topics including labor laws, talent development, organizational management, cultural integration, etc.
At the forum venue, many guests placed 'localization' in a more important position. Globalization layout has broken the talent boundaries of traditional localized operations. What enterprises need is not only R&D, manufacturing, and other professional talents, but also composite talents familiar with overseas regulations, cross-cultural communication, international operations, etc. As overseas business continues to expand, this talent gap is gradually appearing.
NIO chose to advance the globalization layout. Ding Wuxia introduced that NIO has always configured R&D resources according to globalization ideas. 'Where the talent is, NIO builds offices there.' In her opinion, when enterprises layout R&D centers, the first consideration is talent resources, rather than simply dividing by region.
Changan, however, focused its eyes on vocational education. It is promoting the 'Changan Workshop' project, building industry-education integration bases in overseas vocational colleges, hoping to combine enterprise standards, technical systems, and talent cultivation. Geng Yi stated that if Chinese brands hope to take root overseas long-term, just selling products there is not enough, it also needs to let local students familiarize with Chinese brands, Chinese technology, and Chinese standards.
Under this trend, the focus of enterprise concern has also gradually extended from 'selling cars out' to 'taking capabilities out'. This capability includes both R&D and manufacturing, as well as talent cultivation, organizational management, and cultural integration.
What enterprises lack going global is not just people who understand foreign languages. What enterprises hope to find are people who both understand the Chinese automotive industry and are familiar with local regulations, culture, and business environments. This type of talent can connect headquarters with overseas teams, and also help enterprises understand the operating rules of different markets.
Ultimately, It's a Race on Who Cultivates Faster
If in previous years automakers were still competing for talent, then another signal transmitted at this year's forum is that more and more enterprises are starting to focus their centers on cultivation systems.
The reason is not complex. Trends like intelligent driving, software development, AI large models, globalization, etc., put the industry in rapid change. This leads to talent needed by enterprises becoming newer, however mature talent in the market has not increased synchronously. Relying solely on social recruitment makes it difficult to solve long-term talent supply problems.
XPeng Automobile's Dong Hanyu shared a set of data. In 2025, XPeng's management and technical campus recruitment scale was about 500 people; in 2026, this number has already exceeded 1000 people; by 2027, the plan is close to 2000 people. Three categories of positions (management technical, production manufacturing, front-line sales) total campus recruitment scale will reach 5000 people.
Geely Group recruited more than 4000 fresh graduates in 2026. Geely Holding Group Senior Vice President Yang Xueliang said, "We internally call them wild geese. They are all one in a hundred, talented, and passionate young people. We hope they find their positioning on Geely's big stage and hone themselves."
The increase in number is just part of the change. Taking XPeng as an example, it is adjusting the entire talent strategy, shifting from the past dominated by social recruitment with campus recruitment as supplement, gradually towards a long-term model based on campus recruitment, young talent as the main body, and cultivation as key. By 2027, XPeng's campus recruitment proportion of total recruitment will increase from 50% to 70%.
Such adjustments are closely related to the development pace of enterprise business. In XPeng's view, AI has become the basic tool for R&D work. Young people contact new tools faster, learn faster, and adapt to new R&D ways more easily.

Image Source: 2026 China Automotive Forum
Around this idea, XPeng redesigned the fresh graduate cultivation mechanism. New employees implement separate performance and promotion management for the first three years after joining, not sharing evaluation channels with social recruitment employees, hoping to leave a more complete growth cycle for young talent.
Changan Automobile focuses on a more upstream link of talent cultivation. Geng Yi believes that enterprises adjust product and technical directions every year, while school talent cultivation plans usually take several years to complete an update, and there is always a time lag between the two.
In the past, the talent cultivation of many enterprises started from recruitment; now, more and more enterprises are turning their eyes to schools.
Changan established an independent legal person-operated industry-education integration company, hoping to bring enterprise demands forward into the talent cultivation link, letting curriculum settings, practical training content maintain closer connections with industrial development.
In Geng Yi's view, enterprise participation in schooling is not to lock students in advance, but to hope that the people cultivated by schools can adapt to the industrial development pace faster.
Schools also feel this change. Wuhu Vocational and Technical University School of Automotive and Aviation Dean Peng Ding shared a realistic problem. Enterprises may launch multiple new products and technologies in a year, while school talent cultivation plan updates require longer cycles. When rapid industrial change becomes the norm, schools also need to continuously adjust curriculum systems, practical teaching, and school-enterprise cooperation methods.
Facing new demands proposed by enterprises, schools no longer first consider 'can they do it', but 'how to do it as soon as possible'.
This change is not just curriculum adjustment. More and more vocational colleges are starting to introduce real enterprise projects into the classroom, letting students contact actual enterprise R&D and production scenarios during the learning phase, and also allowing enterprises to participate in talent cultivation earlier.
Compared to training after recruitment, this method brings the cultivation cycle further forward. NIO saw another type of change. New businesses such as direct sales systems, battery swapping networks, user communities, etc., are constantly developing, also giving rise to a batch of new positions that did not exist before. For many positions, there are no mature talents in the market for direct recruitment; enterprises can only explore business and cultivate teams at the same time.
According to introductions, NIO established a complete talent system around values, including goal setting, performance evaluation, incentive feedback, etc., hoping to help employees grow continuously during business development.

Image Source: BYD
Looking at them together, although companies like XPeng, Changan, NIO chose different paths, the focus points are getting closer and closer. That is to say, compared to finding ready-made talent, enterprises are starting to invest more energy in building long-term talent supply capabilities.
In the past, automotive enterprises relied more on the market to solve talent problems. Today, more and more enterprises are starting to build their own talent systems. And this change is still continuing.
It can be seen that the discussion of the entire forum has exceeded recruitment itself. Engineers need to face new technical systems, enterprises need to adapt to global competition, universities are adjusting talent cultivation models, more and more automakers are starting to shift the cultivation system forward. The change in talent work almost runs through every link of automotive industry development.
In the past, the automotive industry discussed more about how many people are missing. Nowadays, enterprises are more concerned about what kind of people are needed, and how to cultivate such people faster. Understanding business, understanding strategy, understanding industrial directions, has become an important prerequisite for judging talent demand.
And when the automotive industry enters a new development stage, talent competition also begins to enter a new stage.
Even since first shaking hands with FIFA in 1999, Hyundai Kia locked the World Cup official cooperation until 2030, Chinese automakers still took a different path, each opening a door for themselves.
Changan went to Lisbon, signed the Portugal national team; GAC dug into Mexico City, bound to the century-old club Toluca FC; Chery directly revived the Spanish local brand EBRO from decades ago, allowing it to stand by the Spain team as "one of them"; BYD and Geely though didn't touch teams, but via CCTV broadcasts and Xiaohongshu, stuffed the brand into fans' mobile phone screens.

A few years ago at the Qatar World Cup, Chinese automakers were still erecting billboards on the sidelines. A few years later, Chinese independent brands have learned to "take a detour to enter". In the past, many believed there was a cognitive barrier between Chinese automakers going global with products and going global with brands. Now, this is no longer a problem. From government procurement to youth training, from national team IP to local clubs, Chinese automakers are using the World Cup as a lever to complete the critical leap from "product going global" to "brand going global".
The Miracle of Cape Verde, BYD's Foresight
Many feel that the Cape Verde Ambassador to China announcing all national official vehicles will switch to BYD is a friendly diplomatic gesture. In reality, the strategy behind this decision is far more complex than it appears on the surface.
Cape Verde is composed entirely of islands, no oil and gas resources, fuel entirely imported. BYD gives not just cars, but a whole "PV + Electric Vehicle" solution. This approach is helping Chinese automakers open a government vehicle market previously held by German and Japanese systems. Several countries in West and East Africa, also struggling under fuel import costs, have started follow-up research.
And the gain BYD made from this matter in Cape Verde is far more than just a few government orders. From another angle, Cape Verde's World Cup dark horse story equaled a free global brand promotion for BYD. An island nation with 540,000 population, continuously drawing Spain and Uruguay to a stalemate, dragging defending champion Argentina into extra time, this not only made the world remember Cape Verde, but also made fans remember the BYD logo on Cape Verde's official fleet. The gold content of this brand exposure is higher than any ad placement. The Cape Verde Ambassador to China voluntarily announcing the procurement decision in front of media is equivalent to globally backing Chinese new energy brands with official status. This recognition is something money cannot buy.

For BYD, betting on a correct team is not the ultimate goal, the long-term gain behind each bet is the key. BYD previously supported the private youth training organization "China Football Minors", which has successively won the Thailand Asian Youth Cup and Italy's "Little World Cup". During the World Cup, BYD also funded Football Minors to go to Brazil and Mexico to play friendly matches with local power youth training teams. They walked into the Azteca Stadium to watch the World Cup match on site, and also visited BYD's overseas largest production base in Camaçari, Brazil. For these children playing football, seeing with their own eyes that Chinese brands own factories of such scale in a foreign land is more direct than any patriotic education class. For BYD, what this investment seeks is not what these children can bring today, but many years later, when these children become the backbone of society, their memory starting point regarding football, the world, and Chinese car brands is BYD.
Looking at these moves together, BYD's route is clear. Whether there is a FIFA official sponsor logo spot doesn't matter, start cultivating deeply from the soil of youth training, start infiltration from government procurement in African island nations, use CCTV and Xiaohongshu channels to reach consumers. The same money, spent on short-term exposure is a one-time consumption, spent on brand mindset building is compound interest. When other brands are still calculating ad conversion rates, BYD is already doing compound interest investment on brand assets.

After this World Cup ends, the dark horse popularity of Cape Verde will eventually fade, but BYD's charging piles and after-sales service network there will not withdraw; whether Football Minors will go to the World Cup in the future, no one knows, but those children's recognition of the brand will not disappear. What BYD wants is always the long-term benefits brought by three lines running in parallel.
Changan's 500 Million Bet, The Ambition of a New Central Enterprise Going Global Behind It
For this World Cup, Changan made a big gamble. On May 22, 2026, Changan Motors signed in Lisbon with the Portuguese Football Association, becoming the Portuguese National Team's Global Official Partner. 2026, 2030 two World Cups, plus two Women's World Cups, total investment over 500 million yuan, this is the first time a Chinese car brand has reached global cooperation with a European top football national team.
Choosing Portugal, what did Changan see? The 2026 US-Canada-Mexico World Cup is the 41-year-old Ronaldo's 6th, and also last World Cup journey. Ronaldo's Instagram followers exceed 660 million, global coverage over 1 billion fans. The distribution of Portugal team fans, just in Europe, Southeast Asia, Central and South America, Middle East Africa, highly overlaps with Changan's core going global markets. This is not generalized brand exposure, but a placement precise to user portraits.

As a new central state-owned enterprise, Changan has goals to achieve. After restructuring, Changan proposed the "1445" strategy, aiming to break into the top 10 global automakers by 2030, with overseas sales rising from 637,300 units in 2025 to 1.5 million units in 2030. In the first half of 2026, Changan delivered 402,000 units overseas, up 35.1% year-on-year, with overseas business share rising to 33.6%. Changan needs to accelerate towards its target. If the World Cup bet is correct, combined with Changan New Energy's "Shangri-La Plan" cumulative investment exceeding 100 billion, and the confidence brought by core technologies like "Golden Bell" battery and solid-state batteries, it will have a good positive significance for achieving its goals.

Of course, this 500 million bet also has risks. Portugal group stage 1-1 draw Congo (DRC), 5-0 win Uzbekistan, 0-0 draw Colombia, qualify as group second, then eliminate Croatia. Round of 16, Portugal plays archrival Spain. Although ultimately defeated, Ronaldo's influence is enough to enable Changan to leverage larger global volume. However, for Changan, this account is not calculated for short-term ROI, how much position this money can make the brand occupy in global consumers' hearts, is the more important thing.
From "Detour" to "Rooting", Playing a Differentiated Chess Game
FIFA automotive official sponsorship is locked by Hyundai Kia until 2030, for many Chinese car manufacturers, this is not a big problem. GAC, Chery, Geely take a detour to "open doors", each playing a differentiated chess game.
GAC chose the "Localization" route, signing a two-year strategic partnership with Mexico's Toluca FC directly this May. Toluca FC was founded in 1917 and has won the CONCACAF Champions Cup three times. In 2025, China exported 625,200 vehicles to Mexico, which has surpassed Russia to become the top destination for Chinese car exports. GAC binding with Toluca FC equates to embedding the brand into Mexico's fervent football culture, completing the leap from "entering the market" to "taking root in the market".

Chery's approach is more subtle, not sponsoring the Spanish national team in the name of "Chery", but reviving the Spanish domestic brand EBRO born decades ago, also considered a "roundabout way to save the country". In April 2024, Chery signed an agreement with Spain's EV MOTORS under the witness of Prime Minister Sanchez, establishing a joint venture in Barcelona to restart EBRO. In 2025, EBRO became the official sponsor of the Spanish National Football Team. At this World Cup, Spain topped the group stage with 2 wins and 1 draw, eliminated Austria 3-0 in the Round of 16, and won 1-0 against Portugal in the Round of 8 to advance to the quarterfinals, with zero goals conceded in six games so far. EBRO's brand logo continues to appear before global fans with every victory of the Spanish team.
Some might wonder why Chery uses a hidden approach to back the team? In fact, gaining local recognition for a brand going global is a matter to be planned for the long term, selling cars before this is equally important. For Chery, whether the logo on the steering wheel is EBRO or Chery makes no difference to Chery's financial reports. For Spanish consumers, this is "a local brand supporting a local team". Chery hiding behind the curtain easily gains emotional recognition from local consumers, so why not? Chery's overseas performance has always been "capable", and after this World Cup, Chery's overseas "gains" may continue to amplify with the team's performance. The approach of "technology empowerment + local brand" can instead yield real profits.

Geely chose another path: "Focusing back" on the domestic market. Geely Galaxy became a partner for the CCTV World Cup broadcast, exclusively naming CCTV-5's "The Football Grand Banquet", simultaneously launching "Football Carnival Season" distributing car purchase vouchers daily. The Galaxy brand's main battlefield is domestic; borrowing this World Cup super IP to complete a leap in brand popularity is the most cost-effective choice. Meanwhile, Geely's Mexico subsidiary offered free airport pick-ups for car owners watching matches during the World Cup, equivalent to building the brand domestically and providing service overseas, running both lines in parallel.

Three roads, three judgments, but pointing to the same conclusion: Chinese car manufacturers' going global path is no longer as simple and straightforward as before, independent brands have begun to seek "smarter" paths.
Conclusion
BYD proves the value of long-termism through multiple lines; Changan declares the determination of a new central enterprise going global with a 500 million bet; GAC, Chery, and Geely demonstrate the diverse possibilities of Made in China through differentiated paths. And what is more comforting than these is that Chinese automakers are no longer obsessed with "selling products" or finding "ad spots". Building brands and setting up ecosystems on global stages like the World Cup means that Chinese independent brands now have the major premise for victory in their "extra time" on the world arena.
In the first half of 2026, auto sales broke the 15 million mark, and exports are becoming an important growth point.
Data from the China Association of Automobile Manufacturers (CAAM) shows, the monthly auto export volume broke 1 million in June for the first time; from January to June, cumulative auto exports reached 5.096 million, a year-on-year increase of 65.3%, achieving over 5 million in semi-annual exports for the first time. Regarding the annual trend, CAAM remains cautiously optimistic, with full-year exports expected to break 10 million.

In contrast to the frantic expansion overseas, the domestic market can simply be described as bleak. NIO Li Bin called for the industry to prepare for a 15%-20% year-on-year decline in domestic auto retail volume for the full year of 2026. Data shows that the first half of the year became the most prominent feature of the car market: "strong exports, weak domestic sales." Automakers that fail to achieve a global layout in the future will find it difficult to withstand market cycle fluctuations.
1
Auto Exports Exceed Domestic Sales for Some Manufacturers
The domestic auto market is undergoing a deep adjustment. In the first half of the year, auto production and sales reached 14.993 million and 15.017 million respectively, down 4% and 4.1% year-on-year respectively. Against this backdrop, exports became the key engine driving the growth of China's auto industry, and also brought high-speed growth to auto exports after two years of adjustment.
Looking specifically. In June, auto exports were 1.037 million, increasing 11.6% month-on-month and 75.1% year-on-year, with monthly export volume breaking 1 million for the first time. From January to June, auto exports were 5.096 million, up 65.3% year-on-year. More noteworthy is the structural change—the share of export sales in total production has climbed to 39.34%. This means that for every 10 cars produced domestically, nearly 4 are heading to overseas docks.
Against this backdrop, multiple automakers saw overseas market performance hit new highs.
Among them, Chery Group ranked first with export performance of 943,800, a 71.5% year-on-year increase, with overseas sales accounting for more than 70%. This automaker that has long cultivated the overseas market, exported 191,000 units in June alone, a 79.7% year-on-year increase. A more milestone signal is that Chery's cumulative exports have officially broken the 6.78 million mark.

Not just Chery, the current growth momentum of the entire Chinese auto market comes from overseas market export performance. BYD: Overseas exports 789,400, accounting for 43% of total sales; going overseas has become an important certain link; SAIC Motor Group: exported 735,000 in the first half of the year, up 48.7% year-on-year; Since Chen Jiacai took charge of GAC International 8 months ago, GAC Group's overseas offensive speed has significantly accelerated, exporting 121,000 in the first half of the year, up 132% year-on-year, close to last year's full-year level.

Putting the export data of these automakers together, a clear trend can be seen: the overseas market is becoming the core pillar driving the overall growth of automakers. Especially against the backdrop of domestic market demand peaking, profit pressure, and fierce competition, the overseas market has officially upgraded from "incremental supplement" to "core growth pole." It can be said that the more intense the domestic market competition, the stronger the urgency for Chinese automakers to go overseas.
2
Trade Barriers Are an Inescapable Reality
The deep reasons supporting this wave of export explosion are timing, location, and people. First is timing—the global auto industry is transforming towards electrification; second is location—the Chinese auto industry chain is resilient; third is people—independent brand enterprises are working hard. Overall, China's auto going global is at the best time, and presenting a good situation of "blooming in multiple points globally."

In 2023 and 2024, Russia has always been China's number one auto export destination. But looking at the past two years, China's export volume to Russia has declined. In the first five months of this year, Brazil surpassed Russia, becoming China's number one passenger car export market. In addition, the UK, Australia, and Mexico follow closely behind.

Above the top ten overseas markets, the UK, Belgium, and Italy are all located in Europe. In the competitive landscape of the EU auto market, Chinese independent brands have gradually become stronger. In May this year, five Chinese automakers—BYD, SAIC, Geely, Chery, and Leapmotor—sold a total of 138,400 units in Europe, an increase of over 60% year-on-year, while Japanese automakers' sales were 130,000 units, down 3%. Chinese autos surpassed Japan in the European market for the first time, with a market share reaching 12.01%.
Being able to enter Europe shows that our products can already meet the needs of consumers in developed countries, further proving the increasingly solid overseas competitive strength of China's auto industry. However, the hidden realistic challenges behind the high-speed development are equally impossible to ignore. For example, the EU is building walls, Brazil is raising taxes, Thailand is tightening, and the US is blocking. Global major auto markets are all setting up barriers for Chinese cars. The overseas expansion path of Chinese automakers is still full of challenges.

But Chinese automakers' response is much faster than expected, and they are laying out overseas strategies based on their own situations. Including Chery, BYD, Geely, etc., all set up production bases, R&D centers, and service networks overseas. Meanwhile, GAC Group announced plans to deploy 242 fast-charging stations in Brazil before 2030. The overseas competition of Chinese automakers is no longer just about selling cars, but starting to compete on who can truly stay locally, moving towards true globalization management.

Monthly exports breaking 1 million, 5.096 million vehicles exported in the first half of the year—not only is this a beautiful report card, but also a real breakthrough for Made in China in the global market. This year's 10 million export goal is also within reach, but more important than numbers is whether Chinese autos can establish sustainable competitiveness in the global market. In the future, China's auto globalization will enter the deep water zone, competing no longer on short-term sales, but on long-term systemic capability and global operational wisdom.
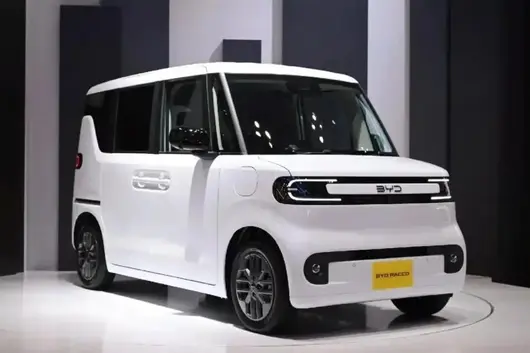
In 2026, domestic passenger cars may say goodbye to the high-growth era, officially entering an adjustment phase characterized by deep competition in the stock market and dual pressure from supply and demand. Slowing growth and profit contraction are stage challenges faced by the entire industry. Latest data from CPCA shows that in June, domestic passenger car retail sales reached 1.602 million units, down 23.2% year-on-year; cumulative retail sales from January to June were 8.701 million units, down 20.2% year-on-year. The entire product category market weakened synchronously, fuel vehicle retail sales plummeted 39% year-on-year. Domestic sales of joint ventures, luxury, and independent brands generally faced pressure. Most automakers saw varying degrees of decline in domestic terminal sales. Increasing revenue without increasing profit has become the industry norm.
Looking at the market performance from the first half of 2026, the automotive industry shows typical cycle adjustment characteristics. Whether traditional independent, leading new forces, or mainstream joint venture brands, all face varying degrees of operational pressure.

Seres Zhang Xinghai revealed at the Chongqing Auto Forum that the price of storage chips rose by more than 400%, and lithium carbonate prices doubled year-on-year. The unit cost for all AITO models under the brand increased by 15,000-20,000 yuan. Cost pressure directly led to the company's H1 performance forecasted loss of 1.05 billion to 1.3 billion yuan. Chips and battery materials are the core sources of cost increases. Voyah Lu Fang publicly stated that chip cost increases for high-end smart models broke through 300% at most. Basic consumables such as copper, aluminum, and plastics rose in price synchronously. The added cost per smart vehicle exceeded 12,000 yuan. The industry generally faces a dilemma of 'rising costs, dare not raise prices'.

Terminal market demand is weak, price wars are fierce. Automakers dare not easily increase selling prices. Upstream raw materials and chip costs rose rigidly. Profit margins are squeezed from both sides. This round of industry downturn is industrial periodical pain formed by the superposition of multiple pressures: weak consumption, skyrocketing upstream costs, overcapacity, and normalization of price wars.
This round of adjustment is a necessary stage of industry development. Short-term pressure will force the industry to eliminate inefficient capacity and homogeneous products, accelerating high-quality enterprises to complete value upgrades. Facing a unified cycle dilemma, domestic leading automakers have escaped the mindset of passively responding to price wars. They have formed systematic, long-term breakthrough strategies, focusing on four core main lines: Opening a second growth curve through global overseas expansion to offset domestic stock bottlenecks; Escaping homogeneous price involution through differentiated new product matrices; Building long-term barriers with full-stack technology self-research to stabilize cost advantages; Achieving cost reduction and efficiency gains through channel model iteration, digging deep into user value.

In sharp contrast to the domestic market downturn, automotive exports have become the core engine for industry growth against the trend. CAAM data shows that in June, domestic automotive vehicle exports reached 1.037 million units, up 11.6% month-on-month and surged 75.1% year-on-year. Monthly export volume exceeded one million units for the first time. Cumulative exports in the first half reached 5.096 million units, up 65.3% year-on-year. Among them, new energy exports grew by more than 120%. Overseas markets effectively offset domestic demand gaps, forming a new industry pattern of 'domestic pressure, overseas volume'.
Opening a second growth curve through global overseas expansion to offset domestic stock bottlenecks:
Chery maintains its position in the first tier of independent overseas exports. Cumulative exports in the first half reached 943,800 units, up 71.5% year-on-year. Exports accounted for nearly 70% of total sales. Relying on local factories in Southeast Asia and South Africa, it digs deep into emerging mass markets, effectively offsetting the pressure of domestic market involution. BYD exported 789,000 units in the first half, up 70.5% year-on-year. Overseas sales accounted for 43.6% of the group's total sales. Relying on localized capacity in Hungary and Thailand to layout European and Southeast Asian markets, it aims to achieve balanced domestic and overseas sales development, effectively offsetting domestic price war profit pressure, and relying on scaled industrial output to establish global cost and channel advantages. Changan Automobile delivered 402,000 units overseas in the first half, up 35.1% year-on-year. Relying on the 'Hai Na Bai Chuan 2.0' strategy to dig deep into emerging markets, Thai and Brazilian local factories continue to go into production. Building overseas localized operation teams and after-sales systems, focusing on exporting hybrid and smart models, using highly adaptable products to seize incremental markets in Southeast Asia and South America. Overseas sales continue to grow steadily, becoming a stable second growth curve;

Escaping homogeneous price involution through differentiated new product matrices:
In a cycle environment of severe overcapacity and product homogenization, automakers generally abandoned 'full-line low-price involution', turning to multi-brand layering, precise positioning in niche tracks, and product strategies where new and old technologies run in parallel, improving overall profit quality through structural optimization.
BYD insists on full price range coverage. Relying on the Dynasty, Ocean, Denza, Yangwang matrix, it covers household mainstream, mid-to-high-end, ultra-luxury markets. Fuel, hybrid, and pure electric are fully iterated. Solidifying the basic board with an extreme product matrix, it increases the proportion of high-margin products through vehicle structure upgrades. Changan Automobile builds a five-brand collaborative system. Qiyuan focuses on affordable hybrid home markets. Deep Blue focuses on mainstream pure electric. Avatr positions itself in high-end smart pure electric. Changan Passenger Cars stabilizes the fuel basic board. Kaiceng digs deep into commercial markets. Full price range differentiated layout, avoiding internal involution, precisely matching different segmented user demands. Geely relies on Thor Hybrid and Galaxy Pure Electric dual product lines, focusing on high cost-performance home new energy markets. Continuously iterating energy-saving hybrid models, seizing fuel vehicle replacement space. At the same time breaking through upwards with Lynk & Co luxury, optimizing overall product structure.

Building long-term barriers with full-stack technology self-research to stabilize cost advantages:
Second half of industry cycle, short-term competing on cost, mid-term competing on products, long-term competing on technology. Leading automakers continue to increase investment in core technology self-research, achieving autonomy and controllability in three-electric systems, smart driving, chips, and hybrid platforms. Offsetting cost volatility from the root and building differentiated competitiveness.
BYD insists on full industrial chain self-research and self-production. Second-generation Blade Battery, high-voltage flash charging technology fully iterated, achieving fuel and electric same-speed refueling experience. Relying on vertical integrated supply chain advantages, it stabilizes cost advantage during raw material fluctuation cycles, forming unreplicable industrial barriers. Xpeng focuses on full-stack smart driving self-research. Continuously optimizing urban NGP, full-domain intelligent assist driving system. Using smart technology as core label, building differentiated product competitiveness, escaping specification involution. Li Auto focuses on vehicle-mounted large models, self-researched computing power chips. Focusing on smart cockpit and whole vehicle smart interaction upgrades. Relying on high computing power hardware and localized smart ecosystem, building high-end smart experience barriers, supporting brand premium. Changan Automobile continues high R&D investment. Digging deep into three core technologies: Blue Whale Super Engine Hybrid, self-researched Tianshu Smart, Golden Bell Shield Solid-state Battery, achieving autonomy and controllability in hybrid, smart, and battery technologies. Both supporting domestic product differentiated upgrades, also providing core technology endorsement for overseas models.

Comprehensive mainstream automaker cycle response actions show that the current domestic automotive industry is experiencing a round of deep adjustment. This is a natural periodic correction after years of scaled expansion. Narrowed profit space and slowed market sales growth are stage problems faced by the entire industry. This does not mean the development momentum of leading automakers has stalled. Need to view the industry status objectively with a long-term industrial perspective.
Through short-term market pain, the automotive industry's three long-term upward development trends remain stable and unchanging. First, electrification and intelligence transformation are already irreversible core main lines of the industry. New energy and smart cars will continue to replace traditional fuel vehicles, reshaping market patterns. Secondly, the trend of Chinese car exports is strong. Overseas market share steadily climbing. Globalization development dividends are still being released continuously. Finally, industry reshuffling accelerates. Market resources are concentrating on leading enterprises with complete overseas layouts, core self-research technologies, and multi-brand differentiated product matrices. Advantaged automakers will continue to seize the market at the bottom of the cycle.
Leading automakers represented by BYD, Geely, Changan did not passively respond to short-term market pressure. Instead, treated this round of cycle as a key window for strategic power accumulation. Synchronously increasing global layout, new product launch, and underlying core technology R&D. Solidifying long-term competition foundations. Price competition and profit pressure are just inevitable pains of industry survival of the fittest. High-quality automakers with global strategies, full-stack self-research technologies, and layered differentiated product systems possess strong risk resistance capabilities. They are able to safely traverse the industry downturn cycle, welcome greater development opportunities in the next round of industry upswing.
Recently, MG returned to its brand birthplace, the UK, held a technology sharing session in London, then rushed to the Goodwood Festival of Speed for the global premiere of two concept cars. MG Go! Agile Pure Electric Small Car and Cyber Concept Coupe SUV appeared together. On one side was the century-old British racing heritage, on the other, mature and complete Chinese intelligent electric technology. The two events did not deliberately create a buzz, yet calmly demonstrated the posture of Chinese automakers looking globally and proceeding steadily, and also just confirmed the outstanding results SAIC achieved in its overseas market in the first half of this year.

MG GO! Concept Car

MG Cyber Concept Car

Overseas Half-Year Sales Continue to Rise Steadily
In the first half of 2026, SAIC's overseas market was very fruitful, with cumulative exports reaching 735,000 units, up 48.7% year-on-year; looking at June alone, overseas sales reached 146,000 units, surging 61.2% year-on-year, setting a new sales record, consistently ranking in the first tier of Chinese automakers going global.
As the backbone of SAIC's overseas layout, MG has topped the sales of Chinese brands in Europe for 11 consecutive years, and is also the first Chinese automotive brand with cumulative sales exceeding 1 million units in Europe. In the first half, MG sold over 190,000 units in Europe, and MG4 Urban has entered mainstream households in Germany.
Looking at the global map, Europe has grown into a key 300,000-unit level market for SAIC. The five major regions of Americas, Middle East, Australia-New Zealand, ASEAN, and South Asia have stably maintained sales volumes in the 50,000-unit level. Today, SAIC's business covers over 170 countries and regions, with overseas cumulative sales exceeding 7 million units. Not only was passenger car performance outstanding, SAIC commercial vehicles also opened a new track, with SAIC Hongyan securing an order for 1,000 new energy heavy-duty trucks in Thailand, breaking the situation of foreign brands monopolizing the local heavy-duty truck market. Passenger cars and commercial vehicles proceeding on two lines, coordinating to explore overseas markets.
Diverse Products Calmly Adapt to Global Diverse Needs
Outstanding market performance has never come from piling up low prices and sales volume. Core confidence comes from SAIC's self-developed technology honed over many years. MG has built three mature technology systems facing the global market: Hybrid+ Hybrid System, SolidCore Semi-Solid-State Battery, and i-Smart Intelligent In-Vehicle System.


Scene of MG UK Technology Conference
At the London Technology Conference, MG fully displayed the full set of intelligent electric technologies, and is also the first automotive brand globally to achieve mass production implementation of semi-solid-state batteries. IM AD Intelligent Driving adapts to road conditions on all five continents. MG Parking Smart Cockpit is finely tuned for overseas driving habits, and overseas i-Smart infotainment activation volume has exceeded one million. The two concept cars debuted at Goodwood extracted the design core of MG classic racing cars, fused with new aesthetics of electrification, balancing brand history and future mobility imagination.
In the next three years, SAIC will gradually launch global new products. Powertrains cover four types: Fuel, Hybrid, Plug-in Hybrid, and Pure Electric. More than 10 sedan, SUV, MPV, and Pickup models will be launched successively to the market, balancing various scenarios such as city commute, family travel, outdoor self-driving, and high-end driving, gently covering global mainstream sub-markets.
Glocal Strategy Deeply Cultivates Locally According to Local Conditions
Many automakers going overseas are accustomed to directly copying domestic products and operation models, applying one standard to adapt to all regions. After landing, it is easy to be incompatible and difficult to fit local users' real driving habits. SAIC chose to walk the Glocal global localization route, doing no one-size-fits-all, slightly adjusting products and services according to regional characteristics of different markets.
European highway network is developed, regulations are strict, so targeted optimization of chassis tuning and intelligent driving logic was done. The Middle East has high temperature all year round, specially strengthened three-electric system heat resistance protection to ensure stable vehicle operation in high-temperature environments. Indian daily commute scenarios are special, continuously iterating cockpit interaction functions to fit local driving preferences. Central Asia cooperated with local automakers to land production, with SAIC Volkswagen multiple new cars landing in Uzbekistan, completing regional market layout breakthrough. Thailand launched MG SMILE exclusive service system, providing lifetime warranty for three-electric systems for pure electric models, sorting out local after-sales chaos. Currently, local MG ownership volume has exceeded 250,000 units.
Building a Full-Link Overseas Ecosystem
True long-term globalization has never been short-term whole vehicle export, but slowly building a complete overseas system integrating technology, products, production, and service. This is also the key to SAIC's overseas market having stronger risk resistance capabilities.
On the production level, emerging markets such as Central Asia and West Africa cooperated with local enterprises to build factories, production on site compresses transportation costs, steadily digging into incremental space. On the service level, building European direct sales outlets in Belgium and Luxembourg, offline service stores exceed 2,000, matching long-term warranty in various places, eliminating overseas users' driving concerns. On the operation level, relying on local teams to face consumers directly, timely capturing market changes, slowly completing the transformation from "selling cars" to "operating users with heart and accumulating brand reputation".
From simple whole vehicle export to full value chain overseas of technology, manufacturing, and service, MG's two appearances in Britain this time is exactly a true portrayal of the steady growth of China's automotive industry. Relying on the calm and pragmatic Glocal globalization system, SAIC has shined the "China Intelligence" sign in the global market, leading Chinese automotive brands to complete the solid advance from simple "Going Out", to securely "Walking Steady, Walking Far".
The first half of 2026, China's car market produced a somewhat complex performance report.
Data from the CPCA shows that domestic passenger vehicle cumulative retail sales reached 8.701 million vehicles from January to June this year, a year-on-year decrease of 20.2%. Affected by the contraction in total market volume, the sales growth rate for the vast majority of automakers slowed down in the first half, and annual growth targets came under pressure.
This is because the era where "delivery volume" determines ranking and success or failure has passed. With the fuel vehicle base accelerating its momentum loss, volatility in overseas policies intensifying, and the industry's average profit margin dropping to the 3.4% warning line, the competitive dimension of China's car market is shifting from "scale competition" to "structural generation gap".
Behind the sales figures, the invisible gap that truly determines life or death has already widened.
The sales landscape has changed again
Gasgoo statistics on the sales situation of nearly 20 automakers in the first half showed a clear step-like distribution.
SAIC Group returned to the sales summit with 2.045 million vehicles, becoming the only full-vehicle group to break through 2 million vehicles so far. This time SAIC returned to first place, relying on the combined efforts of independent brands, new energy vehicles, and exports, achieved through a "radical reform" upon itself.
BYD cumulative sales for the first half reached 1.809 million vehicles. Although the domestic market had declined, relying on overseas market growth, it welcomed a recovery momentum of 403,500 vehicles in June.
Geely (1.423 million) and Chery (1.358 million) are accelerating the chase from behind, further narrowing the gap with the top two. The top tier formed by these four no longer competes on how many of a single blockbuster car was sold, but on whose full industry chain turns faster and whose overseas channels are deployed deeper.

Compared to the blossoming of the top tier, the survival status of the second sales tier exposes the cruelest side of this elimination race: the incremental volume of new energy vehicles is starting to fail to fill the gap left by the decline in fuel vehicles.
Changan is like this, selling 1.196 million vehicles in the first half, a year-on-year decrease of 17.4%. The problem it faces is that the speed of the decline in the fuel vehicle front exceeds the replacement speed of new energy brands.
GAC Group cumulative sales for the first half reached 773,000 vehicles, up 2.4% year-on-year, with moderate performance, urgently needing a new blockbuster. Perhaps the Qijing brand, built with Huawei, could be the breakthrough. Great Wall (584,000) increased slightly by 2.5%, but under the double-pronged attack from rivals on plug-in hybrids and pure electric, the shortcoming of a low proportion of new energy vehicles continues to drag down the overall market.
In this dramatic structural change, the confrontation between the camps of emerging new forces and joint venture brands is exposing deeper differences.
New forces have mostly achieved impressive growth rates. Leapmotor sold 356,000 vehicles in the first half, soaring 65% year-on-year. Zeekr, NIO, and Harmony Intelligent also had fierce offensives, especially the former two with year-on-year growth rates exceeding 60%. However, brands like Li Auto and XPeng encountered sales declines due to insufficient new product competition.
NIO's sales breakthrough was largely thanks to mutual support from three major brands: NIO, Onvo, and Firefly. For example, in an environment where the industry generally relies on aggressive pricing to exchange price for volume, Onvo delivered 42,000 vehicles in the first half, and the average transaction price held above 240,000 yuan, achieving a balance between sales growth and price stability, helping NIO achieve significant improvement in performance fundamentals.
Conversely, foreign brands continue to face pressure in China. CPCA data shows that retail sales of mainstream joint ventures decreased by 34% in June. Among them, SAIC Volkswagen shrank by over 30% in the first half, and GAC Honda was directly halved to 68,000 vehicles. The core issue foreign brands face in China remains how to break the inertia of momentum loss caused by the contraction of the fuel vehicle base and achieve scale effects in the new energy market.
Saying goodbye to broad rises, new energy vehicles enter the structural competition stage
No denying, new energy vehicles remain the deciding factor for the overall car market. In June this year, the retail penetration rate of domestic new energy passenger vehicles soared to a historical high of 62.8%, while pure fuel vehicles plummeted by 42%. But upon closer inspection, the bonus period of broad rise in the new energy market has ended.
As CPCA Secretary General Cui Dongshu put it, the new energy market is sliding towards a polarization of "high-end explosion, low-end pressure".
Data is the most direct microscope. In June, wholesale sales of Class B pure electric vehicles surged by 37% year-on-year, while sales in the A00 class pure electric market, serving as entry-level commuter tools, were directly halved by 50%. Consumers no longer buy simply for green license plates or cheapness, but have focused their gaze on products with higher configurations and stronger intelligent capabilities.
In this structural reshaping, resources are accelerating to converge at the top. Only 20 new energy automakers achieved wholesale sales over 10,000 in June, yet they accounted for 94% of the market share. Among them, independent brands took over more than 60% of the share, emerging new forces split 26%, while the share left for mainstream joint venture brands was only 4.3%.

But even within independent brands holding absolute advantages, differentiation is intensifying.
BYD locks the leading position thanks to coverage of the full price range. Geely advanced on dual lines of plug-in hybrids and pure electric vehicles, with new energy scale reaching 800,000 in the first half, and penetration rate approaching 60%. In contrast, while new energy transformation at companies like Chery, Changan, and Great Wall is accelerating, penetration rates still hover around 30%.
And in the new forces camp, the generation gap in growth rates often depends on who can trickle down high-end technologies to the mainstream market.
Leapmotor is a typical representative, with June sales reaching 93,000, far exceeding Li Auto, XPeng, NIO, etc. The explosion of Leapmotor is essentially based on full-domain in-house R&D cost control capabilities, building an SUV product matrix in the core market under 200,000 yuan, turning intelligence and high configuration into inclusive products. This extremely lethal cost-performance strategy allowed it to expand its market share under the general market pressure on the low end.
Different from Leapmotor relying on a full-spectrum blockbuster to break out upwards, NIO is achieving technology spillover downwards through sub-brands. For example, its sub-brand Onvo leverages NIO's system technology and battery swapping network, bringing 900V high-voltage architecture, self-developed chips, and operating systems, originally belonging to flagship models, into the 200,000 to 300,000 yuan family vehicle market, solving refueling anxiety for pure electric users.
In contrast, due to new products being in a replacement vacancy period or lacking sufficient competition, growth rates for some automakers like Li Auto and XPeng slowed to varying degrees in the first half.
Market increments are accelerating to concentrate at top automakers. Players who can continuously produce blockbusters and build full-spectrum matrices are building competitive barriers higher and higher.
Overseas competition has entered the "deep water zone"
While reshaping the domestic market competition landscape, the overseas market has become the second growth pole that almost all automakers are vying for.
In June this year, domestic passenger vehicle exports surged 82.3% year-on-year to 877,000 vehicles, with new energy exports soaring 152.7% even more. Exports are no longer garnishes on automaker financial reports, but have become key variables influencing the overall market.
However, in the second half of going overseas, the focus of competition has shifted from "how many cars were exported" to "whether one can establish global operations and risk resistance capabilities". In other words, single trade-type exports are entering a downward phase, while overseas localization production and globalization system construction are becoming the invisible gap that truly widens the generation gap between enterprises.
In this global leap, the differentiation at the top has already begun to show signs.
Among the automakers, Chery remains a typical "global harvestor" domestically, with cumulative exports reaching 944,000 vehicles in the first half, achieving a high-speed growth of 71.5%. Its export scale ranks first in the domestic automotive industry, with overseas sales accounting for nearly 70% of total sales. The channel advantages formed in Latin America, the Middle East, and Russia have built a very thick survival foundation for Chery.
More worthy of attention are players like BYD who are completing the leap from exporting products to exporting systems. With overseas factories in Thailand, Brazil, etc., gradually starting production, BYD's overseas sales climbed to 789,000 vehicles in the first half, nearly doubling year-on-year. Its overseas sales have accounted for 40% of total sales. This approach of "building factories in the opponent's home base" is the best way to avoid tariff barriers and achieve localization rooting.

At the same time, Geely and Changan are also accelerating tactical shifts. Geely accelerated the overseas launch of affordable series like Starship, recording an export scale of 474,000 vehicles in the first half, with June alone breaking 100,000 vehicles. Changan pulled export growth by 35% to 402,000 vehicles through overseas efforts on new energy models like Deepal and Qiyuan.
While some are accelerating, others are bearing the pressure of defending their city. SAIC exported 735,000 vehicles in the first half. Although relying on the MG brand for deep cultivation in Europe, Southeast Asia, etc., maintained stable shipments, it has already shown signs of being overtaken by Chery and BYD in the landing pace of overseas localization capacity. With competitor localization factories in Europe and Southeast Asia gradually starting operations, if SAIC cannot quickly upgrade overseas system bonuses, its past first-mover advantage will face the risk of continuous erosion.
In the new forces camp, Leapmotor took another shortcut. It cooperated with the international giant Stellantis, leveraging the latter's global channel network and production bases. Its overseas scale quickly approached 100,000 vehicles in the first half, successfully walking a path of light assets and high-efficiency globalization.
XPeng is also accelerating the expansion of the overseas market. In the first half, its overseas sales reached 32,000 vehicles, up more than 70% year-on-year, increasing the proportion of total sales to about 20%. Chairman and CEO He Xiaopeng had explicitly stated the strategic goal of "half of sales coming from overseas in the next ten years".
XPeng tries to bet directly on the global battlefield by self-operating technology, putting intelligent advantages there. Currently, the results of this strategy are initially visible. But under the current international geopolitical environment, this will put extremely high cross-cycle requirements on the enterprise's overseas supply chain elasticity.
Especially, this year's demand fluctuations in some Middle East markets, and the uncertainty of the global trade environment, objectively tested the risk resistance cycles of each automaker. The traditional single trade model relying solely on domestic production and sea shipping exports, when facing overseas policy adjustments, has a relatively short defensive depth.
This also means that the focus of competition in the second half of going overseas is no longer the frequency of sea shipping logistics, but the construction and landing of overseas localization capacity.
How to break through the final exam in the second half?
The data of half a year is just the process. What the market truly cares about is: Can the sales targets set at the beginning of the year still be completed?
According to Gasgoo Auto Research Institute's forecast, China's passenger vehicle wholesale sales in 2026 will be about 29.634 million vehicles, a slight decrease of 1.4% year-on-year. The overall market is basically treading water, meaning any automaker's growth must snatch food from opponents' mouths. At the node of the first half ending, the gaps in completion rates among each family have already widened.
BYD has not publicly disclosed clear annual sales figures, but forecasts given by UBS and other institutions are around 5 million vehicles. Supporting this massive volume is domestic full price range product coverage and the continuous release of overseas capacity. With the production launch of factories such as Thailand and Brazil, BYD's overseas expansion has upgraded from product output to system output.

Among automakers that have disclosed specific goals, Geely and Chery have higher completion rates, both around 40%, with both having clear sales pillars supporting them.
Geely's new energy penetration rate broke through 60%, running volume on dual lines of plug-in hybrids and pure electric. In the second half, its domestic market will continue to harvest 100,000 to 200,000 yuan mainstream new energy share through models like Starship E5 and Starship 7, and plans to enter the mid-to-high-end track through new products like Starship TT. Overseas will leverage affordable vehicles of the Starship series to land in Europe for volume boosting, and target overseas high-end premium markets with models like Zeekr 9X, thereby hedging against domestic involution.
Chery's overseas exports shoulder nearly 70% of sales, with channel bonuses in markets like Latin America, Middle East, Russia still being released. In the second half, Chery puts its focus on Europe and emerging markets. Through the new brand LEPAS, hybrid flagship layout in Europe, and model launches like Exeed ET8 in Russia and Central Asia, it uses a strategy of blossoming in multiple points to maintain lightweight growth throughout the year.
In contrast, Changan and Great Wall are the two with low completion rates. Changan's annual target is 3.3 million vehicles, completed 36% in the first half. In the second half, the ramp-up speed of new models like Deepal L05, Qiyuan Q06, Avatr 07 L, etc., will directly affect Changan's sales.
Great Wall's completion rate is also around 30%. Its Tank series stabilized the basic platform of hardcore off-road through plug-in hybrids, but the real volume-driving Haval brand lacks an absolute blockbuster in the new energy mass market. In the second half, whether new models like Tank 300, Haval H10 can tear open a breakthrough in the mainstream new energy market is the variable for Great Wall to reverse the situation.
SAIC also faces considerable pressure to achieve an annual target of 5 million vehicles. Its core highlights for the second half lie in whether the incremental release of new energy models like IM Motors and STELATO Z7 can be released, and whether the decline amplitude of the joint venture basic platform can be narrowed.
In the new forces camp, second half pressure also shifted to rapid volume increase of new product sequences. Leapmotor's annual target is 1.05 million vehicles, completing 30% in the first half. To achieve the target in the second half, monthly average sales need to be pulled to above 110,000. Besides the C-Series holding the basic platform under 200,000 yuan, the high-end D-Series and Lafa5 Series will become the main attackers for volume boosting.
NIO anchors its annual growth target around 40% (about 450,000 vehicles), betting most of the increment on Onvo. In the second half, as flagship models L90, L80, and new L60, etc., welcome the product explosion cycle, Onvo's market performance will directly affect NIO's final results for the year.
XPeng and Harmony Intelligent completion rates are also around 30%. XPeng will quickly increase volume in the second half relying on the global launch of new series like MONA L03, GX. Harmony Intelligent needs to rely on new products like STELATO G9, Qijing GT7, etc., to pull deliveries.
The direction of foreign joint venture brands lacks suspense. Under the pinch attack of continuously shrinking fuel base and new energy products far from forming scale, the main task for joint venture brands in the second half can only be to try to slow down the decline speed. Gasgoo Auto Research Institute forecasts that Volkswagen China is expected to reach around 2 million vehicles for the year, and Toyota in China around 1.3 million.
Of course, sales targets are only surface rulers. In January-May this year, China's automotive industry profit margin has dropped to 3.4%. In the second half, if continuing to rely solely on price cuts to boost volume, it will only further overdraft the blood-making ability of enterprises to survive in the deep water zone. At this stage, blindly stacking delivery numbers has lost practical significance.
The real deciding factor is to see whether each automaker can solidly convert the product cycles planned in hand into quality and cash flow-supported scale explosions.
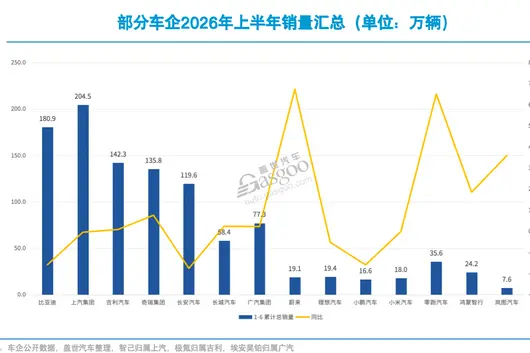
The first stock in Physical AI, Momenta officially rings the bell on the Hong Kong Stock Exchange, market cap close to 70 billion HKD. Public offering oversubscribed 414 times, international capital such as Singapore Government Investment Corporation, Fidelity International, Oaktree Capital followed the investment. This subscription heat is quite rare in the Hong Kong stock market in recent years.
Many people might not be very familiar with this company yet. Simply put: Momenta was founded in 2016, one of the earliest companies in China to do high-level intelligent assisted driving. You might not have heard its name, but the intelligent driving system in the car you drive is likely the solution provided by Momenta.
How strong is Momenta's industry status? Look at July 8th, nearly 20 automakers applauded its IPO together, you can feel the company's industry recognition is not to be underestimated.
Cumulative deployments exceeded 1 million units, 9 of the top 10 global automakers cooperate, third-party city NOA market share 65%, firmly ranking first in the industry, landed in over 10 countries including Asia, Europe, Oceania, etc.
In the global intelligent driving track, a competitive pattern of FSD, Momenta, and Huawei advancing together has formed. Relying on proprietary underlying technology + deep adaptation to Chinese road conditions, Momenta has become one of the only two Chinese intelligent driving forces with global competitiveness.
But the relationship between Momenta and these OEMs is far more than supplier and customer. SAIC, Mercedes-Benz, BYD have upgraded from customers to shareholders, SAIC, Mercedes-Benz, BYD all appear in the investor list. At the same time, Momenta deeply binds intelligent driving business with SAIC, GAC, the two parties form an industrial community of risk sharing and value sharing, at the technical level even deeper co-creation, cooperation almost covers the whole series of models. This forms a virtuous cycle — automakers use Momenta's solution, make money, and in turn continue to invest in Momenta.
The result is Momenta's revenue tripled in three years, reaching 2.413 billion in 2025, compound growth rate exceeding 80%, gross profit margin rose from 17.5% to 71.6%. CEO Cao Xudong said: The "GPT moment" of Physical AI has arrived. The next decade, what Momenta wants to do is General Physical AI — not just cars, but also Robovan, Robotaxi and robots.
A sample of Chinese AI going global, Momenta is already in the lead.


At the beginning of June, all car companies announced their May sales data. Since entering the second quarter of 2026, sales for each brand have generally been steadily increasing.
It is still the familiar two giants, BYD and Geely. May sales figures were respectively383,453 units and237,637 units.But in my personal opinion, their export data is even more worth our attention.

First, looking at BYD's part, in May their passenger cars and pickupsold 160,177 units overseas, an increase of 80.7% year-on-year; cumulative sales from January to May reached 614,470 units.
Geely similarly performed excellently,May overseas export sales volume was 85,144 units, a year-on-year growth of 184%.

Actually, many readers should know, BYD's 'ATTO 3' which is the overseas version of the Yuan PLUS, and their pickup model 'BYD SHARK' sold quite well overseas.
But in fact, BYD sells more than just these products overseas, and BYD's big weapon 'Flash Charging Technology' is also still in the initial layout stage overseas.
They plan to scale up about 6,000 megawatt flash charging stations overseas by the end of 2026, simultaneously exporting flash charging models equipped with second-generation Blade Batteries.

As for Geely, their premium brand Zeekr has recently been shining overseas, not only is Zeekr 9X very popular in the Middle East market, but the video of 'Zeekr 8X Beating Ferrari' is also widely circulated on the foreign internet.
Including in some lower-tier markets, models like Emgrand, Xing Yuan are also opening up recognition, Chinese car exports can be said to be welcoming a new stage.

According to data released by CPCA,in 2025 China's car exports reached 8.32 million units, a year-on-year growth of 30%; new energy vehicle exports in 2025 totaled 3.43 million units, a year-on-year growth of 70%.
Time has come to 2026, January to March China's car exports reached 2.34 million units, year-on-year growth of 53% compared to the same period in 2025. Combining this data and the current situation, see,I think China's car export volume in 2026 is expected to break through 10 million units.

Everyone says the economy is bad now and no money to buy cars, so why are car companies constantly launching new cars? Yes, one important reason is that Chinese car export business is growing rapidly.
Although the domestic car market has already tended towards saturation, the overseas market is still very vast, and Chinese cars are very competitive.
From CPCA's Cui Dongshu's article we can see, Chinese cars are exported in large quantities to countries such as Russia, Brazil and Mexico, and like the UK, Belgium and Italy in Europe, are also important export regions for Chinese cars.

Besides new cars, exporting used cars is also a big trend.
Domestically, the penetration rate of new energy vehicles long exceeded 50%, but it is not so overseas. In recent one or two years, while domestic consumers use replacement subsidies to buy new cars, a large number of fuel cars flowed into the used car market.
But the market cannot timely digest this part of inventory, therefore many used car merchants chose to export some 'Global Models' with relatively good condition to overseas, especially Asian, African, and Latin American countries, they have a huge demand for such products.

It is not hard to see, in the long term in the future, Chinese car exports will be a very big trend. If friends are interested, they might try to enter this industry, maybe there will be good development prospects.
So how are the major car companies laying out? If friends pay attention to this side should know, new force car companies actually attach great importance to export business.
Take the familiar 'NIO, XPeng, and Li Auto' as an example, NIO had already laid out the overseas market as early as 2021, and also built charging swap stations in parts of Europe and the Middle East.

But NIO's current main focus is still on consolidating the domestic market. Indeed NIO just recently 'got better', there is not enough financial strength and energy to cope with overseas challenges, so NIO's going global speed slowed down in 2026.
But with the help of ES8 and ES9, NIO basically passed the most difficult moment. I think it is time for them to work harder on new car going overseas.A car like Firefly is very suitable for the European market, at the same time, it is already being sold overseas, I think more can be done with it.

And XPeng Motor, for example, 2025 delivered over 45,000 new cars overseas, business covering 60 countries and regions globally.
At the same time, they have also set up 3 production bases overseas, to cope with challenges in tariffs and manufacturing costs. As early as July 2025, the Indonesia base was completed and started production; September Graz, Austria factory started European localization production; December Malaysia base was also completed.
Even they set such a grand goal as 'achieving half of sales from overseas by 2033', believe XPeng has the opportunity and ability to complete it.

But among new force brands, the one with the biggest potential I think is still Leapmotor.
Nowadays Leapmotor in the domestic market can be said to be on a strong trend, continuously gaining the title of sales champion among new force car companies,and in the overseas market it relies on Stellantis Group's sales network, at extremely cost-effective prices achieved good results in the European market.
2025 Leapmotor export volume reached 67,052 units, and in 2026 I think this data is expected to improve further, after all, if they want to achieve the goal of 'millions of annual sales', overseas market naturally cannot be ignored.

Of course, there are also some new force car companies whose export business started relatively slowly.
For example, Li Auto officially started export business only in 2025, but their products were sold overseas via 'parallel export' very early, and also received good reviews.
For example, Xiaomi Motor which sold very well domestically, plans to start export business only in 2027, but according to Xiaomi Tech's layout and influence overseas, I think Xiaomi Motor also has the opportunity to sell hotly.

However, the continuous increase of Chinese car export volume is not entirely the credit of 'Chinese brands', many joint venture brands' models produced in China exported overseas also counts as Chinese car export.
This includes products produced by Tesla China factory, and models from brands under SAIC like MG, Chevrolet, etc.Some joint venture brands' products may not be welcome domestically, but placed in the overseas market that is a 'blockbuster'.
This also explains why some brands' presence domestically is not quite high, but when statistics sales data is not considered bad.

Overall, the increase in Chinese car export volume is very beneficial for promoting economic circulation, can promote the inflow of foreign exchange, provide support for reviving the economy.
And independent brand car companies should also attach more importance to export business, only then can they open up a larger market.So which car company is the biggest winner now? I think some readers should be able to guess, it is Chery Motor.

May 2026, Chery Group sold 247,823 cars, year-on-year increase of 20.5%. Among them, group new car exports were 181,871 units, year-on-year growth of 80.5%, and broke Chinese car single-month export record for three consecutive months.
In the full year of 2025, Chery Motor exported new cars totaling 1,344,020 units, a year-on-year growth of 17.4%; cumulative car exports 5.85 million units, ranked first in Chinese brand passenger car exports for 23 consecutive years.
Although I often criticize Chery's product sequence is chaotic, it is precisely the sufficiently rich product sequence that allows Chery to do well in different countries, plus early layout, let Chery Group become the unquestionable 'Chinese Brand Car Company Export No. 1'.

Nowadays the iteration speed of new cars has become incredibly fast, many friends might think 'Why are there so many people wanting to buy cars'? But after understanding this car export matter, everyone should have a new understanding.
Car companies releasing new cars is not just for the domestic market, it is also a layout for overseas business.
The domestic new car market indeed has already tended towards saturation, but if we look further and wider, from a global perspective, isn't the market very vast?

Everyone can perceive that now is no longer the period of economic upward trend, in the situation where the real estate industry has cooled down, we need a new pillar industry.
For the domestic market, the automotive consumption industry is the choice made by the 'Invisible Hand'. So in your opinion, will car export business be a new trend?
((The above content represents only personal opinion))
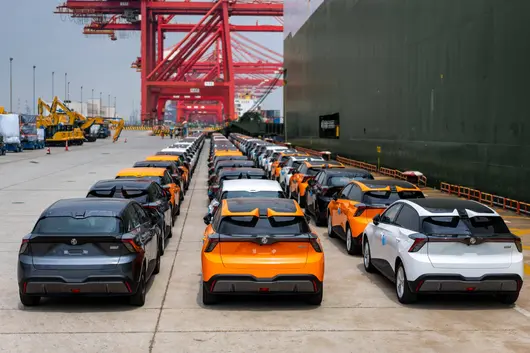
May 28, 2026, the World Living Room of the North Bund in Shanghai. In the live broadcast lens of Dragon TV, there were no lengthy speeches by leaders, but rather a "Global Relay Delivery" spanning across Asia and Europe, connecting multiple cities globally.
SAIC Group welcomed its first 100 millionth global user, officially becoming the first automotive group in the history of China's automotive industry to accumulate production and sales exceeding 100 million vehicles.

15 brands, counting down from the 99,999,996th vehicle to the 100,000,012th vehicle, 18 models were delivered synchronously in Shanghai, Liuzhou, Anting, London, Jakarta, and Singapore.
This is not only a milestone for an enterprise, but also a vivid footnote to China's automotive industry developing from scratch and from weak to strong.
In May 2014, SAIC actively implemented the instruction that "developing new energy vehicles is the only path for China to move from a large automotive country to a strong automotive country" and fully transitioned to new energy.
Twelve years later, SAIC completed the transition from "leading the way" with early transformation to "thousands of horses galloping" with brands, technology, ecosystem, and global reach blossoming, all through this 100 million delivery.
If you tear off all those hollow PR words and focus on the diverse owner profiles at the car delivery ceremony, some even spanning extreme geographical regions, you will find that the true smart-electric mass production capability and systemic power of a big factory lie precisely in these votes by different circles using their feet.
True International Natives
True internationalization has never been about holding a temporary press conference overseas or inviting a few Chinese media outlets, but about your product truly integrating into the lives of ordinary overseas people. Among the military merit medals of SAIC's 100 million deliveries, cumulative overseas deliveries have exceeded 7 million units.
At the delivery site in London, intern doctor Natalia picked up an MG4 EV. For her, this is not just an urban commuter pure electric small car. Her growth path has always had MG company, and her grandfather drove a classic British convertible MGB back then.

MG represents a new chapter in the global expansion of Chinese automakers. This brand, once born in the UK and possessing a century of history, after being wholly owned by SAIC Group, has multiple years consecutively topped European sales among Chinese brands.

At the same time, in Jakarta, the core winger of the Indonesian National Men's Football Team, the "genius boy" Eg who studied in Europe for five years, chose Wuling's 7-seater SUV Eksion produced locally in Indonesia, perfectly adapting to Indonesian local spatial and comfort needs, as the travel partner for himself and his family.

Behind this global multi-time-zone, multi-city relay delivery is SAIC's deployment of over 100 parts bases, 3 R&D centers, and 4 overseas manufacturing centers overseas. Even to avoid being strangled by international logistics capacity, SAIC also formed a self-operated RoRo fleet with a scale of 41 ships covering routes globally.
This "Age of Discovery" throughput of "Glocal" local globalization allows overseas car buyers, when purchasing, not to buy a distant imported symbol, but a reliable product supported by a local R&D layout and a local systemic ecosystem.
Efficiency Tool for Wealth Creators.
Those focusing on new forces of car making in middle-class private cars will find it hard to understand why SAIC's delivery list would simultaneously include a large number of commercial light trucks, logistics vehicles, and buses.
In Singapore, DHL (Dunhuang) Senior Vice President Herbert picked up a batch of MAXUS eDeliver 5 pure electric light trucks to cope with high-density, high-frequency urban last-mile delivery and cross-border parcel transfer;

In Taiyuan, Shanxi, Henglongsheng Industrial and Trade General Manager Zhang Yanbin purchased 56 Hongyan new energy heavy trucks again, working frequently in the most severe and labor-demanding mixing stations and urban infrastructure projects;

In Yangzhou, Jiangsu, Top Land Senior Vice President Yuan Guo batch-delivered nearly 10,000 Feifeng Dana T1 pure electric light trucks;

In Henan, Zhonglian Tourist Automobile General Manager Wang Xiaobing purchased Iveco Joy Star EV in one breath, used to run the high-density mountain road custom shuttle route from Luoyang to Laojun Mountain.

When the car circle is flocking to compete in TVs, refrigerators, and big sofas, these strivers walking on the front lines of infrastructure, culture, tourism, and logistics care most about availability rate, quality bottom line, and energy consumption cost. MAXUS light trucks can reduce cost per kilometer to as low as 5 cents under the city distribution model; Hongyan new energy can withstand extreme working conditions in mountainous slope operation environments.
This is the counter-cyclical structural advantage possessed only by big factories with "Full Scenario, Full Category Coverage". The essence of systemic power is that it can not only build the IM LS9 Hyper to fly close to the ground for the elite class at the 300,000 yuan level luxury electric car, but also build the smart electric tool car running in the urban logistics backbone network to help ordinary people efficiently create wealth.
Without a doubt, such a three-dimensional product matrix cannot be bought for even a lot of money by single-track lane players.
Reject High-Price Monopoly
Frontier smart-electric technology should not just be exclusive high-price toys for the rich.
In this delivery, the most touching story comes from Pang Fuqiang, a post-80s village party secretary in Lantian, Shaanxi. He personally pays every day to provide door-to-door meal delivery service costing 2 yuan per meal for 74 left-behind elderly people in the mountains. Because the delivery routes are scattered and road conditions are dispersed, the tricycle he drove before had small loading capacity and no safety guarantee.
In this activity, he was gifted a Wuling Rongguang Pure Electric Version. The 4.3 cubic meter large space, Shenyan Battery Commercial Version, and collision zero spontaneous combustion safety record became his helper to protect mountain elderly more quickly and safely.

And in Dahua Yao Autonomous County, Hechi, Guangxi, charity blogger Liu Jia drove back and forth through towering mountains for five consecutive years rain or shine to give haircuts and companionship to left-behind children. The Buick ZhiJing E7 he picked up, equipped with eye-protection ceiling lights and zero formaldehyde cabins, became the "full score cabin" for the children in the mountains.
Why can ordinary people and grassroots strivers enjoy the most cutting-edge and reliable technology?
The answer is still the scale effect and technology mass production brought by the system.
Because SAIC owns a full technology route, full price range product layout, it can use the integration capability of the supply chain to smash the Qualcomm 8155 chip and Doubao Deep Thinking Large Model into the 60,000 yuan national family sedan Roewe i6;

Turn Huawei Qiankun Intelligent Driving Pro and HarmonyOS Cockpit into standard configuration across the line for the 150,000 yuan Wuling Huajing S, directly breaking the strong binding between high-level intelligence and high price.
Quickly realize mass production of top technology in the laboratory, downgrade, turn into a delivery car in the mountains, turn into a smart vehicle not lagging in a tens-of-thousands yuan fuel car, let technology empowerment, this is the unique, cutting-edge underlying hard power of car company big factories.
99,999,999th Car Owner
The 99,999,999th vehicle delivered by SAIC Group globally is the SAIC Volkswagen ID. ERA 9X.
This delivery also welcomed the 6,999th car owner of ID. ERA 9X. As the World Cup is about to start, the first Chinese player to fight in the Bundesliga, Yang Chen, became the 6,999th owner of ID. ERA 9X, jointly witnessing SAIC Group's cumulative production and sales entering the "100 Million Level Era".
Deeply integrating "German heritage + Chinese wisdom", ID. ERA 9X broke 10,000 locked orders within 1 hour of launch, and retail delivery reached 2,326 units just 5 days after launch, and in April it forcefully ranked in the top 3 of extended-range large high-end SUVs.

Now, just one month after launch, cumulative delivery exceeded 7,000 vehicles, further confirming its user recognition and product competitiveness in the high-end extended-range market. This achievement stems from SAIC Volkswagen's 42 years of deep cultivation in the Chinese market, and is more the fusion empowerment of the "In China, For China" strategy and "Global Wisdom + Chinese Speed".
This milestone delivery is both an important node for SAIC Group to move towards 100 million global cumulative production and sales, and a solid mark of SAIC Volkswagen's deep cultivation in the new energy track.
"100 Million Units" Is Not a Solo Act
"100 Million Units" has never been a solo act for SAIC alone, but the result of these 100 million car owners with vastly different identities, located in different time zones, voting with their feet on their respective life tracks.
Cao Xudong, CEO of a top intelligent driving enterprise, picking up the IM LS9 Hyper in Shanghai, stepping on the gas pedal in London streets by British intern doctor Natalia, the passenger car driver picking up waves of tourists at Luoyang scenic spots, and village party secretary Pang Fuqiang driving an electric car in the mountains of Lantian, Shaanxi to deliver meals for left-behind elderly...

They have different professions, skin colors, and budgets, but what they experience in intelligence, quality, and peace of mind at the moment they buy the car keys, shares at the bottom level, is the same huge, cutting-edge, and omnipresent smart electric big factory mass production system.
100 million vehicles is not the end point, but the starting line for this big factory smart electric mass production beast to accelerate transformation into a user-centric high-tech company. The system story of Chinese intelligence, in this global relay delivery season, has just turned a new chapter.
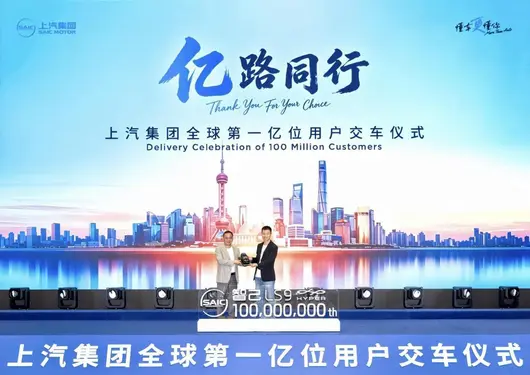

The international energy situation continues to fluctuate, oil prices continue to rise, prompting Europeans to accept electric vehicles, and giving Chinese new energy vehicle brands new hope in Europe. According to foreign media reports, in April 2026, overall sales of Chinese automakers in the European market increased by 114% year-on-year, with SAIC Motor, BYD, and Chery emerging as the big winners.
While products are selling well, facing EU trade barriers and the global reality of excess capacity, Chinese top new and old automakers are also accelerating the layout of overseas production bases, landing localized production by acquiring and renovating idle capacity of traditional automakers in the US and Europe.
From export to sales to production, Chinese new energy vehicle brands going global are accelerating their advancement, expected to enter a new stage of reshaping the European automotive industry landscape.
SAIC Steady, Chery Aggressive, Chinese Cars Selling Big in Europe
On May 22, 2026, European automotive media cited the latest data from local market research firm Dataforce, stating April overall new car sales in Europe continued to recover, up 6.4% year-on-year, with the regional car market maintaining a steady recovery trend overall.
Due to the ongoing conflict in the Middle East, European oil prices have risen by about 20% since 2026, therefore, new energy models became the core driver pulling April growth in the European car market. Among them, pure electric vehicles performed the most prominently, with April sales increasing by 38% year-on-year, setting the highest single-month growth rate since 2026; Plug-in hybrid vehicle sales growth was 21%, and Hybrid vehicle sales growth also reached 15%.
European car users are accelerating their shift to new energy vehicles, which also created a perfect growth opportunity for Chinese car brands to accelerate expanding sales in the European market.

Data shows, in April 2026, overall sales of Chinese automakers in the European market doubled, surging 114% year-on-year. Among them, SAIC Motor sales in April were 30,074 vehicles, stably at the top of the Chinese automaker sales list, BYD single month sales were 28,186 vehicles ranking second, Chery April sales were 25,656 vehicles, ranking third. From a single-month performance perspective, the sales gap between the three Chinese automakers in the European market is also continuously narrowing.
In terms of sales growth rate, April European car market growth rate list was almost dominated by Chinese brands, Leapmotor growth rate was as high as 423%, Chery and BYD followed with year-on-year growth rates of 344% and 125% respectively, overall growth momentum was strong.
Among them, Chery became the Chinese automaker with the strongest growth explosiveness in the European market in April. Compared to April 2025, Chery sales increased by nearly 20,000 vehicles. Dataforce data shows, Chery brand April 2025 sales in Europe were only 4 vehicles, this April reached 5,446 vehicles; In addition, two sub-brands under Chery, Omoda and Jaecoo, both exerted force synchronously, all ranked in the forefront of European market sales growth, among them, Omoda growth ranked third in Europe, Jaecoo ranked sixth. Terminal market performance indicates Chery's layout in Europe has entered a stage of full-force exertion.
Because contrasting sharply with the high growth of Chinese brands is that some European local automakers and traditional car giants encountered sales decline in April. For example, Toyota dipped slightly 1% year-on-year, Renault declined 3%, Ford fell 11%, Hyundai decline reached 12%, Premium brand Porsche also surprisingly declined year-on-year to 17%, Mitsubishi decline was most prominent, reaching 51%.
European local giant Stellantis, which maintains close relations with Chinese automakers Leapmotor and Dongfeng, April sales achieved 4.3% year-on-year growth, but growth rate was lower than the overall European car market performance. Brand performance division within the group was significant, Leapmotor, Fiat, Opel/Vauxhall, Citroen maintained positive sales growth, while Peugeot and Alfa Romeo showed obvious sales decline.
If Chinese new energy vehicle new and old brands can continue this upward momentum, they will be expected to reshape the European market competition landscape.
Chinese Automakers on a Crazy Buying Spree, But Still Must Clear Union Hurdles
On one hand, multiple factors such as oil price hikes and new energy vehicle market transition overlap, leading to weak sales of traditional car giants in the European market. On the other hand, the manufacturing system left over from the fuel vehicle era is also gradually falling into the dilemma of idleness or excess capacity.
Consulting agencies predict, large numbers of low-utilization car factories in the US and Europe will face shutdown or transfer in the future, and the EU's measure of imposing additional import tariffs on Chinese electric vehicles, will further promote Chinese automakers to accelerate the layout of European localized production.
In this context, taking over and renovating traditional automaker factories has become a core method for many Chinese automakers laying out overseas localized production. This phenomenon has also attracted foreign media attention, recently a European automotive media reported that BYD is currently negotiating with Stellantis and other European automakers to take over idle factories in the region. In fact, BYD announced building a factory in Hungary as early as the end of 2023, becoming the first Chinese automaker to build a passenger car factory in the EU.
BYD Hungary factory planned annual capacity is 300,000 vehicles, in 2025 BYD sales in the European market exceeded 187,000 vehicles, year-on-year increase of over 260% compared to 2024. Predicting according to the growth rate, BYD relying solely on one Hungary factory will be difficult to satisfy car sales needs in Europe, therefore rumors about negotiating factory purchase with local car makers are reasonable.
Chinese automakers full of ambition for the European market are not just BYD. Just in one month of May 2026, news has spread about multiple Chinese automakers negotiating European capacity cooperation projects. For example, on May 20, Stellantis Group announced cooperation negotiation with Dongfeng Group, planning to rely on France Rennes factory to achieve local production of Dongfeng new energy models. In addition, Leapmotor also revealed that Leapmotor International established as a joint venture with Stellantis, is expected to acquire Stellantis factory located in Madrid, Spain, quickly build a European local production base.
There is also news that Geely is also actively accelerating the acquisition of Ford Spain Valencia factory partial assembly production line; Xpeng was also exposed to be negotiating with Volkswagen Group, seeking to acquire its European idle capacity. There is also Chery cooperating with Spain Ebro Group to activate former Nissan old factory, currently production has been resumed, Chery models are about to be imported and landed.
Taking over and renovating European automakers' idle capacity, the benefit is avoiding industry duplicate construction, increase local European employment opportunities, conforming to industrial policy orientation, also can save more time and improve efficiency compared to completely self-building factories.
However, what needs to be reminded to Chinese automakers is, buying spree does not mean permanent security, behind it also hides great risks.

Also recently, after news spread about Volkswagen Group and Xpeng negotiating idle capacity sales, Volkswagen Group union head (Daniela Cavallo) stood before tens of thousands of workers, heatedly criticized group management, and strongly opposed management negotiating with Chinese automakers etc. third parties to yield idle capacity.
Under this pressure, Volkswagen Group CEO (Oliver Blume) publicly stated, currently, Volkswagen has not had any negotiations with Chinese manufacturers regarding using European factory capacity, in the future there are absolutely no related cooperation plans.
Compared to emerging markets such as Southeast Asia, Middle East, Africa with high inclusivity to Chinese automakers, mature European car market regulations, unions, environmental protection, employment commitments etc. constraints conditions are more severe, Chinese automakers landing localization through the method of acquiring factories, besides renovating production lines, adapting supply chains, more need to adapt to local rules, adapt to local culture to survive better.
Of course, self-built factories can fully fit the automaker's own manufacturing standards, supply chain systems, and production concepts, autonomy control is stronger, but this also suits fund-adequate, layout pace controllable automakers to go for long-term layout. From this level, currently BYD's capacity layout in Europe fits long-term + short-term coordination better, globally, besides negotiating qualified old factories in major markets for renovation, BYD has landed at least 4 self-built complete vehicle factories in places like Thailand, Hungary, Turkey.
European new energy vehicle sales significantly increased, brought development opportunities to Chinese automakers eager to go global, however European complex emotions on Chinese automaker acquiring factories, again makes Chinese automakers' Europe road full of difficulties. Actually, this round of global automotive capacity restructuring led by Chinese automakers, reflects structural transfer of industry discourse power in the new energy vehicle era.
Fuel vehicle era, US/EU/Japan/Korea automakers dominated global car technical routes, capacity configuration and industry rules, under the wave of smart electrification, relying on complete new energy supply chain, mature three-electric and intelligent technology, efficient capacity system, Chinese automakers are upgrading from product export to full-scale overseas presence of capacity, technology, standards, expected to reshape the European and even global automotive industry landscape.
(Source: autonews.com, reuters.com, bloomberg.com)
May 20, Stellantis and Dongfeng signed a non-binding memorandum of understanding, planning to establish a joint venture in Europe. Among them, Stellantis holds 51% equity, while Dongfeng holds 49%.
This joint venture will do four things: sell VOYAH brand new energy vehicles, localize production at Stellantis' Rennes factory in France, joint procurement, joint R&D.

After establishing the "Leapmotor International" joint venture with Leapmotor in Europe, Stellantis extended an olive branch to its old partner Dongfeng again this time, adding a layer of consideration for "localization production".
Does this mean Chinese automakers have completely changed their strategy for going global?
First, Clarify the Global Expansion Models
Before analyzing this, let's first clarify the several strategies Chinese automakers use for going global.
The first is whole vehicle export. Cars are built domestically, shipped on boats, and sold by dealers locally. This model is the simplest with the lowest investment, but it lacks market control; once tariffs rise, the price advantage disappears. Chery's early export to Russia followed this path; once tariffs were added, the rhythm was completely disrupted.
The second is KD assembly. Parts are shipped locally and assembled in local factories. This model is a step up from whole vehicle export, able to evade some tariffs and carry a "Locally Made" label. But honestly, many KD factories are just large screw-nailing plants; core parts are still shipped from China, with limited localization. Many Geely and Chery factories in Southeast Asia and the Middle East use this model. It solves some problems but not the root ones.
The third is building factories alone. Bringing money overseas to buy land, build factories, hire people, and build channels. This is the most "hardcore" way and the path taken by top independent automakers. Great Wall Motors and BYD have adopted this model. BYD's Thailand factory is already in production, the Brazil factory is under construction, and the Hungary factory is in planning. The benefit is becoming a true "local brand", evading import tariffs, and securing local government industrial subsidies. But the investment is high, the cycle is long, and management complexity increases by an order of magnitude.
The fourth is acquiring local brands. Geely acquired Volvo, later invested in Daimler, and acquired Lotus. This is the path Geely walked earliest and most systematically. Partial equity or binding with a local giant equals directly inheriting the other party's brand assets, channel networks, and local compliance capabilities. But integration difficulty is huge, with high risks of cultural conflict and management chaos.
And this cooperation between Stellantis and Dongfeng does not fit well into any of the above.
Strictly speaking, it is a combination of the third and fourth types.
Using Stellantis' existing French factories for production is borrowing the other party's manufacturing assets, not building independently; selling VOYAH using Stellantis' existing European sales channels is borrowing the other party's commercial assets. Moreover, the capital structure is shared equity, not Party A hiring Party B to help, but a true interest binding.
This model, I will temporarily call it "Grafting Global Expansion" — not planting a tree yourself, but grafting branches onto an existing big tree.

Why is this path worth attention? Because it solves several core pain points of going global.
Where Does Localized Production Really Matter?
Many people talking about localized production first think "evading tariffs". That's right, EU anti-subsidy taxes plus tariffs mean a Chinese EV pays dozens of percentage points more tax entering Europe, basically wiping out the price advantage. But tariffs are just one dimension.
More critical is the carbon footprint. The EU Carbon Border Adjustment Mechanism (CBAM) has started trial operation, and future import vehicle carbon emissions will also need to be considered. If cars are produced in Europe using European green electricity, the carbon footprint will be much better. In the next 5 years, the cost pressure in this area will increase.
Another point to consider is the supply chain.
Dongfeng is producing in European factories, but what about the supply chain? The memorandum wrote "joint procurement", which means some parts are still sourced from China, leveraging Dongfeng's procurement capabilities in China's new energy ecosystem to reduce costs. But the local supply chain must keep up gradually, otherwise, if geopolitical risks arise, production lines will stop.
Next, the brand. European consumers have high loyalty to car brands; Germans buy Volkswagen, French buy Peugeot. This is a habit of decades. Chinese new brands want to break this habit; product strength alone is not enough, there must be "trust endorsement". Stellantis' participation is this endorsement.
Of course, the cost is that the joint venture is led by Stellantis, and the voice in the European market is mainly in Stellantis' hands. This is a price that has to be paid.
Who Will Be Mainstream in the Next Three to Five Years?
My judgment is that in Europe, "binding with local giants" will become the mainstream.
The reason is simple, the European market is too hard to fight. Tariff barriers are highest, regulations most complex, consumers most picky, competition most intense. The whole vehicle export model will become increasingly difficult in the European market, forcing Chinese automakers to find a way out of localized production.
On the other hand, Stellantis needs to make up for the electrification shortcoming. Other Western automakers, such as Ford, General Motors, Renault and other traditional automakers, are struggling in transformation dilemmas. They have channels, factories, and brands, but lack new energy capabilities. This is exactly what Chinese automakers can provide.
Both sides have needs, so cooperation will increase.
The method may not necessarily be a joint venture form like Stellantis and Dongfeng, it could also be more flexible forms such as technology licensing, channel sharing, joint development, but the core logic is the same: not fighting alone, leveraging momentum to land. While in markets like Southeast Asia, Middle East, South America, building factories alone and KD assembly remain mainstream because barriers are relatively low and price advantages still work.
However, "binding with giants" is not without risk. Being tied up with a giant means destiny is partly in others' hands. What if Stellantis cooperates with Dongfeng today but finds a better partner tomorrow? What if joint venture performance fails to meet expectations? What if there are disagreements on product positioning and pricing strategies? Dongfeng Peugeot Citroën's history has already proved that the relationship between joint venture partners is not always smooth.
From Dongfeng Peugeot Citroën to European joint venture, over thirty years, the relationship between Dongfeng and Stellantis has completed a "two-way rush". Behind the role reversal is the accumulation and transformation of the Chinese automotive industry over decades. Chinese automakers are no longer satisfied with "selling cars"; they want "rooting". The prerequisite for rooting is learning to cooperate with locals.
Whether this time can succeed, we will wait and see.