首頁WRX STI

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
广州2026年7月12日 /美通社/ -- 从第一辆车驶下生产线,到即将迎来第3000万辆整车下线,广汽的每一步向前,都源于全球用户的选择与陪伴。7月16日,广汽集团将举行3000万用户感恩活动,与全球用户共庆第3000万辆整车下线的历史性时刻。
自第一辆整车交付用户以来,广汽的发展始终与全球用户的出行生活同频向前。今年以来,源源不断的新用户加入广汽大家庭,共同汇聚成3000万份沉甸甸的信赖。
2026年上半年,广汽自主品牌出口量达12.15万辆,同比大增132%。美洲、亚太、中东、非洲、欧洲五大区域同步实现高增,充分印证全球市场对广汽产品品质的认可与青睐。
目前,广汽国际化业务已覆盖亚太、中东、美洲、欧洲等五大板块110个国家和地区,建成746家销售服务网点、6座海外生产工厂与9个海外零部件仓库,形成覆盖研发、生产、供应、销售的全价值链本地化运营能力。在美洲,多款主力车型跻身当地细分市场前列,巴西、哥伦比亚等国单月销量实现数倍增长;在亚太,中国香港1-5月电动市占率突破11%,泰国市场6月销量环比劲增207%;在欧洲,搭建起从本地化生产到市场终端销售的全链路运营体系,新能源产品稳步进入核心国家市场。每一份市场增长的背后,都是当地用户的认可与选择,共同汇聚成全球3000万用户的信赖版图。
广汽集团3000万辆的里程碑,凝聚着全球用户的信赖与托付。站在新起点,广汽集团将纵深推进"番禺行动"改革,始终坚持"以用户为中心"发展理念,把全球用户的信赖转化为前行动力,以更优质的产品、更先进的技术、更完善的服务回馈每一份支持,与全球3000万用户携手,共启全新发展征程。
欲了解更多关于广汽的信息,请访问:https://www.gacgroup.com/en 或在社交媒体上关注我们。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿 Perodua Aruz 同 Toyota Yaris Cross 嚟做比較。呢兩款車喺價位同定位上都幾接近,而家我哋就從多個方面做一個詳細嘅比較,幫唔使你浪費做功課嘅時間。
Perodua Aruz 喺馬來西亞嘅 OTR 售價係 RM 72,900 - 77,900,總共 2 個版本,包括 1.5L X(RM 72,900)、1.5L AV(RM 77,900) 等。
Toyota Yaris Cross 喺馬來西亞嘅 OTR 售價係 RM 99,900 - 109,900,總共 2 個版本,包括 2026 1.5L Standard(RM 99,900)、2026 HEV 1.5L Standard(RM 109,900) 等。
睇返價錢,Perodua Aruz 嘅起步價確實比 Toyota Yaris Cross 平咗 RM 27,000。如果你預算有限,Perodua 嘅入門版已經可以滿足日常需要。不過要留意,平嗰幾千蚊,可能喺配備方面有取舍,具體就要睇你嘅需要。

Perodua Aruz 搭載 1.5L 4-cyl,馬力 105 hp。官方油耗 6.0 L/100km。
Toyota Yaris Cross 搭載 1.5L 4-cyl,馬力 105 hp。官方油耗 6.0 L/100km。
兩款車用緊同一套動力系統,日常開落去嘅感覺基本冇咩分別。油耗方面都差不多,唔使太糾結這一點。

Perodua Aruz 採用 FWD 驅動方式。
Toyota Yaris Cross 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大區別。

Perodua Aruz 保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
Toyota Yaris Cross 保修 5 年/無限制里程,保養間隔 每 10,000km 或 6 個月。

Perodua Aruz 同 Toyota Yaris Cross 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就揀配備更豐富嗰款。始終都係建議兩款都去試駕,親身體驗先係最重要嘅。

總嘅嚟講,Perodua Aruz 同 Toyota Yaris Cross 都係馬來西亞市場幾唔錯嘅車型。揀邊一部,關鍵都要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係一件大事,花啲時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿 Perodua Aruz 同 Proton X70 嚟做比較。
Perodua Aruz 喺馬來西亞嘅 OTR 售價係 RM 72,900 - 77,900,一共有 2 個版本,包括 1.5L X(RM 72,900)、1.5L AV(RM 77,900) 等。
Proton X70 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,300,一共有 3 個版本,包括 1.5L Standard 2WD(RM 106,800)、1.5L Executive 2WD(RM 115,800)、1.5L Premium 2WD(RM 122,300) 等。
從價錢嚟睇,Perodua Aruz 嘅入門價確係比 Proton X70 平咗 RM 33,900。如果你預算有限,Perodua 嘅入門版已經可以滿足日常需求。不過都要注意,平嗰幾千蚊,可能喺配備上會有取捨,具體要睇返你嘅需求。
Perodua Aruz 配備 1.5L 4-cyl,馬力 105 hp。官方油耗 6.0 L/100km。
Proton X70 配備 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
動力方面,Proton X70 嘅 1.5L Turbo 比 Perodua Aruz 嘅 1.5L 4-cyl 多咗 35 匹馬力。不過日常喺市區開,兩部車嘅動力都夠用,唔會覺得唔夠力。
Perodua Aruz 車身長 4400 mm,尾箱 400 L。
Proton X70 車身長 4400 mm,尾箱 400 L。
兩部車嘅尺寸幾乎一模一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全夠用。
Perodua Aruz 採用 FWD 驅動方式。
Proton X70 採用 FWD 驅動方式。
兩部車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。
總括嚟講,Perodua Aruz 同 Proton X70 都係馬來西亞市場幾唔錯嘅車型。揀邊一部車,關鍵始終要睇返你嘅個人需求同預算。建議大家做足功課,多比較幾間車行嘅報價,再去試駕先做最終決定。買車係件大事,花少少時間做足功課絕對無錯。
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會用 寶騰 X50 同 奇瑞 Tiggo 8 PHEV 來做比較。這兩部車喺價位同定位上都幾接近,今日我哋就由多個方面做一個詳細嘅比較,幫你節省咗做功課嘅時間。
寶騰 X50 喺馬來西亞嘅 OTR 售價係 RM 89,800 - 113,300,總共有 4 個版本,包括 1.5T Executive(RM 89,800)、1.5T Premium(RM 101,800)、1.5T Flagship(RM 113,300) 等。
奇瑞 Tiggo 8 PHEV 喺馬來西亞嘅 OTR 售價係 RM 159,750 - 159,750,總共有 2 個版本,包括 1.6L Turbo Standard(RM 130,000)、1.6L Turbo Premium(RM 145,000) 等。
由價錢嚟睇,寶騰 X50 嘅起步價確實比 奇瑞 Tiggo 8 PHEV 平咗 RM 69,950。如果你預算有限,寶騰嘅入門版已經可以滿足日常需求。但亦要留意,平嘅嗰幾千蚊,可能喺配備上有取舍,具體睇你嘅需求。

寶騰 X50 配備 1.5L 4-cyl,馬力 105 hp。官方油耗 6.0 L/100km。
奇瑞 Tiggo 8 PHEV 配備 Hybrid,馬力 170 hp。官方油耗 4.5 L/100km。
動力方面,奇瑞 Tiggo 8 PHEV 嘅 Hybrid 比 寶騰 X50 嘅 1.5L 4-cyl 多咗 65 匹馬力。不過日常喺市區開,兩部車嘅動力都夠用,唔會覺得唔夠力。
寶騰 X50 車身長 4400 mm,行李箱 400 L。
奇瑞 Tiggo 8 PHEV 車身長 4400 mm,行李箱 400 L。
兩部車嘅尺寸幾近一樣,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。

寶騰 X50 保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
奇瑞 Tiggo 8 PHEV 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
總括嚟講,寶騰 X50 同 奇瑞 Tiggo 8 PHEV 都係馬來西亞市場幾不錯嘅車型。揀邊一部,關鍵仲係要睇你嘅個人需求同預算。建議大家做足功課,多比較幾間車行嘅報價,先至去試駕做最後決定。買車係件大事,花少少時間做功課絕對無錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿 寶騰 X90 同 奇瑞 瑞虎 Cross 黎比較。這兩款車喺價位同定位上都好接近,今日我就由多個方面做一個詳細嘅比較,幫你省卻做功課嘅時間。
寶騰 X90 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,800,一共有 4 個版本,包括 2026 1.5T Prime X(RM 122,800)、2026 1.5T Prime(RM 116,800)、2026 1.5T Lite(RM 106,800) 等。
奇瑞 瑞虎 Cross 喺馬來西亞嘅 OTR 售價係 RM 88,750 - 99,750,一共有 2 個版本,包括 2025 HEV 1.5L CSH(RM 99,750)、2025 1.5T Standard(RM 88,750) 等。
從價錢來看,奇瑞 瑞虎 Cross 嘅起步價比 寶騰 X90 平咗 RM 18,050。坦白講,喺呢個價位段,幾千蚊嘅差距其實唔算大,關鍵仲係睇整體嘅性價比同長期使用成本。

寶騰 X90 配備 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
奇瑞 瑞虎 Cross 配備 1.5L 4-cyl,馬力 105 hp。官方油耗 6.0 L/100km。
動力方面,寶騰 X90 嘅 1.5L Turbo 比 奇瑞 瑞虎 Cross 嘅 1.5L 4-cyl 多咗 35 匹馬力,中段加速更有把握,尤其係跑高速超車嗰陣。不過 奇瑞 瑞虎 Cross 嘅油耗可能更抵,日常市區通勤差別唔會太大。
寶騰 X90 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA)。
奇瑞 瑞虎 Cross 嘅安全評級係 TBD,主動安全系統包括 Basic。
安全配備方面,兩款車都拿到唔錯嘅評級。不過 寶騰 X90 嘅 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA) 同 奇瑞 瑞虎 Cross 嘅 Basic 喺功能上有些差異,如果你比較睇重主動安全嘅話,可以仔細對比吓兩者嘅功能列表。

寶騰 X90 車身長 4400 mm,尾箱 400 L。
奇瑞 瑞虎 Cross 車身長 4400 mm,尾箱 400 L。
兩款車嘅尺寸幾乎一樣,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。

寶騰 X90 保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
奇瑞 瑞虎 Cross 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
總體嚟講,寶騰 X90 同 奇瑞 瑞虎 Cross 都係馬來西亞市場好唔錯嘅車型。揀邊一部,關鍵仲係睇你嘅個人需求同預算。建議大家做足功課,多比較幾間車行嘅報價,先去試駕先做最後決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多個買家喺揀車嘅時候都會拿 Chery Tiggo 8 同 Volkswagen Tiguan 做比較。呢兩款車喺價位同定位上都幾接近,今日我哋就從多個方面做一個詳細嘅比較,幫你節省做功課嘅時間。
Chery Tiggo 8 喺馬來西亞嘅 OTR 售價係 RM 129,750 - 129,750,一共有 1 個版本,包括 2026 1.6T Standard(RM 129,750) 等。
Volkswagen Tiguan 喺馬來西亞嘅 OTR 售價係 RM 206,540 - 260,024,一共有 2 個版本,包括 2025 Allspace 2.0T R-Line(RM 260,024)、2025 Allspace 1.4T Elegance(RM 206,540) 等。
從價錢嚟睇,Chery Tiggo 8 嘅起步價確實比 Volkswagen Tiguan 平咗 RM 76,790。如果你預算有限,Chery 嘅入門版已經滿足日常需要。但都要注意,平嗰幾千蚊,可能喺配備上會有取捨,具體就要睇你嘅需要。

Chery Tiggo 8 採用 FWD 驅動方式。
Volkswagen Tiguan 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。
Chery Tiggo 8 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
Volkswagen Tiguan 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
兩款車嘅保修條件一樣,呢方面唔使糾結。實際保養成本仲要睇品牌嘅服務網絡同零件價格,建議去車友群問吓真實車主嘅經驗。

Chery Tiggo 8 同 Volkswagen Tiguan 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更看重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,嗰就揀配置更豐富嗰款。最後始終建議兩款都去試駕,親身體驗先係最重要嘅。

總嚟講,Chery Tiggo 8 同 Volkswagen Tiguan 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵始終都要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕先做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

最近一段时间,几乎是个公司都要大规模发力AI,这已经不新鲜了,但是就在最近知名网约车企业曹操出行全面转型AI原生公司的消息传来,网约车的生意不好了吗?这是要干什么?

一、曹操出行全面转型AI原生公司
据央广网的报道,据悉,曹操出行计划组建独立AI事业部,全面推进公司AI战略落地,完成从移动互联网公司到AI原生公司的关键转型。公司于近期在招聘平台上线“首席AI官”岗位, 综合薪酬总包超千万元。
根据岗位描述,首席AI官并非传统科技公司常见的常规技术负责人岗位。该岗位不仅负责AI技术应用的落地,也将参与公司AI转型方向的制定、生态合作推进与行业影响力建设,推动公司从传统出行平台升级为AI时代的智能出行服务基础设施。
此外,首席AI官还将负责建设AI组织与人才梯队:组建并管理AI算法与工程团队,搭建高水平、能打硬仗的技术队伍;推动全员AI素养提升,培养核心技术骨干与未来管理者,为公司的持续AI能力建设提供组织保障。
今年以来,曹操出行Robotaxi业务进展不断。今年4月,公司获批成为杭州市首家可开展Robotaxi无人化道路测试的企业,业务正式进入无人化测试阶段。近期,曹操出行又宣布与上海国际汽车城达成战略合作,计划年内于上海投放100辆Robotaxi,加速推动Robotaxi业务在一线核心城市的规模化落地。
值得一提的是,曹操出行深度参与了中国首款原生开发Robotaxi原型车“Eva Cab”的产品定义与研发,该车辆将亮相2026香港车博会。

二、网约车的生意真的不好了吗?
最近,曹操出行高调宣布全面转型AI原生公司,这事儿在出行圈里激起了不小的水花。很多人第一反应可能就是,网约车生意是不是真的做不下去了?才会搞出这么大的动作来转移视线?
首先,传统网约车就是一门薄利生意。在经历了早期的野蛮生长和补贴大战后,整个行业的格局已经基本固化,形成了寡头垄断的局面。在这种格局下,像曹操出行这样的第二梯队平台,其实面临着非常尴尬的生存处境。它们难以摆脱对聚合平台的流量依赖,这就导致了一个极其畸形的商业闭环,陷入了业绩越好却越不赚钱的困境。
表面上看,订单量在涨,流水在增加,但实际上,大部分利润都被上游的流量入口抽走了,留给自身运营的成本空间极其微薄。这种模式本质上还是传统的互联网流量分发逻辑,缺乏核心壁垒。如果继续在这个泥潭里打转,企业不仅无法实现真正的盈利,反而会被高昂的获客成本和合规成本拖垮。因此,曹操出行选择在这个时候宣布全面转型AI原生公司,与其说是主动出击,不如说是被逼到墙角后的一种必然求生策略。它必须跳出单纯拼运力、拼补贴的低维竞争,去寻找新的价值锚点。

其次,网约车这个赛道在资本眼里已经不够性感。我们把目光从行业本身挪开,看看资本市场脸色。对于当前的资本市场来说,网约车是一个极其缺乏想象力的赛道。现在的投资人,你跟他讲日单量、讲GMV,他根本不买账。为什么?因为在他们眼里,网约车就是最传统的互联网服务的一种,重资产、重运营、天花板肉眼可见,故事早就讲完了。一个没有新故事的公司,在二级市场是得不到任何溢价估值的。
这时候,AI技术的引入,意义就完全不同了。曹操出行转型AI原生公司,本质上是在给自己换一套资本市场的叙事逻辑。以前你是一家网约车公司,你的估值模型是按单量算的;现在你是一家AI公司,你的估值逻辑就变成了技术赋能、算法驱动。更重要的是,在传统网约车模式里,AI顶多是个辅助工具,帮你派派单、规划一下路线;但转型之后,AI就升级成了决策中枢。
从车辆调度、动态定价,到安全监控、服务品控,全部由AI来主导。这种从“人力密集型”向“算法密集型”的转变,无疑会给曹操出行带来极大的资本市场想象空间。这就叫作“旧瓶装新酒”,酒香不香先不说,至少这个新概念能重新把投资人的目光拉回来。
第三,曹操更是为了在Robotaxi的新战场中抢占先机。曹操出行的做法其实不仅是为了炒概念,更是为了在Robotaxi的新战场中抢占先机。现在的出行市场,暗流涌动,最大的变数是什么?是L4级自动驾驶技术。随着这项技术的逐渐成熟,Robotaxi已经不是科幻小说里的东西了,它正在一步步落地。未来出行的终局,大概率是没有人类司机的。一旦跨过那个成本临界点,Robotaxi将被视为决定未来出行格局的关键变量。
在这个新战场里,传统的运力规模优势将荡然无存,你有多少辆车、签了多少司机都不重要了,重要的是你的算法够不够硬,你的车队管理够不够智能。曹操出行现在全面AI化,其实就是在为无司机时代做技术储备和组织架构的预演。如果不提前在这个领域卡位,等到Robotaxi真正爆发的那一天,连上牌桌的机会都没有。所以,曹操出行现在的转型,是用短期的阵痛去换取长期上牌桌的资格,这无疑也会给曹操出行带来更多翻盘的机会。

第四,AI化转型已经成为传统互联网发展的大势所趋。从长期来看,AI化转型已经成为传统互联网企业发展的大势所趋。这已经不是做不做的问题,而是怎么做、做得多深的问题。现在甚至有不少互联网公司直接要求全员AI,从产品经理到运营,必须用AI思维重构业务流程。曹操出行不过是这股汹涌浪潮中的一个典型代表而已。
传统互联网的增长红利已经见顶,粗放式的流量打法已经彻底失效。未来的企业竞争,不是比谁的人多,而是比谁的算力强、谁的模型聪明。曹操出行提出AI原生,就是在试图打破原有的路径依赖,用AI来重塑企业的基因。哪怕这个转型过程会非常痛苦,甚至会有反复,但这都是不得不走的路。
说到这儿,我想多说一句。很多人看这个新闻会觉得"又是炒概念",我倒不这么看。当然,概念肯定有,但背后的产业逻辑是真实的。网约车的利润天花板是真实的,第二梯队的困境是真实的,资本市场对传统互联网服务的审美疲劳也是真实的。曹操出行选择在这个节点上全面押注AI,与其说是投机,不如说是一个第二梯队玩家在有限窗口期内做出的最理性的选择。
不过,至于最终能否成功,还要看其AI技术能否真正落地,能否在降本增效上拿出实实在在的成绩,而不是仅仅停留在PPT和概念上。毕竟,资本市场最终看的还是结果,而不是故事。
喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Mazda CX-9 同 Mercedes-Benz GLE 嚟做比較。今日我哋由多個方面做一次詳細嘅對比,幫你節省做功課嘅時間。


Mazda CX-9 喺馬來西亞嘅 OTR 售價係 RM 328,810 - 345,810,一共有 2 個版本,包括 2023 2.5T 4WD(RM 345,810)、2023 2.5T 2WD(RM 328,810) 等。
Mercedes-Benz GLE 喺馬來西亞嘅 OTR 售價係 RM 544,888 - 544,888,一共有 1 個版本,包括 Standard(RM 544,888) 等。
由價錢睇落,Mazda CX-9 嘅起步價確實比 Mercedes-Benz GLE 平咗 RM 216,078。如果你預算有限,Mazda 嘅入門版已經可以滿足日常需求。不過都要注意,平嗰幾千蚊,可能喺配備上會有取舍,具體要看你嘅需求。

Mazda CX-9 車身長 4500 mm,後備箱 450 L。
Mercedes-Benz GLE 車身長 4400 mm,後備箱 400 L。
空間方面,Mazda CX-9 嘅車身比 Mercedes-Benz GLE 長咗 100 mm,車內乘坐空間會稍微寬裕啲,尤其係後座腿部空間。如果你經常載家人或者需要放嬰兒車,大少少嘅車身確實更實用。

Mazda CX-9 採用 FWD 驅動方式。
Mercedes-Benz GLE 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。

Mazda CX-9 同 Mercedes-Benz GLE 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑好嗰款;如果你更在意性價比同配備,嗰就揀配置更豐富嗰款。最終都係建議兩款都去試駕,親身體驗先係最重要嘅。

總括嚟講,Mazda CX-9 同 Mercedes-Benz GLE 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵都係要看你嘅個人需求同預算。建議大家做好功課,多比較幾間車行之報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅汽車市場,好多買家喺揀車嗰陣都會將 Hyundai Palisade 同 Volvo XC60 比較。今日我哋由多個方面詳細對比,幫你慳啲做功課嘅時間。


Hyundai Palisade 喺馬來西亞嘅 OTR 售價係 RM 368,838 至 399,838,合共 4 個版本,包括 2023 3.8L 2WD Luxe 7 Seats Petrol(RM 399,838)、2023 2.2T 4WD Executive 7 Seats Diesel(RM 389,838)、2023 3.8L 2WD Luxe 8 Seats Petrol(RM 378,838)等。
Volvo XC60 喺馬來西亞嘅 OTR 售價係 RM 328,888 至 328,888,合共 1 個版本,包括 2025 2.0T Core(RM 328,888)等。
睇價錢,Volvo XC60 嘅起步價比 Hyundai Palisade 平咗 RM 39,950。實講,喺呢個價位段,幾千蚊嘅差距其實唔算大,關鍵仲係睇整體性價比同長期使用成本。

Hyundai Palisade 採用 FWD 驅動方式。
Volvo XC60 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大區別。

Hyundai Palisade 保養保證 5 年/300,000 公里,保養間隔 每 10,000 公里或 6 個月。
Volvo XC60 保養保證 5 年/無限里程,保養間隔 每 10,000 公里或 6 個月。
Hyundai Palisade 同 Volvo XC60 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,就揀配備更豐富嗰款。最後仲係建議兩款都去試駕,親身體驗先係最重要。
總括嚟講,Hyundai Palisade 同 Volvo XC60 都係馬來西亞市場好唔錯嘅車型。揀邊輛,關鍵仲係睇你個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,先去試駕先做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Mazda CX-60 同 Mercedes-Benz GLC 嚟做比較。今日我哋從多個方面做一個詳細嘅比較,幫你攞省做功課嘅時間。

Mazda CX-60 喺馬來西亞嘅 OTR 售價係 RM 200,510 - 252,873,合共有 2 個版本,包括 2026 3.3T 4WD High Plus(RM 252,873)、2025 2.5L 2WD High(RM 200,510) 等。
Mercedes-Benz GLC 喺馬來西亞嘅 OTR 售價係 RM 336,888 - 336,888,合共有 2 個版本,包括 GLC 200(RM 290,000)、GLC 300(RM 340,000) 等。
從價錢嚟看,Mazda CX-60 嘅起步價確實比 Mercedes-Benz GLC 平咗 RM 136,378。如果你預算有限,Mazda 嘅入門版已經可以滿足日常需求。但都要注意,平嗰幾千蚊,可能喺配備上會有取舍,具體要看你嘅需求。

Mazda CX-60 搭載 2.0L 4-cyl,馬力 170 hp。官方油耗 8.0 L/100km。
Mercedes-Benz GLC 搭載 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
動力方面,Mercedes-Benz GLC 嘅 2.0L Turbo 比 Mazda CX-60 嘅 2.0L 4-cyl 多咗 50 匹馬力。不過日常喺市區開嘅話,兩款車嘅動力都夠用,唔會覺得唔夠力。

Mazda CX-60 保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
Mercedes-Benz GLC 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
Mazda CX-60 同 Mercedes-Benz GLC 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更看重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就選配置更豐富嗰款。最終都係建議兩款都去試駕,親身經歷先係最重要嘅。
總體嚟講,Mazda CX-60 同 Mercedes-Benz GLC 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵都要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對無錯。


車型概覽

JAECOO J6 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講同級車比較,幫你用買家角度篩走唔適合嘅選擇。 近期市場討論到「Jaecoo 6香港車系全新陣容登場!頂規型號6T首發」,代表呢類車型仍然有一定關注度。
零售價 HK$ 188,112 - 242,100、完稅價 HK$ 289,888 - 390,306 令預算位置更清楚,買家可以先估算月供、保險、泊車同日常開支。
購車價格指南
JAECOO J6 嘅購車預算可以先由 零售價 HK$ 188,112 - 242,100、完稅價 HK$ 289,888 - 390,306 開始計。香港買車唔只係睇車價,月供、保險、牌費、泊車同能源成本都會影響每月壓力。
如果有幾個版本可揀,可以先將 2025 371km 後驅長續航版(HK$ 289,888)、2025 364km 四驅長續航版(HK$ 390,306)、2026 436km 四驅T版(價格待確認)、2026 Pro版(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 JAECOO J6 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
65.69/69.77 kWh 嘅電池容量,真正意義係可以幫你估算一星期通勤同周末出車要唔要中途補電。 17.9/19 kWh/100km 嘅耗電表現,會影響你去快充站或者屋苑充電位嘅頻率。 135/205 kW、220/385 N·m 嘅輸出,令高速併線同短距離超車更有信心。 車長 4406/4433 mm、車闊 1910/1916 mm、車高 1715/1741 mm、軸距 2715 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。
優缺點分析
JAECOO J6 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:預算位置清楚,方便同同級車直接比較、日常能源成本有基本參考、電池同續航資訊有助安排通勤同補電。
要留意嘅係,要先確認屋苑、公司或常去商場嘅充電條件、香港停車場同窄路使用要留意車身闊度。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 JAECOO J6 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「JAECOO J6 EV 係咪一部純電動越野車?」簡單講,JAECOO J6 EV 係一款純電動越野車,採用「方盒子」One Box 硬朗造型,線條方正有力,有別於一般 SUV。車身配備車頂行李架、合金摺梯同尾門雜物箱等越野裝備,適合鍾意戶外活動或追求與眾不同風格嘅用家。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 JAECOO J6 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先用 零售價 HK$ 188,112 - 242,100、完稅價 HK$ 289,888 - 390,306 鎖定預算圈、再睇動力係咪足夠應付高速併線同滿載、再比較能源成本同補能便利、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南

擁有 JAECOO J6 最重要係先諗清楚充電節奏。屋苑、公司或者常去商場只要有穩定充電選項,電動化用車就會容易相處好多。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。


車型概覽

長安CS75 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講整體購車判斷,幫你用買家角度篩走唔適合嘅選擇。
售價仍待確認,買家可以先把佢放入候選名單,等價格落實後再同同級車逐項比較。
購車價格指南
長安CS75 目前售價仍未清晰,較理性嘅做法係先睇版本、車身大小同動力形式,等價格落實後再決定值唔值得落訂。
如果有幾個版本可揀,可以先將 2026 1.5T 手動版(價格待確認)、2026 1.5T 雙離合版(價格待確認)、2025 1.5T 雙離合版(價格待確認)、2024 1.5T 雙離合版(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 長安CS75 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
渦輪增壓、4 個 汽缸、1494 mL 排量 嘅動力底子,重點係市區跟車夠唔夠順、高速巡航會唔會吃力。 170 Ps / 125 kW / 192 Ps / 141 kW、260/310/300 N·m 嘅輸出,對滿載、上斜同超車都比單睇馬力數字更有意思。 車長 4742/4650 mm、車闊 1870/1850 mm、車高 1720/1715 mm、軸距 2786/2700 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。 手動(MT) / 濕式雙離合(DCT)、前置前駆 會影響起步順滑度、濕地穩定感同長途巡航性格。
優缺點分析
長安CS75 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:動力輸出對高速同上斜更有底氣、空間同車身尺寸方便家庭買家預判實用性。
要留意嘅係,香港停車場同窄路使用要留意車身闊度、售價未清晰前唔應該太早用性價比落結論。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 長安CS75 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「長安 CS75 空間同實用性表現係點樣?」簡單講,長安 CS75 為緊湊型 SUV,空間實用,後排同尾箱適合家庭使用。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 長安CS75 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先等售價落實,再決定佢應該同邊個級距比較、再睇動力係咪足夠應付高速併線同滿載、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 長安CS75 唔係買車一刻就完結,之後仲有保險、輪胎、保養、泊車同日常能源成本要處理。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

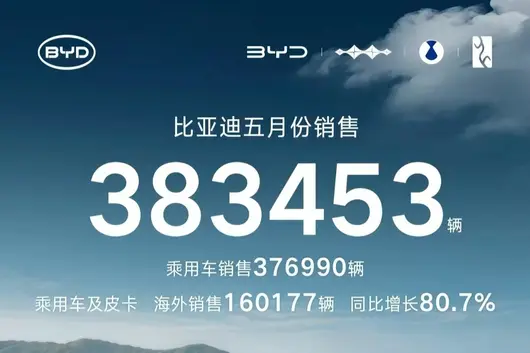
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
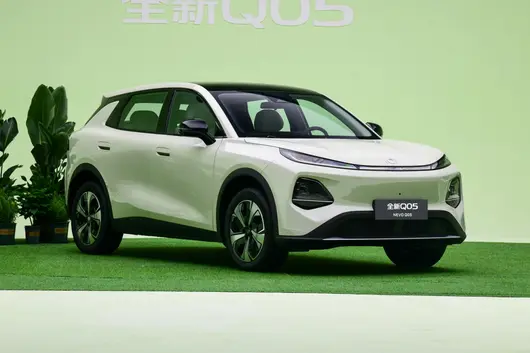
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。

(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
 (零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
 (長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
 (零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
 (長安啟源全新 Q05)
 (零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
 (長安啟源全新 Q05)
 (零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
 (長安啟源全新 Q05)
 (零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
 (長安啟源全新 Q05)

(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.

港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。

喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。

天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。

截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。

喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。

2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。

喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。

截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。

營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。

更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。

此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。

天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。
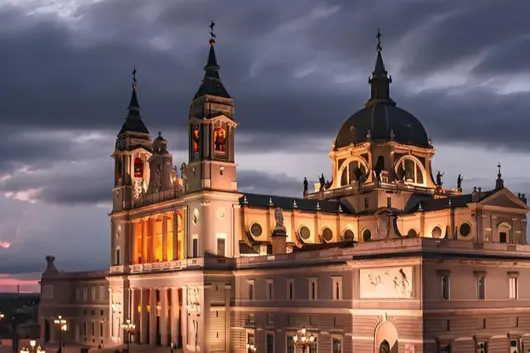
兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
Article | Auto Expert Compilation
Welcome Submissions | Please add WeChat auto188
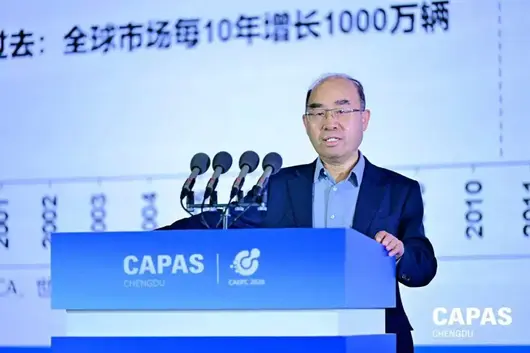
May 21, the opening ceremony of the 12th Chengdu International Auto Parts and Aftermarket Service Exhibition and the China Auto Ecosystem Partners Conference was held at Century City New International Conference and Exhibition Center in Chengdu. This event, themed "Leading the Trend 2026: A Must-Do, Taking a Step Ahead", focused on two current hot topics "Automotive Modification Industry Supply Chain" and "Automotive Complete Vehicle & Parts Industry Going Global", gathering industry elites to discuss the industry's future, injecting strong momentum into the high-quality development of the Southwest automotive industry.

During the keynote speech session, Xu Changming, former Deputy Director of the National Information Center and Senior Economist (Positive Level), believed that China's auto exports are at a historical leap stage, and the underlying logic for future growth is solid - release of demand in emerging global markets, qualitative change in competitiveness of Chinese brands, and active going global of the whole industry chain. Despite volatile factors such as trade friction and local protection, the trend of internationalization is irreversible. Enterprises should focus on quality and service, avoid vicious competition, promote the upgrade from "Complete Vehicle Export" to "Ecosystem Going Global", and achieve sustainable, upward global development amidst fluctuations.
The following is the speech transcript (compared based on recording by Auto Expert):
Respected guests, good morning! I am very happy to share my views on auto export and internationalization trends with you today.
This chart shows that during the "14th Five-Year Plan" period, China's auto exports achieved leapfrog development. Before 2020, for about ten-plus years, auto exports were stable at around 1 million vehicles. In 2021 it reached 2 million vehicles, and last year it reached 7.1 million vehicles. In five years, it increased by 6 million vehicles, which is a major trend. In the first four months of this year, exports reached 3.18 million vehicles, up 62% year-on-year, another year of rapid growth. China has large export volumes in major global regions and countries. Among them, exports to Asia are the highest, reaching 3 million vehicles last year, followed by Europe. At the country level, exports to three countries exceed 500,000 vehicles, exports to five countries are at the 300,000 vehicle level, and exports to more than ten countries are between 100,000 and 200,000 vehicles. Overall, China's export distribution globally is relatively balanced.
Everyone is concerned about the export trend in the next five years. We judge that in the next few years, China's auto internationalization will still maintain a relatively good development trend. There are three reasons:
Reason One: The potential of international markets is huge, providing potential opportunities for China's auto exports.
This chart shows the change in global auto market sales over the past twenty-plus years. Actually, going back forty years, from 1960, global total auto sales increased by 10 million vehicles every ten years. The fastest recent growth was from 2011 to 2017, increasing by 20.2 million vehicles in seven years. Why so fast? Because China and India, two major population countries, saw synchronous market growth in these seven years - China doubled, and India's market also rose. During the "14th Five-Year Plan" period, the past five years saw recovery growth from the pandemic, with the global market increasing by 13 million vehicles, of which China accounted for over 6 million vehicles, and we shared a larger portion of the increase. More critically, the growth of the global market mainly comes from emerging market countries. The two curves in the chart, blue represents mature markets, red represents emerging markets. Mature markets are stable at 40 million vehicles, no growth in twenty years, and even slightly declining in recent years; while emerging markets grew from over 9 million vehicles to over 40 million vehicles. Starting from 2021, consumption in emerging market countries surpassed mature markets. The characteristic is: purchasing power is not strong enough, but they want to buy cars. Therefore, Chinese cars have a market in models with moderate prices and higher performance/quality, and this market will grow relatively fast in the future.
Research on the basic law curve of auto demand: The horizontal axis is GDP per capita, the vertical axis is vehicle ownership per 1,000 people. The basic law is: when GDP per capita is between 1,000 and 3,000 USD, as long as the economy grows, ownership per 1,000 people rises, generating a large amount of new demand every year; after exceeding this range, ownership per 1,000 people no longer grows, mainly shifting to replacement demand. There are still many countries in the world at the bottom left - low GDP per capita, low ownership per 1,000 people. As long as these countries' economy grows in the future, demand will grow.
Looking at specific regions: Latin America, 660 million people, total sales last year 4.25 million vehicles. China has 1.4 billion people, Latin America is about half of China, according to China's per capita purchasing level, its sales should reach 12 million vehicles, but now it is only over 4 million vehicles, huge potential. Middle East region, 380 million people, sales last year 3.43 million vehicles, according to China level should reach around 7 million vehicles. ASEAN region, nearly 700 million people, sales last year only 2.8 million vehicles, sales corresponding to half of China's population should be 12 million vehicles, therefore huge growth space. Africa 1.5 billion people, more than China, sales last year only 1 million vehicles, not even a fraction of China's, potential is even greater. Of course, the prerequisite is economic growth. So, as long as the global economy, especially emerging market countries' economy grows, auto demand has great space, and these markets are exactly where Chinese cars have competitiveness.
Reason Two: The competitiveness of Chinese brand cars globally has improved rapidly, reflected in data performance and reputation.
First look at data: In 2020, for every 100 cars sold in overseas markets, Chinese brands only accounted for 0.8 cars. By last year, this number rose to 6.5 cars, growth was very fast. The share in emerging markets is higher, slightly worse in mature markets. The line below is our share per 100 cars in developed country markets, although also rising, overall share is low, less than 3 cars. But in emerging markets, for every 100 cars sold, we account for 13.6 cars, basically reaching Japan's level. Look at EVs, competitiveness is stronger: for every 100 EVs sold in overseas markets, we account for 18.7 cars; for every 100 fuel cars sold, we only account for 4 cars. EVs also account for nearly 10% in mature markets, and still growing. In emerging markets, for every 100 EVs sold, we account for over 50 cars, more than half are Chinese brands. Thirty years ago, the EV market was dominated by Germany, Japan, South Korea, and the USA, now in emerging markets more than half are Chinese brands.
Just having data is not enough. If the reputation is poor, it will repeat the fate of motorcycles - in 2002, 2003 we quickly became first in the Vietnam motorcycle market, but surpassed by Japan after three or four years because quality was not good. Now our reputation is very good. For example in Thailand, for every 100 EVs sold, Chinese brands account for 86 cars; in Indonesia, account for 92 cars. User evaluation is very high: Great Wall Motor customer feedback, Chinese EV safety systems are done very well, automatic follow, braking, anti-collision technologies are almost all present.
Fuel car reputation is also very good: 23.6% share in Malaysia fuel car market, 38.5% in Egypt. A multi-brand dealer in Malaysia evaluated, Chinese car prices are close to local brands, but configurations are far superior, especially in smart cockpits, sunroofs, electric seats, LED lights, etc., extremely attractive to young consumers. Egypt users say, initially felt owning Chinese cars was risky because Chinese cars often had faults before, but this view changed over the past five years, Chinese auto quality has significantly and unexpectedly improved.
These are conclusions obtained by the National Information Center through in-depth research. Good quality, good reputation, next step if spare parts supply and after-sales service system can be significantly improved, China's auto going global will be unstoppable - this is the extension of domestic competitiveness. Five years ago exports stayed at 1 million vehicles, because domestic competitiveness was not enough. Last year, independent brand domestic market share already reached 64%, while in 2020 it was only 33%.
Reason Three: Industry chain entities represented by complete vehicles are all actively promoting internationalization.
In terms of complete vehicles, three enterprises with million-unit exports: Chery 1.33 million vehicles, BYD 1 million vehicles, SAIC Passenger Vehicle plus Commercial Vehicle close to 1 million vehicles. Half million level: Geely, Great Wall, Changan. 100,000 level: JAC, Dongfeng, GAC, FAW. Enterprise distribution is also relatively balanced, will not affect overall exports due to individual enterprise issues. Chery has ranked first among Chinese brands in exports for 23 consecutive years, overseas sales revenue exceeded 100 billion yuan last year, overseas dealers reached 3,000. During Beijing Auto Show, Chery set up a separate hall, inviting overseas dealers to China to visit Wuhu factory. BYD chased very fast in the recent two years: 400,000 vehicles exports in 2024, reached 1 million vehicles in 2025, relying on EVs to open international market, brand reputation has formed. Others like SAIC, Changan, Great Wall also have unique advantages.
In addition, parts enterprises, logistics, dealers, automotive financial institutions, service agencies, etc. are all actively going global - as experts said "Ecosystem Going Global", although slightly weaker compared to complete vehicles, overall trend is good. Joint venture brands are also doing exports, last year reached 830,000 vehicles, Tesla, Kia, Volvo, Hyundai, Ford leading the way. Many joint venture enterprises see sales decline in China market, only relying on domestic market difficult to sustain, therefore all make export a strategy. Kia is most typical: domestic sales 100,000+ vehicles, exports 170,000 vehicles, maintain 300,000 vehicle scale, realized profit last year, became "Small but Refined" case. Volkswagen, Toyota, etc. are also researching how to utilize China production capacity and manufacturing capability for export, especially new energy vehicles.
As overall export volume rises, professional niche markets will also follow. For example, off-road vehicles, started two years late, accelerated starting 2023, reached 500,000+ vehicles last year, increased more than double for consecutive years. This March off-road vehicle exports 80,000 vehicles, at this scale annual is expected to reach 1 million vehicles. Next step, modified cars will also have good development. Used car exports will also increase. Therefore, future export forms will be diversified, both complete vehicles, also industry chains and ecosystem chains, can build factories themselves, also can utilize local production capacity, etc.
Of course, I also agree with the views of the two experts: exports will not rise in a straight line, but develop amidst fluctuations. Because auto is very important to any country, only exporting complete vehicles opponents will definitely not be willing, and cannot crush local industry. So, my confidence in exports is firm - it will definitely develop gradually forward amidst fluctuations.
Thank you all!