


首頁Skyline V35

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

把百万级超跑底盘卖进15万区间
第二代海豹07上市背后,是比亚迪一整个技术江湖
——产品力·用户圈层·海洋网江湖地位·技术家底与全球销量深度解读
(汽车百人汇 娟子说车 魏惠娟)
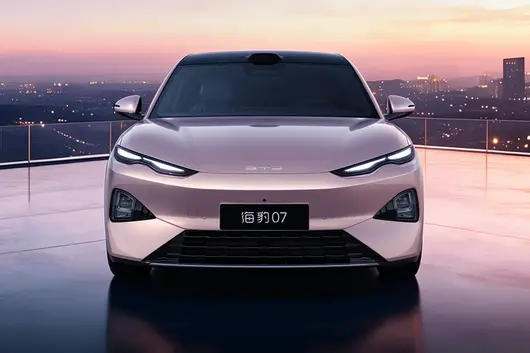
11月5日,比亚迪海洋网的中大型轿车——第二代海豹07正式上市。新车提供纯电、插混两种动力共五款配置,官方指导价13.99万–17.29万元,叠加不限品牌4000元置换补贴后,超级置换价仅13.59万元起。


比起价格,更值得琢磨的是一件事:比亚迪品牌首搭的云辇-M智能磁流变悬架出现在16.89万元的纯电旗舰型上,把百万级超跑同款底盘技术拉进了15万级家用轿车区间。这不是简单的"堆料",而是一种宣言:过去只属于仰望U9这类百万级超跑的底盘控制技术,如今成了主流家庭轿车可以摸到的配置。
云辇-M的硬指标足够说明问题:磁液直驱,1毫秒内极速响应;100–10000N超宽域阻尼调节;加之路面预瞄功能,悬架在车轮碾过坑洼之前就已调整姿态。配合前双叉臂+后增强型五连杆独立悬架,轮胎可以始终紧贴地面。放在三年前,这套组合只可能出现在售价百万的性能车或旗舰豪华车上。
这篇文章想聊清楚四件事:第二代海豹07的产品力到底处于什么水平;它瞄准的是哪一群人;海豹车系与海洋网在比亚迪体系内处于什么位置;以及从整个云辇技术谱系和全球销量版图看,比亚迪今天的"江湖地位"究竟是怎么来的。

第二代海豹07共推出五款配置,其中插混两款、纯电三款。官方指导价13.99万–17.29万元,置换补贴后落在13.59万–16.89万元区间:

这个价格带的指向非常清晰:往上够不到主流合资B级燃油车的高配(雅阁、凯美瑞、帕萨特的高配车型普遍落在18万以上),往下又比紧凑型纯电轿车多出整整一个级别。13.59万元买到的是一台车长5080mm、轴距2960mm的纯正C级轿车——较老款车长增加85mm、轴距增加60mm,正式从B+级升入C级。

底盘是第二代海豹07最硬的底气。前双叉臂+后增强型五连杆的悬架结构本身已属同级高规格,真正的分水岭在云辇系统:16.89万元的纯电旗舰型搭载云辇-M智能磁流变车身控制系统,其余版型配备云辇-C智能阻尼车身控制系统。

云辇-M的核心是磁流变液:电流一变,液体的阻尼特性在1毫秒内完成切换,阻尼力可在100N到10000N之间连续调节。它的前身是搭载于百万级超跑仰望U9的主动悬架技术,如今第一次出现在比亚迪品牌(而非仰望品牌)的车型上——这正是"技术下放"四个字最具体的注脚。再叠加路面预瞄与iTAC2.0智能扭矩控制系统,这台车在操控响应和行驶舒适性之间不再需要做选择题。
3. 空间与舒适:C级尺寸的"全员友好"5080×1960×1495mm的车身和2960mm的轴距,换来的是后排真正意义上的从容。储物层面,纯电版提供160L同级最大前备箱、618L后备箱和全车39处储物空间,全家出行的装载难题一次性解决。舒适配置上,主驾零重力座椅支持按摩、通风、加热,一键开启缓解疲劳;大床模式放倒主副驾与后排贴合;再加上20扬帝瓦雷音响、6.8L智能冷暖冰箱、电动天幕遮阳帘——这些配置单拉任何一项,都是过去30万级车型才舍得给的。

纯电版:搭载第二代刀片电池与闪充技术,245kW/300kW两档后驱电机,CLTC续航775km,百公里电耗最低9.8度;补能速度是最大惊喜——10%充至70%约5分钟、9分钟基本充满,即便在零下30℃的低温环境也只多3分钟,"5分钟充好、9分钟充饱"把纯电补能焦虑压缩到了接近加油的体验。
插混版:插混专用1.5T高效发动机+160kW电机,CLTC纯电续航330km——这个纯电续航足以覆盖绝大多数人的一周通勤,日常基本可当纯电车开;NEDC亏电油耗低至3.3L/100km,满油满电综合续航1700km,长途无焦虑。纯电攻体验、插混攻普及,两条腿都很扎实。

第二代海豹07是比亚迪智慧生态2.0的首搭车型,中控超窄边框生态屏可外接Diva智能表盘、百变按键等生态配件,AI日报、魔方传声筒、海豹IP萌宠等功能悉数上车;驾驶侧配备26英寸W-HUD。辅助驾驶搭载天神之眼B-辅助驾驶激光版(DiPilot 300),支持城市领航、高快领航和泊车辅助,并承诺为智能泊车与城市领航"双兜底"——在智驾责任边界备受关注的当下,这个承诺本身就是竞争力。

安全层面,第二代刀片电池+CTB电池车身一体化技术让电池安全与整车刚性双重提升,全系标配至高9安全气囊;iTBC爆胎稳行控制系统可在高速爆胎瞬间稳住车身,不跑偏、不失控。
小结产品力:第二代海豹07没有只偏一头——想要跑车那种操控质感,它给得到;家人要的宽敞、舒适和实用,它也没落下。一台"驾驶者的家用车",自己开着有乐趣,带着家人不委屈。
三、用户圈层:它要抓住的,是"不愿将就"的家庭要读懂第二代海豹07,得先看它的用户画像。海豹车系从第一代开始,就是海洋网里承担"技术图腾"角色的车型——海豹EV当年对标的是特斯拉Model 3,主打年轻、运动、科技;海豹07把这套基因做了家庭化转译:尺寸从B+级拉满到C级,配置全面转向全员舒适,但驾控基因被刻意保留,甚至用云辇-M进一步加码。
由此,它的目标圈层大致是三类人。一是15万–17万预算、从紧凑级车升级换购的年轻家庭:第一辆车是A级轿车或小型SUV,孩子大了、需求变了,需要大空间但不想牺牲驾驶乐趣;二是合资B级燃油车的"替代者":原本盯着雅阁、凯美瑞、帕萨特的用户,发现同价位能买到大一级尺寸、低一个数量级用车成本的新能源C级轿车;三是技术敏感型用户:关注底盘、关注智驾、关注补能,愿意为"硬核配置"做决策的人群——云辇-M的存在,很大程度上就是给这批人一个无法拒绝的理由。

这个圈层的共同点是"不愿将就":不接受"家用车=无聊",也不接受"运动=不实用"。第二代海豹07的定价和配置策略,本质上是把过去需要50万以上预算才能同时满足的两种诉求,压进了一个普通家庭够得着的区间。
四、海豹与海洋网:比亚迪体系里的"年轻化尖刀"在比亚迪的版图里,海洋网与王朝网并称两大销量基盘。王朝网(秦、汉、唐、宋、元)气质偏稳重大气,覆盖更传统的家庭用户;海洋网(海鸥、海豚、海豹、海狮、驱逐舰)从命名到设计都更年轻、更个性,是比亚迪触达年轻消费群体的"尖刀"。
数据可以说明海洋网的分量:2026年10月,比亚迪海洋网单月销售202,709辆,其中海狮车系61,643辆;而海豹车系当月销售46,834辆,2026年1–10月累计已达351,577辆。[1]
放在整个比亚迪体系里看:2026年10月比亚迪新能源汽车总销量490,168辆,创年内新高;王朝网与海洋网合计423,843辆,仍是绝对的销量基本盘。[2]
海豹车系在海洋网中的角色,恰似汉之于王朝网——它未必是销量最大的那个,但它是技术形象和品牌溢价的担当。第二代海豹07把云辇-M、智慧生态2.0、闪充三个"首搭"集于一身,这个待遇本身就是海洋网江湖地位的直接体现:技术旗舰的位置,官方给到了海豹,而不是别人。
五、从云辇谱系看比亚迪的技术家底一台15万级家轿能配上百万级悬架,前提是这套技术已经体系化、规模化。把镜头拉开,可以看到比亚迪底盘与技术体系的完整谱系:
1. 云辇家族:一套悬架技术的"完整金字塔"云辇是比亚迪的智能车身控制系统家族,按技术路线分层,恰好构成一座金字塔:塔基是云辇-C智能阻尼控制,已广泛搭载于王朝、海洋网多款车型,主打滤震与舒适;往上是云辇-A智能空气悬架,主打高度与软硬可调,多见于腾势品牌;塔身是云辇-P智能液压悬架,支撑起仰望U8的硬派越野与原地调平;塔尖则是云辇-X全主动悬架(仰望U9,让超跑"跳舞"、三轮行驶的那套)与云辇-Z悬浮电机悬架(仰望U7),代表全球车身控制的最高水平。
而云辇-M——这次随第二代海豹07首次进入比亚迪品牌——走的是磁流变路线,响应速度介于云辇-C与云辇-X之间,成本却远低于塔尖技术。它的意义在于:比亚迪已经有能力把"塔尖"技术逐级下放,让每一层产品都能吃到上一层的红利。这正是体系化研发对消费者的真实价值。

与云辇协同工作的,还有一整套底盘电子控制系统:iTAC智能扭矩控制系统通过电机旋变传感器提前50毫秒级调整扭矩分配,把打滑扼杀在发生之前;iTBC爆胎稳行系统则针对高速爆胎这一极端场景,在毫秒间稳住车身姿态;CTB电池车身一体化技术让刀片电池直接成为车身结构件,整车扭转刚度大幅提升,所有悬架的努力都建立在一个足够刚强的"地基"之上。底盘技术从来不是单点胜负,而是悬架、结构、电控的系统工程——这正是整车厂相对供应商拼装模式的根本优势。
3. 更大的技术版图:从刀片电池到天神之眼把视角再拉大,比亚迪的技术家底远超底盘:电池侧有刀片电池及其第二代产品,配合CTB构成安全与结构的双重底座;电动化平台有e平台3.0 Evo与支撑兆瓦闪充的超级e平台;混动侧有第五代DM技术,亏电油耗屡创全球新低;智能化侧,"天神之眼"辅助驾驶系统按算力与传感器分层(A/B/C三个版本),并已对智能泊车与城市领航做出"双兜底"承诺,是行业内唯一;更高端的还有易四方四电机独立驱动(仰望U8原地掉头、应急浮水的底气)。
支撑这套体系的,是长年高强度的研发投入:截至2024年末,比亚迪累计研发投入已超1800亿元,研发人员规模突破12万人,研发团队规模在全球车企中位居第一。[3]
可以这样总结:别家做一款新车是"选型",比亚迪做一款新车是"点菜"——云辇、刀片、DM、e平台、天神之眼,每一道都是自己的菜,成本、迭代节奏和下放速度都握在自己手里。

2025年是比亚迪的里程碑之年:全年销售新能源汽车460.2万辆,连续四年位居全球第一;以460.2万辆的总销量首次跻身全球车企集团销量前五,超越通用、福特、本田、日产,成为首个进入该榜单前五的中国汽车集团——从2023年首次进入全球前十(第九名),到2024年第六,再到2025年前五,三年三个台阶。[4]
更值得注意的是结构性的变化:2025年比亚迪纯电动车型销售225.67万辆,同比增长27.86%,首次超越特斯拉,成为全球纯电销量冠军;海外市场销量超过104.9万辆,同比大增145%,在中国香港夺得全品牌销量冠军,在意大利、西班牙、匈牙利等国位列新能源销量榜首,在泰国、印尼、巴西等新兴市场处于领先地位。全年营收突破8000亿元,达8039.6亿元。[5]
2. 2026:国内承压,海外接棒2026年的比亚迪并非一路坦途。受国内车市整体下行与竞争加剧影响,一季度销量同比下滑30.01%,压力持续到4月;从5月起销量逐月修复,10月单月销售490,168辆,创年内新高,1–10月累计362.17万辆,累计同比降幅已收窄至2.16%。[6]
关键的变量在海外:2026年前三季度,比亚迪海外销量133.78万辆,同比增长92.66%,在总销量中的占比从上年同期的21.52%跃升至42.72%;三季度营收与归母净利润分别同比增长13.59%和28.08%,业绩回暖主要由海外业务推动。截至2026年10月,比亚迪新能源汽车全球累计销量已突破1870万辆。
换句话说,比亚迪正在完成一次增长引擎的切换:国内从"增量市场"进入"存量博弈",海外则从"出口贸易"走向"本地化经营"。
3. 根本原因:四个字背后的体系能力第一,垂直整合带来的成本与技术自主权。从锂矿、电池、半导体、电机电控到整车,比亚迪把产业链关键环节握在自己手里。这套体系在价格战里意味着别人亏钱的价位它还能盈利,在技术下放里意味着百万级悬架可以下放到15万级车型而不至于亏本——第二代海豹07就是最新例证。
第二,全栈自研与"技术鱼池"策略。刀片电池、DM-i、e平台、云辇、天神之眼、易四方,每一项技术都经历了先在高价车型验证、再逐级下放的成熟路径。云辇从仰望U9的塔尖一路铺到海豹07,只用了几年时间。研发规模(超12万研发人员、累计投入超1800亿元)保证了鱼池里始终有下一批鱼。
第三,多品牌矩阵对价格带的完整覆盖。海鸥海豚守住10万内,秦宋元守住主流家用,海洋+王朝守住15万–25万,方程豹、腾势攻30万–60万,仰望立住百万级。每个价位段都有对应的品牌和车型接招,技术则在整个矩阵内自由流动。
第四,出海从"卖车"升级为"造城"。海外工厂、自有滚装船队、本地渠道与售后体系同步建设,使比亚迪在关税与地缘波动中仍保持九成以上的海外增速。海外单车利润接近1.6万元、远高于国内数千元的水平,也解释了为什么"国内卷价格、海外赚利润"能成为现实的经营策略。
第五,也应看到隐忧。国内销量下滑、单车利润承压、海外占比快速抬升带来的汇率与合规风险、以及行业价格战对盈利的持续压缩,都是这家公司在"全球前五"光环下的真实课题。江湖地位不是一劳永逸的封号,而是每天重新打出来的擂台。
七、结语回到第二代海豹07。一台13.59万元起售的C级轿车,配上百万级超跑同源的磁流变悬架——这件事放在五年前的中国汽车市场,是不可想象的。它之所以能发生,是因为比亚迪用二十多年的垂直整合和全栈自研,把"技术下放"从口号做成了流水线。
对消费者而言,这意味着15万级家用轿车第一次不需要在"开得爽"和"坐得舒服"之间做选择;对行业而言,这意味着底盘技术竞争的下限被整体抬高了一个身位;对比亚迪自己而言,这是它从"新能源销冠"走向"全球汽车巨头"的路途中,一次标准的产品力展示。
把超跑底盘卖进15万区间,看似是一台车的卖点,实则是一家公司的答案:江湖地位从来不是喊出来的,是研发费用的累计、是技术鱼池的厚度、是销量曲线的斜率,一款车一款车攒出来的。第二代海豹07,不过是这个答案的最新一行。
(数据来源:比亚迪官方产销快报、2025年年报及公开报道;文中配置参数以官方新闻稿为准。)
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會攞 Toyota Harrier 同 Land Rover Discovery Sport 嚟做比較。呢兩款車喺價錢同定位上都好接近,今日我哋就從多個方面做一個詳細嘅對比,幫你節省做功課嘅時間。
Toyota Harrier 喺馬來西亞嘅 OTR 售價係 RM 289,000 - 289,000,合共 1 個版本,包括 2026 HEV 2.5L Standard(RM 289,000) 等。
Land Rover Discovery Sport 喺馬來西亞嘅 OTR 售價係 RM 499,800 - 499,800,合共 1 個版本,包括 Standard(RM 499,800) 等。
由價錢睇,Toyota Harrier 嘅起價確實比 Land Rover Discovery Sport 平咗 RM 210,800。如果你預算有限,Toyota 嘅入門版已經滿足日常需要。不過都要留心,平嗰幾千元,喺配備上可能會有所取舍,具體要睇你嘅需要。

Toyota Harrier 配備 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
Land Rover Discovery Sport 配備 3.0L Turbo,馬力 350 hp。官方油耗 12.0 L/100km。
動力方面,Land Rover Discovery Sport 嘅 3.0L Turbo 比 Toyota Harrier 嘅 2.0L Turbo 多咗 130 匹馬力。不過日常喺市區開,兩款車嘅動力都夠用,唔會覺得唔夠力。

Toyota Harrier 採用 FWD 驅動方式。
Land Rover Discovery Sport 採用 4WD 驅動方式。
Toyota 嘅 FWD 同 Land Rover 嘅 4WD 喺操控上會有唔同感受,建議試駕對比。

Toyota Harrier 保修 5 年/無限里程,保養間隔 每 10,000km 或 6 個月。
Land Rover Discovery Sport 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。

Toyota Harrier 同 Land Rover Discovery Sport 都係馬來西亞市場嘅主流選擇,適合家庭用、日常通勤。如果你更重視品牌口碑同二手價,可以優先考慮口碑更好嗰款;如果你更重視性價比同配備,就揀配備更豐富嗰款。最終始終建議兩款都去試駕,親身體驗先至係最重要嘅。

總體嚟講,Toyota Harrier 同 Land Rover Discovery Sport 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵始終係要睇你嘅個人需要同預算。建議大家做足功課,多比較幾間車行嘅報價,再去試駕先至做最終決定。買車係件大事,花啲時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿豐田 Yaris Cross 同現代 Tucson 嚟做比較。這兩款車喺價格同定位上都幾接近,今日我就從多個方面做一个詳細比較,幫你省返做功課嘅時間。
豐田 Yaris Cross 喺馬來西亞嘅 OTR 售價係令吉 99,900 - 109,900,一共有 2 個版本,包括 2026 年 1.5L 標準型(令吉 99,900)、2026 HEV 1.5L 標準型(令吉 109,900) 等。
現代 Tucson 喺馬來西亞嘅 OTR 售價係令吉 143,888 - 197,888,一共有 5 個版本,包括 2025 HEV 1.6T AT 2 驅 Prestige(令吉 197,888)、2025 1.6T DCT 4 驅 Prestige(令吉 186,888)、2025 1.6T DCT 2 驅 Prime(令吉 164,888) 等。
由價錢睇,豐田 Yaris Cross 嘅起售價確實比現代 Tucson 平咗令吉 43,988。如果你預算有限,豐田嘅入門版已經可以滿足日常需要。但都要注意,便宜嗰幾千蚊,可能喺配備上會有取捨,具體要看你嘅需要。

豐田 Yaris Cross 車身長度 4400 毫米,行李廂 400 公升。
現代 Tucson 車身長度 4400 毫米,行李廂 400 公升。
兩款車嘅尺寸幾乎一樣,車內空間差別唔大。呢個級距嘅車,日常使用完全夠用。

豐田 Yaris Cross 採用 FWD 驅動方式。
現代 Tucson 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。

豐田 Yaris Cross 同現代 Tucson 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,嗰就揀配備更豐富嗰款。最終都係建議兩款都去試駕,親自體驗先係最重要嘅。

總括嚟講,豐田 Yaris Cross 同現代 Tucson 都係馬來西亞市場好唔錯嘅車型。揀邊輛,關鍵仲要睇你嘅個人需求同預算。建议大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

In the SUV market in Malaysia, many buyers compare Honda CR-V and Subaru Outback when choosing a car. These two models are quite close in price and positioning. Today, we will make a detailed comparison from multiple aspects to help you save time on research.
The Honda CR-V's OTR price in Malaysia ranges from RM 178,200 to RM 195,900, with a total of 4 versions, including 2026 e:HEV 2.0L 2WD RS (RM 195,900), 2026 1.5T 4WD V (RM 181,900), 2026 e:HEV 2.0L 2WD E (RM 178,200), etc.
The Subaru Outback OTR price in Malaysia ranges from RM 260,000 to RM 280,000, with a total of 2 versions, including 2025 2.4T R-Touring EyeSight (RM 310,340), 2025 2.5L Touring EyeSight (RM 280,340), etc.
In terms of price, the starting price of Honda CR-V is indeed RM 81,800 cheaper than Subaru Outback. If your budget is limited, Honda's entry-level version can already meet daily needs. But keep in mind that the few thousand ringgit savings might involve trade-offs in features, depending on your specific requirements.

Honda CR-V comes with a 2.0L 4-cyl, horsepower 170 hp. Official fuel consumption 8.0 L/100km.
Subaru Outback comes with a 2.0L Turbo, horsepower 220 hp. Official fuel consumption 9.5 L/100km.
In terms of power, the Subaru Outback's 2.0L Turbo has 50 more horsepower than the Honda CR-V's 2.0L 4-cyl. However, for daily city driving, both cars have sufficient power and won't feel underpowered.

Honda CR-V body length 4500 mm, trunk 450 L.
Subaru Outback body length 4400 mm, trunk 400 L.
Regarding space, the Honda CR-V body is 100 mm longer than the Subaru Outback, and the interior seating space will be slightly more spacious, especially the rear legroom. If you frequently carry family or need to fit a stroller, the larger body is indeed more practical.

Honda CR-V warranty 5 years/unlimited mileage, maintenance interval every 10,000km or 6 months.
Subaru Outback warranty 3 years/100,000km, maintenance interval every 10,000km or 6 months.

Overall, Honda CR-V and Subaru Outback are both excellent models in the Malaysian market. Which one to choose depends mainly on your personal needs and budget. It is recommended to do your research, compare quotes from multiple dealerships, and then test drive before making a final decision. Buying a car is a major matter; spending some time doing homework will never be wrong.

Monthly sales of 100,000, yet market cap only half of competitors: Why can't Leapmotor's scale earn valuation?

Evening of August 24, Leapmotor released an interim performance report with almost flawless data: First half deliveries 356,487 units, YoY growth 60.8%, ranking first among New EV makers; Revenue 38.11 billion yuan, growth 57.2%; Net profit attributable 208 million yuan, achieving profitability for two consecutive half-years. July single-month deliveries 101,267 units, becoming the first domestic New EV maker to break 100,000 monthly sales. Established for 11 years, cumulative deliveries exceeded 1.6 million units.

Leapmotor displayed its full series of models at a promotion event | Source: Leapmotor official website
But the reaction from the capital market was quite interesting. As of the August 26 market close, Leapmotor's HK stock market cap was approximately HKD 45.36 billion; on the same day, Nio was about HKD 85.5 billion, XPeng about HKD 88.4 billion, and Li Auto about HKD 97.7 billion. The one selling the most, its market cap is less than half of Li Auto. More importantly, Li Auto's second-quarter net loss was 1.705 billion yuan, XPeng's second-quarter net loss was 1.34 billion yuan — they are making losses, yet the market is willing to give them higher prices.
Being the sales champion doesn't beat the market cap, this is not just a problem for Leapmotor, but it is Leapmotor's most prominent issue. This deep dive wants to clearly break down three things: how exactly these 200 million in profit was squeezed out; why that overseas report is Leapmotor's real trump card; and what evidence the market is waiting for before re-pricing this company.
01 How the 200 Million in Profit was "Squeezed" OutFirst, let's look at the profit structure. First half revenue of 38.11 billion yuan and 11.7% comprehensive gross margin, corresponds to gross profit of approximately 4.45 billion yuan. After deducting R&D, sales, administrative and other period expenses and taxes, final operating profit was 128 million yuan, with net profit attributable to shareholders of 208 million yuan.
Converted to per unit: 356,487 vehicles, with an average profit of only about 585 yuan per car. A 100,000 yuan level car, profit isn't enough for a decent meal. Net margin 0.55%, thin as a blade.

Leapmotor 2026 Semi-Annual Report · Performance Highlights | Source: Leapmotor official website
These 208 million are pieced together from several parts. The first part is selling cars itself. Management gave whole vehicle gross margin guidance of 10~11 percentage points at the conference call — meaning selling cars is low profit high volume, the bulk of gross margin depends on scale rolling. The second part is carbon credits, contributing 800 to 900 million yuan in the first half, about 500 million yuan in the second quarter. This is the profit's "plug-in", and its unit price is declining, management original words: "Carbon credit sales unit price fell compared to last year", "Just like the path our country walked back then". The third part is R&D service revenue, contributed in the first half but not much; the fourth part is Leapmotor International, slightly profitable but with a small loss in the first half due to exchange rates, management expects to recover in the second half.
The trend of gross margin also hides structure: First half comprehensive gross margin 11.7%, YoY decline of 2.4 percentage points, but second quarter single quarter recovered to 12.6%, QoQ improvement 3.2 percentage points. Full year guidance is 13%~14%. Management attributed the improvement to scale effect and raw material price stabilization — to translate: volume growth is diluting per-unit cost, but carbon credit decline is pulling profit margin back from the other side.
Compare with peers, the irony is stronger. Li Auto second-quarter net loss 1.705 billion yuan, deliveries 98,330 units, YoY still declined 11.5%; XPeng second-quarter net loss 1.34 billion yuan. Full market only Leapmotor, the only New EV maker stable in making money, market cap yet bottomed out. In Tech Jungle's view, the market is not that it doesn't recognize profit, but doesn't recognize "profit of doubtful gold content" and "profit that hasn't proven sustainable scaling".
02 Going Overseas: The Real Profit Pool is FormingLeapmotor interim report's most eye-catching numbers are actually not in the domestic market. First half exports 96,294 units, YoY growth 372.6%, already exceeded 2025 full year export total, accounting for 27% of total sales; July single month exports 17,569 units. European market revenue 8.875 billion yuan, YoY surge 379.7%, accounting for about 23% of total revenue.

Leapmotor exceeded 900,000 global deliveries in June | Source: Leapmotor official website
Overseas per-unit gold content is far higher than domestic: Same platform models selling price in Europe is several times that of domestic, even after incurring freight, tariffs and channel costs, per-unit gross margin is clearly better than the involution of domestic market. This is the real meaning of "Second growth curve" — not selling tens of thousands more cars, but selling a market with higher profit margin.
Local assembly map also unfolds simultaneously: Malaysia relies on Stellantis Kedah plant, C10 already mass production, B10 planned Q3 mass production launch; European Spain Zaragoza plant completed retrofit, B10 Q3 start production, B05 trial production within the year, 2027 formal mass production, supporting battery plant Q3 start mass production; South America selected Brazil Goiania plant, B10 planned 2027 second half start production. Management stance is: This year overseas expected around 200,000 units (start of year target 100,000~150,000 units), next year target 350,000~400,000 units, internal challenge 400,000 units.
But management also said two sentences worth noting truths. First is local production gross margin indeed better than whole vehicle export has improvement, "but improvement not as obvious as imagined", profit margin's real improvement needs to wait for "policy changes" — simply put, wait for EU tariff and local procurement rules to clear. Second is RoRo ship capacity tight, company has reached cooperation with Shipping Group, "Full year 200,000 units is guaranteed". Going overseas doesn't lack orders, lacks capacity and policy window.
There is also a detail ignored by most interpretations: Leapmotor International is Leapmotor 49%, Stellantis 51% joint venture, when established agreed on previous three years lower gross margin split. Management explicitly said at conference call, both parties "3-year agreement period" gradually approaching, will sit down to re-communicate. This is both an area where first half comprehensive gross margin was "structurally suppressed" dark corner, also potential option for gross margin upward repair in future one to two years — Stellantis sells every car, after re-pricing may contribute more profit.
03 Balance Sheet: Where Did Money and Goods GoSeveral numbers on the interim report balance sheet explain Leapmotor's current strategy better than income statement.

Leapmotor 2026 Semi-Annual Report · Financial Performance | Source: Leapmotor official website
Cash and equivalents 38.59 billion yuan, borrowing only 2.39 billion yuan, net cash over 36 billion yuan. A car company with annual sales of hundreds of thousands of units holding such scale of cash, at least on cash flow there is no danger signal.
What is truly worth pondering is inventory: 9.27 billion yuan, QoQ increase 103.7%, approximately equal to 1.65 months cost of sales. Why prepare so much inventory? Two months ago this number was not even half. The answer is written in the timeline: A05 launched on August 11, A10 enter ramp-up, D19 and C series volume, second half delivery target obviously is to go high; plus exports in transit whole vehicles and parts all floating at sea, inventory double more like intentional "ammo".
More ruthless is accounts payable: 47.08 billion yuan, is 5.1 times inventory. This shows in supply chain system, upstream suppliers are advancing funds for Leapmotor. Use suppliers' goods first, then pay money, account period dragged longer, Leapmotor cash more abundant. This is an invisible low cost financing, also realization of scale effect — only when your procurement volume large enough no one dares easily cut supply, this chain then can move. Huawei-style "V-formation supply chain" in auto industry replicate difficulty compared to consumer electronics is much bigger, but Leapmotor is trying to run with same logic.
Future two years still need to spend a big sum: As of end of June, company for purchase of properties, factory and equipment capital commitments were 7.76 billion yuan, first half capital expenditure 2.03 billion yuan, mainly used for new factory equipment and new car production line introduction. Where do these money go? Answer is 2027 — management's words "very big product big year": D series brand new models, C series existing brand new and also replacement, B series new products. 2026 profit, largely is for 2027 product matrix storing water.
04 FAW and Stellantis: Two "Technology for Market" AccountsAugust 24, same day financial report release, Leapmotor and China FAW signed deepening cooperation framework, listed ten major synergy fields: Battery, Electric Drive, Chassis, Intelligent Cockpit, Intelligent Driving, Auto Electronics, Whole Vehicle Design Manufacturing, Export, Supply Chain, and Embodied AI Robot. Time line extended look, March 3, 2025 both parties signed strategic cooperation MOU, December 28, 2025 FAW subscribed about 5% domestic shares with 3.744 billion yuan (per share 50.03 yuan) — this investment's book floating loss, according to Chegulu Media calculation already exceeded 1 billion yuan (Aug 19); and concurrently, founder Zhu Jiangming was reported multiple announcements increase holdings.

Leapmotor and China FAW signed deepening strategic cooperation agreement | Source: Leapmotor official website
A state-owned giant floating loss, founder investing against trend, both parties again on financial report day announced ten major synergy — this set of signals put together, reads like a "Long-termist mutual confirmation" agreement. Leapmotor wants one FAW R&D synergy and policy resources, FAW wants Leapmotor full domain self-developed powertrain ready-made capability, use money and technology double binding.
Another line is Stellantis. 2023 shareholding, May 2024 established Leapmotor International, May 2026 both parties announced cooperation upgrade (Opel etc brand dedicated production line and technical support, according to public reports). Conference call management revealed, cooperation direction with Stellantis is "Empowerment based on mature powertrain component supply capability", and "Recent very likely there will be further good news"; With FAW, Stellantis R&D service cooperation, "Very soon everyone will receive external announcement".
This words actually already fulfilled half: FAW framework agreement is announcement day hammered. Leapmotor is upgrading "Selling cars" into "Selling cars + Selling technology + Selling supply chain capability" three parts income. This is also Zhu Jiangming repeatedly publicly expressing "Market cap undervalued" confidence source — market gives Leapmotor valuation according to whole vehicle manufacturer, but its financial statements are growing into technology exporter shape.
05 Robots: Second Curve Waiting Behind AnnouncementAnd FAW's ten synergy list appeared "Embodied AI Robot", this is official level first time writing robot into cooperation framework. Accompanying public business information (Leapmotor power subsidiary business scope newly added robot related content), and conference call management "Company has robot related planning, very soon will formal announcement" statement, Leapmotor's robot business has entered "Night before official announcement" from "Rumors".
But to speak rigorous: Robot currently still is expectation, not profit. Before announcement landing, it is just valuation imagination option. Management at conference call also confirmed, September 16 will hold technology launch conference in Huzhou, Zhejiang, heavyweight content concentrated on Intelligent Driving, Battery and Electric Drive — this is future few weeks most immediately visible catalyst, Robot is farther that "Easter egg".
Risks also need to be mentionedOutside bullish, a few risks worth listing on table.
First is carbon credit decline. First half 80~900 million points income pushed net profit to 200 million, but unit price is returning towards "Country back then path". If next year points income shrinks, and whole vehicle gross margin not substantially stand at 13%~14%, profit statement will be hit back to original form. Leapmotor needs to use real material scale effect, to fill points decline dug hole.
Second is customer concentration. Financial report disclosed single largest customer contribution accounted for about 23.3% revenue ratio — combine European revenue scale and joint relationship, overseas big customers are double-edged sword: It supports growth, also handed over fate's much part into others hands.
Third is policy window. EU localization procurement proportion requirement is rising, anti-subsidy tax and price commitment "Soft landing" whether continue, directly decides 2027 400,000 units overseas target whether can fulfill; and localization profit margin improvement, management also said "Needs policy changes".
Fourth is execution difficulty. Next year overseas 350,000~400,000 units, means need to on this year about 200,000 units basis close to double, capacity, channel, localization capacity three lines parallel, any link fail chain will transmit to report.
Conclusion: Monthly Sales of 100,000 is Just an Entry Ticket
Leapmotor full series of models lineup | Source: Leapmotor official website
In Tech Jungle's view, market cap repair not rely on shouting, market wants three verifiable evidence: Whole vehicle gross margin whether can stabilize 13%~14% and continue upward, prove "Selling cars itself can make money"; Carbon credits decline after profit not empty, prove "Profit is real"; Overseas 350,000~400,000 units and robot announcement quality, prove "Second curve is not an empty promise".
This half year, Leapmotor proved itself can use extremely low per-unit profit roll up scale, also can hold cash firmly in hand — Net cash over 36 billion, Accounts payable leverage 470 billion supply chain account period, this is not every New EV maker can do. But capital market not pay for "Amazing", only pay for "Proven sustainability".
Monthly sales of 100,000 is just an entry ticket, net profit of 200 million is a passing score, and dozens of times market cap gap, need to rely on next one or two years' report page by page to fill.
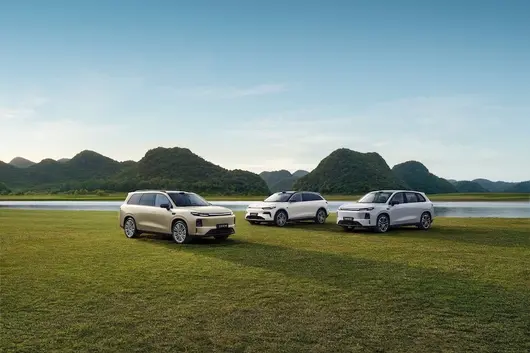
In the Malaysian SUV market, many buyers compare the Honda WR-V and Kia Sportage when choosing a car. Both cars are quite close in price and positioning. Today, we will make a detailed comparison from multiple aspects to help you save time on research.
The OTR price of Honda WR-V in Malaysia is RM 89,900 - 107,900, with a total of 4 variants, including 2023 1.5L V (RM 99,900), 2023 1.5L E (RM 95,900), 2023 1.5L S (RM 89,900), etc.
The OTR price of Kia Sportage in Malaysia is RM 129,639 - 179,320, with a total of 4 variants, including 2025 1.6T DCT 4WD High (RM 179,320), 2025 1.6T DCT 2WD High (RM 159,320), 2025 2.0L AT 2WD High (RM 139,639), etc.
Looking at the price, the Honda WR-V entry price is indeed RM 39,739 cheaper than the Kia Sportage. If your budget is limited, Honda's entry-level model can already meet daily needs. However, note that the few thousand dollars saved might involve trade-offs in features, depending on your specific needs.

Honda WR-V is equipped with a 1.5L 4-cyl, 105 hp. Official fuel consumption 6.0 L/100km.
Kia Sportage is equipped with a 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
In terms of power, Kia Sportage's 1.5L Turbo has 35 more horsepower than Honda WR-V's 1.5L 4-cyl. However, for daily city driving, both cars have sufficient power and won't feel underpowered.

Honda WR-V safety rating is 5★ (ASEAN NCAP), active safety system includes Honda SENSING.
Kia Sportage safety rating is 5★ (ASEAN NCAP), active safety system includes Drive Wise.
Both cars have the same safety rating, and safety features are quite comprehensive for this class. Safety of new cars nowadays is not poor, no need to worry too much about this.

Honda WR-V adopts FWD drive mode.
Kia Sportage adopts FWD drive mode.
Both cars use the same drive mode, both are FWD, there will not be a big difference in daily driving experience.

Both Honda WR-V and Kia Sportage are mainstream choices in the Malaysian market, suitable for family use and daily commuting. If you value brand reputation and resale value more, you can prioritize the one with better reputation; if you care more about cost-performance ratio and features, then choose the one with richer configuration. Ultimately, it is recommended to test drive both, and experiencing it personally is the most important.

Overall, Honda WR-V and Kia Sportage are both excellent models in the Malaysian market. Which one to choose depends mainly on your personal needs and budget. It is recommended to do your research, compare quotes from several dealerships, and then go for a test drive to make the final decision. Buying a car is a major event, spending time on research will never be wrong.

In the Malaysian SUV market, many buyers compare the Honda WR-V and Mazda CX-5 when choosing a car. These two cars are quite close in price and positioning. Today, we will do a detailed comparison from multiple aspects to help you save time on research.
The OTR price of the Honda WR-V in Malaysia is RM 89,900 - 107,900, with a total of 4 versions, including 2023 1.5L V (RM 99,900), 2023 1.5L E (RM 95,900), 2023 1.5L S (RM 89,900), etc.
The OTR price of the Mazda CX-5 in Malaysia is RM 135,469 - 166,760, with a total of 3 versions, including 2025 2.0L AT 35th Anniversary (RM 316,154), 2025 2.0L AT (RM 296,154), 2025 2.0L MT (RM 294,154), etc.
Looking at the price, the starting price of the Honda WR-V is indeed RM 45,569 cheaper than the Mazda CX-5. If your budget is limited, Honda's entry-level version can already meet daily needs. But note that the few thousand difference might involve trade-offs in features, depending on your needs.
Honda WR-V is equipped with 1.5L 4-cyl, 105 hp. Official fuel consumption 6.0 L/100km.
Mazda CX-5 is equipped with 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
In terms of power, the Mazda CX-5's 1.5L Turbo has 35 more horsepower than the Honda WR-V's 1.5L 4-cyl. However, for daily city driving, both cars have enough power, you won't feel underpowered.
Honda WR-V warranty 5 years/unlimited mileage, maintenance interval every 10,000km or 6 months.
Mazda CX-5 warranty 5 years/150,000km, maintenance interval every 10,000km or 6 months.
Both the Honda WR-V and Mazda CX-5 are mainstream choices in the Malaysian market, suitable for family use and daily commuting. If you value brand reputation and resale value more, consider the one with better reputation first; if you care more about cost-performance and features, choose the one with richer configuration. Ultimately, it is recommended to test drive both, as personal experience is most important.

Overall, the Honda WR-V and Mazda CX-5 are both very good models in the Malaysian market. Which one to choose mainly depends on your personal needs and budget. We suggest doing your research, compare quotes from several dealerships, and then test drive to make a final decision. Buying a car is a big matter, taking time to research will never be wrong.
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿 寶騰 X90 同 福斯途銳 嚟作比較。呢兩款車喺價錢同定位上都幾接近,今日我哋就從多個方面作詳細比較,幫你省返做功課嘅時間。
寶騰 X90 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,800,一共有 4 個版本,包括 2026 1.5T Prime X(RM 122,800)、2026 1.5T Prime(RM 116,800)、2026 1.5T Lite(RM 106,800) 等。
福斯途銳 喺馬來西亞嘅 OTR 售價係 RM 206,540 - 260,024,一共有 2 個版本,包括 2025 Allspace 2.0T R-Line(RM 260,024)、2025 Allspace 1.4T Elegance(RM 206,540) 等。
由價錢嚟睇,寶騰 X90 嘅起步價確實比 福斯途銳 平咗 RM 99,740。如果你預算有限,寶騰嘅入門版已經可以滿足日常需求。但都要注意,平嗰幾千蚊,可能喺配備上會有取捨,具體要看你嘅需求。

寶騰 X90 搭載 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
福斯途銳 搭載 2.0L 4-cyl,馬力 170 hp。官方油耗 8.0 L/100km。
動力方面,福斯途銳嘅 2.0L 4-cyl 比 寶騰 X90 嘅 1.5L Turbo 多咗 30 匹馬力。不過日常喺市區開,兩款車嘅動力都夠用,唔會覺得唔夠力。
寶騰 X90 車身長 4400 mm,備用箱 400 L。
福斯途銳 車身長 4400 mm,備用箱 400 L。
兩款車嘅尺寸幾近相同,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。
寶騰 X90 採用 FWD 驅動方式。
福斯途銳 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。

寶騰 X90 同 福斯途銳 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就揀配置更豐富嗰款。最尾都係建議兩款都去試駕,親身體驗先係最重要嘅。

總體嚟講,寶騰 X90 同 福斯途銳 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵都係要看你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花點時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿 Proton X90 同 Hyundai Tucson 嚟做比較。這兩款車喺價位同定位上都幾接近,今日我哋就從多個方面做一次詳細嘅比較,幫你省返做功課嘅時間。
Proton X90 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,800,一共有 4 個版本,包括 2026 1.5T Prime X(RM 122,800)、2026 1.5T Prime(RM 116,800)、2026 1.5T Lite(RM 106,800) 等。
Hyundai Tucson 喺馬來西亞嘅 OTR 售價係 RM 143,888 - 197,888,一共有 5 個版本,包括 2025 HEV 1.6T AT 2WD Prestige(RM 197,888)、2025 1.6T DCT 4WD Prestige(RM 186,888)、2025 1.6T DCT 2WD Prime(RM 164,888) 等。
從價錢嚟睇,Proton X90 嘅起步價確實比 Hyundai Tucson 平咗 RM 37,088。如果你預算有限,Proton 嘅入門版已經可以滿足日常需求。但都要留意,平嗰幾千蚊,可能喺配備上會有取捨,具體要看你嘅需求。
Proton X90 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA)。
Hyundai Tucson 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 SmartSense。
兩款車嘅安全評級一樣,喺呢個級別入面安全配備都算好齊全嘅。而家嘅新車安全性都唔錯,唔使太擔心這一點。
Proton X90 保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
Hyundai Tucson 保修 5 年/300,000km,保養間隔 每 10,000km 或 6 個月。
Proton X90 同 Hyundai Tucson 都係馬來西亞市場嘅主流選擇,適合家庭用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,就選配置更豐富嗰款。最後都建議兩款都去試駕,親身體驗先係最重要。
總括嚟講,Proton X90 同 Hyundai Tucson 都係馬來西亞市場幾好嘅車型。揀邊一輛,關鍵仲係要看你個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去做試駕先做最終決定。買車係件大事,花少少時間做功課絕對無錯。
In Malaysia's SUV market, many buyers compare the Proton X90 and MG MG HS when choosing a car. These two models are quite close in price and positioning. Today, we will make a detailed comparison from multiple aspects to help you save time on research.
The OTR price of Proton X90 in Malaysia is RM 106,800 - 122,800, with a total of 4 versions, including 2026 1.5T Prime X (RM 122,800), 2026 1.5T Prime (RM 116,800), 2026 1.5T Lite (RM 106,800), etc.
The OTR price of MG MG HS in Malaysia is RM 130,450 - 146,450, with a total of 2 versions, including 1.5L Standard (RM 105,000), 1.5L Executive (RM 115,000), etc.
From a price perspective, the entry price of Proton X90 is indeed RM 23,650 cheaper than MG MG HS. If your budget is limited, Proton's entry-level version can already meet daily needs. But also note, the savings of a few thousand might involve trade-offs in features, depending on your specific needs.
Proton X90 is equipped with a 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
MG MG HS is equipped with a 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
Both cars use the same powertrain system, and the driving experience feels basically the same. Fuel consumption is also similar, no need to worry too much about this point.
Proton X90 body length 4400 mm, trunk 400 L.
MG MG HS body length 4400 mm, trunk 400 L.
The dimensions of both cars are almost identical, and the interior space differs little. For cars in this class, it is fully sufficient for daily use.
Proton X90 adopts FWD drive mode.
MG MG HS adopts FWD drive mode.
The drive mode of both cars is the same, both FWD, daily driving experience will not have much difference.
Proton X90 and MG MG HS are both mainstream choices in the Malaysian market, suitable for family use and daily commuting. If you value brand reputation and resale value more, you can prioritize the one with better reputation; if you care more about cost-performance ratio and features, choose the one with richer configurations. Finally, it is recommended to test drive both models, as personal experience is the most important.
Overall, Proton X90 and MG MG HS are both very good models in the Malaysian market. Which one to choose depends mainly on your personal needs and budget. We suggest doing your research, comparing quotes from several dealerships, and then test driving to make the final decision. Buying a car is a big matter, spending time on research will definitely not be wrong.


