


首頁Sales

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
[CNMO Tech News] On July 7, Bitauto Ranking released the first half of 2026 and June Thailand Auto Market Brand Sales Top 10. According to data organized by Bitauto based on official Thailand institutions/associations:

BYD
The top 3 brand sales in the first half are: Toyota, Honda, BYD, sales are respectively: 102,006 vehicles, 41,837 vehicles, 25,890 vehicles;
The top 3 brand sales in June are: Toyota, Honda, BYD, sales are respectively: 16,599 vehicles, 6,233 vehicles, 4,824 vehicles.


In the first half brand sales list, Toyota leads the Thailand market with absolute advantage, first half cumulative sales 102,006 vehicles, year-over-year rise 11.3%, it is the only brand in the list with sales breaking 100,000 units. The second on the list is Honda, sales 41,837 vehicles, year-over-year small growth 1.8%.
CNMO Tech notes that BYD, Chery, MG, AION, and Great Wall made it into the top 10 list: BYD ranks third on the list, the number one Chinese brand, first half sold 25,890 vehicles, year-over-year slight increase 0.9%; Chery presents phenomenal growth, ranks fifth, sales 20,163 vehicles, year-over-year surge 1066.8%, growth rate leads the list with a huge gap, becoming a growth dark horse in Thailand's first half market; MG ranks sixth, sales 16,263 vehicles, year-over-year growth 71.5%; AION ranks eighth, sales 10,393 vehicles, year-over-year growth 83.0%; Great Wall ranks tenth, sales 8,703 vehicles, year-over-year growth 62.5%.
Additionally, Isuzu is one of the few brands in the list with year-over-year decline, sales 22,862 vehicles, year-over-year slight drop 0.4%; Ford's drop is more obvious, sales 8,830 vehicles, year-over-year decline 14.3%.
Once the China Passenger Car Association released the pure electric retail ranking for the first half of 2026, the industry finally saw the true temperature of the market. The top ten seats underwent a complete shake-up, with long-standing top models collectively diving. Seagull, Qin PLUS, and other former top hits fell out of the head lineup, replaced by all-new products concentrated on the market in the past year. Many people say the pure electric market is not doing well, but looking closely at the data reveals that what is not doing well are old products, low price points, and stock models without technology. Truly new products that hit users' core needs are still surging against the trend.

No.1 Geely Star Wish
Geely Star Wish, which took the pure electric sales crown for the first half of the year, has mixed feelings. The result of 194,000 units looks impressive, but actually decreased slightly by 5.3% year-on-year. Against the background of the overall contraction of the entry-level pure electric market, holding onto this volume is already considered a win. This 60,000-level A0-class small car has ranked at the top for 16 consecutive months, the core being that it solves the pain points of commuter cars to the extreme. Rear-drive architecture, independent suspension, CATL cells, and fast-charge configurations are fully loaded on all models. Using superior specifications, it beats competitors at the same price point. Cumulative sales exceeded 800,000 units in less than two years.
Conversely, the 50,000 to 100,000 market is continuing to shrink. Leapmotor and other competitors have entered with lower prices and higher configurations. Plus, car profits are thin as razor blades. Star Wish's domestic market share has basically hit the ceiling. The next incremental growth can only be supported by overseas markets.

No.2 Tesla Model Y
Tesla Model Y, ranked second, sold 172,500 units in the first half of the year, with a slight increase of 0.6% year-on-year. It barely held onto its basic market position amid the blockade of domestic models. As the industry benchmark for the 250,000 to 300,000 pure electric SUV market, Model Y's core competitiveness has never been interior configurations, but mature powertrain systems, a supercharging network spread across the country, and Tesla's brand premium. Many family users choose it for peace of mind and value retention.
However, with new products from Li Auto, Xiaomi, and AITO taking turns siphoning users, Model Y's growth has long entered stagnation. The latest news is that the high-performance version of this car has completed MIIT declaration. It will likely maintain sales with facelifts and price adjustments in the second half of the year, but it is highly probable that its overall market share will continue to be eroded.

No.3 Li Auto i6
Li Auto i6 reached third place with 120,400 units, the brightest dark horse in the first half of the year, and marked that Li Auto's pure electric transformation is fully completed.
This 250,000-level family pure electric SUV completely continues Li Auto's product logic oriented towards family users. It does not compete on paper data like 0-100 km/h acceleration, but makes 800V high-voltage platforms, dual-chamber air suspension, and advanced intelligent driving standard configurations. It maximizes space, comfort, and energy replenishment efficiency, precisely hitting the pain points of urban family users.
Since its launch, this car has had monthly sales exceeding 20,000 for four consecutive months, directly accounting for 62% of Li Auto's total sales, siphoning its own extended-range L series. However, the 200,000 to 300,000 pure electric SUV market is the most competitive track this year. New products are flocking to the market in the second half of the year. It is not easy for the i6 to maintain current sales levels. Later, it will depend on new products like the i8 to take over.

No.4 Xiaomi YU7
Xiaomi YU7, as a popular model, sold 104,600 units in the first half of the year, ranked fourth. As a brand-new car launched only half a year ago, this result has exceeded industry expectations. This mid-size SUV focusing on sports and family, relying on Xiaomi's ecosystem traffic, reached a peak of nearly 38,000 units in the first month after launch, directly breaking the market pattern at the same price level.
However, the subsequent trend can be described as opening high and closing low. After the heat subsided, sales declined month by month until June, relying on the launch of the standard version and employee internal purchase discounts to return to the ten-thousand club. Ultimately, the 200,000-level pure electric SUV track is too competitive. Tesla Model Y is above, and cost-effective brands like Leapmotor are below. YU7's product strength has not pulled an absolute gap. Next, Xiaomi's focus will shift to its extended-range series. YU7 will likely maintain steady sales, making it difficult to replicate the explosion in the early stages after launch.

No.5 BYD Yuan UP
BYD Yuan UP sold 82,700 units in pure retail sales in the first half of the year, increasing by 14.7% year-on-year, making it BYD's new backbone in the entry-level pure electric market. It gained volume because it took over from Yuan PLUS. The old Yuan PLUS saw a cliff-like drop in sales. Yuan UP used lower pricing, newer designs, and BYD's mature powertrain system to quickly fill the market gap for pure electric SUVs under 100,000.
Plus, BYD's service network spread across the country and the reputation of Blade Batteries have extremely strong attraction for mass market users. However, there is bad news: Leapmotor A10 has overtaken Yuan UP in retail volume for two consecutive months. It is advancing step by step with a cost-effective strategy of larger space and higher configurations. In the second half of the year, it will be quite difficult for Yuan UP to continue climbing. It will likely hold its current market share and maintain stable output through capacity ramp-up.

No.6 Xiaomi SU7
Xiaomi SU7 sold 80,500 units in the first half of the year, dropping 48.3% year-on-year, with the ranking falling to sixth. The main reason is that the replacement gap dragged it down. At the beginning of the year, the old SU7 was discontinued to pave the way for the new model. Two months of delivery vacuum directly lowered the total for the first half of the year. After the new generation model was launched in March, it quickly returned to a monthly sales level of 20,000+, remaining the benchmark for 200,000-level pure electric sedans.
As Xiaomi's founding work, SU7 thoroughly opened up the capacity of the niche sports car market, even siphoning users from BMW 3 Series and Tesla Model 3. However, the sports car market itself has a low ceiling. Plus, with more and more competitors, SU7's sales have basically hit the upper limit. Next, it will be more about stabilizing output as the brand's basic market. The stage of explosive growth has passed.

No.7 NIO ES8
NIO ES8 accumulated 78,600 units in retail sales for the first half of the year, ranking seventh, being the absolute sales king in the high-end market above 400,000. The fully new ES8 can fight, the core is hitting the pure electric replacement demand of high-end family users. The swapping system solves energy replenishment anxiety. Luxury and service experience crush same-price BBA fuel cars. Users accounting for more than 97% are exchange/purchase users, of which 60% come from BBA owners.
Less than a year after launch, the new ES8 cumulative delivery broke 120,000 units, ranking the large SUV sales champion for six consecutive months, hard撑着 (proping up) the market capacity of the high-end pure electric market. Next, its own lower-positioned ES9 has already siphoned many users after launch. The 6-seater version has just started reservations. Plus, the high-end market itself has limited capacity. ES8's main goal for the second half of the year is to hold onto the basic market of the high-end market.

No.8 Wuling Hongguang MINI
Once the national god car Hongguang MINI EV sold only 72,800 units in the first half of the year, dropping 57.4% year-on-year, falling directly from the top spot to eighth. It is known as the most tragic fall among old models.
The loss of speed of Hongguang MINI is not caused by a single reason. On one hand, the A00-class microcar market is contracting overall. Adjustment of purchase tax policy has significantly shrunk the cost-performance advantage of low-price cars. On the other hand, user consumption upgrades are obvious. Adding 20,000 can buy a small car with larger space, higher configuration, and longer range. Many users who watched MINI EV finally bought Bingo, Star Wish. Wuling itself is clear about the problem. The fifth-generation model changed to a four-door structure, added fast charging and safety configurations, but it still could not stop the downward trend.

No.9 Changan Qiyuan Q05
Changan Qiyuan Q05 sold 71,600 units in the first half of the year, breaking into ninth, a true comeback dark horse.
This car had little presence last year. After price reduction and configuration increase in April this year, it took off directly. It pulled the entry-level range to 506km, even downgraded laser radar to the 80,000 level. Using a "technology equity" strategy, it precisely hit the pain points of home users. It sat firmly as the pure electric compact SUV sales champion for three consecutive months. Changan's capacity also kept up with the rhythm. After the Nanchang factory was put into production, bottlenecks were gradually relieved. The overseas market also bloomed synchronously. Thailand launched in half a month, and orders broke 3,000. After capacity is fully released in the second half of the year, Qiyuan Q05 sales still have rising space. It is expected to冲击 (attack/strive for) the first echelon of entry-level pure electric.

No.10 MG4
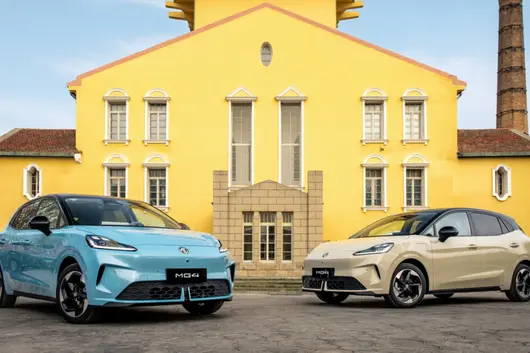
Ranked tenth, MG4 sold 70,800 units in pure retail sales in the first half of the year, purely relying on overseas market endorsement. This 100,000-level pure electric hatchback has been selling well in Europe for several years. It has ranked as the China-brand European sales champion for 11 consecutive years. Overseas sales share far exceeds domestic.
In the domestic market, MG4 began to gain volume gradually after its refresh last year. Rear-drive architecture and five-link independent suspension chassis quality are unique at the same price level. The MG4X version launched this year even downgraded semi-solid-state batteries. The technology普惠 (universal benefit) strategy was very effective. Domestic monthly sales have exceeded 10,000 for 9 consecutive months. However, hatchbacks themselves are a niche market in China. MG's brand voice is far less than mainstream autonomous brands. There will be no big breakthroughs domestically. Next, its incremental growth will still come from overseas. Maintaining steady state domestically is sufficient. It is a model that relies on the global market to amortize costs.

Summary
After reading the top ten ranking, you can see that the pure electric market has long passed the barbaric growth period where any car can be sold by just building it. The logic now is very clear. The low-end market is continuously shrinking. Consumption upgrading is the big trend. Old products that do not iterate quickly will be eliminated quickly. New products that truly hit user needs, have proper configurations, and reasonable prices can still break through against the trend even in an environment where the overall market is declining. Competition in the second half of the year will only be more intense. More new products will be concentrated on the market. The price war will continue. Looking at the ranking by the end of the year, the rankings may have to change one more time.
Recently, Geely Holding Group announced its performance for the first half of 2026, once again becoming the focus of industry attention.

Data shows that Geely Holding Group's total sales volume in the first half of 2026 reached 1,934,842 units, setting a new historical record. Among them, new energy vehicle sales reached 1,100,893 units, a year-on-year increase of 10%, with new energy penetration rate further rising to 56.9%. In the first half, Geely Automobile Holdings Limited (0175.HK) sold 1,422,958 units, setting a new high for the same period; new energy vehicle sales (including Geely, Lynk & Co, Zeekr) were 799,454 units, a year-on-year increase of 10%, with a new energy penetration rate of 56%.
According to CPCA data, Geely Automobile's domestic terminal retail sales volume in the first half of the year was 1.021 million units, ranking first in China's passenger car domestic sales for the first half of 2026, and also the only domestic brand to exceed sales of one million units.
However, to truly understand Geely's "new historical record" this time, one cannot only look at the total volume of 1.93 million units, nor stay only at the domestic first place of 1.021 million units. What is more worth asking is: Against the backdrop of slowing industry growth, divergent user demands, and intensifying global competition, what exactly does Geely rely on to beat the market?
It can be said that Geely's performance in the first half of the year was not just a refresh of sales records, but a concentrated realization of its long-term system capabilities once again.
In Geely's first-half performance report, several "Firsts" stood out especially.
Among them, Geely China Star sales reached 581,000 units, firmly holding the first place in domestic brand fuel vehicle sales; Zeekr delivered 178,000 units, a year-on-year increase of 97%, with delivery growth rate ranking first in the luxury new energy market. At the same time, Geely Xingyuan monthly sales broke through 50,000 units, cumulative sales exceeded 750,000 units since listing, continuously reigning as the sales champion across all brands and categories, becoming a genuine national hit.

These "Firsts" seem to come from different tracks, but together reveal an important characteristic of Geely's growth: running fast, and walking steadily. Among them, China Star stabilizes the fuel vehicle base, continuing to maintain leadership in the stock market; Zeekr accelerates upward breakthrough, and Xingyuan continues to scale up in the mainstream new energy market.
Fuel and new energy, mainstream and high-end, scale and value, different sectors are not simply a zero-sum game, but gradually forming a mutually supportive growth structure. This balance is precisely the most worthy part of attention in Geely's first-half performance.
Supporting this balanced growth, on one hand is a multi-brand lineup with clear positioning and wide coverage; on the other hand, it is the continuous deepening of the "One Geely" strategic integration.
Not long ago, Geely Holding Group Chairman Li Shufu publicly stated that they will orderly close, cancel, and merge relevant redundant entities of Geely Automobile Group Co., Ltd., focusing advantageous resources to strengthen the core listed platform of Geely Automobile Holdings Limited. This more precise resource allocation for different market cycles and user needs is also further improving the operating efficiency and anti-cycle ability of the entire group.
From this perspective, what Geely truly deserves attention to is not just how many "Firsts" were captured, but behind these "Firsts", a growth system balancing scale, structure, and efficiency is forming. This ability to hold the base while continuously opening up new volume is the key for Geely to traverse industry cycles and maintain long-term leadership.
Another important growth lever for Geely comes from the overseas market.
From the performance in the first half of the year, Geely's overseas business is entering an accelerated realization period. Its overseas sales reached 474,228 units, a year-on-year increase of 158%, exceeding the total export sales of 2025. More worth noting is that its overseas growth is not mainly relying on traditional fuel vehicles for volume, but simultaneously upgrading towards new energy and high-end. Its new energy product export sales in the first half were 277,000 units, a surge of 585% year-on-year, with new energy proportion reaching 58%. This means Geely's overseas business growth logic is gradually shifting to relying on new energy technology, product experience, and brand value to open up incremental space.

Among them, Geely Galaxy new energy products entered the top sales ranks in multiple overseas markets; Zeekr won championships in niche markets of countries such as Thailand, Malaysia, Mexico.
This global synergy is also reflected in the performance of other brands under Geely Holding Group. Among them, Volvo Cars sold 325,000 units in the first half, of which new energy sales were 161,000 units, a year-on-year increase of 3.8%, with new energy penetration rate 50%. Pure electric model deliveries grew for 9 consecutive months, and new energy transformation continued to breakthrough.
In addition, Polestar Cars sold 30,400 units in the first half, setting a new historical record, achieving sales breakthroughs in major markets such as the UK, Germany, and South Korea. Proton Cars sold 100,300 units in the first half, a year-on-year increase of 39.1%, creating the best sales performance since 2011. It is worth mentioning that the Proton e.MAS 7 PHEV launched in February of this year continued to sell well, leading the Malaysian plug-in hybrid niche market.

Of course, a new historical record is only an interim result. Another issue worth noting is, with Geely having already stood on a new step, what cards does it have in hand for the second half of the year?
From the currently released information, Geely's new product and technology offensive in the second half of the year remains dense. First is Geely Galaxy TT. As a mid-to-large pure electric sedan, its body length reaches 4999mm, wheelbase is 2920mm, and it will match the Qianli Haohan H7 assisted driving solution. From the product positioning perspective, Galaxy TT targets young consumers' needs for sports design, smart experience, and personality expression, and also means Geely Galaxy will further extend to the higher value pure electric sedan market.

While products break through upwards, Geely's technical base is also continuing to upgrade. On July 16, Geely Galaxy's global first "Thunder 16-in-1 Intelligent Electric Drive" is about to be launched, native adapted to 800V high voltage platform, and 16 categories of functional modules including motors, silicon carbide electronic control, whole vehicle thermal management, etc. are highly integrated. The "16-in-1" will also be systemically integrated to further optimize whole vehicle space, weight, energy consumption and cost, continuously enhancing Geely Galaxy's competitive barrier.
Additionally, the imminent arrival of Galaxy Warship 700 also means that Geely will officially enter the new track of plug-in hybrid hard-core SUVs, which combines growth potential and profit margins.
For an enterprise that has already stood at the forefront of the Chinese automobile market, "selling more" is only the first stage; how to improve efficiency while expanding scale, how to maintain business quality during new energy transformation, and how to replicate domestic competitiveness to the global market are the questions that must be answered to become a world-class automobile group. And Geely is steadily walking on this path of advanced development.
Editor's Note: Geely Group's performance in the first half of the year can be called bright, but in the automotive market where variables are ever-present, its challenges for the second half of the year remain.
On July 15th, Geely Holding Group released the mid-year sales performance report: Total vehicle sales for the group from January to June reached 1.93 million units, setting a new high for the same period in history; among them, new energy vehicle sales reached 1.1 million units, a year-on-year increase of 10%, with the new energy penetration rate climbing to 56.9%. This means that for every 100 cars sold by Geely Holding Group in the first half of the year, nearly 57 were new energy vehicles, and the group as a whole has entered the harvest period of electrification scale.

As the core listed entity under Geely Holdings, Geely Auto's sales reached 1.43 million units in the first half of the year, with new energy sales (including Geely, Lynk & Co, Zeekr) at 799,000 units, a year-on-year increase of 10%, and a new energy penetration rate of 56%. Sales data from the group to the core brand outline a traditional Chinese automaker that started with fuel vehicles, and in the background of intensifying industry stock competition, how to complete a structural transformation through a multi-brand matrix and global layout.
Multi-brand matrix synergy, new energy becomes the main axis of growth
Geely's ability to refresh records in the first half of the year was not pulled by a single brand, but the result of synergy between the three major brands Geely, Lynk & Co, and Zeekr in different sub-segments.
The Geely brand, which targets the mainstream home market, achieved cumulative sales of 1,100,373 units in the first half, of which the China Star series sold 580,580 units, continuing to firmly rank among the top sales of domestic brand fuel vehicles, playing the role of a "ballast" for the basic market. What truly drives the volume increase in new energy is Geely Galaxy—cumulative deliveries in the first half reached 519,793 units, with single-month sales in June at 108,206 units, a year-on-year increase of 20% and a month-on-month increase of 32%. The Star Wish under the Galaxy brand broke 50,000 units in a single month, with cumulative sales since launch exceeding 750,000 units, becoming the core product in Geely's new energy volume-selling camp.

Lynk & Co, positioned in the mid-to-high-end hybrid market, achieved cumulative sales of 144,215 units in the first half, with new energy vehicle sales at 93,597 units, and the proportion of new energy products reaching 65%, stabilizing the mid-to-high-end hybrid sub-market by relying on the EM-P hybrid family promoted by the simultaneous launch of three car models. Zeekr continued its strong performance on the high-end luxury track, delivering 178,370 units in the first half, a significant year-on-year increase of 97%; single-month deliveries in June were 35,169 units, a year-on-year increase of 111%, achieving consecutive five-month year-on-year and month-on-month double growth, with global cumulative deliveries officially breaking through 820,000 units.
From the perspective of the group as a whole, June single-month Geely Auto new energy sales reached 161,449 units, a year-on-year increase of 32% and a month-on-month increase of 21%, with new energy sales proportion of the group's total sales exceeding 67%—equivalent to nearly 7 out of every 10 Geely new cars sold being new energy vehicles. This structural change marks that Geely's "oil and electricity simultaneous promotion" transformation rhythm has entered a new stage dominated by new energy.
It is worth noting that Geely's new energy transformation is not at the expense of abandoning fuel vehicles. The China Star series still maintains strong competitiveness in the fuel vehicle market, and this "fuel ballast, new energy volume" dual-track strategy enabled Geely to hold its basic market share in the domestic auto market in the first half. Data from the China Passenger Car Association shows that in the ranking of narrow passenger vehicle manufacturer retail sales from January to June, Geely ranked first with 1.021 million units and an 11.7% share, being the only domestic brand to break the million-unit mark in the first half.
Overseas business leaps, globalization enters harvest period
If new energy penetration rate is the most eye-catching internal change in Geely's first half, then the explosion of export business is its most prominent external highlight.
Data shows that Geely Auto's first-half overseas export sales reached 474,228 units, a year-on-year increase of 158%—this number has already exceeded Geely's total export volume for the full year of 2025. June single-month overseas export sales broke the 100,000 unit threshold for the first time, reaching 102,874 units, with a year-on-year increase of 157% and a month-on-month increase of 21%, achieving consecutive six-month year-on-year and month-on-month double growth.
A more critical change lies in the export structure. In the first half, Geely's new energy product export sales were 277,189 units, surging 585% year-on-year, accounting for 58% of the total export volume. This means Geely's main overseas products have completed the switch from traditional fuel vehicles to new energy vehicles, with new energy products gradually becoming the core driving force for overseas market growth.
Geely Holding Group's overall global layout also landed at multiple points in the first half: Geely signed Swiss dealers to strengthen the European market, Lynk & Co 900 launched in Vietnam and Qatar, Geely Xingyuan EX2 began local production in Brazil, Binyue Cool launched in South Africa; Zeekr topped the Malaysia luxury pure electric sales list, 007 GT has launched in 16 European countries, flagship model Zeekr 9X plans to go to the Middle East in Q3, and will subsequently expand into US/Europe and Central Asian markets.
Overseas high-end brands also performed steadily. Volvo Cars first-half global sales were 325,000 units, with new energy sales at 161,000 units, a year-on-year increase of 3.8%, with new energy penetration rate reaching 50%, and pure electric vehicle deliveries growing for 9 consecutive months. Polestar first-half sales were 30,400 units, achieving sales breakthroughs in markets such as the UK, Germany, and South Korea, setting a new high for the brand at the same period in history. In the Southeast Asia and commercial vehicle sector, Proton first-half sales were 100,300 units, a year-on-year increase of 39.1%, achieving the best half-year performance since 2011; Farizon New Energy Commercial Vehicles first-half sales were 88,000 units, a year-on-year increase of 41.3%, with overseas export sales ranking at the forefront of the new energy commercial vehicle industry.
Geely Group's performance in the first half of the year can be called bright, but in the automotive market where variables are ever-present, its challenges for the second half of the year remain. Intensifying domestic car market stock competition and unrelenting price war pressure, Geely brand and Lynk & Co brand first-half cumulative sales declined year-on-year by 5% and 6% respectively, indicating that the fuel vehicle basic market still faces contraction pressure; and in the overseas market, geopolitical tensions, trade barriers, and the difficulty of localization operations will also rise synchronously with the expansion of export scale. Whether Geely can continue its growth momentum in the second half depends on the volume pace of Galaxy and Zeekr, the development progress of Middle East and European markets, and the balancing ability of resource allocation between fuel vehicles and new energy.
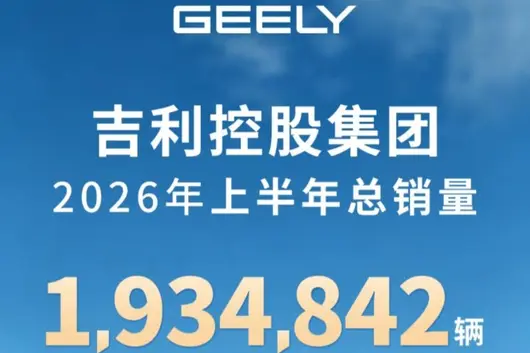
Geely Holding Group total sales reached 1,934,842 units in the first half of 2026, setting a new all-time record. New energy vehicle sales amounted to 1,100,893 units, up 10% year-on-year, with a penetration rate reaching 56.9%. In the first half, Geely Holding Group maintained a high-quality growth trend, accelerated internationalization and new energy transformation comprehensively, demonstrated development resilience across cycles, and outperformed the industry through steady operations.
In the first half, Geely Automobile Holdings Limited (0175.HK) sold 1,422,958 units, reaching a new high for the same period; New energy vehicle sales (including Geely, Lynk & Co, Zeekr) totaled 799,454 units, up 10% year-on-year, with a new energy penetration rate of 56%. Among them, Geely China Star sales reached 581,000 units, firmly holding the No. 1 spot among domestic brand fuel vehicles; Geely Galaxy sales reached 520,000 units, with multiple core products continuing to perform strongly; Lynk & Co sales reached 144,000 units, with new energy products accounting for 65%; Zeekr deliveries reached 178,000 units, up 97% year-on-year, with delivery growth rate ranking No. 1 in luxury new energy.

Geely Automobile's global expansion continued to break through, with overseas sales of 474,228 units in the first half, up 158% year-on-year, already exceeding the full-year 2025 export sales. Geely Automobile's overseas business accelerated towards high-end and new energy integration, with 277,000 units of new energy product exports in the first half, a surge of 585% year-on-year, accounting for 58% of new energy. Geely Galaxy new energy products firmly ranked in the top sales tier in multiple markets, while Zeekr took the championship in niche markets in multiple countries such as Thailand, Malaysia, and Mexico.

Star Wish will be produced at the Geely-Renault Brazil Plant
Volvo Cars (VOLCAR-B.ST) sold 325,000 units in the first half, of which new energy sales were 161,000 units, up 3.8% year-on-year, with a new energy penetration rate of 50%. Pure electric vehicle deliveries grew for 9 consecutive months, with new energy transformation continuing to break through.
Polestar Automotive (PSNY) sold 30,400 units in the first half, setting a new all-time record, achieving sales breakthroughs in major markets such as the UK, Germany, and South Korea.

Proton Cars sold 100,300 units in the first half, up 39.1% year-on-year, achieving the best sales performance since 2011. Besides maintaining steady growth in the fuel vehicle business, Proton also made progress in new energy transformation. The Proton e.MAS 7 PHEV launched in February this year continued to sell well, leading the Malaysia plug-in hybrid niche market.

Farizon New Energy Commercial Vehicle sold 88,000 units in the first half, up 41.3% year-on-year. Overseas export sales firmly ranked No. 1 in the new energy commercial vehicle industry, topping the new energy commercial vehicle markets in countries such as the UK, UAE, and Australia.

On the 40th anniversary of its founding, Geely Holding, led by the "Taizhou Declaration", deeply advanced the "One Geely, Fully Leading" 2030 Strategy. In the first half, facing a complex and changing market environment, Geely Holding Group continued to consolidate its leading position through steady and high-quality development, accelerating the realization of the enterprise vision of "leading the green intelligent mobility ecosystem".

Surprisingly, this year's World Cup soccer tournament actually had a 'negative impact' on car sales.
The market analysis report for June released by the CPCA mentioned that with the World Cup starting, the time and budget of car buyers were diverted. Implicitly, cars aren't selling well, and even the World Cup is to blame.
This is not just passing the buck. In the first half of this year, the China auto market was indeed very difficult, where any minor factor could affect final transactions.
According to data, national passenger car retail sales were 8.701 million units in the first half, a year-on-year drop of 20.2%. The drop in June alone widened to 23.2%. Statistics from CAAM also show that total vehicle sales including exports were 15.017 million units, a year-on-year decline of 4.1%.
Fortunately, just like a football match, halftime does not mean the end. In the first 100 matches of this World Cup, based on 90-minute results, 40 matches had different halftime win/draw/loss outcomes compared to the final result.
The second half for automakers has just begun. Whether they can rewrite the score depends on what cards each company holds. But one thing is unquestionable: Only leading automotive enterprises that seriously 'prepare' and have a stable 'chassis' have the opportunity to continue leading.
More Difficult Than Sales Decline is Profit Squeezing
A retail drop of 20.2% is already enough to catch the eye, but the more troublesome pressure compared to sales decline is hidden in the automakers' profit statements.
Data from the National Bureau of Statistics shows that in the first five months of this year, industrial enterprise profits above a certain scale nationwide increased by 18.8% year-on-year, while automobile manufacturing industry profits fell by 19.8%.
During the same period, the automobile industry achieved revenue of 420.96 billion yuan, a 1.4% year-on-year increase, but the profit margin was only 3.4%. Back in 2017, this figure was around 8%.

Revenue barely grew while profits plummeted, indicating that insufficient demand is only part of the pressure. Price competition continues, raw material prices like lithium carbonate and aluminum have risen, and R&D, channel, and marketing investments are hard to shrink synchronously with sales. For many automakers, even if cars are sold, the profit remaining on the balance sheet is decreasing.
This pressure is more intuitive when falling on specific enterprises.
In the first half, Li Auto delivered a cumulative 193,500 units, down 5.13% year-on-year, and saw single-month sales decline for two consecutive months; XPeng delivered 165,000 units, down 15.8% year-on-year. New force automakers that used to maintain high-speed growth are also beginning to face growth pressure brought by the expansion of sales volume bases and intensified product competition.
The situation on the profit side is even more severe.
On July 12, Seres released performance forecasts, expecting a net loss of 1.5 billion to 1.8 billion yuan in the first half, while the net profit for the same period last year was 2.941 billion yuan. This means its performance decreased by more than 4.4 billion yuan compared to the same period last year. Price hikes in raw materials such as memory chips and lithium carbonate have pushed up costs, compounded by book adjustments of certain existing assets, significantly impacting its profitability.
The pressure is also transmitting to the channel end. In June, the dealer inventory warning index reached 57.2%, continuing to remain above the prosperity-thriving line; more than 70% of dealer stores did not complete their half-year sales targets. Slower inventory turnover and expanded terminal discounts further compressed the profit space for dealers and automakers.
The new energy market is no exception either. The penetration rate of new energy in June has reached 62.8%, but new energy passenger car retail sales still dropped by 14% in the first half. The substitution of new energy for fuel vehicles continues, but no longer naturally equates to the total growth of the auto market.
Insufficient domestic market growth has also made exports an important direction for automakers to seek new growth and diversify operational pressure.
Exports Contribute Growth, Going Overseas Shifts to Local Operation
Data from CAAM shows that in the first half of the year, China's auto exports reached 5.096 million units, a 65.3% year-on-year increase; June alone exports were 1.037 million units, a 75.1% year-on-year increase, with monthly export volume standing at the million-unit level for the first time.
While domestic demand shrinks, exports have become an important fulcrum for many automakers to maintain scale. However, from exporting whole vehicles to building factories overseas to opening channels with international partners, the paths chosen by each company are not the same.
Chery remains the vanguard of exports. In the first half, Chery Group exported 943,800 units, accounting for nearly 70% of total sales; June alone saw exports of 191,100 units, breaking the record for single-month exports by Chinese automakers.
BYD's overseas focus is shifting from whole vehicle exports to local manufacturing. In the first half, BYD sold 789,400 units overseas, a 68% year-on-year increase; June overseas sales accounted for more than 40% of its total monthly sales. With factories in Brazil and Thailand coming into production successively, BYD is gradually spreading capacity 'beyond tariff barriers'.

Geely and Leapmotor's export growth rates are equally outstanding. Geely exported 474,200 units in the first half, a 158% increase year-on-year; first-half export volume has already exceeded that of the full year of 2025. Leapmotor utilized Stellantis' channels and factory layout to go overseas, exporting nearly 100,000 units in the first half, also exceeding the full previous year. Borrowing from a mature global system allowed Leapmotor to save the time needed to build its own channels and capacity.
SAIC's overseas sales in the first half were 735,000 units, a 48.7% year-on-year increase, accounting for about 36% of the group's total sales. Overseas manufacturing, channel, and brand systems accumulated over the years have become an important buffer in this round of domestic market adjustments.
Changan is also accelerating the transformation from product exports to local operations. The 2.0 version of the 'Sea Accepts Rivers' plan released in April proposed long-term, local, and systematic approaches, promoting global business extension into manufacturing, investment, service, and brand operations. With the landing of multiple results such as Brazilian President witnessing the Brazil factory production start, the 20,000th whole vehicle coming off the line at the Thailand factory, and Qiyuan Q05 launching in Uzbekistan, overseas localization layout is gradually showing results. In the first half, Changan delivered 402,000 units overseas, a 35.1% year-on-year increase, accounting for about one-third of the group's delivery volume.
In May, Changan reached a global official cooperation agreement with the Portuguese National Football Team. Carrying out sports marketing in the World Cup year can also be seen as a step where its overseas investment extends from channel construction to brand operations.
As the proportion of overseas sales in the enterprise's total portfolio continues to increase, export numbers are no longer the only standard for measuring the effectiveness of globalization.Tariff policies, certification standards, and consumption habit differences in different markets are significantly distinct. Channels, after-sales, local production, and brand building all require long-term investment, and may not directly translate into profits in the short term.
Therefore, in the second half of the year when evaluating automakers' overseas performance, sales volume is still the foundation, but local operation efficiency, brand recognition, and profit quality will become more important. Whether exports can truly precipitate into long-term growth depends on whether automakers can move from 'selling cars' to 'operating locally'.
Viewing Sales Proportion: Domestic Market Is Still the Main Battlefield
The rapid growth of overseas markets has not changed the basic proportion of the domestic market.
Data from CAAM shows that domestic car sales in the first half were 9.921 million units. Although down 21.1% year-on-year, the scale is still close to twice that of exports, accounting for about two-thirds of total auto sales. Calculated by half-year alone, one percentage point of market share is close to 100,000 units. No mainstream automaker would give up easily.
Domestic market competition is already fierce, but overseas giants have also not chosen to leave.
Data from the CPCA shows that in June, domestic retail of mainstream joint venture brand new energy passenger cars increased by 45% year-on-year. Volkswagen plans to launch more than 20 electrified models in China this year. The locally developed CEA electronic/electrical architecture has entered mass production with the first model, and subsequent models will also be launched successively within the year. As joint venture brands accelerate local R&D and new energy transformation, competition intensity in the domestic market will continue to increase.

Facing internal demand pressure, domestic independent brands are also looking for breakthrough points from different directions such as products, technology, organization, and capacity.
BYD stabilizes the sales basic disk while supplementing infrastructure. June sales reached 403,500 units, achieving year-on-year positive growth again; Megawatt flash charging is also starting to move from conferences to implementation, and charging networks are gradually spreading nationwide.
Geely is asking internal efficiency.Li Shufu proposed 'stopping, merging, transferring, and transforming' redundant entities, compressing repeated brand and R&D investments, and concentrating resources further on main platforms. In the first half, Geely stabilized overall sales volume with 1.423 million units.
New forces in the growth phase have also not stopped expanding. Leapmotor delivered 356,500 units in the first half, a 60% year-on-year increase, becoming the new force with the highest sales volume. The A10 launched in March entered the top three in SUV sales in three months, and the flagship model D19 cut into the fiercely competitive mid-to-large SUV market, promoting volume sales and brand elevation along two lines simultaneously.

Xiaomi delivered more than 180,000 units cumulatively in the first half. Compared to the 550,000 annual target set at the beginning of the year, monthly delivery volume in the second half needs to be increased to above 60,000. Expanding capacity and accelerating deliveries will become the core task of its second half.
Changan Auto achieved deliveries of 1.1956 million units in the first half, with 402,000 units delivered overseas (up 35.1% year-on-year), and new energy deliveries of 456,000 units (up 5.2% year-on-year). In the second half of this year, Changan Auto will concentrate on promoting product launches and technology implementation, continuously promoting the strategic synergy of Avatr and Deepal frontend independence and backend integration, while accelerating the application of self-developed intelligent technology.Currently, the Tiandu intelligent driving assistance function has been successively applied to Qiyuan Q07, A06, and the new Q05. According to the mass production plan announced in May this year, the Qiyuan Q06 launching in the second half will be equipped with Tiandu Pilot on all models, becoming an important node for Changan's self-developed assisted driving solution to further expand its application.

The domestic market still has a semi-annual scale of nearly 10 million units, and replacement demand will not disappear into thin air. The issue is, facing the increasingly dense new car launches and continuously increasing price pressure, automakers not only need to compete for sales but also need to try to repair profits.
In the second half, whether new cars can quickly gain volume, whether technology can be converted into experiences consumers are willing to pay for, and whether scale growth can bring operational efficiency improvements will jointly determine the performance of automakers in the domestic market.
Final Remarks:
In the first half of this year, the pressure on China's auto industry was reflected simultaneously at both sales and profit ends.Exports grew rapidly, providing a new scale fulcrum for automakers; but the domestic market still determines the basic disk of most enterprises and is the most intensely competitive main battlefield in the second half of the year.
The key to follow lies in whether overseas layout can precipitate into continuous orders and local operating capabilities, whether domestic new products can form scale delivery, and whether technology investment can truly be converted into revenue and profit.
For automakers that have completed a certain amount of preliminary layout, subsequent performance depends on whether products, technology, and global reserve can be timely redeemed for sales and income.
For the entire industry, simply pursuing sales volume is no longer enough; delivery speed, cost control, and profit quality will become equally important.
Halftime has passed, but the outcome has not yet been determined.
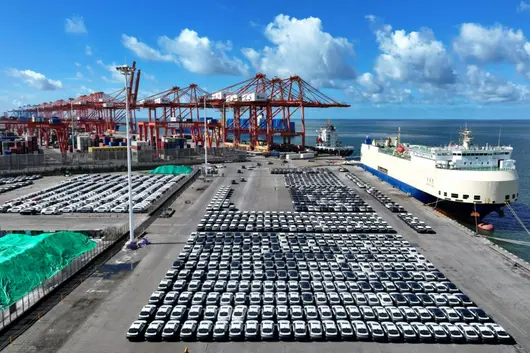
This year is a milestone year for Chinese automakers going global. According to new car sales statistics from the European Automobile Manufacturers Association, in May, sales of Chinese brand cars in Europe surpassed Japanese brands for the first time.
Following this, SAIC Group also sparked a wave of enthusiasm in the UK. On July 8, SAIC MG held a technology conference in London, bringing the most cutting-edge intelligent and electric technology back to the brand's birthplace; On July 9, SAIC MG appeared at the Goodwood Festival of Speed, where two concept cars, the two-door electric compact MG Go! and the coupe SUV Cyber Concept, shone brightly. The heritage of a century-old brand and the strength of a technological ace sparked sparks, as Chinese automakers ignite the global automotive market with intelligent and electric innovation technologies.

Scene of MG UK Technology Conference
At the same time, SAIC's overseas market also submitted an excellent half-year exam report: Sales overseas in June reached 146,000 vehicles, a year-on-year surge of 61.2%, setting a historical high. In the first half of this year, SAIC's overseas market cumulative sales reached 735,000 vehicles, a strong increase of 48.7% year-on-year, ranking among the leaders in the industry. Driven by the "Glocal Strategy", SAIC is transforming from selling cars to full-chain global expansion, continuously deepening overseas value chain construction.
Comprehensive Technological Advancement, Polishing the Product Name Card
At the technical brand level, SAIC is systematically building global intelligent labels for "Hybrid+ Hybrid Technology", "SolidCore Solid/Semi-Solid Battery Technology", and "i-Smart Intelligent Driving Technology". At the UK technology conference, the MG brand showcased MG Plug-in Hybrid+ Hybrid, SolidCore Semi-Solid Battery, and MG Parking Smart Cockpit and Assistive Driving. In addition, MG became the first automotive brand globally to achieve mass production of semi-solid batteries; The IM AD intelligent driving system of IM Motors has covered five continents globally; The global activation volume of the overseas travel i-Smart system has exceeded one million.

Scene of MG UK Technology Conference
At the Goodwood Festival of Speed, the MG brand unveiled globally two concept models: the two-door electric compact MG Go! and the coupe SUV Cyber Concept, stunning the entire audience. The design inspiration for the two models comes from MGB GT, MG 6 R4 Group B Rally Cars, MG EX181 Streamlined Racing Cars, and other classic brand models, showcasing brand heritage and future vision.

MG GO! Concept Car

MG Cyber Concept Concept Car
At the product implementation level, SAIC will achieve massive product global deployment in the next three years: Full powertrains cover ICE, HEV, PHEV, EV four forms, adapting to energy policies and consumption habits of various countries; At the same time, SAIC is creating over ten new overseas models including SUV, sedan, MPV, pickup, comprehensively covering household, commuting, high-end driving, long-distance travel, outdoor and other full scenario needs, connecting global mainstream market segments.
From Frankfurt to London, from technology exhibitions to runways, SAIC MG advances in leaps and bounds, showcasing a new name card of Chinese intelligent manufacturing to the world with more cutting-edge technology and newer models.
Deepening Regional Markets, Serving Global Users
While technology sails overseas, the pace of SAIC deepening the global market is also accelerating. Currently, SAIC's products and services cover over 170 countries and regions worldwide, forming 1 "300,000-class" market (Europe) and 5 "50,000-class" markets (Americas, Middle East, Australia & New Zealand, ASEAN, South Asia), with overseas cumulative sales exceeding 7 million vehicles.
Europe is SAIC's largest overseas market. The MG brand has won the "Chinese Brand European Sales Champion" for 11 consecutive years and has become the first Chinese automotive brand to exceed 1 million cumulative sales in Europe. In the first half of this year, MG brand sales in Europe exceeded 190,000 vehicles, a year-on-year growth of over 20%. On July 1, MG brand established a direct sales company in Belgium and Luxembourg, which is also an important step for SAIC to implement the "Glocal Strategy" and take root in local Europe. From leading Chinese automotive brands in sales scale to deepening the European market and building long-term user relationships, MG is realizing a transformation from "selling cars" to "managing", thereby better improving service capabilities, listening to customer needs, achieving agile responses to market dynamics, and precise control of customer experiences.

MG Brand Appears at Goodwood Festival of Speed
Not only in Europe, SAIC is blooming in multiple points globally by continuously deepening local markets. In Thailand, the MG brand launched the new service strategy "MG SMILE" in May, solving local user concerns such as price transparency, dealer commitment fulfillment, and consumer rights protection with a full-process service standard system, and providing lifetime warranty for three-electric systems for pure electric models. With the support of new service standards and lifetime warranty policies, the new MG URBAN went on sale in Thailand on June 24, bringing high-quality products and services of Chinese intelligent manufacturing to more Thai users.

MG URBAN
In Central Asia, in June this year, multiple models such as SAIC Volkswagen Tiguan L Pro, Passat Pro, Teramont X, Teramont Pro, T-Roc New, Lavida New entered the Uzbekistan market, achieving the "zero breakthrough" for SAIC Volkswagen in the Central Asian market. Previously, the SAIC Group Almaty MG Flagship Store officially opened in April this year, SAIC joined hands with Allur, Kazakhstan's largest automotive production and assembly enterprise to achieve localized production and model adaptation for customer needs. The two brands join hands to explore the Central Asian map, providing more intelligent models and higher-level services for local consumers.
Good news also came from the commercial vehicle sector. Recently, SAIC Hongyan formally reached a strategic cooperation agreement with a top port major customer in Thailand for 1,000 new energy heavy trucks. The first batch of complete vehicles has completed packing and boarded ships in batches, setting off from domestic production bases to Thailand. This also marks that SAIC Hongyan, relying on independent core three-electric technologies, full-scenario customization capabilities, and a comprehensive overseas local service system, breaks the monopoly of foreign brands in the Thai heavy truck market, showcasing the complete industrial chain of Chinese commercial vehicles and the hard power of green intelligent manufacturing to the world.
From monthly sales breaking the best historical record to technology label formation and localization deepening landing, behind SAIC's overseas market report card is the systemic effectiveness of the Glocal Strategy "Global Automotive Brand + Localized System Ecosystem". Facing the future, SAIC will continuously accelerate the transformation from complete vehicle overseas to value chain overseas, writing a new chapter of Chinese intelligent manufacturing in the global automotive industry landscape.
GAC Group released a half-year performance report for 2026. The numbers are quite shocking — net loss for the first half estimated at 4.06 billion to 4.57 billion yuan. The net profit after deducting non-recurring gains and losses was even worse, with a loss of 4.8 billion to 5.6 billion yuan. More than 4 billion yuan, losing over 20 million yuan per day, it doesn't look very ideal.
But look at another set of numbers — GAC sold 773,100 vehicles in the first half, a year-on-year increase of 2.35%. New energy vehicle sales accounted for over 60%. Independent brands sold 346,000 vehicles, a surge of 35.69%. AION was even more fierce, 181,600 vehicles, a year-on-year increase of 67.08%. Overseas exports 121,500 vehicles, a year-on-year increase of 132%, the semi-annual export scale is already close to last year's full year level. Sales are up, new energy transformation is accelerating, and exports are doubling — but the books show an even bigger loss. How is this account calculated?

GAC Group
What does the official say?
GAC's announcement was very straightforward, three reasons:
First, domestic market competition intensified, independent brands continued to increase sales investment, plus changes in product sales structure, and rising upstream raw material costs, leading to a decline in independent brand profits.
Second, joint venture brands are facing operational pressure. Specifically, terminal sales decline, continued increase in sales investment, rising raw materials, etc., are all important factors, and the company's investment income decreased year-on-year.

Reason for Loss
Third, exchange rate fluctuations caused exchange losses, adding another blow. Obviously, GAC Group gave a relatively clear interpretation of the reasons for the loss in the first half.
To translate, it might be that independent brand profits are not as high as before, joint venture brands are under greater pressure, and exchange rates also caused a certain loss to profits.
Combining all the above factors, GAC Group is expected to incur a loss in the first half of 2026. Moreover, the loss amount is expected to reach 4.06 billion to 4.57 billion yuan, which is quite high.
However, Car Universe World believes that if you only focus on the word "loss", you might miss the real story.

Loss Forecast Announcement
Joint Ventures: One "Under Pressure", One "Steady"
GAC Group official data shows, GAC Honda sold 68,300 vehicles in the first half, a year-on-year decline of 55.82%, almost 60% down. June single month 14,000 vehicles, although it increased more than 50% month-on-month, it fell 53% year-on-year.
The joint venture giant that used to sell 700,000 annually, now the average monthly sales of the first half is over 10,000 units. Accord, Fit, Vezel, Integra these classic models, monthly sales generally not as high as before.
Obviously, from the sales perspective, in the first half of 2026, GAC Honda still declined significantly, reaching over 50%, bearing a certain amount of pressure.

Production and Sales Express
But the performance of GAC Toyota is different, the overall performance is still steady. Moreover, under the situation that domestic car market joint venture brands are under pressure overall, its sales volume is stable and rising.
GAC Group official data shows, in the first half of 2025 GAC Toyota sold 356,000 vehicles, monthly average sales close to 60,000 units. Year-on-year increase 3.29%. March, April, May for three consecutive months topped the sales list of joint venture car companies. July 2nd, GAC Toyota also welcomed the 10 millionth mass-produced vehicle rolling off the assembly line, joining the "million-unit level large factory".
Moreover, Car Universe World found, supporting GAC Toyota is not low-price volume-selling cars, but the Camry, Highlander, Sienna three major flagships continuing to exert effort, smart electric hybrid double engine vehicle proportion reached 54% . Boxi brand sold 52,000 units in the first half, Boxi 3X consecutive 10 months holding joint venture pure electric sales champion.
One continues to bear pressure, one steady, this joint venture card, GAC has not finished playing yet.

Boxi 7
Independent and Overseas Markets, The Real Highlights
Car Universe World believes, if there is anything eye-catching in GAC's first-half performance report, it must be the overseas market and the surge in independent sales.
Official data shows, first half of 2026, GAC Trumpchi cumulative sales 164,000 units. Compared to the same period last year, sales increased by 12.36%.
AION rose even harder. Official data shows, first half of 2026, GAC AION cumulative sales 181,000 units. Compared to the same period last year, sales increased by 67.08%.
In terms of overseas markets, first half independent brand exports 121,500 vehicles, year-on-year growth 132%, semi-annual export scale already close to last year's full year. Americas, Asia-Pacific, Middle East, Africa, Europe five major regions simultaneously achieved high-speed growth.

Trumpchi E8
Mexican market, AION ES and AION UT both entered the top ten in new energy BEV sales. Bolivia, GAC brand consecutive months holding China brand passenger car sales champion. Singapore, Thailand, Malaysia, Indonesia — GAC's overseas map is blossoming in multiple points.
GAC's overseas target set at the beginning of the year was 250,000 vehicles for the full year, striving for 300,000 vehicles. First half completed 121,500 vehicles, completion rate close to half. When the domestic market is too hard to compete, overseas became GAC's strongest growth curve.

AION N60
The Account of Transformation, Cannot Look Only at the Present
The "Panyu Action" launched in 2025 is being implemented step by step.
Headquarters moved to Panyu, closer to the production frontline. Feng Xingya said an interesting sentence — "We moved the office to the place closest to the gunfire, so that those who hear the gunfire can call for it." Business Unit (BU) restructuring finished, Hyper AION BU formed first, January 2026 Trumpchi BU also established. GAC independent brands have formed a new operating architecture centered on BU.
Cooperation with Huawei also produced results. Jointly created high-end brand "Qijing" first model GT7, launched in Hangzhou on June 26th. Price 209,900 to 329,900 yuan, launched 24 hours big deposit orders broke 5200 units, Post-90s, Post-00s user proportion over 60%. Pre-sale 5 hours orders broke 10,000. 90 cities nationwide 300 stores gradually launched.
Qijing GT7 is equipped with Huawei Qiankun Intelligent Driving ADS 5. This is GAC's first car with deep cooperation with Huawei, and also a hard battle facing the market after the "Panyu Action".
These moves are all "money" in the short term — R&D needs money, channels need money, brand building needs money. But looking at a longer time dimension, these investments are storing power for the next stage. GAC positioned 2026 as the "Internal Renovation" critical stage, likely this is the meaning — first solidify the foundation, then talk about building high-rise buildings.

AION N60
Conclusion of This Article:
GAC's full-year target set at the beginning of the year was 2 million vehicles, first half completion rate less than 40%. Second half needs to sell nearly 1.23 million vehicles, monthly average over 200,000 vehicles. Under the current situation of joint venture pressure and intensifying new energy competition, how hard this task is, no need to say more.
But Car Universe World believes, the cards GAC holds are not finished playing yet. Joint ventures have GAC Toyota stabilizing, independent brands have AION and Trumpchi rushing, overseas releasing volume, Qijing just started.
How to play these cards, when to play them, perhaps will become an important factor for GAC Group when to walk out of the pain of transformation. These, we still let time give an answer.
Transformation is always bitter first then sweet, and never looking only at the present. What do you think? Let's chat in the comments.
Statement: This article involves relevant events, originating from brand official or authoritative media messages, for reference only, specific based on official information. If there are information, data discrepancies caused by typos, based on official information. Hope everyone looks rationally, do not believe rumors, do not spread rumors.
Article Statement:
This article is original writing of Car Universe World, reviewed by Ling Qing/Liu Shuai, Total Issue 14186, some pictures from the internet, marked source data and related materials are all citations. Car Universe World original copyright owned, infringement will be investigated.
In the past two years of the Chinese auto market, price wars, technology wars, and global expansion wars have advanced intertwined. In the first half of 2026, as these variables accelerate simultaneously, the complexity and intensity of market competition have also been pushed to a new historical height. Looking back at the first half of 2026, the Chinese auto market was full of magical colors. The density of new car launches and the intensity of upgrades have once again refreshed external cognition.
Under such a competitive rhythm, hit products are becoming fewer. Products that can maintain continuous global hot sales, keep monthly sales exceeding 10,000, and maintain high heat and word-of-mouth are extremely rare.
Deepal S05 is one of this "very small number" camp.
According to the latest June global sales data released by Deepal S05, the June global sales achieved 18,369 units, a year-on-year increase of 78.86%.
Not only that, Deepal S05 also won the sales champion of 120,000-180,000 RMB-level compact SUVs for 4 consecutive months from March to June this year. Its global hot sales map has already covered 73 countries and regions worldwide, and the global cumulative sales have broken through 240,000 units.

Just looking at the data, this series of numbers is enough to explain the market's recognition of Deepal S05. You should know that currently, the vast majority of products generally face the "Valley of Death" effect. The hot sales cycle of a new car is extremely short, while Deepal S05 has achieved monthly sales exceeding 10,000, continuous topping, and fully blooming results domestically and globally.

If numbers are just the result, then what is truly worth questioning is clearly what Deepal S05 got right behind this set of hot sales data?
In our opinion, there are three key passwords for hot sales behind this. The first is the satisfaction of rigid demand in product power.
In the compact new energy SUV sub-market, although market choices are rich, with layout from independent to joint ventures, the product power involution around configurations, prices, materials, etc., is arguably fierce, but Deepal S05 did not blindly pile materials nor obsess on showing off skills. Instead, it anchored the highest frequency, most real vehicle usage scenarios for users, spending every bit of cost on the "edge" users can perceive.

In terms of range, compared to the mainstream 500 km level of most products in the same price range, Deepal S05's pure electric range can reach up to 620 km. For complex climates, Deepal S05 is also equipped with the world-first Micro-core High-Frequency Pulse Heating Technology and Heat Pump Air Conditioning System, which can effectively solve the problem of range attenuation in low temperatures.
In terms of recharging, Deepal S05 directly standardizes 3C supercharging technology across the entire series, requiring only 15 minutes to complete SOC 30%-80% energy replenishment. In terms of safety, Deepal S05 also equips the entire series with CATL + Golden Bell Battery technology. Safety certifications far exceed new national standards, building the most basic trust foundation for users with unseen hard power.
In terms of space, relying on the 2880mm class-leaping wheelbase and CTV body-battery integration technology, seating space close to a mid-size SUV was achieved within the size of a compact SUV. Plus the storage combination of a 159L front trunk and a 492L trunk, Deepal S05 has written the two words "practical" into every detail.
Not greedy for many, not seeking complete, aiming for rigid demand, achieving the best in class in the scenarios users use most frequently. This is exactly the product philosophy of Deepal S05 standing out in configuration involution.

The second is Deepal Automobile's forward-looking global vision and agile global layout speed.
In the new energy compact SUV sub-market, the vast majority of Chinese brands still focus their focus on the stock game in the domestic market, and overseas strategies often stay in the "long-term planning" stage. But Deepal S05, based on a globally unified manufacturing and quality control system, quickly advanced into 73 countries and regions worldwide in just over a year.
From Southeast Asia to Middle East and Africa, from Central and South America to European core markets. The pace of steps, the extent of coverage, is almost impossible to find a second sample in the same class of models.
Beyond speed, depth is also worth paying attention to. In the overseas market, Deepal S05 also won multiple authoritative recognitions such as the German iF Design Award, Thailand Annual Best Rear-Wheel Drive Compact Electric SUV, Chile Autocosmos 2026 Best Recommended Model, FIPA Americas Automotive Journalists Association Annual Hybrid Model Award.
These authoritative awards from different regions and different evaluation systems all point to one conclusion: Deepal S05's product strength can stand up to the most rigorous scrutiny globally. According to planning, Deepal S05 will enter 150+ countries and regions worldwide in the future. The continuous expansion of the global map means that the Deepal S05 phenomenon of monthly sales exceeding 10,000 and continuous hot sales will be the norm.

The third is the dissemination at the cultural level and the satisfaction of emotional value.
Current market competition is no longer just a simple battle of product power, especially when the rise of the main young consumer army, the satisfaction of emotional value has also become an important part of each car company's competition soft power. For this form of competition, Deepal S05 also had insight early on.
In May this year, Deepal Automobile officially signed to become the global official partner of the Portugal National Team. At the Lisbon announcement site, Deepal Automobile delivered Deepal S05 to the team and simultaneously launched a 1,000 km Europe long-term test.
With sports spirit as the emotional link, under the hot promotion of the World Cup, Deepal S05 not only won more market exposure but also further solidified the global consumer market's image cognition of its "global flagship product". This will also form key empowerment for its upcoming global journey.
In summary, product competitiveness lays the foundation, global map expands increment, product emotional value reversely empowers hard power. Three layers advance, linked rings. This itself is a complete hot sales closed loop. And this closed loop, undoubtedly, will also usher in continuous self-reinforcement and expansion as Deepal S05 enters more countries and regions, the global user base continues to expand, and product power continues to evolve.
Recently, Kia China announced that sales in June 2026 reached 25,791 units, with a month-over-month growth of 15.8% and a year-over-year growth of 11%. Single-month sales exceeded 20,000 units for 3 consecutive months, and cumulative sales from January to June reached 118,114 units. In the first half of this year, facing the overall downward pressure in the auto industry, Kia China firmly implemented the "In China, For China" strategy. Through measures such as strengthening brand image, improving product competitiveness, expanding service channels, and optimizing user experience, it achieved double growth in sales year-over-year and month-over-month for 2 consecutive months, showcasing steady development momentum and strong corporate resilience.
Meanwhile, facing the environment of overall pressure in the global auto market, Kia's global sales in June reached 295,720 units, and cumulative sales in the first half reached 1,630,988 units, growing 2.7% year-over-year against the trend, setting a new high for first-half sales again! Among them, Sportage and Seltos ranked first and second in Kia's global single-model sales with 303,203 units and 177,148 units respectively.

Currently, the 2026 US-Mexico-Canada World Cup is in full swing. As an official partner cooperating with the International Football Federation (FIFA) for nearly 20 years, Kia not only sponsored 660 operational vehicles for this tournament but also brought a "World Cup Co-branded Gift" to Chinese consumers: Consumers who visit the store for a test drive before July 31 can participate in the lottery to win prizes such as a purchase voucher worth up to 5,000 yuan, a Kia x World Cup x Adidas merchandise set; sharing test drive experiences, one can also receive a limited edition Kia x World Cup x Adidas official football. At the same time, Kia also provided a 2,500 yuan purchase tax subsidy for 3 "Fixed Price" models: New Sportage, K3, and Sonet, and gifted a 2,000 yuan fuel card / electric card to customer groups including university graduates, newlyweds, newborn families, as well as faculty, medical staff, media practitioners, etc., fully demonstrating full sincerity towards Chinese consumers.
It is worth mentioning that as a partner of the International Football Federation (FIFA) for nearly 20 years, Kia possesses exclusive rights to select official ball boys and girls globally. For this World Cup, Kia selected 104 teenagers aged 10 to 14 to serve as ball bearers globally. On July 3, the 2026 US-Mexico-Canada World Cup Knockout stage Round of 16 match between Spain and Austria was held at Los Angeles Stadium. Under the cheers of tens of thousands of fans, 11-year-old girl Liu Shuying, the only Chinese official ball bearer of this World Cup, walked onto the green field with world's top players and personally handed the match ball to the referee's hands.

In the first half of this year, from the nationwide "Fixed Price" car purchasing policy launched at the beginning of the new year to fuel card subsidies, purchase tax reductions, and multiple privileges successively implemented, Kia China continued to reward Chinese consumers with super-value car purchasing plans, effectively lowering consumers' car buying threshold, making prices more transparent, and car buying more worry-free. Thanks to a series of super-value car purchasing policies, sales of Kia's star models grew significantly compared to the same period last year. This also validates Kia's reliable global quality, excellent driving and riding comfort, outstanding fuel economy, and other advantages, which are winning recognition and trust from more and more Chinese consumers.

In addition to actively integrating global top-tier event resources, Kia China also deeply cultivates domestic Chinese sporting events. In the first half of this year, Kia China has sponsored the Yancheng Marathon for 6 consecutive years and became the main sponsor of the "Jiangsu Super League" Yancheng Team for 2 consecutive years. Not only providing all-round support for Yancheng local events, it also organized official volunteer shuttle fleets, invited children from special groups to watch Jiangsu Super League matches, planned the "Little Ball Boy Dreams Come True" Program, and created exclusive experience activities for car owner families such as free viewing, factory visits, new car test drives, extending the brand warmth to every participant inside and outside the venue, continuously conveying a positive and warm brand image.
In terms of products, Kia China combined Kia's global quality and China's intelligent technology advantages, using high-quality, high-intelligence, and high-value products to respond to Chinese users' diverse expectations for quality mobility. In April this year, the "Global Urban SUV Pioneer" with global cumulative sales exceeding 8 million units, the New Sportage from Kia, was relaunched. The new car inherited "Sportage"'s 33-year history and 5 generations of models' reliable quality, comprehensively improving in styling design, space experience, intelligent technology, safety configuration and other dimensions. The "Renewed Fixed Price" starts from as low as 109,900 yuan, and the main-selling 1.5T Prestige Edition "Fixed Price" is only 124,900 yuan. Compared to the old model, 13 configuration upgrades were implemented, further meeting Chinese users' needs for more comfortable and intelligent mobility.

It is worth noting that the Kia New Sportage has been on the market for over 100 days and still maintains the excellent result of "zero customer complaints" for new car quality. This not only proves its solid product quality but also highlights the world-leading manufacturing standards and quality control strength of Kia China No. 3 Factory. As Kia's global core production base, Kia China No. 3 Factory fully benchmarks against international first-class manufacturing standards, introducing advanced tools such as Kia Global Quality Management System (GQMS), MES Manufacturing Execution System, and IQIS Production Finish System, building a full lifecycle quality management system covering R&D, manufacturing to after-sales. It is precisely by embedding rigorous quality control standards throughout the entire production process that at the "2026 China Automotive Product Quality Trend Symposium" jointly hosted by China Auto Quality Network and Kearney Consulting, Kia China No. 3 Factory was rated as "2025 Automotive Quality Excellence Factory", highlighting its benchmark status in manufacturing quality among joint-venture enterprises.

It is also worth mentioning that on June 5, at the Israel "2026 Annual Car" selection, the Kia New Sportage stood out among competitors and won the "Annual Compact SUV" award, validating its comprehensively advanced product value and leading product power in the same class again!

In terms of channel construction, Kia China persisted in promoting the expansion and improvement of terminal channels, continuously deepening cooperation with large dealer groups represented by United Crown, Blue Pool, Jiangsu Zhixing, Guoao, Zhongchi, etc., strengthening service networks and promoting the deployment of standard services. In the first half of this year, Kia China partnered with partners to add 28 new outlets. In particular, the first Global SI 2.0 Standard Flagship Store jointly built by Kia and Longjiu Group in Guangxi since April this year not only filled the gap in high-quality mobility services in the Guangxi region but also brought efficient and convenient comprehensive service experiences to local users.

For a long time, Kia China has always regarded customer service as the cornerstone of the brand's long-termism. In the first half of this year, relying on globally unified high-quality service standards, Kia China continuously optimized the service ecosystem covering pre-sales, in-sales, and after-sales stages, creating high-quality service experiences for the full lifecycle. In pre-sales and in-sales stages, Kia China optimized customer experiences around key touchpoints such as store visits, test drives, signing, and delivery, gaining wide trust from consumers and industry authoritative institutions. In the 2026 China Purchase Customer Experience Index Research SM (PXI) released by J.D. Power, Kia scored 806 in Purchase Customer Experience Score, ranking fourth in mainstream traditional energy brands and second in joint-venture brands, continuously entering the top five mainstream brands and top two joint-venture brands of this list, showcasing deep accumulation and leading strength in user service and car buying experience fields.

(Source: J.D. Power China Purchase Customer Experience Index Research SM (PXI))
In the after-sales service field, Kia China continuously brought more efficient and higher-quality service experiences to users around service management system upgrades, service quality control optimization, service facility implementation, and application. At the same time, by regularly holding Service Consultant Skills Competitions and Maintenance Technician Skills Competitions, Kia China continuously improved the service level of its service teams through the method of "promoting skills through competition, service upgrade". At the 12th Kia Global Skills Competition held this year, Maintenance Technician Guo Wenlei from Jinan Jinwantong Store won the overall silver medal of the competition, fully demonstrating Kia China's maintenance technicians' solid professional foundation and excellent service capabilities.

In the first half of this year, Kia China continued to consolidate the development pattern where domestic and foreign sales progressed together and continuously expanded global export business. To date, Kia China has cumulatively exported vehicles exceeding 617,000 units, with export sales exceeding 6.79 billion US dollars, building an export matrix consisting of 6 models including EV5, Sportage, Seltos, K5, Cerato, and Rio, covering 91 countries and regions worldwide including Australia, Mexico, Saudi Arabia, etc. Engine exports also achieved remarkable results. In June, 7,491 units of engines were exported, with cumulative exports of about 531,000 units, sold to countries such as Russia, Czech Republic, Slovakia, South Korea, Vietnam, Malaysia, India, Kazakhstan, Turkey.

In addition, in the environment of overall volatility and adjustment in the auto industry, Kia China firmly implemented the people-oriented long-term development philosophy, focusing on building a workplace culture of harmony between enterprise and employees, mutual empowerment. At the Jiangsu Provincial Corporate Culture Excellent Results Launch Event held in April this year, Kia China won the "2024-2025 Jiangsu Provincial Corporate Culture Excellent Results First Prize" with the project "Building a New Communication Engine to Achieve Cultural Aggregation and Leap" for systematic innovation and excellent results in the field of corporate culture, becoming a benchmark example for corporate culture construction in joint-venture enterprises.
Deeply cultivating the Chinese market for 24 years, Kia China has cumulatively gained the trust of over 6.85 million users. In the future, Kia China will firmly implement the "In China, For China" development strategy, continuously improve in dimensions such as brand value, product quality, channel network, and service experience, bringing travel experiences far exceeding expectations to more Chinese consumers.
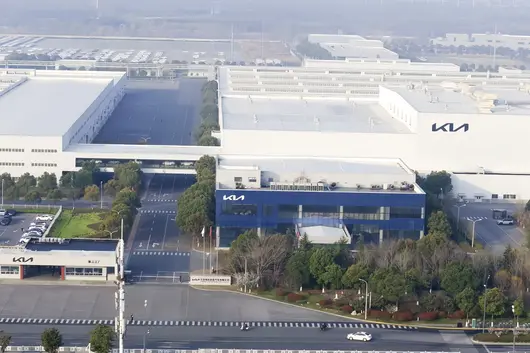
The global automotive industry is welcoming a deep transformation towards electrification, intelligence, and globalization. Industry competition is no longer limited to product comparisons, but extends to an all-around contest in technological R&D, brand building, industrial chain layout, and overseas markets. As a backbone domestic central state-owned automotive enterprise, Dongfeng Motor is steadily advancing the "Oriental Wind 2030" strategy. In 2026, the opening year of the "15th Five-Year Plan" development plan, relying on cutting-edge technologies, diverse new energy products, and a global layout, the market performance in the first half of the year was brilliant, achieving sales "five wins", highlighting development resilience in fierce industry competition, and carving out a high-quality development path towards new technologies, upward growth, and the globe.

In the first half of 2026, Dongfeng Motor's cumulative total vehicle sales reached 1.021 million units, with all five core indicators outperforming the industry benchmark. Overall sales growth rate was 1.1 percentage points better than the industry; domestic market cumulative sales were 831,000 units, growth rate 9.6 percentage points higher than the industry, firmly stabilizing the local base; new energy vehicle sales reached 493,000 units, up 27.5% year-on-year, growth rate leading the industry by 21.2 percentage points, showing significant results in green transformation; independent brand sales reached 725,000 units, up 13.6% year-on-year, growth rate exceeding the industry by 13.2 percentage points, with the independent upward strategy landing and proving effective; overseas exports surged 97% year-on-year, global layout entering a rapid realization phase. These bright data points are not short-term market dividends, but the result of Dongfeng's long-term deep cultivation in intelligent self-research, green tracks, and global channels.
2026 is designated as Dongfeng Motor's "Technology Realization Year". The enterprise takes the "Tianyuan Intelligence" plan as a key driver, continuously breaking through intelligent core technologies and building an autonomous and controllable intelligent car underlying system. In the cockpit field, Dongfeng launched a complete Tianyuan Smart Cockpit product matrix, covering all sub-segments from high-end to mainstream. Among them, Tianyuan Smart Cockpit Plus is the first domestic integrated cockpit and driving platform, integrating 3D immersive vehicle control interaction and intelligent driving SR rendering technology, equipped with a self-developed AI large model, creating a new generation of intelligent cockpits that are intuitive, easy to understand, and convenient to operate, to be batch-mounted on domestic chip benchmark models. In the AI field, the self-developed "Taiji Large Model" passed the Generative AI filing with the National Cyberspace Administration, deeply collaborating with the Tianyuan vehicle architecture and vehicle operating system, building a smart security defense line while implementing AI in vehicles. At the same time, Dongfeng released the OpenWorld Multimodal Real Road Dataset Open Plan, opening massive real-world road data to the industry, providing important support for autonomous driving world models and vehicle embodied intelligence R&D, assisting the coordinated development of the domestic intelligent driving industry.

Automotive-grade chips are the core hardware foundation of intelligence. Dongfeng continues to attack chip domestication, with multiple self-developed products filling domestic blanks. The all-domestic high-performance automotive MCU chip DF30 completed verification, adapted for engine ECU, and has been mounted on Epai 007, Mengshi M817, and other models to promote mass production; the automotive high-side driver chip INH025X performance benchmarks international top products, selected in the central enterprise science and technology innovation results catalog, cumulative installations over 350,000 units, significantly reducing dependence on foreign core components. Intelligent upgrades were simultaneously landed in manufacturing. In January this year, the world's largest 16000T integrated die-casting production line went into production, used for battery box production, and Dongfeng became the only enterprise in the industry to achieve whole vehicle front-mid-rear fully integrated die-casting layout. The production line carries a large number of industrial robots and self-developed intelligent systems, capable of reducing costs and increasing efficiency, and improving battery collision protection capabilities, first applied to Epai M8. The world's single largest medium and heavy commercial vehicle smart factory put into production at the same time is equipped with 288 collaborative robots, welding and painting automation rate 100%, relying on digital twin and AI quality inspection technology, production efficiency increased by 30% compared to traditional factories, smart manufacturing strength remains at the forefront of the industry.
Green and low carbon is the core direction of automotive industry transformation. Dongfeng landed the "Tianjing Zero Carbon" plan, adhering to the "Pure Electric Foundation, Hydrogen Leadership, Diverse Layout" route, creating a new energy product matrix covering all power types, adapting to various mobility scenarios. In the first half of the year, multiple new products were launched centrally, fully covering all sub-segments. In the high-end new energy sector, Voyah Taishan Ultra, Taishan X8 completed delivery, consolidating high-end brand positioning; Mengshi M817 broke the industry bottleneck where luxury off-road comfort, intelligence, and performance are difficult to balance; the new brand Yijing launched flagship six-seat SUV Yijing X9, setting new generation vehicle standards from three dimensions of safety, comfort, and driving control. In the home market, Epai M8 six-seat SUV directly hits the pain points of multi-child family travel, pre-sale orders broke 10,000 on the first day; 2026 model Aeolus L7 EV consolidates the 100,000 yuan level pure electric SUV market; Nano 06 Smart Fun Version downgraded intelligent configurations, lowering car purchasing thresholds; Fengxing Haixiang T5, Haixiang V6 focus on affordable commuting market, enriching mass green travel choices.

Hydrogen business relies on over 20 years of technology accumulation to form differentiated advantages. Dongfeng built a 20kW to 400kW full-coverage hydrogen power platform, holding over a thousand hydrogen energy invention patents, technology continuously converting into commercial orders. Self-developed 400kW fuel cell stack passed national standard 10,000-hour durability test in May, becoming the first domestically rated "Durability Star" metal bipolar plate stack. Commercialization landing sped up, signed 1,500 hydrogen heavy truck big order in March, mass put into use in Three Gorges Water Transportation Engineering in June, promoting hydrogen heavy trucks into mainline logistics, ports, sanitation, infrastructure and other scenarios. Currently Dongfeng hydrogen fuel vehicle cumulative sales exceeded 9,000 units, demonstration operations covered over 40 cities nationwide, operation scale industry first. R&D system upgraded simultaneously, 2026 Dongfeng established Basic and Pioneer Technology Research Institute, Global Design Center put into use, "Three Countries Six Places" R&D network formed; led to establish Hubei Solid State Battery Innovation Consortium, uniting 18 industry-university-research units to attack next-generation battery technology, landed the province's first new energy vehicle academician workstation, relying on top teams to attack automotive new materials, consolidating long-term green technology competitiveness.
Around "Sky Sail" globalization strategy, Dongfeng innovates overseas cooperation models, perfecting R&D, production, and sales integrated overseas layout. This May, Dongfeng signed deepening strategic cooperation agreement with Stellantis Group, paving the way for entering European new energy market. Domestically, six parties injected over 8 billion yuan to empower Dongfeng Peugeot-Citroën, promoting brand intelligence and green transformation; overseas planning both sides jointly build European joint venture, coordinating new energy vehicle local R&D, production, distribution and procurement, building a stable export platform. Logistics guarantee aspect, Dongfeng renewed strategic cooperation with COSCO SHIPPING, strengthening cross-border vehicle and parts logistics, improving global supply chain risk resistance ability.

Passenger car overseas implementation high-low end dual-line layout, affordable models and high-end brands simultaneously put in effort. DONGFENG BOX, 007, MAGE, and other models sold hot in Europe, Latin America, Africa markets due to high cost-performance; Voyah, Mengshi enter Saudi, UAE, Egypt, and other Middle Eastern countries, completed exclusive tuning for local high temperature and sand environment; Voyah captured high-end users with new Chinese style luxury, Mengshi off-road performance gained foreign enthusiasts' favor. Commercial vehicles adhere to one place one policy, scenario customization: customized V5 tractor for Saudi long-distance logistics; launched two differentiated delivery models for Peru fresh fruit transport; Southeast Asia deployed full series light and heavy trucks, Malaysia single batch delivery 830 units, signed 500 units; adapted to Australia right-hand drive regulations launched light logistics vehicle CAPTAIN.45. Channel network continues to expand, Dongfeng overseas authorized marketing outlets reached 1,600, covering over 150 countries worldwide, over 30 overseas markets sales doubled, overseas channel deep cultivation effectiveness highlighted.
Standing at the "15th Five-Year Plan" opening new starting point, Dongfeng Motor takes "Tianyuan Intelligence", "Tianjing Zero Carbon", "Sky Sail" three plans as core lever, steadily promoting four industrial ecology construction. Next step, enterprise will continue to deep cultivate product iteration, core technology self-research, global market expansion, constantly enrich new energy product matrix, break through intelligent vehicle hardware and software key technologies, perfect global production and sales channels, go all out to shape technology-oriented, international, and youthful brand image, seize development opportunities in the global automotive industry transformation wave, assist domestic automotive industry high-quality transformation and upgrading with SOE responsibility.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
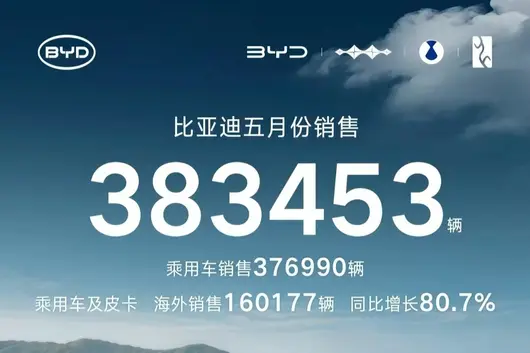
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.


