


首頁New Energy

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
Editor's Note: Geely Group's performance in the first half of the year can be called bright, but in the automotive market where variables are ever-present, its challenges for the second half of the year remain.
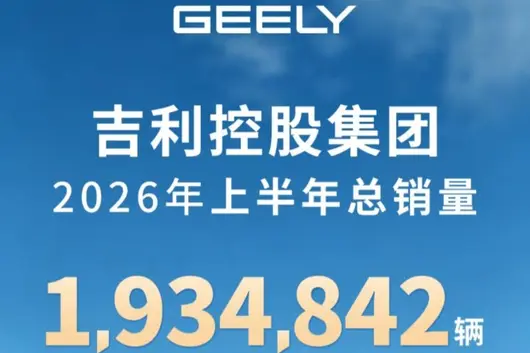
On July 15th, Geely Holding Group released the mid-year sales performance report: Total vehicle sales for the group from January to June reached 1.93 million units, setting a new high for the same period in history; among them, new energy vehicle sales reached 1.1 million units, a year-on-year increase of 10%, with the new energy penetration rate climbing to 56.9%. This means that for every 100 cars sold by Geely Holding Group in the first half of the year, nearly 57 were new energy vehicles, and the group as a whole has entered the harvest period of electrification scale.

As the core listed entity under Geely Holdings, Geely Auto's sales reached 1.43 million units in the first half of the year, with new energy sales (including Geely, Lynk & Co, Zeekr) at 799,000 units, a year-on-year increase of 10%, and a new energy penetration rate of 56%. Sales data from the group to the core brand outline a traditional Chinese automaker that started with fuel vehicles, and in the background of intensifying industry stock competition, how to complete a structural transformation through a multi-brand matrix and global layout.
Multi-brand matrix synergy, new energy becomes the main axis of growth
Geely's ability to refresh records in the first half of the year was not pulled by a single brand, but the result of synergy between the three major brands Geely, Lynk & Co, and Zeekr in different sub-segments.
The Geely brand, which targets the mainstream home market, achieved cumulative sales of 1,100,373 units in the first half, of which the China Star series sold 580,580 units, continuing to firmly rank among the top sales of domestic brand fuel vehicles, playing the role of a "ballast" for the basic market. What truly drives the volume increase in new energy is Geely Galaxy—cumulative deliveries in the first half reached 519,793 units, with single-month sales in June at 108,206 units, a year-on-year increase of 20% and a month-on-month increase of 32%. The Star Wish under the Galaxy brand broke 50,000 units in a single month, with cumulative sales since launch exceeding 750,000 units, becoming the core product in Geely's new energy volume-selling camp.

Lynk & Co, positioned in the mid-to-high-end hybrid market, achieved cumulative sales of 144,215 units in the first half, with new energy vehicle sales at 93,597 units, and the proportion of new energy products reaching 65%, stabilizing the mid-to-high-end hybrid sub-market by relying on the EM-P hybrid family promoted by the simultaneous launch of three car models. Zeekr continued its strong performance on the high-end luxury track, delivering 178,370 units in the first half, a significant year-on-year increase of 97%; single-month deliveries in June were 35,169 units, a year-on-year increase of 111%, achieving consecutive five-month year-on-year and month-on-month double growth, with global cumulative deliveries officially breaking through 820,000 units.
From the perspective of the group as a whole, June single-month Geely Auto new energy sales reached 161,449 units, a year-on-year increase of 32% and a month-on-month increase of 21%, with new energy sales proportion of the group's total sales exceeding 67%—equivalent to nearly 7 out of every 10 Geely new cars sold being new energy vehicles. This structural change marks that Geely's "oil and electricity simultaneous promotion" transformation rhythm has entered a new stage dominated by new energy.
It is worth noting that Geely's new energy transformation is not at the expense of abandoning fuel vehicles. The China Star series still maintains strong competitiveness in the fuel vehicle market, and this "fuel ballast, new energy volume" dual-track strategy enabled Geely to hold its basic market share in the domestic auto market in the first half. Data from the China Passenger Car Association shows that in the ranking of narrow passenger vehicle manufacturer retail sales from January to June, Geely ranked first with 1.021 million units and an 11.7% share, being the only domestic brand to break the million-unit mark in the first half.
Overseas business leaps, globalization enters harvest period
If new energy penetration rate is the most eye-catching internal change in Geely's first half, then the explosion of export business is its most prominent external highlight.
Data shows that Geely Auto's first-half overseas export sales reached 474,228 units, a year-on-year increase of 158%—this number has already exceeded Geely's total export volume for the full year of 2025. June single-month overseas export sales broke the 100,000 unit threshold for the first time, reaching 102,874 units, with a year-on-year increase of 157% and a month-on-month increase of 21%, achieving consecutive six-month year-on-year and month-on-month double growth.
A more critical change lies in the export structure. In the first half, Geely's new energy product export sales were 277,189 units, surging 585% year-on-year, accounting for 58% of the total export volume. This means Geely's main overseas products have completed the switch from traditional fuel vehicles to new energy vehicles, with new energy products gradually becoming the core driving force for overseas market growth.
Geely Holding Group's overall global layout also landed at multiple points in the first half: Geely signed Swiss dealers to strengthen the European market, Lynk & Co 900 launched in Vietnam and Qatar, Geely Xingyuan EX2 began local production in Brazil, Binyue Cool launched in South Africa; Zeekr topped the Malaysia luxury pure electric sales list, 007 GT has launched in 16 European countries, flagship model Zeekr 9X plans to go to the Middle East in Q3, and will subsequently expand into US/Europe and Central Asian markets.
Overseas high-end brands also performed steadily. Volvo Cars first-half global sales were 325,000 units, with new energy sales at 161,000 units, a year-on-year increase of 3.8%, with new energy penetration rate reaching 50%, and pure electric vehicle deliveries growing for 9 consecutive months. Polestar first-half sales were 30,400 units, achieving sales breakthroughs in markets such as the UK, Germany, and South Korea, setting a new high for the brand at the same period in history. In the Southeast Asia and commercial vehicle sector, Proton first-half sales were 100,300 units, a year-on-year increase of 39.1%, achieving the best half-year performance since 2011; Farizon New Energy Commercial Vehicles first-half sales were 88,000 units, a year-on-year increase of 41.3%, with overseas export sales ranking at the forefront of the new energy commercial vehicle industry.
Geely Group's performance in the first half of the year can be called bright, but in the automotive market where variables are ever-present, its challenges for the second half of the year remain. Intensifying domestic car market stock competition and unrelenting price war pressure, Geely brand and Lynk & Co brand first-half cumulative sales declined year-on-year by 5% and 6% respectively, indicating that the fuel vehicle basic market still faces contraction pressure; and in the overseas market, geopolitical tensions, trade barriers, and the difficulty of localization operations will also rise synchronously with the expansion of export scale. Whether Geely can continue its growth momentum in the second half depends on the volume pace of Galaxy and Zeekr, the development progress of Middle East and European markets, and the balancing ability of resource allocation between fuel vehicles and new energy.

[CNMO Tech News] July 16, @NEVData released observation data on the Southeast Asia automotive market: Chinese brand market share in the six ASEAN countries (Indonesia, Malaysia, Thailand, Vietnam, Philippines, Singapore) exceeds 60% in the new energy sector. Among them, Indonesia reached as high as 91%.

Chinese New Energy Vehicles
According to statistics, cumulative sales of passenger cars and pickups in the six ASEAN countries in the first half of the year totaled 1.9246 million, up 7.2% year-on-year. Specifically for June data, retail sales of passenger cars and pickups were 332,700, up 9.7% year-on-year. Indonesia (passenger cars, same for subsequent mentions) sales were 74,507 units, up 10.5% year-on-year; Malaysia sales were 72,943 units, up 23.1% year-on-year; Thailand sales were 68,912 units, up 11.2% year-on-year; Vietnam and Philippines sold 51,366 and 38,124 units respectively, up 6.4% and 4.1% year-on-year; Singapore was the only country with sales declining year-on-year, selling 6,948 units, down 1.8%.

Data shows, June NEV penetration rates varied significantly across countries. Singapore ranked first with a penetration rate of 66.4%, up 19.2% year-on-year; Vietnam and Thailand ranked second and third with penetration rates of 41% and 30.3% respectively, up 94.7% and 31% year-on-year. Although Indonesia and Malaysia penetration rates were under 20%, they surged 78% and 122% year-on-year. The Philippines lagged severely due to a lack of charging infrastructure, with a penetration rate of only 2.1%. These market increments were mainly contributed by Chinese new energy vehicle brands.
In the new energy sector, Chinese brand market share exceeds 60%. Among them, Malaysia reached 62%, Thailand 78%, Indonesia 91%. However, in the overall market, Japanese brands still lead with 68%. However, the overall market share of Chinese brands increased by 6.2 percentage points year-on-year (reaching 13.7%), reaching 17.3% in Thailand, surpassing Japanese and South Korean brands to become the largest group.
On July 8, the 100,000th Avatr 07 vehicle rolled off the production line at Chongqing Digital Intelligence Factory. This milestone model is the right-hand drive overseas version, marking the main model's leap from a domestic blockbuster to a global product. With a delivery scale of 100,000 units, simultaneous overseas layout, and dual-model matrix implementation, this reflects three clear industrialization upgrade paths for China's high-end new energy vehicle industry—manufacturing, technology, and globalization—providing a replicable development model for the industry.
From the dimension of manufacturing industrialization, the core confidence behind the 100,000 units comes from the full-domain intelligent factory system. Currently, the domestic new energy market has entered a stage of stock competition, where price wars compress profits, making stable, low-cost, and high-quality mass production capabilities the bottom line for brand survival. The Chongqing Digital Intelligence Factory supporting Avatr 07 production is the world's first full-domain 5G+AI flexible whole vehicle manufacturing base, integrating over 40 cutting-edge technologies such as digital twins, full-process automated welding, and digital quality control. Annual production capacity can stably support the synchronous production of multiple models, with a supporting capability of up to 200 units per year, achieving a balance between personalized customization and mass production.

This intelligent manufacturing system co-built by Changan, Huawei, and China Unicom solves the challenge of mass production consistency for high-end models. In the past, high-end new energy vehicles commonly faced the pain points of low-volume, hard-to-mass-produce customization. Avatr connects the R&D, production, and quality control full-link through a three-party collaborative supply chain, rapidly transforming frontier laboratory technologies into standardized products. The stable delivery of 100,000 units proves that domestic high-end new energy has shaken off the label of "niche concept cars", completed industrialization landing, and moved away from the fragile model relying on a single blockbuster for short-term volume.
Secondly, technological collaborative industrialization is the core competitiveness of Avatr 07 to secure its position in the 200,000-300,000 RMB high-end track. Unlike the single automaker self-research model, Avatr integrates core resources from the three-party industry chain, forming a complete technical closed loop: Huawei provides Kunqun ADS 4 intelligent driving and HarmonyOS Cockpit, CATL outputs Shenxing Supercharging battery, Changan is responsible for the whole vehicle chassis and whole vehicle manufacturing. The six major core technologies are fully independently controllable, with no risk of core components being externally choked off.
In the current era of homogeneous industry configurations, a complete industry chain collaborative system builds differentiated barriers. The model has successively won the USA IDA and German iF International Design Awards; its original appearance design possesses global aesthetic adaptability; 90-second fast recharging, full-scenario advanced intelligent driving, and extended-range pure electric dual powertrain solutions cater to both domestic commuting and overseas diverse road condition needs. This integrated collaborative model of whole vehicle, intelligence, and battery/electric/powertrain represents a new division of labor for China's new energy industry: automakers coordinate and integrate, tech companies output intelligent software and hardware, battery enterprises provide energy solutions. The industry chain functions in its respective role with deep binding, marking a significant sign of industry maturity.
Third, global industrialization layout opens up new growth space for the industry, and the right-hand drive milestone model releases a clear industry signal. The domestic market volume has peaked, going overseas has become a mandatory question for all new energy automakers, while industrial overseas expansion has long moved away from simple vehicle exports, turning to integrated layout of products, capacity, and channels. The 100,000th vehicle rolled off the line this time is the right-hand drive model, specifically adapting to massive right-hand drive markets such as Southeast Asia, the Middle East, and the Commonwealth. It is not simply changing the steering wheel layout, but achieving full-dimension localization adaptation from chassis calibration, infotainment interaction, to safety regulations.

Currently, Avatr products have landed in markets such as Singapore, Thailand, UAE, etc., with channels covering 43 countries. Planned to enter Europe in 2026, covering over 110 countries by 2030. Compared to the scattered exports of most automakers, Avatr completed the synchronous R&D and mass production of right-hand drive models in advance, directly connecting domestic and overseas dual-market supply at the manufacturing end. Relying on mature domestic production capacity bases to radiate globally, avoiding high investments in building factories overseas, using local super factories as global production capacity pivots. This is a more cost-effective industrialization overseas route.
At the same time, Avatr 07L has simultaneously started pre-sale. 07 and 07L form a dual-car matrix, perfecting the coverage of segmented markets, completing the industrial iteration from a single blockbuster to a product matrix. The 100,000 units sales of a single model is just the starting point. Dual-model parallelism can dilute R&D, production, and supply chain costs, further amplifying scale advantages, and hedging against market cycle fluctuations.
Against the backdrop of the overall transformation of the automotive industry, the rolling off of the line of 100,000 Avatr 07 right-hand drive whole vehicles is not just a brand milestone, but also a microcosm of the maturity of the domestic new energy industry. Intelligent manufacturing builds a solid mass production base, the whole industry chain collaboration creates technical barriers, and the simultaneous layout of domestic and overseas dual markets expands the growth ceiling. The three industrialization paths support each other, allowing Chinese high-end electric vehicles to break free from low-price involution and truly possess the strength to compete globally with international luxury brands. In the future, as domestic automakers continuously deepen industry chain integration and perfect global product layout, the new energy vehicle industry will complete the qualitative change from scale leadership to all-around leadership in technology, manufacturing, and brand.

July 8, BYD's 17 millionth new energy vehicle rolled off the line at the Xi'an factory. From 16 million to 17 million, it took less than 3 months. Average daily production exceeds 12,000 units.
 17 million units, what concept is this? Over a century of global automotive history, no new energy vehicle manufacturer has ever reached this scale. More crucially, from the first million taking 13 years to now adding another million in just over 80 days—this acceleration curve is truly staggering. This is not just a leap in production and sales data, but also creates a new benchmark for the development of the global new energy industry.
Many think BYD just rode the wave of new energy policy benefits. But can policy benefits explain the production ramp-up of a million units in three months? Can it explain the overseas growth rate of 789,000 units in half a year, up 68% year-on-year? Can it explain a Chinese carmaker beginning to export technical standards to the globe?
Obviously not.
What truly supports this number of 17 million units are three core capabilities that are hard for others to replicate.
First: Full-stack independent research, from "being bottlenecked" to "holding in hand"BYD's technology route has never been single-point breakthroughs, but rather full-stack independent research.
In March 2026, the second-generation Blade Battery and Flash Charging technology were released. Fully charged in 5 minutes at room temperature, 9 minutes full, plus only 3 minutes at minus 30 degrees — overcoming the "slow charging" and "cold weather charging difficulty" two major global problems in one go.

In May, China's first 4nm process smart driving chip "Xuanji A3" mass-produced, three-chip collaborative computing power exceeds 2,100 TOPS. Same month, BYD took the lead in promising to guarantee city pilot safety for 1 year, all series available with Sky's Eye B Laser version.
From battery, motor, electronic control to chips, smart driving, chassis, BYD achieved full-link independent controllability from upstream lithium mine resources to downstream complete vehicles. Core link independent R&D and production rate exceeds 90%.
Others build cars by assembling supply chains, BYD builds cars from mine to complete vehicle one-stop. Once this system runs smoothly, it is a moat others cannot copy, and also the bottom-line support for BYD pushing the new energy industry to a new height.
Good technology is just a premise. What makes BYD truly amazing is that — these core technologies are not used for "showing off skills". Sky's Eye standard equipment across series, city pilot and smart parking "safety double guarantee", making good technology accessible to everyone. The 17 million units data proves that domestic suppliers already possess global competitiveness in automotive-grade certification, yield control, and cost optimization.
Technology is not used for enshrinement, but for popularization. This is what defining standards should look like.
Second: Vertical integration, from "subject to others" to "self-sufficient"BYD is not only a complete vehicle manufacturer, but also a vertical integrated supply chain giant. Its subsidiaries such as FinDreams Battery, FinDreams Power, BYD Semiconductor, etc. constitute a complete domestic Tier1 camp.
 What is the direct result brought by this model? Core component costs are more than 33% lower than the industry average.
In the early days of global chip shortage and raw material price increase cycles, peers reduced production and stopped work, BYD production capacity was almost unimpacted. When others were bottlenecked by supply chains, BYD quietly built cars. When others were still grabbing chips, BYD had already designed its own chips.
17 million units rolled off the line is not only a victory for the complete vehicle factory, but also a production volume landmark for the domestic supply chain. From second-generation Blade Battery to Sky's Eye smart driving, autonomous controllability and mass production delivery capability of core components have become the industry moat. This fully industry chain autonomous controllability system is itself a new height that the new energy industry can reach.
This model allows cutting-edge technology to quickly trickle down to all series models, no need for high-end cars to exclusively occupy core configurations. Seal 08 sells from 196,900 starting, but equipped with DiSus-A, rear-wheel steering, 905km range, flash charging, smart driving double guarantee — 200,000 RMB car, million-level configuration.
This is not a price war, this is a system war.
Third: Globalization, from "product going overseas" to "standards going overseas"In the first half of 2026, BYD sold 789,000 units overseas, up 68% year-on-year, overseas sales proportion exceeds 43%. June single month exports 175,300 units, creating a new historic high.
But more noteworthy than sales volume is the layout. Thailand, Brazil factories already mass-produced, Hungary, Indonesia factories to start production in 2026. From Southeast Asia to South America to Europe, a localized manufacturing system covering Asia, Europe, and Africa is taking shape.
More crucially — BYD is simultaneously exporting charging standards. Scale implementation of Flash Charging stations overseas at the end of 2026, from "Flash Charge China" to "Flash Charge Planet". Domestic has already built 7,018 Flash Charging stations, covering 325 cities, end of year target 20,000 stations.
Before it was Chinese cars chasing others' standards. Now it is others considering whether to connect to China's charging standards. This role shift is the most worthy of discussion behind 17 million units.
Final Thoughts
Xi'an is the place where BYD's car building dream started. 2003 first car rolled off the line, 2008 global first plug-in hybrid born, to today 17 millionth new energy vehicle rolls out from here.

17 million units is not just cold production capacity numbers, but also a landmark node for Chinese carmakers turning from policy followers to technology definers. From the depth of technology self-research, to the breadth of vertical integration, to the speed of global layout, BYD used a complete system capability to turn 17 million units from numbers into confidence, pushing the Chinese new energy industry to an unprecedented new height.
This is not only a milestone in production and sales volume, but also a new starting point for a Chinese carmaker to export standards and rules to the globe.
#BYD17MillionthNewEnergyVehicleRolledOffLine#
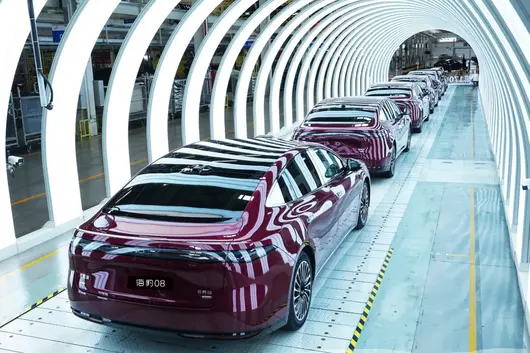
In the first half of 2026, cumulative retail of passenger cars in China's automotive market reached approximately 8.75 million units, a year-on-year decline of about 20%; meanwhile, new energy penetration rate broke 63% in May to set a historical high, and climbed further to about 63.6% in June.
The overall market downturn and structural upgrade running in parallel can be said to be the theme of this half-year; against this backdrop, true new energy top players are beginning to surface.
BYD, with 1.7774 million units in sales, continues to top the sales list; Geely Auto follows closely, with cumulative sales of 1.423 million units in the first half of the year, setting a new historical high for the same period, with the two companies combined taking about 38.7% of the new energy market share in China. More than one-third of new energy vehicles are either made by BYD or Geely.

At this point, the "Two Supers and Many Strong Powers" new energy market structure has been formed, and the top two automakers are widening the gap with the followers. Many automakers have fought in the new energy market for so many years; the elimination round is approaching its end, the market share of domestic brands has exceeded 73%, and the "Hegemony War" of China's new energy market has basically been locked between these two companies.
BYD and Geely are seizing territory with different paths respectively; one is a strong hand at integrating the industry chain, and the other is a skilled hand at organizing the system. In this "Hegemony Battle", will it ultimately end with two strong heroes standing together, or will someone seize power at once?
# BYD and Geely, Leaving Followers Far Behind? #
Stretching the timeline to 2025, the basic outline of China's new energy vehicle market structure was already apparent.
BYD, with 4,602,436 units of new energy vehicle sales for the full year of 2025, a year-on-year growth of 7.73%, among which pure electric vehicle sales were 2.2567 million units, surpassing Tesla for the first time to become the annual sales champion of pure electric vehicles globally. The domestic new energy vehicle market share exceeded 35%, and the full-year sales of 2025 entered the global automotive group sales top five for the first time.

Geely, with 3.0246 million units in sales for the full year of 2025, breaking 3 million units for the first time, up 39% year-on-year. New energy sales exceeded 1.68 million units, up 90% year-on-year. Full-year revenue was 345.2 billion yuan, up 25% year-on-year. Core net attributable profit was 14.41 billion yuan, up 36% year-on-year.

Entering the first half of 2026, BYD reached 1.7774 million units (down 15.9% year-on-year), Geely 1.423 million units (up about 1% year-on-year). Still the top two in domestic sales. From the market share perspective, the China new energy passenger car market in the first half of 2026 was about 5.5 million units. BYD's share was about 32.3%, Geely's share was about 14.5%.
One could say that in China's new energy market, these two brands took nearly half of the market. You should know that six years ago, Geely's new energy proportion was in single digits, and BYD was far from forming the scale it has today. At this point, the pattern of China's new energy market has basically been set, with multi-brand chaos evolving into "Two Giants and Multiple Strong Contenders".
# Scale and System: Which is the Key to Seizing Market Hegemony? #
Why is it BYD and Geely that can form dominance in China's many new energy brand markets with so many cars, plus policy support?
Let's look at BYD first. Currently, its biggest moat is its massive scale. This scale not only protects itself but also blocks the invasion of competitors. So where does this scale come from?
At the beginning of the development of China's new energy market, it could be said to be a complete blue ocean. At that time, even large global automotive groups dared not easily get involved. After all, this is a fundamental energy transition. Entering this market means that the profit model, production and manufacturing system, and product definition model of the previous fuel car era must be completely started from scratch. Not only must time costs be paid, but an economic account must also be calculated.
But in China, there is an undeniable point, which is the support of policy direction. BYD is able to become the current hegemon of the new energy industry because it also bet on the direction of policy. Under the decision to go ALL IN on new energy, it successfully became the first Chinese automaker to conquer the new energy market, thereby helping itself quickly take a large share of the market.
On top of this, through the path of vertical integration, from lithium mining to battery manufacturing, from chip design to vehicle production, BYD itself has built a complete industry chain closed loop.

Its advantage lies in that even if the industry's overall profit margin is only 3.2% now, BYD can still press down costs by self-producing batteries, self-producing chips, and self-producing electronic controls. In 2025, why BYD was able to reach a 35% market share in the domestic market, it relied on "others cutting prices, and I can still make money".
So at this time, this first-mover advantage combined with cost control can give it the initiative in market competition, not being led by the nose by other opponents, but making itself the person who moves first. When grasping the initiative, it will be more at ease in the market, thereby quickly forming scale expansion.
But historical experience shows that when scale expansion reaches a certain extent, it will naturally slow down or even decline. Even as strong as BYD has not escaped this law. In the first half of this year, its sales saw a decline, and the market sales of main models such as Song PLUS, Qin PLUS, and Seagull saw a year-on-year decline.
When the price war dividend has fully receded, simple price strategies are difficult to form differentiation barriers. Wang Chuanfu admitted at the shareholders' meeting: Current technology leadership is not as good as in previous years, the market wow factor of technological results has decreased, and industry homogenization characteristics are becoming increasingly obvious.
For this, in June 2026, BYD launched the largest scale organizational reform of its vehicle business since its inception, reorganizing the four brands Dynasty, Ocean, Denza, and Fang Cheng Bao into independent operating units, implementing independent accounting and bearing their own profit and loss. The R&D system was reconstructed into "Group Technology Middle Platform + Brand Research Institute". The purpose is very clear: after achieving expansion, gradually shifting from "scale driven" to "profit and efficiency driven".
Let's look at Geely. Its play is completely different from BYD. It does not build a wall with one industry chain, but uses a set of system structure to deploy.
The foundation of such a system is built under Li Shufu's "One Geely" strategy. Closing redundant entities, integrating R&D, procurement, and intelligent resources, the Qianli Haohan Intelligent Driving System is reused across brands. This unified technology base, relying on brands to form product differentiation, is forming the late-mover advantage of traditional large factories against rapid iteration and price wars.
Specifically, Geely Galaxy undertakes the task of high-volume market mainstream new energy vehicles, with cumulative sales of 519,793 units in the first half of the year; the China Star Series stabilizes the fuel car base, with cumulative sales of 580,580 units in the first half of the year; Zeekr raises brand premium with an average price of 350,000 yuan, delivering 178,300 units in the first half of the year, up 97% year-on-year; Lynk & Co covers both high-end new energy and overseas expansion.
This division of labor where each fulfills its duty allows Geely to maintain the healthiness of its own brand development in the background of the increasingly fierce price war in China. Reflected in the data is that the core net profit per vehicle in the first quarter reached 6,429 yuan, up 30% year-on-year, with the gross margin rising to 17.5%. In the context of the industry generally declining by over 20%, this performance has a certain persuasiveness.
And Geely's product layout is quite targeted. It seized the most high-volume market from 100,000 to 200,000 yuan, relying on the dense coverage of products and the full coverage of power types. This point has a strong effect on improving consumer awareness. Among them, Geely Star Wish one car contributed 34.6% of group sales.

At the same time, the overseas market is becoming Geely's second growth curve. Exports in the first half of the year were 474,200 units, up 158% year-on-year, already exceeding the total export volume of the whole year of 2025; new energy product exports were 277,200 units, up 585% year-on-year. Exports in June broke 100,000 units for the first time. Currently, Geely has raised export targets to 1 million units twice consecutively.
Combining the above content, we can see that BYD's scale gives it enough exposure in the market, and this scale effect can also bring a certain positive impact to the brand. Meanwhile, facing the current bottleneck of scale development to a certain extent, BYD is also starting to delegate authority to consider efficiency issues, seeking to allow each sub-brand to respond to the market more flexibly.
Under the background of Geely's "One Geely" strategy, scattered resources have been concentrated again. It carries out targeted layout of different markets according to the different positioning of its sub-brands. While reducing internal friction, it is also easier and more accurate for consumer groups to see Geely products in the corresponding market, thereby driving sales growth.
Although these two paths are different, the purpose is one, which is to improve its own competitiveness in the existing market. The Chinese automotive market has long entered a saturation status. So at this time, being able to live better here relies on scale and system capabilities. This point, through the examples of BYD and Geely, can verify the correctness of this development model. Although they are in a competitive relationship in the market, their development models start from different paths and end at the same destination.
Except for the domestic market, the overseas market is becoming a factor that determines the pattern of the two strong ones. Interestingly, BYD and Geely, the sales champions who took different routes in the domestic market, still have two different paths in their overseas layout.

BYD took the heavy asset wholly-owned route, building its own factories in Brazil, Thailand, Hungary, etc., intending to maintain technical and management autonomy. The Thailand factory is the only overseas full-process factory currently in production. The Hungary factory will be put into production in Q2 2026. "Local production + domestic exports" jointly improve delivery flexibility.
Geely took the light asset synergy route, cutting into local manufacturing and channels by leveraging existing cooperation networks such as Volvo, Proton, Renault, etc. Acquiring Ford's Valencia plant production line in Spain, signing Swiss distributor Emil Frey. This model avoids the heavy asset burden of large-scale self-built factories.
The two routes have pros and cons. BYD's wholly-owned model can守住 technical sovereignty, but the capital pressure is huge and implementation is slow; Geely's synergy model can quickly pave the way, but it has a high dependence on cooperation partners and weak brand control. From the data in the first half of 2026, Geely's export growth (157%) was higher than BYD's (70%), but BYD's overseas sales absolute value (789,400 units) still leads Geely (474,200 units).
Subsequently, the performance of these two giants in the overseas market may become a key factor affecting their overall brand development. Under the background of the EU IAA Act locking foreign shareholding at 49%, Geely's joint venture synergy model may face lower policy compliance costs, while BYD's wholly-owned route may face greater institutional barriers.
# Top Structure Established: Can Followers Replicate the Success Path? #
When the market has a successful template, naturally others are like copying. So can BYD and Geely's development model be replicated?
BYD's vertical integration is built on more than twenty years of deep cultivation in the industry. Starting from batteries to vehicle manufacturing, this is a road that cannot be done quickly. CATL is a battery giant, but it doesn't make cars; Nio and Li Auto are new car-making forces, but they don't produce batteries. To keep the whole industry chain in hand, it requires time, capital, and strategic resolve. All three are indispensable.
Geely's systematic capability is built on the long-term accumulation of multi-brand acquisition and integration. Volvo, Proton, Lotus, Polestar, etc., these brands were not bought overnight; it is the result of a ten-plus-year continuous layout. Without this "brand pool", the "One Geely" strategy loses the foundation of synergy. New entrants only have one or two brands, and traditional automakers mostly have only one main brand. None have the conditions for Geely's "multi-brand matrix synergy".

So, saying it is that these two roads, BYD and Geely can walk, does not mean others can too. So is there another way to squeeze into the camp of China's new energy "Strong Ones"? Let's see how subsequent followers respond.
Currently, relying on brand premium and single-model efficiency are the general tactics of most market followers. Among them, Tesla and Xiaomi are considered two representatives.
From the brand statistical scope, the new energy brands ranked behind BYD and Geely are Tesla. In the first half of 2026, Tesla's China domestic market retail sales were approximately 325,000 units. If referring to the total delivery volume of the Shanghai Gigafactory (including exports) in the first half of the year, it was 468,000 units.
But it is worth noting that Tesla's product portfolio has not been updated for a long time. Two flagship models, Model S and Model X, were discontinued in the first half of this year. The main models currently on sale are Model 3 and Model Y. So what is the reason boosting its sales? The answer is very simple, it is its brand influence.

If switching to other brands, or saying the majority of domestic brands, having only two models in the market is obviously not enough competitiveness. Otherwise, they would not deploy numerous models in the domestic market. You should know that in the first half of this year alone, there were over 500 new and upgraded models entering the Chinese automotive market. The main purpose is to exchange consumer attention and sales through short time and high frequency exposure.
But Tesla's advantage lies in its brand influence. One is entry early, counting as the absolute pioneer of the electric market, and having its own energy replenishment system. Plus, the personal charm of the brand founder adds to it. Many consumers, if not considering price and other factors, will take it as one of the primary or main choices.
Speaking of Xiaomi, this can actually be counted as a sample of high efficiency for a single model. In the first half of 2026, Xiaomi Auto cumulative deliveries exceeded 180,000 units, basically reaching a monthly average of 30,000. It relied on one car in its first year, and now it only has two models on sale.
If you put it together with BYD, you can see what level its per-vehicle efficiency reaches. Two cars with 180,000 sales, compared to 1.196 million for 66 models, its per-vehicle average sales are far higher than most other brands on the market, basically reaching more than 3 times the industry average.
Why are these two paths worth being discussed separately? The cases of Tesla and Xiaomi answer the question "Can BYD and Geely's paths be replicated".
BYD's scale requires twenty years of industry chain deep cultivation; Geely's system requires ten-plus years of brand acquisition integration. These two things, other brands can almost not replicate. So if other brands want to gain presence in the market, they must have other differentiation advantages, relying on brands, or relying on their own ecosystems, or starting from other ways.

And there is one more point, relative to scale and system which are barriers that won't be easily broken, other methods may all have a certain uncertainty.
For example, Tesla's brand influence. Tesla's domestic retail sales in the first quarter of 2026 declined by 16.2% year-on-year. In January, Model Y even fell to 20th place in the retail ranking. Its pure electric retail market share in April of this year was only 3.06%. All of this explains one issue, that is, brand influence can be diluted by competitors.
Then there is Xiaomi's per-vehicle efficiency. If market acceptance of products is acceptable, then per-vehicle extreme efficiency is an advantage. If per-vehicle appeal in the market declines, then it is a serious blow to the brand, and it may even appear that one car decides life or death.
So, the "Hegemony" established by BYD and Geely is the effect of the superposition of factors such as time. In the short term, it is like ascending to heaven to replicate this brand development path. So the endgame of China's new energy market later will not be a "BYD + Geely" duopoly, but the top structure they are in has solidified. This barrier will not be easily broken by latecomers. On the contrary, these giants may "absorb" small and medium brands that are hard to sustain in the market.
# One Dominant Leader or Two Tigers Coexisting? #
As the saying goes, one mountain cannot hold two tigers. So will this point be reflected in the "Hegemony" contest between BYD and Geely?
In the short term, BYD appeared with teething pains after scale expansion. Domestic sales declined, and organizational reform just started, but its trump cards are relatively still thick enough. After all, it is the world's largest new energy capacity, has a complete industry chain layout, and has the largest user base in the current new energy field. If organizational reform can activate the combat power of respective brands, BYD's scale advantage still has hope for expansion.
In the medium to long term, Geely's growth momentum may have a longer sustainable period. Per-vehicle net profit hit a new high in the first half of the year, overseas exports surged, and new energy penetration rate steadily improved. The complementary structure of major brands gives it a buffer at any single market fluctuation.
At the same time, whoever can turn the overseas market from increment to profit, can get the hope of leading opponents. BYD's wholly-owned model has verified feasibility in Brazil and Thailand; Geely's synergy model is accelerating landing in Europe. Both roads can be passed, but which road can be walked better depends on who can find a better balance between localization operations, brand construction, and cost control.
Objectively speaking, the endgame of China's new energy market, one dominating is difficult, the probability of two strong heroes standing together is obviously higher. This point has already been confirmed in many markets globally. Regardless of BYD's scale or Geely's system, these two weapons can eliminate, but a more important point in the market is who can be more flexible. At this time, whether it is BYD's organizational adjustment or Geely's integration concept, they are all the adaptive answers produced to cope with current problems.
As for the final hegemony contest, whoever can take the lead in finding that key balance point between scale expansion and efficiency, product coverage and technology focus, development speed and product quality, is the one who may find the opportunity to lead opponents in the tense hegemony battle.
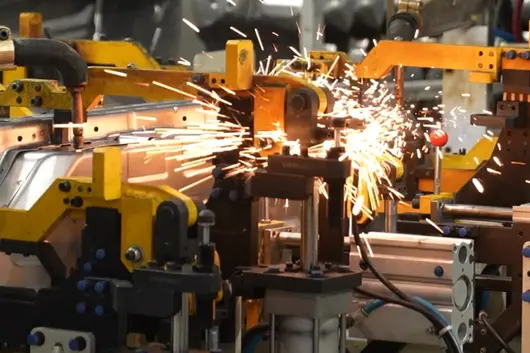
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
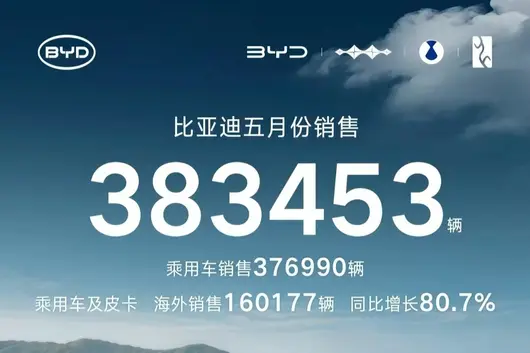
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
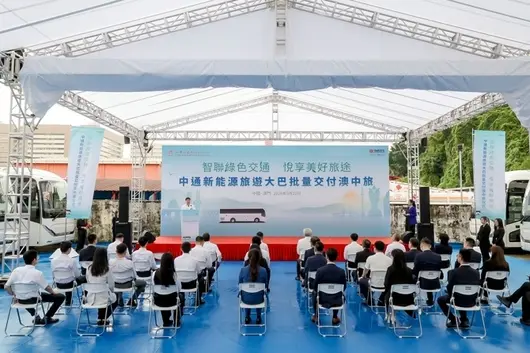
Connecting smart green transportation, enjoying a wonderful journey! On May 22, the ceremony for the batch delivery of Zhongtong New Energy Tourist Coaches to Macao China Travel Service Co., Ltd. under the Southlight Group (hereinafter referred to as "Southlight Macao Travel") was successfully held in Macao. Wang Zhijian, Party Secretary and Chairman of Shandong Heavy Industry Group, and Fu Jianguo, Chairman of Southlight Group, attended the event and cut the ribbon.

The delivery of this batch of range-extended new energy coaches is a landmark achievement of the deep collaboration between Zhongtong Bus and Macao's culture, tourism, and transportation sectors to jointly build a green and low-carbon Greater Bay Area. It is also a vivid practice of Zhongtong Bus using core technologies to create green application cases for the global high-end market and promoting the high-quality development of global green transportation.

Deeply Cultivating Core New Energy Technologies
Empowering Macao's Low-Carbon Transportation Development
As a high-end window for China's opening up and an important node city of the Greater Bay Area, Macao sets strict standards for the safety, stability, comfort, and regional environmental adaptability of passenger vehicles. It is a "high-end trial field" to test the smart manufacturing strength of new energy coaches.

Southlight Macao Travel is Macao's largest land passenger transport service provider. As a leading enterprise in Macao's tourism industry and a core operating entity for transportation, culture, and tourism, it has deeply cultivated Macao's entire industry chain of "eating, living, traveling, entertainment, sightseeing, and shopping". It is the backbone force of Macao's public transportation and cultural tourism passenger transport services.
To actively respond to the Macao Special Administrative Government's "Macau Long-term Decarbonization Strategy" and "Green Transition of Land Transportation" deployment, and implement the national "Dual Carbon" goals, in recent years, Southlight Macao Travel has comprehensively launched the new energy upgrade of its passenger fleet, accelerating the construction of a green, smart, and efficient modern passenger transport system. Zhongtong Bus has become its core partner for new energy development.

Zhongtong Bus has deepened its focus on new energy technology R&D and possesses the capability for full-series new energy coach product solutions, including pure electric, hybrid, and range-extended technologies. At the same time, with deep exploration of the global market, Zhongtong Bus has accumulated a massive amount of complex road conditions and multi-scenario operation data. Technology iterations continue to lead the industry.
Relying on hardcore technology and extreme adaptability, Zhongtong Bus's cooperation with Southlight Group covers cross-border, urban, and tourist passenger transport fields. The total cooperation scale reached 600 units, effectively boosting the quality improvement and upgrade of the local transportation industry.
Deeply Adapting to Macao Scenarios
Customizing to Build Green Travel Benchmarks
Macao has a special regional environment, complex road conditions, congested traffic, and limited charging resources, facing challenges in new energy transition. Based on a deep understanding of Macao's local operation scenarios, Zhongtong Bus has tailored a range-extended product solution for the local area.

Zhongtong range-extended coaches combine the dual advantages of pure electric models (quiet and comfortable, zero idling pollution) and fuel vehicle models (worry-free range, convenient refueling/recharging), precisely solving Macao's pain points of insufficient charging infrastructure, limited long-distance range, and high operating costs.
At the same time, the vehicle has undergone comprehensive upgrades in comfort details and intelligent safety. High-end configurations such as ergonomic seats and healthy environmental interior decoration improve the quality standards of cultural tourism passenger transport. Deeply optimized vehicle passability and turning radius make the vehicle better adapt to Macao's street conditions, improving operational flexibility and safety. At the same time, the vehicle integrates intelligent systems such as collision warning, automatic emergency braking, tire pressure monitoring, and driving assistance, achieving a dual upgrade in safety and intelligence.

Relying on refined customization and all-dimensional comfort experiences, Zhongtong range-extended coaches have now become the main model for Macao tourism transfer and commuter services. Delivered in three batches to the Macao market, it has won high recognition from passengers and users.
Leading the Global Green Track
Zhongtong Manufacturing Empowers Global High-Quality Development
Currently, the global carbon neutrality process is accelerating, and the green public transportation system is iterating and upgrading. New energy coaches have become a winning track for China's automotive industry development.

As a representative enterprise in China's coach industry, Zhongtong Bus closely follows the national "Going Global" strategy and the "Belt and Road" Initiative deployment. It takes new energy going overseas as a core development strategy, continuously increasing investment in overseas markets. Against diverse global market needs, it adheres to localization strategies, tailoring solutions for the market and enhancing product adaptability.
In Chile, over 1,000 Zhongtong pure electric coaches have become the backbone of local green public transportation; in Denmark, Zhongtong coaches on Bornholm Island have become a green landscape for the local area; in Dubai, Zhongtong Bus pioneered the entry of Chinese coach brands into the Dubai public transportation system; in Singapore, Zhongtong new energy coaches continue to provide innovative solutions for public transportation in Singapore's high-density cities...

Currently, more than 100,000 Zhongtong new energy coaches are roaming around the world. They not only bring green, intelligent, and efficient travel experiences to the world but also demonstrate the quality standards and innovative strength of Chinese manufacturing to the globe. With high-quality, highly intelligent, and low-energy-consumption green coach product solutions, they contribute Chinese wisdom and Chinese solutions to the development of global green transportation.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
Milestones Forge New Starting Points, Dual Brands Unite to Reach New Heights. In May, SAIC Group's cumulative production and sales exceeded 100 million, becoming China's first automobile group to enter the "100 Million Vehicle Club". As the core entity of SAIC Commercial Vehicles, SAIC Maxus sold 25,605 vehicles in total series, a year-on-year increase of 44%! Among them, overseas sales reached 12,392 vehicles, a year-on-year increase of 56%; SAIC Maxus New Energy vehicles sold 11,051 units, and "Dannai" sales reached 5,934 units, creating a new triple sales high! Yuejin New Energy accounted for over 67%, reaching a new high for the year; Domestic and overseas sales both exceeded 10,000 again, presenting hard-core results to celebrate the 100 million milestone and laying a solid foundation for high-quality development for the whole year.

[SAIC Commercial Vehicles Five Brands Relay Delivery, Celebrating the 100 Million User Moment Together]


[SAIC Maxus May Hot Sales]
Light Commercial Vehicles Doubled Year-on-Year, Dannai Reaches New High, "China's Top Light Commercial Vehicle Brand" Accelerates Leadership. In May, light van series sales reached 11,865 vehicles, up 56% year-on-year. The hit "Dannai" series, relying on "Big Battery + Small Extended Range" super extended range technology and full-scenario wealth creation capabilities, further consolidated its benchmark status in the new energy light van market, with this month's sales reaching a new high of 5,934 vehicles, a surge of 197% year-on-year. Dannai and New Tu series jointly cover user full-scenario wealth creation needs, "China's Top Light Commercial Vehicle Brand" accelerates leadership.

[Dannai Super Extended Range]
Pickup Steadily Climbs, Firmly Ranking First in Chinese High-End Pickup Exports. In May, pickup sales reached 7,223 vehicles, up 58% year-on-year. The domestic market continues to strengthen steadily, Maxus Pickup continues to cultivate high-end commercial, home leisure, off-road adventure, and other diverse scenarios. International competitiveness continues to lead, relying on the Star Stack Super Full-Stack Off-Road Platform technology strength, Maxus Pickup combines rugged performance with intelligent configuration, firmly ranking as China's Top High-End Pickup Export Brand, selling well in global mainstream markets.

[Brand New Interstellar L]
"Dark Horse" Yuejin New Energy Share Reaches 67%, Transformation Effect Leads the Industry. SAIC Maxus Yuejin light trucks are accelerating with new energy transformation, becoming a key growth pole in the 100 million user milestone. In May, Yuejin continued the strong momentum, achieving double growth in sales and new energy transformation — monthly sales reached 4,287 vehicles, up 41% year-on-year; among them, the sales share of new energy models reached 67%, a new high for the year, with sales volume surging 99% year-on-year! The transformation effect is significant, fully showing "Dark Horse" style. At the same time, channel and ecosystem layout continued to deepen: The national first ecosystem operation center Henan Zhian store grand opening, relying on Dannai T series new products, perfecting one-stop sales, service, and O&M system, precisely docking urban distribution logistics user needs.

[Yuejin Delivers Dannai T1 to SAIC Group Global 100,000,012th User "Didiron"]
Overseas Sales Reach New High, Globalization Map Continues to Expand. In May, SAIC Maxus overseas sales of 12,392 vehicles reached a new high, up 56% year-on-year, breaking the 10,000 vehicle threshold again. Southeast Asian market welcomed another key breakthrough: Stably ranked first in Singapore light commercial vehicle market share, and delivered eDeliver 5 (Domestic Dannai V1) to international logistics giant DHL, welcoming the Group's 100,000,009th user, nine years of cooperation footprint covering Europe, America, Asia, Oceania; At the same time, SAIC Maxus Yuejin brand reached cooperation with Vietnam's well-known commercial vehicle enterprise, empowering green logistics, accelerating China's intelligent manufacturing going global; T70 (Domestic Brand New Interstellar L) will land in Australia and Chile in the second half of the year, already secured over 800 intention orders before launch, highly sought after. Currently, SAIC Maxus products sell well in more than 100 countries and regions, light van and high-end pickup export volumes remain first in China, obtained global three five-star safety certifications, joined the preferred cooperation camp of global top enterprises, international influence continues to rise.

[eDeliver 5 (Domestic Dannai V1) Delivered to International Logistics Giant DHL]
Building Momentum for June: New Product Launch and 618 Promotion Relay, Continuously Lowering Car Purchase Threshold. Entering June, Maxus welcomes the all-new 2026 Model G50 launch, precisely entering family and commercial markets with "70,000 yuan-level super large super easy-to-use MPV", providing fuel and hybrid dual power. At the same time, Maxus 618 time-limited subsidy activity kicks off feverously: Dannai series time-limited rights price starting from 86,800 yuan, New Tu series time-limited fixed price starting from 86,800 yuan, pickup series launches 7-day free trial and trade-in subsidy up to 10,000 yuan, G50 elite version government-enterprise dual subsidy price starting from 80,800 yuan. Multiple benefits will further stimulate market heat, helping the brand continue the growth momentum.

[2026 Model Maxus G50]
Taking the group's production and sales exceeding 100 million as a new starting point, SAIC Maxus will anchor the vision of "Global Light Commercial Vehicle Leader", deepen dual brand synergy, accelerate new energy and globalization layout, persist in empowering global users with technology, products, and services, continuously leading the industry's high-quality development, and write a new chapter of globalization for China's intelligent manufacturing.
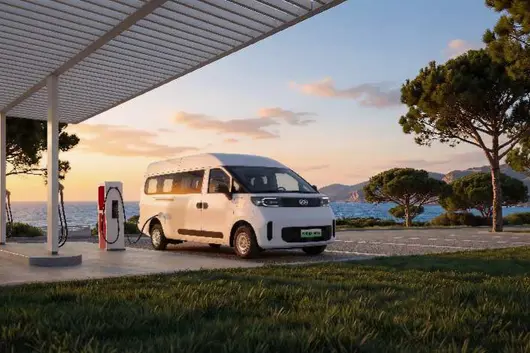
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.


