首頁Mazda Miata

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
車型概覽

長安銳程Plus 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講售價未落實前點樣先篩選,幫你用買家角度篩走唔適合嘅選擇。
售價仍待確認,買家可以先把佢放入候選名單,等價格落實後再同同級車逐項比較。
購車價格指南
長安銳程Plus 目前售價仍未清晰,較理性嘅做法係先睇版本、車身大小同動力形式,等價格落實後再決定值唔值得落訂。
如果有幾個版本可揀,可以先將 2024 1.5T 雙離合版(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 長安銳程Plus 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
渦輪增壓、4 個 汽缸、1494 mL 排量 嘅動力底子,重點係市區跟車夠唔夠順、高速巡航會唔會吃力。 188 Ps / 138 kW、300 N·m 嘅輸出,對滿載、上斜同超車都比單睇馬力數字更有意思。 車長 4800 mm、車闊 1825 mm、車高 1465 mm、軸距 2770 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。 濕式雙離合(DCT)、前置前駆 會影響起步順滑度、濕地穩定感同長途巡航性格。
優缺點分析
長安銳程Plus 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:動力輸出對高速同上斜更有底氣、空間同車身尺寸方便家庭買家預判實用性。
要留意嘅係,香港停車場同窄路使用要留意車身闊度、售價未清晰前唔應該太早用性價比落結論。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 長安銳程Plus 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「長安銳程 Plus 於香港的落地價大約係幾多?」簡單講,長安銳程 Plus 於香港落地價約240,000–280,000 港元,視配置而定。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 長安銳程Plus 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先等售價落實,再決定佢應該同邊個級距比較、再睇動力係咪足夠應付高速併線同滿載、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 長安銳程Plus 唔係買車一刻就完結,之後仲有保險、輪胎、保養、泊車同日常能源成本要處理。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
車型概覽

吉利EX5 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講版本取捨,幫你用買家角度篩走唔適合嘅選擇。 近期市場討論到「自動駕駛全新突破 吉利Eva Cab亮相香港汽車博覽會」,代表呢類車型仍然有一定關注度。
零售價 HK$ 160,216、完稅價 HK$ 238,000 - 299,900 令預算位置更清楚,買家可以先估算月供、保險、泊車同日常開支。
購車價格指南
吉利EX5 嘅購車預算可以先由 零售價 HK$ 160,216、完稅價 HK$ 238,000 - 299,900 開始計。香港買車唔只係睇車價,月供、保險、牌費、泊車同能源成本都會影響每月壓力。
如果有幾個版本可揀,可以先將 2026 550km Max Plus(HK$ 299,900)、2025 430km Pro(HK$ 238,000)、2025 425km Max(HK$ 257,389) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點

睇 吉利EX5 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
68.39/60.22 kWh 嘅電池容量,真正意義係可以幫你估算一星期通勤同周末出車要唔要中途補電。 14.3/15.8/16 kWh/100km 嘅耗電表現,會影響你去快充站或者屋苑充電位嘅頻率。 160 kW、320 N·m 嘅輸出,令高速併線同短距離超車更有信心。 車長 4615 mm、車闊 1901 mm、車高 1670 mm、軸距 2750 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。
優缺點分析
吉利EX5 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:預算位置清楚,方便同同級車直接比較、日常能源成本有基本參考、電池同續航資訊有助安排通勤同補電。
要留意嘅係,要先確認屋苑、公司或常去商場嘅充電條件、香港停車場同窄路使用要留意車身闊度。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 吉利EX5 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「吉利 EX5 於香港的落地價大約係幾多?」簡單講,吉利 EX5 於香港的落地價大約介乎 240,000–300,000 港元,視乎版本而定。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 吉利EX5 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先用 零售價 HK$ 160,216、完稅價 HK$ 238,000 - 299,900 鎖定預算圈、再睇動力係咪足夠應付高速併線同滿載、再比較能源成本同補能便利、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 吉利EX5 最重要係先諗清楚充電節奏。屋苑、公司或者常去商場只要有穩定充電選項,電動化用車就會容易相處好多。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

車型概覽

Ferrari Monza SP2 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講同級車比較,幫你用買家角度篩走唔適合嘅選擇。
售價仍待確認,買家可以先把佢放入候選名單,等價格落實後再同同級車逐項比較。
購車價格指南
Ferrari Monza SP2 目前售價仍未清晰,較理性嘅做法係先睇版本、車身大小同動力形式,等價格落實後再決定值唔值得落訂。
如果有幾個版本可揀,可以先將 2025 6.5L Standard(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 Ferrari Monza SP2 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
自然進氣、12 個 汽缸 嘅動力底子,重點係市區跟車夠唔夠順、高速巡航會唔會吃力。 596 kW、719 N·m 嘅輸出,對滿載、上斜同超車都比單睇馬力數字更有意思。 車長 4657 mm、車闊 1996 mm、車高 1155 mm、軸距 2720 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。 濕式雙離合(DCT)、前置後駆 會影響起步順滑度、濕地穩定感同長途巡航性格。
優缺點分析
Ferrari Monza SP2 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:動力輸出對高速同上斜更有底氣、空間同車身尺寸方便家庭買家預判實用性。
要留意嘅係,香港停車場同窄路使用要留意車身闊度、售價未清晰前唔應該太早用性價比落結論。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 Ferrari Monza SP2 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「Ferrari Monza SP2 全球限量生產幾多部?」簡單講,Ferrari Monza SP1 同 SP2 合共全球限量生產 499 部。由於兩款車嘅產量係共同計算,而且只會邀請品牌最核心嘅 VIP 客戶購買,令佢喺二手市場嘅升值潛力極高。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 Ferrari Monza SP2 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先等售價落實,再決定佢應該同邊個級距比較、再睇動力係咪足夠應付高速併線同滿載、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 Ferrari Monza SP2 唔係買車一刻就完結,之後仲有保險、輪胎、保養、泊車同日常能源成本要處理。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

近日,國家市場監督管理總局正式公布首批國家質量標準實驗室培育建設名單。上汽通用五菱汽車股份有限公司申報的「新能汽車國家質量標準實驗室」成功入選,成為車企申報唯一獲批建設的國家質量標準實驗室。這標誌着企業在新能汽車質量技術體系建設方面邁入國家級新階段。
國家質量標準實驗室是依據《質量強國建設綱要》設立的國家級技術創新平台,主要承擔產業重大質量標準的基礎研究與應用、高水平質量標準的研制與推廣、以及質量標準人才的培養與集結等任務,對推動質量強國建設具有重要戰略意義。

【上汽通用五菱「新能汽車國家質量標準實驗室」成功入選】
上汽通用五菱獲批的「新能汽車國家質量標準實驗室」,匯聚了4000 餘名研發人員,涵蓋博士、碩士及外籍專家,設有博士後工作站、國家企業技術中心、國家級工業設計中心等多個國家級創新平台,擁有14 個國際一流水準的實驗室,涵蓋三電、碰撞、NVH、EMC、熱管理、智能聯網、輕量化材料等全鏈條驗證能力,已獲 CNAS 認可 275 項(其中包含 ECE 國際認可 81 項),具備從整車到零部件的全鏈路測試能力。
依托 3200 萬基盤用戶的場景數據及百萬輛級新能汽車大數據中心,實驗室能夠復現用戶真實使用工況,實現從研發試驗到用戶使用的全鏈條質量預判與閉環迭代,全面支撐新能汽車電智化技術的試驗驗證。

【整車試驗場】

【碰撞實驗室】

【三電系統實驗室】
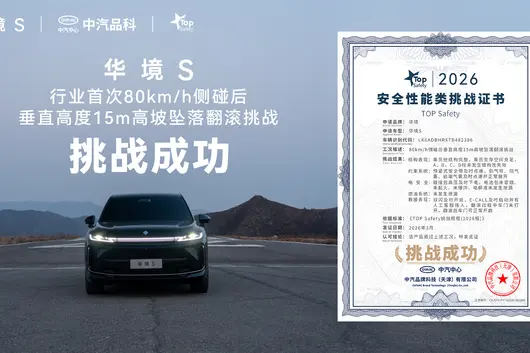
目前,實驗室已形成一批全球首創、國際領先、行業先進的標誌性成果,其中包括全球首創的智能島製造體系,入選國家首批「領航級智能工廠」培育名單;華境 S 通過行業首次 80km/h 側碰 15 米高坡墜落挑戰;神煉電池實現 766 億公里 0 自燃記錄。此外,五菱 Air ev 安全設計納入東盟官方技術規範,直流充電標準獲印尼 SNI 認證,實現中國車企在東盟標準制定領域「零的突破」,成功打破歐美日標準壁壘。

【華境 S 通過行業首次 80km/h 側碰 15 米高坡墜落挑戰】
此次入選首批國家質量標準實驗室,是上汽通用五菱長期堅持正向研發、深耕質量基礎設施建設的成果。它意味著企業的新能汽車質量技術標準將與國家級最高標桿對齊,實現從「造好車」到「定義好車標準」的關鍵一躍,真正做到技術自主、標準自主、質量自主、安全可控。與此同時,實驗室將通過創新質量管理與服務模式,實現技術攻關、標準引領、試驗驗證、產業賦能,讓「中國標準」沿著產業鏈出海,為「一帶一路」標準联通貢獻五菱力量。對用戶而言,國家質量標準實驗室將成為上汽通用五菱產品品質的「最高校驗場」——從三電安全到車身結構,從智能聯網到整車耐久,每一款車型都將在高標準、高起點的質量體系下完成嚴苛打磨。
面向未來,上汽通用五菱將以國家質量標準實驗室建設為戰略支撐,推動中國新能汽車從規模領先邁向標準領先,為全球消費者帶來更高品質的出行體驗。
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.

When it comes to domestic car brands, many people's impression may still be stuck at the stage of mainstream family cars. However, this is already old news from a few years ago. You should know that current domestic car brands not only beat joint venture brands in the domestic market, but have also surpassed foreign car brands on multiple tracks such as high-end development and overseas exports. Take the Geely Automobile we are talking about today for example.

Growth Momentum Leads the Industry
According to the latest data released by the official, Geely Automobile's cumulative sales in May reached 237,637 vehicles. It achieved double growth year-on-year and month-on-month for three consecutive months, leading the overall market with stable growth and impressive results. However, compared to this already excellent total performance, many industry insiders, after seeing the sales results of each brand under Geely Automobile, will be amazed that its quality is also getting higher.

As is well known, there are two hardest markets in the automotive industry: the luxury high-end market and the overseas export market.
Taking Geely Automobile as an example, its "Global Luxury Technology Brand" — Zeekr Automobile, reached deliveries of 34,377 vehicles in May, an 81.8% increase year-on-year and an 8.1% increase month-on-month, achieving double growth for four consecutive months. The average transaction price per vehicle also increased by 52.4% year-on-year. What is even more shocking is that the sales share of Zeekr 9 Series and 8 Series, which are priced as high as 400,000 to 500,000, accounts for nearly 50%!

Not only that, Geely Automobile's "Global New Energy High-End Brand" — Lynk & Co, also achieved May sales of 20,732 vehicles, with new energy vehicle sales accounting for 70.8%, and the brand's cumulative sales have broken 1.8 million. This shows that Geely Automobile's high-end models have not only won the recognition of a large number of consumers with excellent product power, but have also completed the transformation of volume and price rising together at the brand level.

Of course, as the undisputed leading automotive enterprise in China, Geely Automobile's focus is no longer limited to the domestic market. It chose to go global to challenge the more difficult overseas market. This is not the case, May's overseas export achievement of 85,144 vehicles set a new record for export sales. It is worth mentioning that the hot-selling products of Geely Automobile brands overseas are also mostly high-end or new energy vehicles.

For example, Zeekr has entered more than 50 countries and regions, and the cumulative global delivery volume of Zeekr 7X has exceeded 160,000 vehicles; Geely Galaxy Starship 7 EM-i remained the champion of new energy plug-in hybrid SUV sales in Kazakhstan for March and April; Geely Galaxy E5 remained the champion of pure electric SUV-C market sales in Australia, Argentina, UAE, Morocco, and Uruguay for the first quarter, and stayed in the top three in Brazil, Uzbekistan, and Indonesia new energy pure electric SUV-C models!

Hardcore Strength Creates Brilliance
Obviously, whether it is the rapid sales growth trend, or the hot sales in new energy, high-end market and overseas market, it is inseparable from hard strength as support. Taking Lynk & Co Automobile as the first car racing brand in China for example, top technology shouldn't just stay on the marketing level, but must be proven on the track. Therefore, it recently announced carrying 03+ TCR Racer, 03++ Racer, and 03 CUP EVO three racing cars to participate in TCR China, CTCC China Cup, and Lynk & Co Cup three major events simultaneously.

With hardcore strength, Lynk & Co naturally fears no high-difficulty tests. In the two-round finals of TCR China, the 03+ TCR Racer achieved the results of 4 championships, 1 runner-up, and 2 third-place finishes with its hardcore performance strength; in the CTCC China Cup, the Lynk & Co Zongheng Racing Team even achieved the results of 2 championships, 2 runner-ups, and 1 third-place finish. At the same time, in the 2026 Season FIA TCR World Tour opener, the Starri TCR Racer of Geely China Star Racing Team (Geely Cyan Racing) also won the race in the final and brought back the historical first win. This not only means that Starri TCR has world-class competitiveness, but also marks that Geely China Star Racing Team has officially completed the first chapter of the Geely Automobile Sports New Era.

At the same time, in technical levels such as intelligence and safety, the Haohan inherited Geely and Volvo safety heritage, assisted driving mileage grew by 215% in one year, leading the entire industry with the fastest growth rate. In the recent Euro NCAP official test, Geely Galaxy Starship 7 EM-i (Geely STARRAY EM-i) successfully completed the exceeding standard bilateral serial limit crash test at the France UTAC Laboratory. This not only intuitively confirms Geely's leading vehicle safety technology and mature systematic safety strength, but also lays a solid foundation for Chinese automotive safety technology to go international and participate in global industry standards!

Daxia Car Talk: I believe many people, after seeing Geely Automobile's sales data, will have the praise "It's too comprehensive" in mind. After all, car enterprises that can achieve impressive results in new energy, high-end, overseas exports, and even on the track at the same time, let alone in the independent domestic brand circle, you can't even find a few car enterprises in the global automotive industry that can achieve these things simultaneously!
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
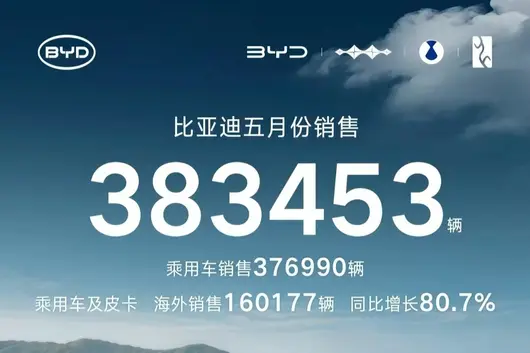
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。
然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。
要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。
高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。
《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。
如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
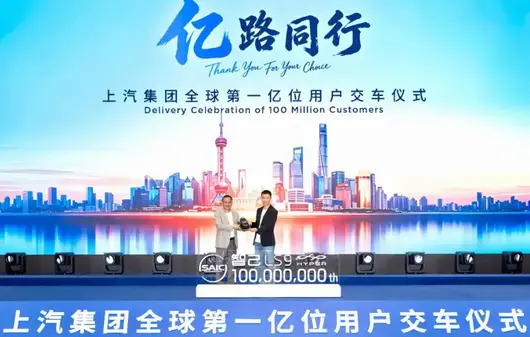
二零二六年五月二十八日,上汽集團「全球第一億位用戶交車儀式」喺上海北外灘世界會客室舉行。上汽旗下十餘個整車品牌、十九款車型,以「全球接力交付」嘅方式,橫渡山海、跨越洲際、聯動全球,上汽集團由此成為首個累計產銷量突破一億輛嘅中國汽車集團,為中國汽車行業鑄就新嘅里程碑。

一九五五年,上海內燃機配件製造公司成立,上海汽車工業由此起步。一九五八年,工人們用榔頭敲出第一輛「鳳凰牌」轎車,實現上海轎車製造「零嘅突破」。七十餘年來,上汽親歷並推動咗中國汽車工業從無到有、從弱到強嘅全過程:一九八三年桑塔納下線,開啟合資合作;一九九七年上海通用成立,創造 23 個月建廠出車嘅「上海速度」;二零零六年自主品牌榮威誕生出,二零一六年推出全球首款網際汽車榮威 RX5;二零二零年高端智能電動品牌智己汽車成立。
貫穿呢一征程嘅,係上汽始終秉持嘅「懂車更懂你」用戶理念。從桑塔納國產化共同體到合資 2.0 技術共創,從網際汽車到全線控底盤、固態/半固態電池、AI 大模型上車——每一次跨越,都係「懂車」能力嘅進階,都係「懂你」初心嘅一脈相承。一億輛,更加係一億份用戶信賴嘅集中兌現。
第一億輛交付車型智己 LS9 Hyper 係上汽七十餘年技術積澱嘅集大成之作,開啟咗新能源車「新三大件」嘅嶄新時代。佢搭載咗下一代底盤技術,同級首發嘅全線控四輪轉向;下一代智駕硬體,520 線超視域激光雷達 + 英偉達 Thor 晶片,下一代三電——全域 800V 高壓平台與恆星超級增程。全面預埋咗面向 L3 及以上高階智駕持續進化嘅冗餘能力。
同時,智己 LS9 Hyper 首搭上汽金標颶風三電機,從容躋身性能 3 秒俱樂部;更聯合紫金實驗室,全球首發「內生安全」技術,將汽車安全邊界從「物理安全」拓展至「資訊與系統安全」,係 AI 時代嘅必備安全基石。
一億輛嘅背後,係上汽涵蓋整車、零部件、移動出行同服務、金融、國際經營、創新科技六大板塊嘅全價值鏈閉環。二零二六年 1-4 月,上汽累計銷售 130.2 萬輛,連續四個月位居中國車企銷量冠軍。其中自主品牌銷量 91 萬輛,佔比近 70%;新能源車銷售 41.2 萬輛;海外市場銷售 45.9 萬輛,同比大漲 50.2%。
交付儀式現場,上汽全品牌、全產品矩陣協同發力。自主品牌全線出擊:尚界 Z7、華境 S、榮威 M7、MG4 半固態電池版、五菱星光 560、大通 eDeliver5、紅岩重卡、躍進大拿 T1、申沃純電客車、依維柯聚星 EV 等相繼交付,覆蓋個人出行、家庭生活、商用運營、物流運輸等多元場景。
合資品牌集中亮出「合資 2.0」成果:大眾 ID. ERA 9X 將全球首發搭載 Momenta R7 強化學習世界模型,上市一個月交付突破 7000 臺;AUDI E7X 計劃成為奧迪全球首款實現 L3 級自動駕駛落地嘅車型;別克至境 E7 基於「逍遙」超級融合架構打造,上市一個月交付破 1 萬台。

從上海主會場出發,交付畫面喺南京、柳州、太原等國內多城及英國、印尼、新加坡等國家接續點亮,開創咗中國汽車品牌嘅全新敘事方式。
呢背後,係上汽全球化佈局嘅深厚根基。上汽係中國汽車企業「走出去」嘅先行者:喺海外擁有超 100 個零部件生產基地、超 3000 個經銷商網絡,建成倫敦等 3 大研發創新中心同泰國、印尼、印度、巴基斯坦 4 個生產製造中心;安吉物流擁有各類滾裝船 42 艘,8 條國際航線覆蓋東南亞、歐洲、美洲。
如今,上汽產品同服務遍佈 170 多個國家同地區,海外累計銷量突破 700 萬輛。二零二五年,上汽發佈海外「Glocal 戰略」(全球 + 本土),正加速由「產品出海」邁向「價值鏈出海」,令「中國智造」進一步走向世界。
「懂車更懂你」嘅最終落腳點,係每一個真實用戶嘅出行生活。得到 APP 創始人羅振宇作為華境 S 第 001 號體驗官,從跨年演講盛讚華為乾崑智駕到走進工廠見證下線;前留德國腳楊晨選擇 ID.ERA 9X,因其黃金增程與長期主義不謀而合;曹開亮全家訂車後,偶像周杰倫恰好成為別克 MPV 家族代言人;公益博主劉佳連續五年為廣西山區留守兒童理髮、送陪伴,別克第一時間援助,佢被至境 E7「滿分座艙」打動。從自媒體博主到村支書,從公益守護者到物流企業——每一位用戶都係真實生活嘅縮影,正係呢「懂車更懂你」最生動嘅詮釋。
一億輛係上汽七十餘年發展嘅階段性答卷,更加係上汽面向智電未來「二次創業」嘅全新起跑線。二零一四年,上汽積極落實「發展新能源車係我國從汽車大國邁向汽車強國嘅必由之路」嘅重要指示,率先全面轉型。十二年後,從智電轉型嘅「一馬當先」,到自主合資、乘用商用、海內海外嘅「萬馬奔騰」,上汽將不斷以「懂車更懂你」為用戶理念,令科技創新真正惠及每一位用戶。
從 1955 到 2026,從第一個用戶到第一億個用戶,從初創探索到行業引領——上汽將繼續同全球用戶、全球夥伴億路同行,共創美好出行新未來。