首頁Laurel C35

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
車型概覽

Aston Martin DB12 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講每日相處是否輕鬆,幫你用買家角度篩走唔適合嘅選擇。
售價仍待確認,買家可以先把佢放入候選名單,等價格落實後再同同級車逐項比較。
購車價格指南
Aston Martin DB12 目前售價仍未清晰,較理性嘅做法係先睇版本、車身大小同動力形式,等價格落實後再決定值唔值得落訂。
如果有幾個版本可揀,可以先將 2025 4.0T Standard(價格待確認)、2025 4.0T Volante(價格待確認)、2025 4.0T Volante 60th Anniversary Edition(價格待確認)、2025 4.0T S(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 Aston Martin DB12 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
雙渦輪增壓、8 個 汽缸 嘅動力底子,重點係市區跟車夠唔夠順、高速巡航會唔會吃力。 680 Ps / 500 kW / 700 Ps / 515 kW、800 N·m 嘅輸出,對滿載、上斜同超車都比單睇馬力數字更有意思。 12.2 L/100km 嘅油耗參考,會直接影響每日通勤同周末出車嘅入油頻率。 車長 4725 mm、車闊 1980 mm、車高 1295/1290 mm、軸距 2805 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。
優缺點分析
Aston Martin DB12 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:日常能源成本有基本參考、動力輸出對高速同上斜更有底氣、空間同車身尺寸方便家庭買家預判實用性。
要留意嘅係,香港停車場同窄路使用要留意車身闊度、售價未清晰前唔應該太早用性價比落結論。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 Aston Martin DB12 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「Aston Martin DB12 適唔適合香港用家?」簡單講,適合。Aston Martin DB12 作為一部 Super GT,懸掛調校兼顧舒適性,日常市區行車唔會太硬,隔音出色。車身尺碼喺 GT 跑車入面算係合理,配備 360 度泊車鏡頭,喺香港街道同停車場 manageable。Volante 開篷版仲可以享受開篷駕駛樂趣。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 Aston Martin DB12 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先等售價落實,再決定佢應該同邊個級距比較、再睇動力係咪足夠應付高速併線同滿載、再比較能源成本同補能便利、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 Aston Martin DB12 嘅日常成本,會反映喺燃油、保險、輪胎同定期保養上。12.2 L/100km 令通勤預算較容易掌握。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。


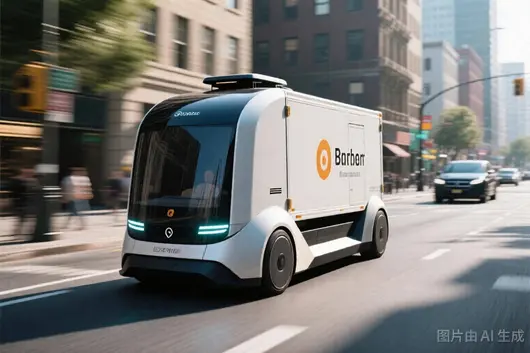
OwlAuto Report (ID:owlauto), In 2026, the IPO wave of autonomous driving enterprises is surging, but market evaluation of companies has tended towards rationality, and commercialization capability has become a core consideration. Against this backdrop, the unmanned logistics vehicle sector has stood out with a clear business model, becoming the autonomous driving commercialization direction most favored by capital and the market. Among them, the four companies Cainiao Unmanned Vehicle, NewStone, White Rhino, and Jiushi - established successively between 2015 and 2021 - are known in the industry as the "Four Little Dragons" of unmanned logistics vehicles.
Reviewing the growth journey of the "Four Little Dragons", they each have distinct characteristics. Cainiao Unmanned Vehicle started earliest, establishing the ET Lab in 2015, launching "Little Donkey" in 2020 and deploying it on a large scale in campuses and communities, with cumulative deliveries exceeding 1 million orders, and was strategically integrated with Jiushi in 2023, showcasing ten years of accumulation leading to rapid growth. NewStone was founded in 2018 by Yu Enyuan with a logistics hardware background; after encountering setbacks on the "Mobile Container" route early on, it transformed and accumulated early customers with the X3, X6. White Rhino founder Zhu Lei possesses Baidu autonomous driving DNA, founded in 2019 directly entered instant delivery, received investment from SF Express and Xinyuan Motors, and steadily advanced in express delivery connection scenarios. The latest entrant Jiushi, its core team comes from Baidu Apollo, Waymo, expanded rapidly after being established in 2021, the fleet rose from 200 units at the beginning of 2023 to 2,000 units in 2024, reaching 20,000 units after integration with Cainiao, demonstrating strong upward momentum.
Among them, Jiushi is undoubtedly a highly explosive player. In 2023, it released the world's first Robovan — Z5, breaking the industry's fixed perception of unmanned vehicles as "small, low-speed, closed scenarios" with 5 cubic meters volume, nearly 1 ton load, and 40km/h speed. Before that, Cainiao Little Donkey cargo box was only 2 cubic meters, 20km/h; NewStone X3 Plus was only 2.4 cubic meters, and White Rhino R3 was also only 3 cubic meters. Jiushi tore open a market gap with the Robovan category, subsequently launched Z8, Z10, and heavy-load L series, after which Cainiao, NewStone, and White Rhino also followed suit, all launching models exceeding 5 cubic meters in 2025, and the industry entered a stage of scaled competition.
And 2025 also became a year of significant growth in fleet size for each company. Jiushi operates over 7,000 units in more than 300 cities nationwide; cumulative deliveries exceeded 20,000 units after integration with Cainiao. Cumulative sales of 5+ cubic meter models exceeded 25,000 units, accounting for nearly 70% of Robovan investments among mainstream express companies like ZTO and YTO. It also won all bidding segments for China Post's 7,000 unit procurement project and operates in overseas markets including UAE, Malaysia, and Singapore. NewStone cumulative deliveries exceeded 17,000 units, co-launching the world's first "Robovan-as-a-Service" model with Didi. White Rhino covers nine business scenarios under deep empowerment from SF Express. After the merger of Cainiao Unmanned Vehicle and Jiushi, a "Super Carrier" was formed, possessing the world's largest Robovan fleet, with delivery volume exceeding the sum of all other enterprises.
In 2026, the "Four Little Dragons" landscape has evolved into a "one super, many strong" structure. With the merger of Cainiao and Jiushi, industry concentration has significantly increased, and the implementation of map-less technology will become a new competitive watershed. Jiushi, NewStone, and White Rhino all plan to launch map-less autonomous driving technology this year, which will significantly reduce deployment costs and accelerate scaled implementation. The influx of new players such as Desay SV, Momenta, and Dreame, along with the ecosystem deepening of giants like JD and Meituan, is further revitalizing this market. Robovan is no longer a distant concept product; how its future development prospects will unfold and how the capital story will be written is worth waiting for.
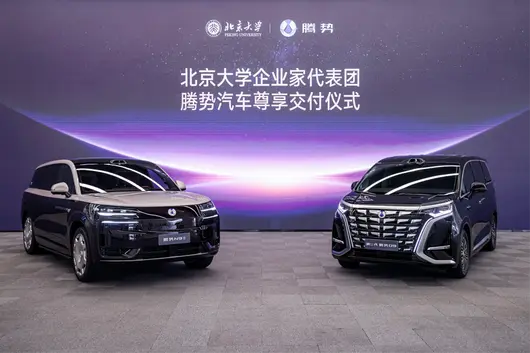
6月23日,北京大学企业家代表团腾势汽车尊享交付仪式在深圳比亚迪全球总部举行。比亚迪集团董事长兼总裁王传福亲自将第二代腾势D9与腾势N9闪充版交付给北京大学汇丰商学院的企业家。此次交付标志着腾势汽车在赢得广泛市场与口碑之后,再次获得中国顶级知识精英与商界领袖的集体认可,成为中国豪华品牌向上的又一重要注脚。

北大董事长严选,腾势精英朋友圈持续扩容
此次交付活动由北京大学原副校长、汇丰商学院创院院长海闻带队,汇集多位在各行各业极具影响力的北大汇丰杰出企业家学员。在现场,汇创达科技董事长李明、曼恩斯特董事长唐雪姣、跨越速运副董事长徐黧凤、岑科科技总裁柯珊、雄帝科技董事长高晶、得辉达董事长刘媖、喜盈资本董事长董月青等商界翘楚,将科技豪华旗舰MPV——第二代腾势D9收入囊中;伟维运通董事长刘伟则选择了科技驾控旗舰SUV——腾势N9闪充版,作为其新座驾。

这群运筹帷幄的企业家,选择座驾的严苛程度远超常人。对他们而言,座驾既要是移动办公室,能在通勤途中无缝接入全球会议、处理紧急公务;又要是移动起居室,能在高强度工作间隙快速回血,也能在周末假期化身为承载家人欢笑的舒适空间。
他们的选择,正是对腾势科技实力和产品价值的深度认同。比亚迪第二代刀片电池及闪充技术,让企业家们彻底告别里程焦虑与充电等待,一杯咖啡的时间,便能充饱电,把宝贵的时间交还给决策与生活;全球首创的易三方,赋予车辆极致转向、圆规掉头、智能蟹行等领先功能,让大尺寸座驾在狭窄车位与复杂路况中依然游刃有余;天神之眼 5.0辅助驾驶系统,则在长途奔波中分担驾驶压力,让每一段旅程都更轻松、更安心;而云辇智能车身控制系统配合路面预瞄2.0,从容化解路面颠簸,无论是后排办公,还是家人小憩,都能不被打扰。正是这份对全场景需求的精准满足,让腾势赢得这群商界名流的信任。

圈层价值共鸣,腾势成时代精英出行新标配
而这份信任,并非孤例。从政商舞台到科技前沿,再到文体聚光灯下,腾势已成为顶尖圈层的“标配”。选择腾势,已然成为精英圈层的共识。
在中国香港,腾势D9凭借领先的智能化、安全性以及豪华大气的形象,成为高端政务出行信赖之选,超过半数的司长都将其选为日常出行座驾。

在科技圈,腾势汽车则凭借科技旗舰的魅力,赢得中国科技圈“最强大脑”的青睐。Momenta CEO曹旭东、编程猫CEO李天驰、优必选科技CEO周剑、游戏科学创始人兼CEO&《黑神话:悟空》制作人冯骥等科技新贵,不约而同地选择腾势。这背后,是顶尖科技精英对腾势的高度认同,更是对“科技豪华”的深度共鸣。

作为豪华MPV价值标杆,腾势D9还深受商业领袖的认可。京东创始人刘强东、香港信和集团主席黄永光、福耀集团董事长曹晖、亚洲最年轻的纳斯达克上市公司创始人何猷君等商界大咖,纷纷选择腾势D9作为商务出行与高端接待的座驾,彰显了其在商务场景中的影响力。

不仅如此,腾势的科技豪华也席卷了文体圈,成为品位与身份的象征。从杨澜、高圆圆等知名媒体人、演员,到王力宏、胡海泉等实力音乐人,再到王皓、潘晓婷等世界冠军,腾势深入融入他们的工作与生活。


当中国最具智慧的头脑与最具影响力的企业家,将腾势选为他们出行的第一选择时,“中国豪华”便有了最有力的注脚。这次新车交付,不仅是北大精英与腾势的双向奔赴,更是中国高端智造强势崛起的生动缩影。未来,腾势还将继续与每一位时代引领者同行,共同书写属于中国的豪华出行新篇章。
鈉離子電池儲能,正從示範驗證,邁向規模化應用嘅快車道。
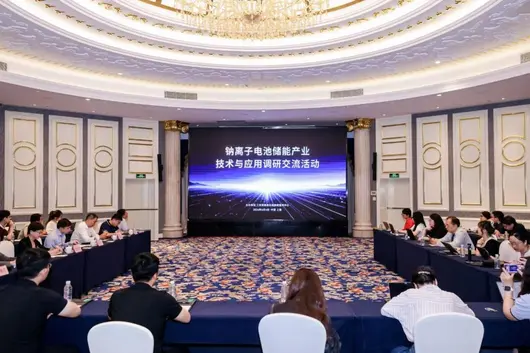
過去,鈉離子電池被視為“備胎”或“補充”,但喺 6 月工業和信息化部“鈉離子電池儲能產業技術與應用調研交流活動”會議上,由材料創新到系統集成,再到下游應用,產業鏈各環節嘅代表提出咗截然不同嘅判斷。

材料端、製造端、系統端與應用端嘅同步成熟。
鈉電嘅時代,真係嚟啦。
鈉離子電池,最堅實嘅優勢唔係技術,而係資源稟賦嘅地緣政治免疫性。
鋰資源全球分佈極不均衡,且中國鋰原料對外依存度長期超過 60%。鈷、鎳資源同樣高度集中喺剛果(金)、印尼等國。
呢種資源集中度,令鋰電產業鏈面臨持續嘅地緣政治風險同價格波動風險。
鈉資源則完全不同,地殼豐度約 2.3%,係鋰嘅 1000 倍以上;海水同鹹水湖中儲量幾乎無限;中國係全球最大嘅原鹽生產國,2025 年原鹽產量超過 1 億噸。
這意味著鈉電正極材料嘅原料供應,完全唔受國際資源政治約束。

材料端破局
復刻“鐵鋰”奇蹟
鈉離子電池能否大規模應用,核心在於材料同成本。
“鈉離子電池正係復刻 2020 年磷酸鐵鋰之路。”容百科技鈉電事業部總經理王尊志判斷。

佢給出咗具體嘅數據支撐:
目前鈉電正極極片壓實密度已增加至 2.5g/cm³,複合磷酸鐵鈉(NFPP)循環壽命超過 15000 次,量產穩定性正不斷被驗證。
作為正極材料龍頭,容百科技正全力推進以 NFPP 為核心嘅聚陰離子路線。
王尊志透露,公司透過首創適配鈉電嘅工藝同設備,創新性地將聚陰離子鈉電材料嘅加工成本降低咗 30%-50%,呢個無疑係加速鈉電量產嘅關鍵一招。
產能佈局上,容百已喺湖北仙桃落地 6000 噸聚陰離子正極材料產能,2026 年將拓展至 2.8 萬噸,到 2027 年,更計劃根據市場需求新建 30 萬噸鈉電專用產線。
負極材料都有好消息。
硬碳負極成本下降速度超出市場預期,預計將從 2024 年嘅每噸 6 萬至 7 萬元降至 2026 年嘅 3.5 萬至 4 萬元,遠期目標直指 2.5 萬元/噸以下。

萬華化學電池產業公司營銷中心總經理魏東表示,開闢煤基、樹脂基兩條工程化硬碳技術路線,從根本上解決咗早期依賴天然生物質原料所帶來嘅供應限制與性能波動問題。
煤基路線成本優勢突出,適合對價格敏感嘅場景,樹脂基路線則喺產品一致性同綜合性能方面表現更優。
具體嚟講,容百科技推進嘅 NFPP(複合磷酸鐵鈉)路線,其核心原料係磷酸鈉、硫酸亞鐵,均係大宗化工產品,供應鏈極其成熟。
萬華化學開闢嘅煤基/樹脂基硬碳路線,原料分別來自煤化工副產物同石油化工產品,均喺中國國內有充足供應。
正極成本劈半、負極成本腰斬,材料端嘅降本曲線已經明確。

鈉離子電池
迎嚟咗全面產品化
材料端嘅成熟,為電池同系統集成商提供咗登上舞臺嘅可能。
寧德時代國內儲能解決方案 CTO 林久標表示:“鈉離子電池迎嚟咗全面產品化時代。”
寧德時代喺鈉離子電池上,開拓進展迅速。

鈉離子電池特性重構電化學模型,攻克咗硬碳電極水分控制、產氣等量產難題,產品具備寬溫域及 15000 次超長循環壽命。
林久標介紹,寧德時代採用“一殼雙芯”平台化方案,與鋰電系統保持同尺寸、可實現便捷切換。
目前已推出由 3MWh 直流艙同 3MW 升壓變流一體機構成嘅完整儲能單元,系統壽命達 20 年。
林久標仲透露咗量產同交付時間表。
寧德時代正透過產品設計同生產製造兩方面推動降本,鈉離子電池專用產線已建成投產。同時,由於鈉電材料本身唔含鋰、鈷、鎳,佢唔需要承擔呢啲戰略性金屬嘅溢價。
今年 9 月,公司將向客戶交付首批鈉離子電池儲能系統,全年實現 GWh 級出貨。 這標誌住鈉電儲能真正進入咗商業化交付階段。
GWh 級出貨,意味著鈉離子電池儲能唔再係兆瓦級示範,而係真正進入咗規模化商業交付嘅軌道。

大單鎖定
海博思創實驗測試中心總經理王壘,給出咗清晰嘅應用場景:
鈉離子電池儲能喺大型獨立儲能電站、算電協同等新型高耗能場景、4-6 小時及以上長時儲能、高循環頻次儲能項目、15 年以上長運營週期項目等領域,具有顯著嘅差異化優勢。
喺西北某大型風光基地,配套建設一座鋰鈉融合嘅儲能電站。白日,光伏大發,鋰電系統負責高頻次嘅調頻響應;夜晚,當需要長達 4-6 小時嘅平穩供電支撐時,具備成本優勢同長循環壽命嘅鈉電池開始發作用。
呢種“鈉鋰耦合”嘅模式,既發揮咗鋰電嘅高能量密度同快速響應優勢,又利用咗鈉電嘅經濟性同長時儲能能力,實現咗整體系統效益嘅最大化。
另外隨著 AI 大模型嘅發展,“算電協同”變成咗極具潛力嘅場景。
數據中心電力需求激增,且要求不間斷、高質量供電。鈉離子電池優異嘅寬溫域性能同本徵安全性,令佢成為數據中心備用電源同峰谷套利嘅理想選擇。
睇到潛在需求,市場已用腳投票,海博思創將推動鈉離子電池儲能嘅規模化應用,並打造鋰鈉融合儲能電站示範項目,首批項目將喺 2026 年內實施落地。
寧德時代同海博思創已簽署為期 3 年、規模 60GWh 嘅鈉離子電池儲能訂單。呢個超級大單,為整個鈉電產業鏈注入咗強勁信心。


未來
產業鏈嘅信心,仲來自頂層設計嘅支持。
浙江大學兼職教授、中國能源研究會特邀首席專家劉亞芳指出,展望“十五五”,鈉離子電池儲能產業應借政策東風加快研發同產業化落地,積極拓展大基地、算電協同等應用場景。
當然,挑戰依然存在。
中國化學與物理電源行業協會動力電池應用分會研究中心總經理周波建議,行業需要快速推進全生命週期嘅標準與認證體系建立,加速產業化進程。
容百科技 30 萬噸產能嘅規劃,萬華化學硬碳負極成本向 2.5 萬元/噸邁進,寧德時代 GWh 級出貨同"一殼雙芯"嘅平台化設計,海博思創 60GWh 訂單嘅鎖定。
15000 次循環壽命嘅技術驗證,20 年系統壽命嘅商業承諾,鈉離子電池儲能產業正喺完成從"技術可行"到"商業可行"嘅關鍵跨越。
從材料端嘅降本突破,到系統端嘅 GWh 級交付,再到應用端嘅 60GWh 大單鎖定,鈉離子電池儲能已經唔再係“概念”或“備選”。
關鍵嘅一點,海博思創提出"打造鋰鈉融合儲能電站示範項目",寧德時代採用"一殼雙芯"方案實現鋰鈉同尺寸切換。
鈉離子電池儲能嘅真正優勢,唔係替代磷酸鐵鋰,而係喺一個大型儲能系統入面與鋰電形成互補組合:
鋰電承擔高能量密度、高功率密度嘅主力角色。
鈉電承擔長時儲能、高循環頻次、低溫環境下嘅輔助角色。
透過統一嘅平台化設計(同尺寸、同接口),降低系統集成嘅複雜度同切換成本。
呢種"鈉鋰融合"架構可以優化成個儲能系統嘅資產組合:
用鈉電覆蓋鋰電唔擅長或唔經濟嘅工況,從而提升成個電站嘅全生命週期收益。喺呢個框架入面,鈉電嘅優勢唔係絕對嘅,而係相對互補嘅。
冬天嘅汽車,嗰點有保障~
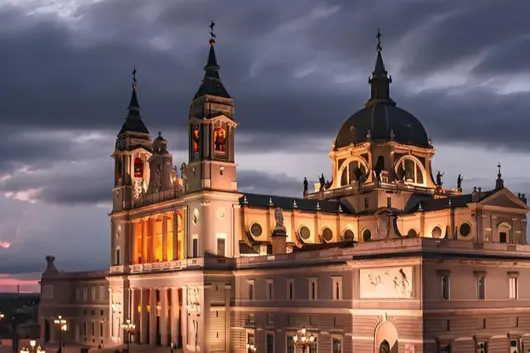
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
"In the first 5 months of this year, hundreds of new car models launched, but sales contracted. The combination of declining sales, revenue, and profits is unprecedented." At the just-concluded 2026 China Automotive Chongqing Forum, Wang Xia, President of the Automotive Division of the China Council for the Promotion of International Trade and President of the Automotive Chamber of the China Chamber of Commerce, pinpointed the chronic involution in the current auto market.

The first half of this year has not ended yet, with 544 new car models launched domestically, including 71 brand new and facelifted models. However, national passenger car retail sales dropped nearly 20% year-on-year in the first 5 months. If exports are excluded, this figure is 23.8%. Not only fuel vehicles, but new energy vehicles also declined over 15% year-on-year. The auto market has fallen into 'false diligence' where the more effort one puts in, the more poignant it becomes.
The most terrifying aspect is that the automotive industry's profit margin was only 3.2% in Q1, a historical low. Regarding this, President Wang Xia stated: "Sales without profit support are just empty number games; profits maintained by subsidies are ultimately a castle in the sand."

As top new force players, Li Auto and Xpeng reported revenue growth rates of -11.4% and -17.6% respectively in Q1 2026. NIO benefited significantly from high-end models like the new ES8 launched in Q4 last year, with a growth rate of 112.2% in Q1, but still reported a net loss of 330 million yuan. Leapmotor, ranked first in deliveries, had a growth rate of 8%, with revenue hitting a record high for the same period last year. Why was Leapmotor able to achieve a 'double kill' of sales and revenue during the Q1 downturn in the auto market? Will the newly launched C Series help Leapmotor achieve its annual million sales target?
C Series sales share decline 'reasonable'? Will it definitely return to 50% after new launch!
Leapmotor was the new force sales champion of 2025. Following a full-domain self-research route, over 65% of core components are self-produced, resulting in lower manufacturing costs than competitors. The product matrix simultaneously covers the 100,000-200,000 yuan market segment. Pure electric + extended range dual lines have no shortcomings. Coupled with sufficient capacity support for continuous delivery, the pragmatic industrialized car manufacturing route and the 'half-price home SUV' label perfectly fit current mainstream consumer demands. This is the reason for its counter-trend growth.

In the past two years, C10/C11/C16, C Series models contributed massively to Leapmotor's sales. Sales share was 77% in 2024, 55% in 2025, but only 36% in Q1 2026. Why do the sales pillars fail? Because Leapmotor knows that to achieve the million sales target, C Series alone cannot support it; they must optimize product structure and bloom at multiple points.

So at the end of last year we saw the volume-driving A Series, profit-guaranteeing B Series, foundation C Series, and premium D Series. These four pillars support Leapmotor's sales. This year Q1 was also the C Series gap period, old models clearing stock, users waiting for facelifts, demand will concentrate on the second half.

The recently launched Leapmotor C Series focuses on unchanged prices with upgraded configurations. The whole range gets 8295 chips, LiDAR is moved down, and range is improved. This product structure repair was very timely, filling all pain points, so C Series sales share will significantly recover in the second half. Bold prediction: it will return to 50%.
Can the million sales target still be achieved? Where is the bottleneck? How to win?
Conclusion first: The 1 million annual sales target is challenging to reach, but likely achievable. Leapmotor's annual sales target composition is 900,000 domestically, 100,000-150,000 overseas.

Bottlenecks remain, a well-worn topic being slow capacity ramp-up. The Jinhua, Zhejiang factory producing the 100,000 yuan main model A10 started two-shift production in April, aiming for 30,000+ capacity in June. It still has distance from the 100,000 per month target. The Hefei factory just started production in May, with two-shift annual output 200,000-400,000, but capacity release is late, contributing limitedly in the short term. Plus battery cells, chips, and automotive-grade storage are still tight and prices are rising, restricting full production progress.

However, Leapmotor is very confident in the Jinhua, Hangzhou, Hefei golden triangle capacity layout, with a total annual planned capacity of 1.46 to 1.51 million units, nearly 1.5 times the million sales target. There is determination that as long as orders continue to pour in, they can handle this tremendous fortune.

Back to products, A10 first month firm orders broke 40,000 units, D19 broke 15,000 firm orders in 15 days. Plus this month's facelifted C Series, sales will likely hit new highs in the second half. Also, there is an ace card positioning the 50,000-70,000 yuan range, targeting the sinking market—A05 launching soon. This small car can add L2-level driving assistance systems, crushing competitors at the same level.

As long as Leapmotor can take a huge market share in this price range, other competitors will have no chance to turn the tables. Consumers at this price point are usually very price-sensitive. Either first-time buyers with budget constraints, or second family cars with limited demand, so price will be the biggest factor in decision-making. A05 will likely become a rocket accelerator on Leapmotor's million sales journey.

Except for the domestic market, Leapmotor Q1 overseas exports were about 40,000 units, exports skyrocketed 442% year-on-year, ranking first in export volume and export share among new forces. This benefits from Stellantis Group's 40 countries, 800+ store resources. Leapmotor doesn't need to build global channels itself, which is unique among all new forces. In the second half, with factories in Spain, Malaysia, etc., going into production, Leapmotor's overseas sales might have even bigger surprises.

In the road to smashing the million sales target, Leapmotor has one last trick: trade price for volume. Compared to competitors, Leapmotor still has room for price cuts in the 100,000 yuan range, but Leapmotor leading sales won't take risks desperately. After all, once prices drop, it's hard to recover.

Another reason for confidence in Leapmotor's second half sales is market laws. Looking at the past 5 years, the auto market shows a pattern of slow first half, busy second half. Usually, the second half accounts for 55%–60% of the full year. As Leapmotor Vice President Li Tengfei said: "Annual sales will show a trend of first suppress then rise. We are very confident in the goal of hitting 1 million units."
Can selling at low prices break the predicament where bigger scale means weaker profitability?
From annual loss of 5.1 billion to profit of 540 million, Leapmotor interpreted a textbook loss reduction curve in just three years. But Q1 2026 Leapmotor welcomed new challenges. Gross margin 9.4%, less than the 14.9% of the same period last year. Net loss 390 million yuan. Last year same period lost only 130 million yuan. And last year Q4 still made 360 million.

Leapmotor car profit in 2025 was 903 yuan per unit, less than one-tenth of BYD, one thirty-fifth of Li Auto. Selling the most, but earning the least. And B10 new model R&D, overseas channel deployment, Malaysia and Spain factory production, all require continuous investment.

Although Leapmotor has run through the economies of scale loop through extreme cost control and high sales turnover, the profit ceiling under the low-price strategy is gradually becoming clear. Leapmotor sales are still new highs, scale is still growing. By 2028 economies of scale will be fully released, fixed cost per unit significantly diluted.

Additionally, Leapmotor's LEAP 3.5 architecture, C/B Series model component commonality rate reached 88%, amplifying 'reuse effect' not only shortened new model development cycle by 25% compared to previous generation, whole vehicle R&D investment will also reduce by 40%. It also improved procurement bargaining power by sharing core parts like chassis, lights, seats. Only then will economies of scale welcome the true inflection point on profits. At the same time, Leapmotor also announced plans to launch its own second high-end independent brand in 2027. New product pricing will target the 300,000 yuan+ high-end market, opening price ceiling, boosting brand premium.

Domestically using high specs low prices to seize market, overseas Leapmotor actively borships seeking premium space. Global fourth largest carmaker Stellantis Group, after announcing deepening strategic cooperation with Leapmotor on May 8 this year, decided to hand over operation rights even ownership of its European flagship factory to Leapmotor. In the near future the Spain Zaragoza Plant that once produced Opel, Peugeot will produce Leapmotor's B10. And the Madrid Villaverde Plant that once produced Citroën will also start producing Leapmotor in 2028.

Besides this, based on Stellantis Group's advantage of over 30% market share in South America, Leapmotor's Brazil Plant is also progressing in an organized manner. And with South East Asia market performance year-on-year improvement this year, Leapmotor is also actively advancing Indonesia, Malaysia, Thailand plant plans. In the future high gross margin overseas business share will rise, balancing Leapmotor's domestic low-price involution losses.
Conclusion
Leapmotor founder Zhu Jiangming once said: "Only by surviving can we develop. Making scale bigger is a goal more important than profitability." So at this stage after Leapmotor completes the million sales target, it will smoothly pass through the cycle. But profitability yields to scale expansion, annual 5 billion net profit goal will be missed.

Just as President Wang Xia said at the beginning, scale without profit is poison. In this final elimination race of global new energy giants, million sales were never the goal. To get the ticket to the future, either run through unmanned driving, get the next baton of technical revolution, or run through overseas markets, become the 'Toyota' of the new energy era.
你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。

然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。

要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。

高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。

《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。

如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
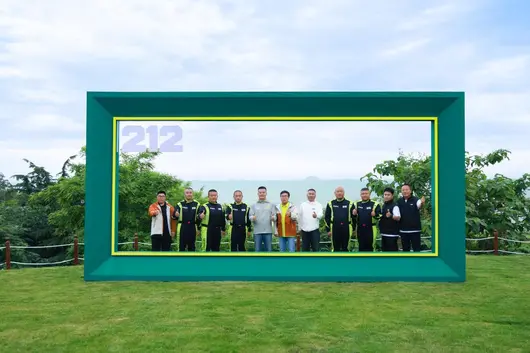
June 6, the 212 off-road vehicle Altay Rally finale ceremony landed in Qingdao. Han Qiaosheng, well-known driver Han Wei, manufacturers and amateur drivers, and event logistics teams gathered on-site to recap the just-concluded 2026 Altay International Rally. This year's event covered an extreme journey of 7,500 km. The 212 team relied on near-stock T01 mass-produced models, facing a host of 3.0T large-displacement competitors with 2.0T power, securing two wins and one runner-up in stages SS10 to SS13, winning the runner-up position in the T2.1 production factory team, and was the only participating manufacturer to achieve 100% course completion in this category. From the extreme battles on the Gobi sand fields to the glory summary at the offline ceremony, the old off-road IP proved with a practical fight: classic off-road is not just about preserving nostalgia; stock mass-produced cars can also stand on the podium of domestic top-tier rally events. The ordinary person's Altay off-road dream is taking root and sprouting.
The Altay Rally is known as the 'Eastern Dakar'. The 2026 session is considered the peak of difficulty in history by the industry. It spans across the northern and southern sides of the Tianshan Mountains, interwoven with desert, Gobi, Yardang, and shell crater road conditions. Over 60% of stages are shifting desert terrain, with partial stage surface temperatures breaking 60°C. Ultra-long distance high temperatures, continuous marches in no-man's-land caused many old teams to fail consecutively. The single ultra-long SS3 stage alone saw more than 30 vehicles suffer tire blowouts and more than 10 race cars helplessly withdraw, a tragic scene. The T2.1 category, as the core arena for factory mass-produced head-on showdown, rules clearly require that participating vehicles' power, chassis, gearbox, and other core hardware remain consistent with the mass-market production version. Only safety accessories like roll cages can be added, making it a 'strict open-air testing laboratory' for measuring a off-road vehicle's factory reliability. Against this background, 3.0T large-displacement models have long occupied category advantages. For small-displacement 2.0T models to break through was viewed by most off-road practitioners as an almost impossible task before the race.
No one expected that the old domestic off-road 212 would become the biggest dark horse of this event. The T01 battle cars that participated throughout had no heavy event modifications. The factory standard 2.0T turbocharged engine paired with ZF 8AT gearbox, assisted by BorgWarner large transfer case, 4L mode torque can be amplified 2.64 times. Under extreme operating conditions such as Gobi steep slope climbing and full-load towing, low-torque output is enough to rival large-displacement models. Long-distance crossing power remained smooth throughout, and failure rate was controlled at an extremely low level. At the body level, body-on-frame + front and rear solid axle classic hard-core architecture, combined with specialized optimized chassis tuning, faced continuous bumps and deep pit impacts, with body torsion resistance and deformation control performance standing out; full vehicle galvanized steel body calmly resisted Gobi gravel continuous scraping corrosion. Regarding safety configurations, the load-bearing capacity of the reinforced occupant cabin top increased by 16%. The cage body structure, paired with 540° panoramic imaging and emergency rescue call system, balanced extreme off-road performance with daily driving safety. This set of factory hardware configuration stood up to the solid real-world all-scenario verification in more than 7,000 km of bad road conditions.
At the finale ceremony scene, a group of Altay witnesses took turns sharing stage stories. From steady positioning earlier to preserve vehicle condition, to the latter half's devil desert stages suddenly powering up to sweep stage championships and runner-ups, drivers admitted that before the race no one was certain a 2.0T factory car could break out from a group of large-displacement opponents. The vehicle's stable and durable foundation was the key for the team to achieve full completion. Famous event host Han Qiaosheng commented on-site: "212 is a symbol of off-road nostalgia for generations of Chinese. In the past, people only remembered its classic history. Now it refreshes cognition with Altay results. Domestic hard-core off-road is breaking stereotypes with practical factory quality." Champion driver Han Wei also stated on-site: "T01 factory mechanical quality exceeded industry expectations. Relying on event data to polish products is a reliable path for domestic off-road brands to move steadily upwards."
Stage results landing in the consumer market was the heavy signal released by this ceremony. 212 officials officially announced at the event that the Altay same off-road modification kit will soon land on the brand's official mall. The kit includes chassis armor, beadlock wheels, professional off-road tires, and a full set of recovery and rescue equipment. All modification accessories have been tested on 212's 7,500 km extreme road conditions. Ordinary 212 owners do not need to modify the vehicle body significantly and can quickly upgrade off-road hardware to easily realize a cross-over switch from city commuting to wilderness crossing. 212 Off-Road Vehicle Marketing General Manager He Zhaopeng stated in the ceremony interview: "212's original intention was never to only be a race champion car, but to popularize off-road culture, giving every ordinary owner a chance for the off-road seeds in their hearts to take root and sprout. Verifying products at the Altay venue and benefiting users with modification kits is a key step for the brand to connect the race track and consumer market."
Focusing on future event layout, 212 has finalized the global off-road event map: the Altay Rally, Malaysia Sabah International Rainforest Race, Alxa T3 Challenge, and 2027 Altay Rally are all included in the participation plan, continuously practicing the 'race promoting research' product development philosophy. In addition, the brand's two heavy user support plans were launched simultaneously: the 2027 Altay amateur driver national recruitment has officially started, ordinary owners have the chance to fight in the top Altay venue as drivers; partnering with champion driver Han Wei to build the Champion Off-Road Training Academy, providing systematic off-road teaching, pre-race training, and full-chain empowerment for race participation to national owners. From professional factory teams fighting international events to cultivating amateur off-road enthusiasts, 212 is building a complete national off-road ecosystem from products, events to user training.
Looking at the domestic hard-core off-road market, many brands fall into the quagmire of 'heavy track modifications for results, mass-market vehicles disconnected from race cars', while 212 chooses to go against the grain, insisting on factory mass-produced car participation, using Altay extreme road conditions to reverse-optimize mass-produced models, and then releasing off-road technology precipitated from the track to ordinary consumers. With more than 60 years of brand accumulation, 212 has long stepped out of the single-nostalgia marketing old road. The Altay 7,500 km yellow sand trial is a self-renewal of classic domestic off-road. When modification kits enter the mall and amateur drivers can go directly to the Altay venue, 'Every 212 has an Altay dream' is no longer a slogan, but a reality that can be touched upon landing.
In the future, accompanied by multiple domestic and international top events landing successively and the off-road training academy operating on a normalized basis, 212 will also continue to convert track technology into consumer product strength, letting domestic hard-core off-road not only gallop across the Gobi and Altay but also accompany thousands of owners to rush to the distant mountains and fields.
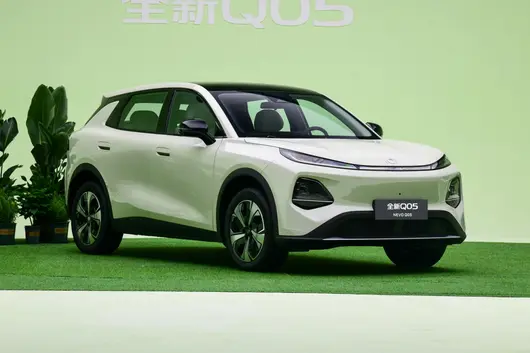
唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。

(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
 (零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
 (長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
 (零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
 (長安啟源全新 Q05)
 (零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
 (長安啟源全新 Q05)
 (零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
 (長安啟源全新 Q05)
 (零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
 (長安啟源全新 Q05)
 (零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
 (長安啟源全新 Q05)

(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。
唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。
(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
(零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
(長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
(零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
(長安啟源全新 Q05)
(零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
(長安啟源全新 Q05)
(零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
(長安啟源全新 Q05)
(零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
(長安啟源全新 Q05)
(零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
(長安啟源全新 Q05)
(零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
(長安啟源全新 Q05)
(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".
However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.
You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.
Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.
The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.
If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
唔知有幾多朋友最近期關注 10 萬內純電 SUV 市場?近段時間睇嚟,呢個細分市場好熱鬧。就講長安啟源全新 Q05 同零跑 A10,上個月銷量分別達 15814 輛同 14372 輛,全部挺進 2026 年 4 月銷量排行全品類前 10,長安啟源全新 Q05 甚至奪得緊緊湊型純電 SUV 市場嘅銷冠。
(長安啟源全新 Q05)
值得留意係,兩款大熱門產品亮點亦唔少,9 萬級可以得到 500km+嘅續航,零跑 A10 甚至配備激光雷達,有高級智駕輔助需求嘅朋友嚟講,呢架車吸引力的確唔低。但係喺價格上,同為高配嘅長安啟源全新 Q05 506Max+ 同零跑 A10 505 激光雷達版,終端價格分別係 9.59 萬同 8.68 萬,手握 9 萬左右預算嘅朋友都可以考慮。明顯係,又去到決賽圈二揀一環節。
(零跑 A10)
如果對預算比較敏感,咁喺長安啟源全新 Q05 同零跑 A10 之間,後者可能更受歡迎,畢竟終端價格實打實平咗幾千元。而且,高配 A10 配有激光雷達,市區/高速情況均能啟動領航輔助駕駛,呢個就係佢嘅優勢所在。當然,如果預算允許,揀長安啟源全新 Q05 高配,都有帶激光雷達嘅高級輔助駕駛。
(長安啟源全新 Q05)
但既然係買車前嘅橫評,唔少全方位對比。首先從尺寸睇,作為緊湊型 SUV,長安啟源全新 Q05 長寬高分別係 4435*1855*1595mm,軸距為 2735mm。而零跑 A10 車型級別就係小型 SUV,長寬高分別係 4270*1810*1635mm,軸距為 2605mm。
(零跑 A10)
如果只係考慮代步、通勤,零跑 A10 嘅細個嘅略有優勢,方便行街串巷。但實際上,好多人買車都要兼顧家用,10 萬內預算也多以剛需用車群體為主。既然係剛需,且有家用需求,嗰空間自然唔好掉鏈子。
(長安啟源全新 Q05)
(零跑 A10)
講返日常家庭出行嚟講,兩車之間 130mm 軸距差異,直接反映喺後排體驗。坐入長安啟源全新 Q05 後排,腿部空間平整兼寬敞,一齊坐 3 位成年人都唔會太擠;但係坐入零跑 A10 後排,無論坐寬定係腿部空間都會細少少。媽咪喺後排照顧孩子,長安啟源全新 Q05 後排更加寬敞嘅空間會更加方便佢操作,孩子都能有更大嘅活動空間。
(長安啟源全新 Q05)
(零跑 A10)
除咗空間,通勤黨同家庭用戶對舒適配置都比較關注。睇嚟對比,兩車都有配電動尾門、無匙進入、自適應遠近光等外部配置。但係從車廂內睇,零跑 A10 副駕無法電動調節,後排靠背都唔支援角度調節,同埋缺少後排空調出風口、車內 PM2.5 過濾裝置等。
(長安啟源全新 Q05)
(零跑 A10)
反觀長安啟源全新 Q05,除咗副駕支持電動調節,前排仲集成咗加熱/通風/按摩/副駕腿托功能,對比零跑 A10 只提供前排座椅加熱,佢嘅品質無疑更上一層樓。包括後排乘員都有少少照顧,例如靠背角度可調、配有後排空調出風口、後排中央扶手/杯架等,更加適合家人同行呢類場景。
(長安啟源全新 Q05)
(零跑 A10)
除咗舒享體驗,行駛系統嘅對比我哋都唔好忽略。首先從大家關注嘅續航睇,長安啟源全新 Q05 同零跑 A10 分別搭載 51.9kWh、53kWh 電池,CLTC 純電續航做到 506km、505km,差異大可忽略。但從電芯供應鏈睇,前者出自寧德時代,後者就係國軒高科/江蘇正力,若論品牌含金量,“寧王”順位自然靠前,更值得信賴。另外,兩車都有全球品質,按照全球嚴苛嘅標準打造,零跑 A10 符合國內、歐盟雙標準,長安啟源全新 Q05 已經喺泰國上市,未來仲會相繼落地多個國家地區,最終開拓歐洲區域,此外仲有央企背書,質量品質都好可靠。
因為本文討論嘅係 A10 嘅 505 版本,採用電池液冷技術,溫控較好,而如果係 403 版本,採用成本低嘅風冷技術,散熱效果較差。呢點上,全新 Q05 做得更好,入門就採用電池直冷技術,高配用嘅係液冷技術,能更好地實現熱管理,保證電池安全。
(長安啟源全新 Q05)
(零跑 A10)
動力方面,長安啟源全新 Q05 同零跑 A10 都係前置單電機佈局,電機最大動力輸出分別係 120kW/190N·m、90kW/150N·m,0-100km/h 加速時間分別做到 8.9 秒同 10.6 秒。坦率嚟講,兩款車喺純電陣營加速性能都中規中矩;但係相對嚟講,長安啟源全新 Q05 嘅 8 秒級零百加速,喺山路行駛、高速超車等情況下會比零跑 A10 更加分。
(長安啟源全新 Q05)
(零跑 A10)
總結嚟講,零跑 A10 505 激光雷達版優勢突出:價格更低、智駕輔助覆蓋範圍更廣,適合預算優先 + 科技嘗鮮嘅消費者。而長安啟源全新 Q05 更強調“全面”二字:加少少預算同樣可以獲得高級輔助駕駛,而且尺寸更大、舒適配置更高、採用頭部電芯供應鏈,動力亦更強,綜合表現更全能。總括嚟講,預算 9 萬級追求面面俱到嘅家用體驗,長安啟源全新 Q05 506Max+ 更加值得考慮。
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
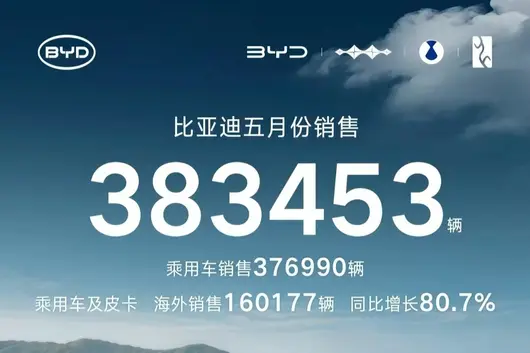
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
Geely recently announced overseas sales for May: 85,000 units, a year-on-year increase of 184%. Placing this in last year's context, this number might have been a surprise; but today, it feels more like a routine operation — after all, in the first two months of 2026, Geely's overseas monthly sales have continuously exceeded 60,000 units. From an average of over 30,000 per month to over 60,000+, the overseas market is becoming the area of strongest sales growth for Geely.
However, looking only at the numbers makes it easy to overlook some more significant changes.

Growth is not driven by 'piling up volume'
The domestic car market is fiercely competitive like a red ocean, but Geely's overseas performance continues to rise. 85,000 units is not an isolated phenomenon; what is more worth examining is the structure.
In Australia, deliveries broke 10,000 in the 14th consecutive month, becoming one of the fastest-growing Chinese car companies locally; in Brazil, it hit over 4,000 units in a single month, setting a new local record; in Mexico, cumulative sales from January to April reached 16,000 units, also setting a historical high. The Eastern European market was once Geely's export pillar, but 2025 financial reports show that revenue from Asia-Pacific (excluding China) surged from 5.7 billion to 14.6 billion, while Eastern Europe dropped from 30.2 billion to 29.2 billion. This is not market fluctuation, but an active shift — from high-risk areas to the more resilient Asia-Pacific.

Not just "selling more", but "selling at a premium"
In terms of total export volume, Geely may not rank first. Chery exported 1.34 million units in 2025, and BYD also surged past 1.04 million units. But Geely's approach is different.
The most obvious difference is product tier. EX2 took the B-segment new energy vehicle sales top spot in Mexico, Indonesia, and Costa Rica; EX5 won the first-quarter pure electric SUV sales champion in markets such as Australia, UAE, and Uruguay; Zeekr 7X in Australia directly surpassed the long-chart-topping Tesla Model Y. This is not the result of a price war, but Geely directly competing with international brands in the high-end market.
To achieve this, it relies on multi-brand synergy. Zeekr targets luxury pure electric, Lynk & Co aims for the global new energy high-end, and Geely Brand outputs mainstream products relying on the GEA architecture. In 2025, the group's new energy penetration rate reached 56%; this product network allows Geely to find suitable entry points in different markets.

The overseas expansion model is changing
Sales growth is just the surface; the real change is the profit structure. 2025 financial reports show that overseas revenue has already accounted for 21.41% of Geely Auto's total revenue; among the 420,000 units sold overseas for the year, new energy exports were 124,000 units, surging 240% year-on-year. Overseas business is no longer burning cash to exchange for market share, but a genuine source of profit.
What is even more interesting is Geely's strategy. In Brazil, Geely did not sell cars itself, but obtained 21.29% equity and nearly 4.86 billion warrants of Renault Brazil through technology transfer, exchanging technology for market share. In Southeast Asia, taking Malaysia Proton as a fulcrum, through technology licensing and parts synergy, Geely's products appear in the identity of a "local brand". This model avoids heavy asset investment in traditional overseas expansion and retains supply chain control.
Challenges are also plentiful
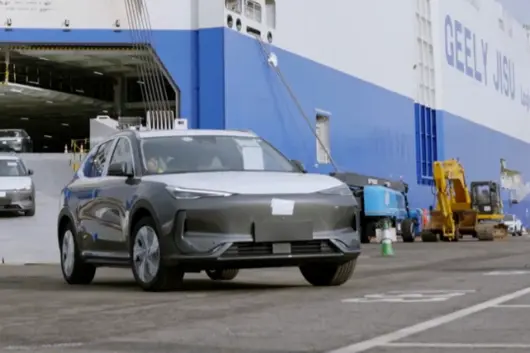
Fast growth brings plenty of trouble. Capacity and logistics are the most direct bottlenecks. Facing exploding orders, Geely has already utilized RoRo ships, container ships, and international train services, able to stably ship nearly 10,000 units monthly to European ports, but logistics pressure remains high.
Greater uncertainty comes from geopolitics. Trade friction and tariff barriers can change the rules of the game at any time. The 2025 EU anti-subsidy investigation into Chinese electric vehicles has already sounded the alarm. However, Geely's 2026 export target is 640,000 units, indicating it still has confidence.
When a car company has over 1,200 outlets in 77 countries and regions globally, using five years to pull overseas sales from 410,000 to a target of 640,000, the word "exports" is barely enough to describe it. For Geely, going overseas is not an elective question, but a mandatory one. Whether it can answer well depends on the implementation in the coming years.