首頁Hilux Surf

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Hyundai Palisade 同 Porsche Macan 嚟做比較。今日我哋由多個方面做一個詳細嘅比較,幫你省返做功課嘅時間。


現代 Palisade 喺馬來西亞嘅 OTR 售價係 RM 368,838 - 399,838,一共有 4 個版本,包括 2023 3.8L 2WD Luxe 7 Seats Petrol(RM 399,838)、2023 2.2T 4WD Executive 7 Seats Diesel(RM 389,838)、2023 3.8L 2WD Luxe 8 Seats Petrol(RM 378,838) 等。
保時捷 Macan 喺馬來西亞嘅 OTR 售價係 RM 469,000 - 469,000,一共有 4 個版本,包括 2025 55 quattro S line(RM 467,285)、2025 50 quattro Advanced(RM 361,135)、PMT 1874, Lorong IKS BukitTengah 14000 Bukit Mertajam(RM 296,610) 等。
從價錢睇來,現代 Palisade 嘅起步價確實比 Porsche Macan 平咗 RM 100,162。如果你預算有限,現代嘅入門版已經可以滿足日常需求。但要注意,平嗰幾千蚊,可能會喺配備上有取舍,具體要睇你嘅需求。

現代 Palisade 配備 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
保時捷 Macan 配備 3.0L Turbo,馬力 350 hp。官方油耗 12.0 L/100km。
動力方面,保時捷 Macan 嘅 3.0L Turbo 比現代 Palisade 嘅 2.0L Turbo 多咗 130 匹馬力。不過日常喺市區開嘅話,兩款車嘅動力都夠用,唔會覺得唔夠力。

現代 Palisade 車身長 4400 mm,尾箱 400 L。
保時捷 Macan 車身長 4400 mm,尾箱 400 L。
兩款車嘅尺寸幾乎一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全夠用。

現代 Palisade 同 Porsche Macan 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更重視品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就揀配備更豐富嗰款。最終都好建議兩款都去試駕,親身體驗先係最重要嘅。
總體嚟講,現代 Palisade 同 Porsche Macan 都係馬來西亞市場好唔錯嘅車型。揀邊一輛,關鍵都要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Ford Everest 同 Volvo XC40 嚟做比較。今日我哋由多個方面做一次詳細嘅比較,幫你省返做功課嘅時間。


Ford Everest 喺馬來西亞嘅 O T R 售價係 RM 266,338 - 430,838,一共有 6 個版本,包括 2026 3.0T 4WD Platinum(RM 430,838)、2026 2.0T 4WD Platinum(RM 348,838)、2026 2.0T 4WD Sport(RM 316,838)等。
Volvo XC40 喺馬來西亞嘅 O T R 售價係 RM 278,888 - 278,888,一共有 1 個版本,包括 2025 2.0T Plus(RM 278,888)等。
由價錢嚟睇,Ford Everest 嘅起步價確實比 Volvo XC40 平咗 RM 12,550。如果你預算有限,Ford 嘅入門版已經可以滿足日常需求。但都要注意,平嘅那幾千蚊,可能喺配備上要有取捨,具體要看你嘅需求。

Ford Everest 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 Co-Pilot360。
Volvo XC40 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 Pilot Assist, City Safety (標準)。
安全配備方面,兩款車都拿到唔錯嘅評級。不過 Ford Everest 嘅 Co-Pilot360 同 Volvo XC40 嘅 Pilot Assist, City Safety (標準) 喺功能上有些分別,如果你比較睇重主動安全嘅話,可以仔細對比下兩者嘅功能清單。

Ford Everest 採用 FWD 驅動方式。
Volvo XC40 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。

Ford Everest 同 Volvo XC40 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就揀配備更豐富嗰款。最後都係建議兩款都去試駕,親身體驗先係最重要嘅。

總嚟講,Ford Everest 同 Volvo XC40 都係馬來西亞市場好唔錯嘅車型。揀邊一部,關鍵始終都要睇你嘅個人需求同預算。建议大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Subaru Outback 同 Land Rover Discovery Sport 嚟做比較。今日我哋從多個方面做一個詳細嘅對比,幫你省下做功課嘅時間。


Subaru Outback 喺馬來西亞嘅 OTR 售價係 RM 260,000 - 280,000,一共有 2 個版本,包括 2025 2.4T R-Touring EyeSight(RM 310,340)、2025 2.5L Touring EyeSight(RM 280,340) 等。
Land Rover Discovery Sport 喺馬來西亞嘅 OTR 售價係 RM 499,800 - 499,800,一共有 1 個版本,包括 Standard(RM 499,800) 等。
從價錢嚟睇,Subaru Outback 嘅起步價確實比 Land Rover Discovery Sport 便宜咗 RM 239,800。如果你預算有限,Subaru 嘅入門版已經可以滿足日常需求。但都要注意,便宜嗰幾千塊,可能喺配備上會有取舍,具體要睇你嘅需求。
Subaru Outback 嘅安全評級係 TBD,主動安全系統包括 Basic。
Land Rover Discovery Sport 嘅安全評級係 TBD,主動安全系統包括 Basic。
兩款車嘅安全評級一樣,喺呢個級別入面安全配備都算畀得好齊全。而家嘅新車安全性都唔差,唔使太擔心這一點。
Subaru Outback 車身長 4400 mm,行李廂 400 L。
Land Rover Discovery Sport 車身長 4400 mm,行李廂 400 L。
兩款車嘅尺寸幾乎一樣,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。
Subaru Outback 同 Land Rover Discovery Sport 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌聲譽同二手價,可以優先考慮聲譽更好嗰款;如果你更在意性價比同配備,嗰就揀配置更豐富嗰款。始終都係建議兩款都去試駕,親身體驗先係最重要。
總嘅嚟講,Subaru Outback 同 Land Rover Discovery Sport 都係馬來西亞市場幾唔錯嘅車款。揀邊一輛,關鍵仲要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,先去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

車型概覽

智己汽車IM5 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講整體購車判斷,幫你用買家角度篩走唔適合嘅選擇。 近期市場討論到「Momenta完成來港上市備案 智駕龍頭加速港交所IPO進程」,代表呢類車型仍然有一定關注度。
完稅價 HK$ 398,000 - 568,000 令預算位置更清楚,買家可以先估算月供、保險、泊車同日常開支。
購車價格指南
智己汽車IM5 嘅購車預算可以先由 完稅價 HK$ 398,000 - 568,000 開始計。香港買車唔只係睇車價,月供、保險、牌費、泊車同能源成本都會影響每月壓力。
如果有幾個版本可揀,可以先將 2025 490km 後驅標準版(HK$ 398,000)、2025 710km 後驅長續航版(HK$ 468,000)、2025 615km 四驅性能版(HK$ 568,000)、2026 GTS(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 智己汽車IM5 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
75/100 kWh 嘅電池容量,真正意義係可以幫你估算一星期通勤同周末出車要唔要中途補電。 217/300/572 kW、450/500/802 N·m 嘅輸出,令高速併線同短距離超車更有信心。 車長 4931 mm、車闊 1960 mm、車高 1474 mm、軸距 2950 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。 固定齒比、後置後駆 / 雙電機四駆 會影響起步順滑度、濕地穩定感同長途巡航性格。
優缺點分析
智己汽車IM5 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:預算位置清楚,方便同同級車直接比較、電池同續航資訊有助安排通勤同補電、動力輸出對高速同上斜更有底氣。
要留意嘅係,要先確認屋苑、公司或常去商場嘅充電條件、香港停車場同窄路使用要留意車身闊度。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 智己汽車IM5 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「智己 IM5 (LS6) 喺香港買到嗎?」簡單講,目前 智己 IM5 (LS6) 暫時未引進香港右軚版市場。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 智己汽車IM5 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先用 完稅價 HK$ 398,000 - 568,000 鎖定預算圈、再睇動力係咪足夠應付高速併線同滿載、再比較能源成本同補能便利、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南

擁有 智己汽車IM5 最重要係先諗清楚充電節奏。屋苑、公司或者常去商場只要有穩定充電選項,電動化用車就會容易相處好多。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

車型概覽

Aston Martin Vanquish 值唔值得睇,第一步唔係望牌子或者外形,而係睇佢能唔能夠配合你嘅香港日常。 呢篇會集中講家庭乘坐、行李同舒適度,幫你用買家角度篩走唔適合嘅選擇。
售價仍待確認,買家可以先把佢放入候選名單,等價格落實後再同同級車逐項比較。
購車價格指南
Aston Martin Vanquish 目前售價仍未清晰,較理性嘅做法係先睇版本、車身大小同動力形式,等價格落實後再決定值唔值得落訂。
如果有幾個版本可揀,可以先將 2025 5.2T Standard(價格待確認)、2025 5.2T Volante(價格待確認)、2025 5.2T Volante 60th Anniversary Edition(價格待確認) 放喺同一張清單。日常通勤重視舒適同易用,家庭買家就要優先睇後排、尾箱同安全配置。
核心規格重點
睇 Aston Martin Vanquish 嘅規格,重點唔係背數字,而係理解佢喺香港用車場景會帶嚟咩分別。
雙渦輪增壓、12 個 汽缸 嘅動力底子,重點係市區跟車夠唔夠順、高速巡航會唔會吃力。 835 Ps / 614 kW、1000 N·m 嘅輸出,對滿載、上斜同超車都比單睇馬力數字更有意思。 車長 4855 mm、車闊 2044 mm、車高 1290/1295 mm、軸距 2885 mm 可以幫你預判商場停車場、屋苑車位同後排腿部空間。 手自一體(AT)、前置後駆 會影響起步順滑度、濕地穩定感同長途巡航性格。
優缺點分析
Aston Martin Vanquish 嘅優點唔需要講到天花龍鳳,真正有價值係佢能唔能夠令日常用車更省心:動力輸出對高速同上斜更有底氣、空間同車身尺寸方便家庭買家預判實用性。
要留意嘅係,香港停車場同窄路使用要留意車身闊度、售價未清晰前唔應該太早用性價比落結論。呢啲唔一定係缺點,但係落訂前應該先諗清楚。
買家常見問題
買 Aston Martin Vanquish 之前,真正要問嘅唔係單一規格,而係佢可唔可以融入你每日嘅生活節奏。
常見疑問係「Vanquish Volante 60th Anniversary 特別版有咩特色?」簡單講,Vanquish Volante 60th Anniversary 特別版由 Q by Aston Martin 部門打造,全球限量 60 部。外觀採用專屬 Q Pentland Green 墨綠色車身,配 Westminster Green 綠色軟篷、青銅色飾件(鬼面罩、側腮)及 21 吋緞面青銅輪圈。內櫳採用三色皮革(Cente。 放到實際用車,就係要睇佢對通勤、泊車、家庭乘坐同長期成本有幾大幫助。
同級對比內容
將 Aston Martin Vanquish 放入同級車清單時,唔建議只用外形或者品牌光環決定。比較順序可以係:先等售價落實,再決定佢應該同邊個級距比較、再睇動力係咪足夠應付高速併線同滿載、最後睇車身大小、座位同尾箱是否適合家人。
咁樣篩選會貼近香港買家真實生活:平日塞車、商場泊車、周末去新界、甚至一家人出入,先係一部車每日要面對嘅考驗。
用車全周期指南
擁有 Aston Martin Vanquish 唔係買車一刻就完結,之後仲有保險、輪胎、保養、泊車同日常能源成本要處理。
如果你主要喺市區行,視野、低速順滑度同泊車輔助會好影響心情;如果經常行高速或跨區,座椅舒適度、隔音同動力從容感會更重要。

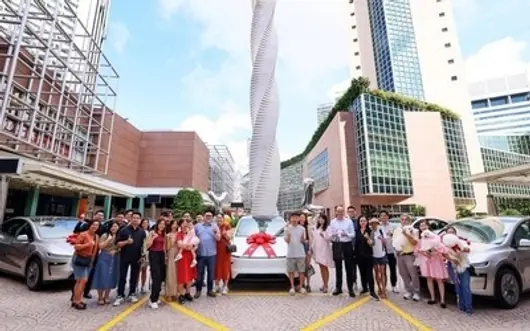
【CNMO 科技消息】5 月 29 日,特斯拉官方宣佈,Model Y L 車型已喺新加坡啟動首批交貨。

Model Y L 喺新加坡啟動首批交貨
據 CNMO 科技了解,今年 5 月,6 座位版 Model Y L 獲得澳洲汽車安全評鑑協會(ANCAP)五星綜合安全評級。Model Y L 喺成人保護、兒童保護、行人及騎行者保護同安全輔助系統四大測試項目中均取得高分成績。該車型此前喺多個市場上市,未來將喺其他市場交付,其後亦會同步參與各地安全機構嘅評測認證。

今年 3 月,特斯拉公司副總裁陶琳曾話,Model Y 上市 7 年,已經連續三年成為全球最暢銷嘅乘用車。Model Y 被權威雜誌《消費者報告》評為“2026 年度最佳電動車”,仲喺澳洲、紐西蘭、日本等市場屢獲殊榮。Model 3 同樣表現亮眼,喺新加坡奪得“2026 年度車型”同“最佳電動轎車”兩項大獎。
值得一提嘅係,近日,特斯拉推出咗 6 月買車福利,Model Y L 首期只需 9.99 萬元,月供可低至約 3,985 元。特斯拉仲推出全新“輕鬆貸”活動,以售價 26.35 萬元嘅 Model Y 後輪驅動版為例,尾款為 52,700 元,首期 55,900 元起,五年嘅最低月供約 2,691 元。
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。

然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。

要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。

高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。

《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。

如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
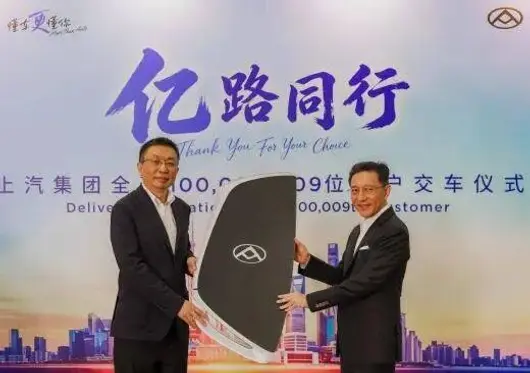
The first in China, SAIC Group's cumulative production and sales exceed 100 million vehicles! On May 28, at the Shanghai North Bund World Living Room, SAIC Group took this place as the origin to launch a global-reaching "First 100 Millionth User" vehicle delivery ceremony, becoming the first automotive group in Chinese automotive history to break 100 million cumulative production and sales. As a global leader in new energy commercial vehicles, SAIC Commercial Vehicles, with Maxus, Keya, IVECO, Hongyan, and Sunwin five brands, completed the global delivery relay from the 100,000,009th to the 100,000,013th vehicle, jointly creating a milestone in the Chinese automotive industry and engraving a historical coordinate for the Chinese commercial vehicle industry.
Behind the 100 million vehicles lies the long-term accumulation and explosive growth of SAIC's 70-plus years of deep cultivation, and it is also a vivid miniature of Chinese commercial vehicles moving from scale leadership to value leadership. Relying on the group's global resource empowerment, SAIC Commercial Vehicles has built the industry's most complete commercial vehicle matrix covering heavy trucks, buses, light trucks, light vans, pickups, MPVs, and RVs, continuously leading the Chinese commercial vehicle industry with a 35% new energy penetration rate and seizing opportunities in the global carbon neutrality wave. With reliable quality, cutting-edge technology, and a complete ecosystem, products are sold in over 100 countries and regions, winning deep trust from top global partners such as DHL, becoming the core force for Chinese commercial vehicles going global, moving in, and moving up.
Continuously leading Chinese brands to go global, Maxus drives global green logistics upgrade with benchmark strength. In Singapore, Maxus delivered eDeliver 5 (domestic Dana V1) to international logistics giant DHL, welcoming the group's 100,000,009th user. This is another milestone moment since both parties joined hands in 2017. Years of deep cultivation, Maxus not only won the largest procurement order of Chinese brands in DHL's European region, but also firmly stayed in its list of preferred partners for green transformation, with cooperation footprints covering Europe, America, Asia, and Oceania. Nowadays, relying on leading product strength and global strategy, Maxus light vans and high-end pickup export volumes firmly rank first in China, building five 10,000-unit level core markets; won C-NCAP, Euro NCAP, ANCAP global three major five-star safety certifications, continuously leading exports in high-end markets such as Singapore, Europe, Australia, and successfully joined the preferred cooperation camp of global top enterprises such as FedEx, DPD, JD.com, SF Express, Cainiao Logistics, with global strength to strongly expand the 100 million user map.


Based on the domestic market, the four brands deeply cultivate two major tracks of livelihood and infrastructure with green capacity. Keya delivered Dana T1 to Dizhantie in Yangzhou, Jiangsu, relying on high load-bearing, long range, and intelligent connectivity advantages to cover green urban distribution scenarios. In 2025, Keya delivered nearly 10,000 units cumulatively to Dizhantie, unblocking urban-rural logistics "capillaries". Sunwin delivered 10-series low-floor pure electric buses in Shanghai, empowering urban public transport smart upgrade with zero-carbon travel. Hongyan delivered i Jieshi dump trucks in Taiyuan, Shanxi, calmly mastering complex mountain operating conditions with military foundation and powerful performance, deeply protecting the construction of a strong country in infrastructure. IVECO delivered Juxing EV in Luoyang, Henan, 100-degree large capacity battery solved the mountain operation range problem, setting a new benchmark for green passenger transport. The four brands relay delivery, welcomed the group's 100,000,010 to 100,000,013th users, jointly casting a 100-million level milestone with hardcore strength.


From domestic core cities to key overseas markets, from logistics delivery and infrastructure engineering to public travel and tourist passenger transport, every delivery of the five brands is a vivid practice of SAIC Commercial Vehicles "Hand in Hand with Chinese Power, Driving the World's Pulse". 100 million users are not the end point, but a new starting point of trust. Facing the future, SAIC Commercial Vehicles will continue to take technological innovation as the core, user value as the guide, lead green transformation, deepen global layout, and write the brilliant chapter of the Chinese commercial vehicle industry on the new journey.
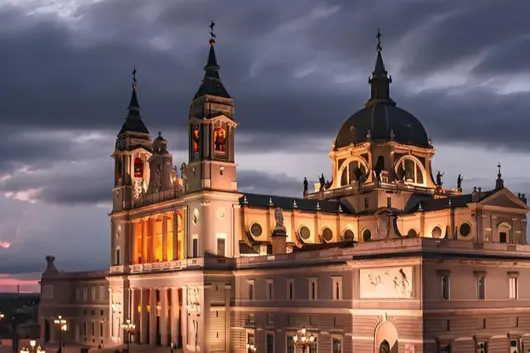
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
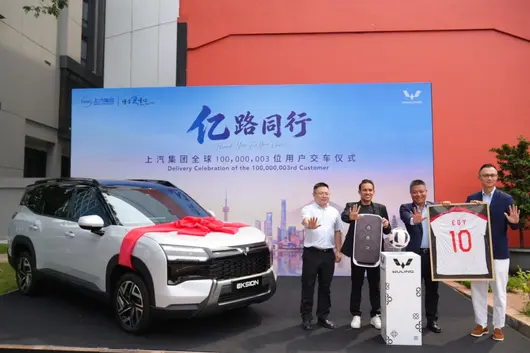
May 28, SAIC Motor Group delivered its 100 millionth vehicle, becoming the first domestic automotive group to have cumulative production and sales volume exceeding 100 million. Among these, SAIC-GM-Wuling contributed more than 32 million units. On the same day, SAIC-GM-Wuling's global model EKSION was delivered to its first batch of users in Jakarta, Indonesia.

"Whatever the people need, Wuling will build it." This saying is not empty talk. Wuling always grasps users' real needs and launches hit models. For example, Wuling Hongguang, which can carry cargo and passengers, is durable and tough, becoming a reliable helper for countless entrepreneurs and families. Later, as living standards improved, Baojun 730 broke the monopoly of joint venture brands in the MPV market with its flexible space and affordable price. In 2020, catching the window of opportunity for new energy transition, Hongguang Mini EV went viral and became one of the pioneers among domestic small electric commuter cars. This May, Wuling partnered with Huawei Qukun to launch the first technological flagship large six-seater SUV — Huajing S, breaking down the price threshold for high-end intelligent driving.
Wuling is not only accelerating its layout in new energy and intelligence, but its overseas market is also going deeper. Currently, Wuling's cumulative overseas sales have exceeded 1.5 million units, covering business in over 110 countries and regions worldwide.

The reason Wuling has come this far lies in three "skills": First, the globally first intelligent island manufacturing system, simply put, is "vehicles find workstations, materials find vehicles", using flexible production methods to improve efficiency and reduce costs; Second, launching different models for different countries, such as EKSION (Starlight 560), DARION (Starlight 730), BINGO (Wuling Bingo), BINGO S (Bingo S), etc., covering SUVs, MPVs, and sedans to meet the diverse needs of users in various places; Third, the unique "moving supply chain overseas" model, deeply binding the five chains of manufacturing, supply, sales, finance, and talent, no longer simply selling cars, but pushing the entire system and standards of Chinese smart manufacturing to the globe.

This global car EKSION delivered in Indonesia this time is the latest achievement of Wuling's globalization strategy. Taking Indonesia as the core, Wuling continues to deeply cultivate the "Indonesia-Malaysia-Thailand" integrated regional strategy, gradually covering new energy products and localized supply chains to Malaysia and Thailand, and will radiate to ASEAN countries such as Vietnam and the Philippines in the future, forming a globalization pattern of regional linkage and common development.
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
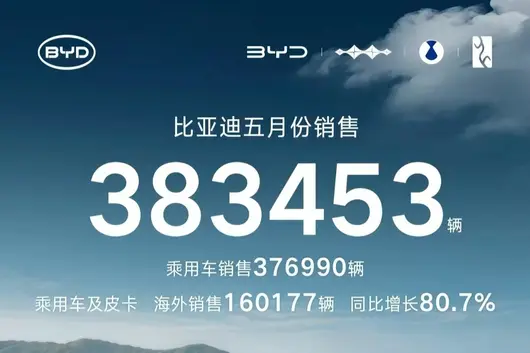
BYD officially released the May 2026 production and sales flash report, with new energy vehicles from all brands reaching a monthly sales volume of 383,453 vehicles, a slight increase of 0.26% year-on-year, achieving year-on-year positive growth in monthly sales after ten months; among them, passenger car deliveries reached 376,990 units, surging 19.4% month-on-month, wiping out the pain of previous model iterations, presenting a new pattern where the domestic base is stable, overseas sales are soaring, and high-end brands are scaling up across the board. Amidst the market environment of intensified competition in the domestic new energy sector, Tesla FSD entering China, and an intense launch of independent new products, it has forged a unique structural growth path.

The Dynasty and Ocean main brands combined sold 330,215 vehicles in May, accounting for over 80% of the group's total sales, remaining the stabilizer for BYD's sales volume. The full series had 8 models exceeding 20,000 units in monthly sales, covering products from 50,000 entry-level commuter to 200,000 home SUV.

Inside the Dynasty Network, the Yuan family sold 56,691 units, and the Song family 51,370 units. Both crossed the 50,000 threshold, becoming two major sales pillars for the brand, catering to home commuter and urban-rural travel needs; the Qin family followed closely with a stable performance of 28,360 units. The Han and Tang series maintained a volume in the six-thousand range, deeply cultivating the mid-to-large home sedan and SUV niche markets; the brand new model Xia is in the market cultivation phase, delivering 1,810 units monthly, with potential for steady volume growth as channels expand.
The Ocean Network's growth momentum is even more rapid, with 5 models entering the 20,000 club across the series: Sealion 42,615 units, Seal 34,117 units, Seagull 39,919 units, Dolphin 22,260 units, and Song PLUS 27,755 units. Among them, Seagull remains the best-selling entry-level commuter model thanks to its affordable pricing of 60,000-80,000. Sealion, as a new volume model, stands firm at the 40,000 level upon launch, filling the mid-size SUV product gap in the Ocean Network and perfecting the Ocean product tier layout. From commuter small cars to compact SUVs, the two main brands rely on DM-i hybrid and pure electric dual-line technologies to牢牢锁住 the mainstream home market share within 150,000 domestically.
Fang Cheng Bao Year-on-Year Surges 139.7%, Brand Upward Positioning Takes EffectThe high-end matrix of Denza, Fang Cheng Bao, and Yangwang sold a combined 46,489 vehicles in May, officially breaking away from the niche positioning to become a new pivot for BYD's brand premium and profit growth, breaking the industry curse of difficulty in high-end breakthrough for domestic brands.

The off-road brand Fang Cheng Bao sold 30,186 units monthly, surging 139.7% year-on-year, creating a new high in monthly sales since the brand launched. Its Titanium 7 model sold 18,280 units monthly, while Leopard 5 and Leopard 8 output remained stable, continuously squeezing the survival space for joint venture and imported models in the 250,000-400,000 hardcore off-road niche market.

Denza delivered 16,303 units in May, with the MPV benchmark D9 selling 6,721 units, and the Z9 series close to 6,000 units. MPV and mid-to-large sedan dual-line efforts helped them stand firm in the luxury new energy track; the million-level ultra-luxury brand Yangwang continued its steady climb, delivering 286 units that month, a year-on-year increase of 105.8%, completing market verification of the domestic brand ceiling product and forming a full price range product layout from 100,000+ home, 300,000-400,000 off-road, 500,000 luxury MPV to million-level flagship.

In May, BYD's overseas sales of passenger cars and pickup trucks reached 160,177 units, surging 80.7% year-on-year. Exports accounted for over 42% of the full series total sales, setting a new historical high for brand export and becoming the core driving force to stabilize May overall sales and achieve year-on-year positive growth.
Southeast Asia, Europe, and Latin America became the main incremental markets. Seagull, Song PLUS, and Yuan series continued to top new energy best-seller lists in multiple countries; the SHARK pickup truck exceeded 4,000 units in monthly exports for two consecutive months. Relying on the completion of localization production in Thailand, Brazil, Hungary, and Uzbekistan with four overseas vehicle factories, localized production continues to land, avoiding tariffs while rapidly penetrating terminal channels. Against the background of stock market competition in the domestic auto industry and normalized price wars, the rapidly expanding overseas market effectively counteracts sales volatility brought by domestic model iterations, officially upgrading from a supplementary market to BYD's core growth engine. As of now, BYD's global cumulative new energy vehicle sales have exceeded 16.5 million units, with the globalization map continuously broadening.
Intelligent Driving Empowers Product Iteration, H2 New Products Prepare to Surge VolumeMay marked a key node in BYD's intelligent driving landing, with the God's Eye intelligent driving system becoming a core bonus point for models: the number of vehicles with advanced intelligent driving across all brands exceeded 3.15 million, with daily road test data exceeding 200 million kilometers; that month, BYD implemented City Pilot and Smart Parking dual safety backup services, becoming the world's first auto manufacturer to achieve dual intelligent driving backups. Three days after policy implementation, the activation rate of models equipped with the God's Eye system in cities surged 50%. Intelligent driving experience upgrades directly drove in-store order conversion, solidifying product competitiveness for subsequent models to continue volume sales, and facing the intelligent driving market shock brought by FSD entering China.
From data details, BYD's cumulative sales from January to May 2026 were 1,405,039 units, down 20.32% year-on-year. The core reason is that the full series of main models were concentratedly iterated, and the capacity ramp-up of the 2nd Gen Fast Charge Blade Battery was restricted. The new Flash Charge Battery upgraded fast charging and low-temperature performance. Full series iteration models prioritized installing new batteries, but production line retrofitting dragged down capacity release. Order backlogs on popular models and delayed deliveries compressed the May delivery volume to a certain extent.
As the end of the second quarter approaches and the 2nd Gen Blade Battery capacity continues to release, coupled with new models such as Denza N8L, Fang Cheng Bao Titanium 7 Pure Electric Version, Sealion 05, and Xia L landing the market, the industry generally predicts that BYD's full brand sales in June are expected to exceed 400,000 vehicles. Relying on the four-dimension development logic of low-end volume locking share, high-end raising profit, overseas pushing volume, and intelligence improving product power, amidst the intensified new energy elimination round in the domestic market, BYD's full category layout advantage continues to amplify, securing its status as the domestic new energy leader, accelerating steadily towards global top auto manufacturers.