


首頁180SX S13

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
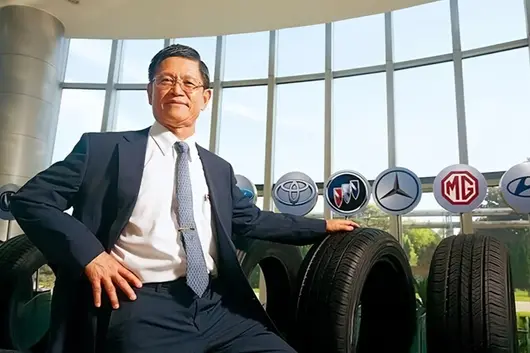
5 月 26 日,台灣輪胎巨頭正新橡膠召開股東大會,順利完成董事會全面改選,核心高層團隊實現交棒。創始人次子羅才仁正式接替陳榮華出任董事長,原總經理李進昌升任副董事長,而總經理一職則由正新“第三代生力軍”羅元隆接掌。此舉標誌著正新橡膠正式進入新老交接與戰略升級嘅新階段。

核心管理層落定:老將坐鎮與新銳領航
此次高層變動體現了正新橡膠“穩中求進”嘅交接思路。新任董事長羅才仁(1953 年生,台灣彰化人),其早年曾長期深耕一線,歷任正新輪胎(中國)總經理與董事長,對中國大陸市場極為熟悉。據相關資料,羅才仁家族財富達 195 億元。

升任副董事長嘅李進昌為原總經理,其豐富嘅經營管理經驗將繼續為集團保駕護航;而新任總經理羅元隆嘅履新,則代表著正新第三代接班人正式走向台前,承擔起一線營運重任。

在新一屆董事會陣容中,除上述核心三人外,還包括正新總裁陳秀雄、美利達董事長曾嵩柱及陳涵琦。獨立董事則由吳中書、朱博湧、許捷忠組成,專業背景涵蓋宏觀經濟、企業戰略等領域,將為公司管治提供獨立視角。
瞄準全球高階市場,確立四大核心成長引擎
面對全球汽車產業與輪胎市場嘅激烈競爭,正新橡膠新經營團隊已明確戰略方向,制定出四大核心成長引擎以驅動未來業績:
打入歐洲高階汽車供應鏈:持續深化與全球頂尖汽車廠商嘅 OEM 合作,提升品牌喺高端整車市場嘅滲透率與話語權。
開發高附加值產品:聚焦高性能輪胎嘅研發與製造,優化產品結構,提升整體盈利能力。
重兵布陣印度與印尼市場:將南亞與東南亞作為關鍵增長極,搶佔新興市場嘅人口與汽車增量紅利。
數位化賦能競賽型輪胎:運用數位化技術研發運動及競賽型輪胎,以賽道級科技反哺民用市場,確保公司喺技術領域嘅領先地位。

內地深耕與百億版圖
作為全球輪胎橡膠行業嘅大型製造商,正新橡膠嘅中國營運總部設於江蘇崑山,旗下「正新/Maxxis」品牌已具備廣泛嘅全球影響力。2024 年,正新橡膠全年營收達 960 億新臺幣。在全新嘅管理團隊與四大引擎嘅驅動下,這家老牌輪胎巨頭能否喺高端化與全球化嘅新賽道上實現跨越,值得業界持續關注。
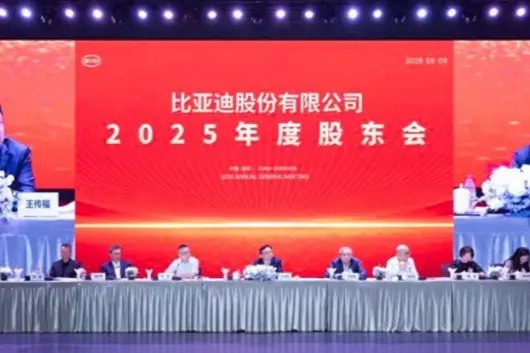
6 月 9 日,比亞迪召開 2025 年度股東大會。董事會主席兼總裁王傳福的演講內容亦涵蓋了短期業績、技術研發、智能駕駛、海外戰略及長期目標等多個範疇。

「今年一季度,新能源車經歷了至暗時刻。」
2026 年 1 月開始新能源車購置稅政策減半,導致去年底需求前置,新能源乘用車零售滲透率大幅下降。比亞迪只做新能源車,難免受到影響。
「最壞的時刻已經過去了。」
隨著 3 月發布二代刀片電池和閃充技術,比亞迪訂單開始回升,5 月銷量已經開始轉正,年底經營現金流有望逐步恢復到較好水平。
「今年的銷量取決於電池的產能。」
二代刀片電池產能還是不夠,目前正在以每月兩萬到三萬的增量在爬坡。明年我們的產能完成爬坡以後,相信將在全球兩個市場同時發力。
二、關於長期目標:五年做到全球第一「五年以後,比亞迪在規模上,能夠做到真正的全球第一。」
未來三到五年,比亞迪仍將保持持續增長。憑藉二代刀片電池、閃充技術以及明後年推出的新技術,國內、國外有望實現雙輪驅動,形成良性互動,讓中國的技術走向全球。
三、關於技術理念與閃充開放「汽車行業曾經充斥著各種花巧虛榮的流量,但實際上汽車是涉及安全的交通工具。」
少一些套路、少一些花巧,回到本源,做好技術和產品,才能獲得中高端消費者認可。
「比亞迪不會把閃充技術‘據為己有’。」
充電樁上不打比亞迪 Logo,閃充生態將服務所有汽車品牌和所有消費者。好的技術除了為比亞迪服務,更要為整個行業服務。而與中國石化的合作,將極大推動閃充技術的擴張。
四、關於智能化與 L3 準備「整車智能就是具身智能。」
比亞迪已經有 315 萬台智駕車型在全球落地,每天產生超過 2 億公里智駕相關行駛數據,智能駕駛研發工程師規模超過 5000 人。未來累計投入將超 1000 億。
「未來 L3、L4 一定會提前落地。」
比亞迪已經在晶片(4 納米的智駕晶片璇玑 A3 不久前剛發布)、演算法、數據、生態等方面做好充足準備,包括在歐洲、南美洲、東南亞、中東等地區的訓練中心都已做好準備。一旦法規落地,比亞迪就將推出全系列的、符合 L3 要求的产品。
五、關於全球化與海外市場「我們年初設定的 2026 年海外銷量目標是 150 萬輛,現在預計應該會超越這個目標。」
以比亞迪為代表的中國車企在產品競爭力、價格、體驗和技術上,已經超越當地很多同行。
「在海外市場一定要做好本地化。」
比亞迪在南美洲構建了以巴西為主生產基地,歐洲匈牙利工廠即將投產,東南亞泰國工廠已經投產。出口不僅要增長,還要能維持本地化服務,實現和本地共贏、共發展。
六、關於工程師文化與企業價值觀「比亞迪有 12 萬名工程師,這是公司真正的財富。」
工程師文化後繼有人,不用擔心。我每周有一半時間用於參加技術會議,與工程師交流,“在技術的海洋裡游泳”是我最感興趣的事。

Author: Guan Hongye
Who Leads the Tide — A Milestone for SAIC's 100 Million Vehicles and a Watershed Moment for the Chinese Automotive Industry.
Rivers surge and peaks compete. In the 2026 Chinese automotive market, unprecedented scenes are surging forward.
Local brands have broken through a market share of 60%, new energy vehicle penetration is approaching 40%, and export volume has ranked first globally for two consecutive years... This is not merely a pile of numbers, but a profound structural transformation. Chinese cars have shed the old label of "large but not strong", and now stand on the map of the global automotive industry, using wheels as the brush and mountains and rivers as the ink to write their own majestic footnotes.
Amidst the magnificent progress of Chinese automobiles, on May 28, 2026, SAIC Group became the first domestic automaker to reach this historic milestone with a cumulative production and sales volume of 100 million vehicles.
The formation of any industry's landmark volume is not the work of a day or two, but the result of long-term resonance between the general trend of the times, industrial iteration, and corporate resolve.
Behind the "100 million vehicles" lies not only the ceiling of one company's growth, but a microcosm of China Manufacturing's independence, autonomy, and self-strengthening, and even more so, an epic of growth where the enterprise and industry grow in sync and share in the ups and downs.
Understanding SAIC's "100 million vehicles" is to understand the growth code of Chinese automobiles moving from large to strong, breaking the cocoon and becoming a butterfly.
Protagonist: A Global Relay of 100 Million Trusts
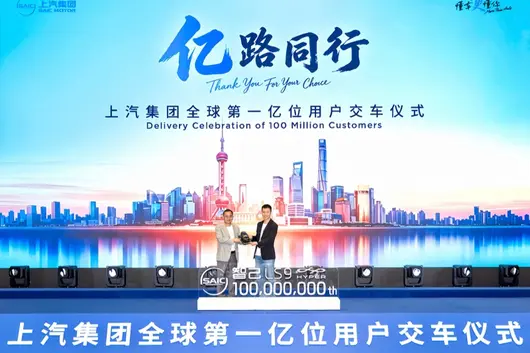
On the afternoon of May 28, the Shanghai North Bund World Living Room. This place has witnessed a century of tides on both sides of the Huangpu River, the exchange and dialogue of Chinese and foreign civilizations, and many historic moments when China opened its doors to the world. And today, a "Global Relay Delivery" spanning the Asian and European continents is about to unfold here.
The camera starts from the banks of the Huangpu River, sweeps across the ocean, and lands in London — a young doctor receives the keys to the MG4 EV from his grandfather, inheriting the legacy; it turns to Jakarta, where an Indonesian men's football national player sits in the Wuling Eksion, heading towards the distance; it comes to the Singapore DHL regional center, where a batch of Maxus eDeliver5 pure electric light trucks goes into operation, mission accomplished. In Shanghai Anting, in Liuzhou, Guangxi, in Lantian, Shaanxi... 15 brands, 18 models, multiple time zones, multiple cities succeeding each other, completing a historic delivery spanning mountains and seas, resonating in sync.
The special thing about this delivery is that users were pushed to the center of the stage. There was no deliberate positioning, only a handoff of keys stick after stick, and a silent relay of 100 million trusts.
The 100 millionth user was Momenta CEO Cao Xudong. This is highly symbolic — Cao Xudong not only became the 001st owner of the LS9 Hyper himself, but also announced at the delivery site that L3 autonomous driving will be launched first by SAIC.

There are more stories worth remembering.
Luo Zhenyu, founder of the GetAPP, became the 001st experimenter of the Huajing S; former German national football player Yang Chen chose the ID.ERA 9X, as its golden hybrid and long-termism were in sync; 85-born village secretary Pang Fuqiang delivered meals to elderly people left behind using a Wuling Rongguang pure electric vehicle; a tech media blogger was moved by the Huawei smart driving of the Shangjie Z7; bulk users such as DHL and Jiading Bus — behind every commercial vehicle is a "wealth creation tool" for the strivers.
This is a delivery ceremony without an absolute protagonist, yet where everyone is the protagonist. 100 million vehicles is not just a number rolling over on the production line, but 100 million real, specific, and warm choices.
And only SAIC has the capability to complete such a global relay: Wuling deepens into the people's livelihood and inclusive market, MG flies the flag of Chinese brands going global, IM Motors pushes into the global high-end intelligent manufacturing track, Shangjie promotes the inclusiveness of intelligent technology for the public, plus a mature and profound matrix of joint venture brands — this is no longer a simple delivery, but a panoramic parade of SAIC's seventy-year system competitiveness, a comprehensive practical exercise.
Scale: Three Leaps Behind 100 Million Vehicles
Fifteen brands, eighteen models, multiple time zones, 100 million trusts — this ruler measuring the thickness of the Chinese automotive industry clearly records the deep value at the three levels of enterprise, industry, and country.
Enterprise Dimension: From an alley workshop to a giant of 100 million vehicles.
In 1955, the Shanghai Internal Engine Parts Manufacturing Company was established, with only workshops in alleyways and a group of enthusiastic workers. In 1958, workers hammered out the first Phoenix brand sedan with hammers — "A golden phoenix flies out of a straw nest". Seventy years later, SAIC became China's first automotive group to break through 100 million cumulative production and sales.
What is more noteworthy is the structural change: over ten years, the proportion of local brands rose from 38.0% to 65.0%, new energy penetration rose from 0.2% to 36.4%, and overseas sales increased from 697,000 vehicles to 1.071 million vehicles. This is a profound transformation of "trading structure for scale" — numbers are adjusting, quality is leaping. Outside of 100 million vehicles, challenges still exist, but SAIC has bid farewell to the old era of making money solely from joint ventures; the sequel to scale will be written by technology-driven.

Industry Dimension: From "Market for Technology" to "Defined by China".
SAIC's 100 million vehicles is a bright mirror of the rise of Chinese automobiles. Forty-odd years ago we traded market for technology; today Chinese car companies begin to export technology, standards, and ecosystems to the world.
Especially "Autonomous, New Energy, Export" — the New Three Items have become the core support of the Chinese automotive industry. Local brands have broken through a market share of 60%; new energy penetration is approaching 40%. SAIC started with 1,125 new energy vehicles from the 2010 World Expo and ended 2024 with 1.368 million vehicles delivered at terminals; semi-solid-state batteries, zero-combustion magic cube batteries, and other technologies lead the world; exports have ranked first globally for two consecutive years. SAIC products are distributed in over 170 countries, with cumulative overseas deliveries exceeding 7 million vehicles; MG has been the top-selling Chinese brand in Europe for 11 consecutive years.
In 2025, Chinese automobile production and sales ranked first globally for 17 consecutive years, and new energy vehicles ranked first globally for 11 consecutive years. Innovation has moved from "single-point breakthroughs" to "systematic promotion". SAIC has cumulatively invested over 150 billion yuan in R&D, with nearly 25,000 valid patents. Semi-solid-state batteries were mass-produced first, steer-by-wire was implemented, and dual L4 licenses were secured — hard-core technology has moved from the "bookshelf" to the "store shelf".
National Dimension: From Economic Pillar to World Business Card.
In 2023, China's automotive industry output value reached 11 trillion yuan, accounting for nearly 10% of GDP, exceeding real estate for the first time as the primary economic pillar, with direct and indirect employment exceeding 30 million people. Strong automobiles mean strong manufacturing; strong manufacturing means a stable Chinese economy.

SAIC's globalization is upgrading from "Product Going Global" to "Value Chain Going Global". Relying on three R&D centers and four overseas manufacturing bases, the self-operated RoRo fleet has reached 41 ships, with routes covering the globe. This is not just growth in export data, but a profound reconstruction of global capabilities. The technology and products of Chinese intelligence are bringing greener and smarter travel choices to global users — this is the most vivid world meaning of "Made in China".
Genetics: The Underlying Logic of 100 Million Choices
100 million vehicles is not just a number. It is more like a milestone, leading us to look back: on what basis did this group reach today?
Over seventy years of prosperity, leading the way through multiple waves of industry changes, is not accidental. Amidst the ups and downs where wind tunnels alternate one after another and frivolity prevails, SAIC has precipitated three core genes: dare to break through, good at coexisting, and valuing original intentions — this is the fundamental confidence for enterprises to cross cycles and resist risks, and the most precious spiritual base color for high-quality industrial enterprises in China.
Dare to break through, do not stick to the comfort zone.
In 1958, workers in an alley workshop hammered out the Phoenix brand sedan with hammers — "A golden phoenix flies out of a straw nest". This is the simplest interpretation of "knowing cars": even without conditions, create conditions to build cars and let Chinese people drive their own sedans.

In 1987, the localization rate of the Santana was only 2.7%. Zhu Rongji proposed "Never do substitute engineering". The Shanghai Automotive Gear Factory sent 43 people to Germany to disassemble and transport second-hand transmission equipment. In 1989, the domestic Santana transmission was born, with quality fully meeting standards. By 1993, the localization rate exceeded 80%.

In 2016, SAIC and Alibaba crossed boundaries to launch the Roewe RX5, the world's first mass-produced Internet car. Jack Ma sighed that "the driving force needed for innovation to land is huge", but SAIC dared to be the first to move, evolving cars from mechanical tools into intelligent terminals. This breakthrough was the starting point of "understanding you" — users need not just transportation, but a partner connected to digital life.

In the Intelligent Electric Era, from mass-producing semi-solid-state batteries to implementing steer-by-wire, from dual L4 licenses to AI large models on cars, SAIC has always responded to "how to understand users better" with technological breakthroughs — range anxiety? Solved. Control pain points? Solved. Smart experience? From understanding commands to predicting needs.

Not sticking to past achievements, not following industry trends blindly, seeking survival in change and developing in innovation — this is the development base color that SAIC has always followed.
Good at coexisting, do not build cars in isolation.
In the 1980s, SAIC gathered the strength of the city to overcome parts localization. German experts taught technology, Chinese workers learned craftsmanship. German experts sent coffee for Chinese workers, Chinese workers invited German experts home for Chinese New Year. Cooperation was to let Chinese users have cars of world-class quality — this is the original intention of "understanding you" in itself.
In 1998, the Shanghai General Motors project was built and put into production in just 23 months, creating "Shanghai Speed". The chairman of General Motors of the US sighed: "We brought the management and technology of General Motors in the US to Shanghai General Motors, we also want to bring the construction speed of Shanghai General Motors back to the US."
Today, SAIC never becomes an "ecosystem island". With Huawei, the Stelato was launched, bringing high-level intelligent driving into the 150,000 yuan family bracket; in-depth co-creation with Momenta, intelligent driving solutions empower IM Motors, Volkswagen, Audi, Buick, Cadillac, and other brands; together with tech companies such as OPPO, Doubao, and Horizon Robotics, they turn AI large models, intelligent cockpits, and chip computing power into smooth experiences that users can touch and feel.

The 100 millionth user is the Momenta CEO — partners becoming car owners, this is the most vivid persuasiveness of an open co-creation ecosystem.
Openness is not dependency, coexistence is not compromise, but turning external resources into own technology, product, and service capabilities, ultimately benefiting thousands of users.
Valuing original intentions, not betraying trust.
The iron law of Santana localization "Never do substitute engineering" continues today in every factory and production line of SAIC. From promoting the concept change with small matters like "Toilet Revolution" to making "exquisiteness" the vow of quality work — users do not understand technical parameters, but they understand "This car is reliable to use".
Fengxiang supplied bumpers for Shanghai General Motors. The first batch of products met the standards, but General Motors required higher quality. The general manager said nothing and sawed off that bumper on the spot: "Customers are God. What God does not want is to be sawed off."
This obsession with quality eventually turned into the reputation of "10-year fade-proof paint", "zero self-ignition battery", "300,000 kilometers without major overhaul". Quality is the baseline of "understanding you". No "understanding" can leave "reliability". SAIC exchanged 70 years of quality adherence for 100 million times of trust choice by users.

Three cultures, one lineage. Breakthrough makes SAIC constantly break boundaries; coexistence makes SAIC gather global wisdom; original intention makes SAIC win user trust. These three genes eventually converge into one simple promise: Know cars, understand you better.
Knowing cars is the extreme pursuit of core technology. Understanding you is to accurately implement every frontier technology into a perceivable and enjoyable美好 travel experience for users. "Know cars, understand you better" is not a slogan, but an action guideline that runs through SAIC.

Just as the temperature conveyed by the global delivery ceremony — no deliberate positioning, only a handoff of keys stick after stick, and 100 million trusts completing the relay.
Journey: 100 Million Is Not the End, The New Journey Surpasses the Past
In 1955, a starting point of a small alley workshop.
In 1983, the first Santana assembly was off the line, localization rate 2.7%. The German Spiegel asserted the project might fail.
In 2006, the first Roewe 750 was off the line, breaking the ice for local brands.
In 2016, the first Internet car Roewe RX5 was launched.
On May 28, 2026, the global 100 millionth user was delivered.
This is a long-distance run spanning over 70 years. Every leg was accompanied by doubts and challenges, and every step stepped on the key nodes of the Chinese automotive industry.

100 million vehicles is a milestone and also a watershed. The era of wild growth for the Chinese automotive industry has ended, and the old path of extensive scale expansion and homogeneous low-price competition has reached its end. SAIC has bid farewell to the traditional thinking of "scale priority" and is accelerating the deep transformation into a user-oriented high-tech travel company.
On the technical end, deepen the "Three Electrics", intelligent driving, digital chassis, AI cockpit, and promote technology equality; on the market end, consolidate the local brand base, deepen the globalization strategy, and promote the full-range global export of brands, technology, standards, and ecosystems; on the industrial end, persist in open coexistence and build a more vital intelligent travel ecosystem.
From the faint starlight in Shanghai alleyways to the industrial galaxy of 100 million volumes; from passively following overseas standards to proactively defining the industry's future; from a single vehicle manufacturing enterprise to a technology travel service provider with a full domain layout — SAIC's 70 years is an engineering history of a single enterprise, and more so, an evolutionary history of the Chinese automotive industry's turbulent advancement, seeking light and rising upward.

Now, standing on a new starting point, SAIC's next 100 million vehicles will also present a more distinct new posture: Local brands as the flag, global as the boundary, technology as the core. The road ahead will be run faster and travel farther, making Chinese automobiles not only have the weight of scale, but also the power of technology, the gold content of brands, and truly stand at the top of the world.
100 million is not the end — the road ahead is long, the journey is not yet finished.
兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。
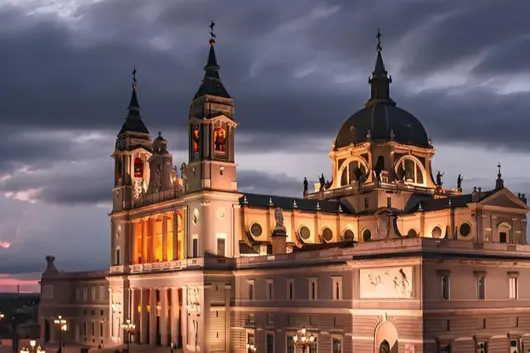
兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.

港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。

喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。

天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。

截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。

喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。

2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。

喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。

截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。

營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。

更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。

此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。

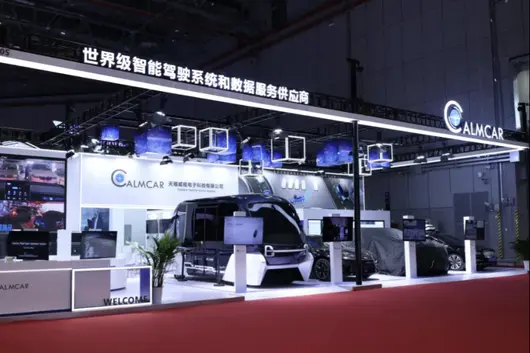
天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。
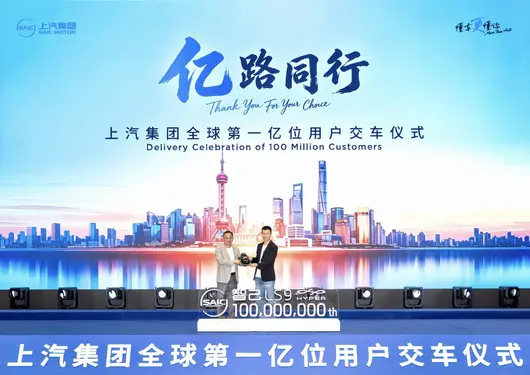
On May 28, 2026, SAIC Motor Group held the "Global 100 Millionth Vehicle Delivery Ceremony" at the Shanghai North Bund World Hall. SAIC Motor, with over ten passenger car brands and nineteen vehicle models under its umbrella, achieved "global relay delivery," crossing mountains and seas, spanning continents, and connecting globally. SAIC Motor Group thus became the first Chinese automotive group to accumulate a production and sales volume exceeding 100 million vehicles, creating a new milestone for the Chinese automotive industry.
From "Phoenix" to "IM": 100 Million Vehicles Witness the Striving and Original Intention of China's Automotive Industry
In 1955, the Shanghai Internal Combustion Engine Parts Manufacturing Company was established, marking the beginning of Shanghai's automotive industry. In 1958, workers used hammers to hammer out the first "Phoenix" sedan, achieving a "zero breakthrough" in Shanghai car manufacturing. For over seven decades, SAIC has witnessed and driven the entire process of China's automotive industry from nothing to something, from weak to strong: In 1983, the Santana went off the line, kickstarting joint venture cooperation; In 1997, Shanghai GM was established, creating the "Shanghai Speed" of building a factory and launching cars in 23 months; In 2006, the independent brand Roewe was born; In 2016, the world's first internet car, Roewe RX5, was launched; In 2020, the premium smart electric brand IM Motors was established.
Running through this journey is SAIC's consistent user philosophy of "Knows Cars, Knows You Even Better". Knowing cars means pursuing core technologies to the extreme; knowing you means accurately implementing every frontier technology into a travel experience that users can perceive and enjoy. From the Santana localization community to Joint Venture 2.0 technology co-creation, from internet cars to full-wire chassis, solid-state/semi-solid-state batteries, and AI large models entering vehicles — every leap is an advancement of "knowing cars" capability and a continuity of the original intention of "knowing you". 100 million vehicles are, more importantly, a concentrated fulfillment of 100 million units of user trust.
100 Millionth Vehicle: IM LS9 Hyper, Concentrating over 70 Years of SAIC Technology
The first 100 millionth delivery vehicle, the IM LS9 Hyper, is the culmination of SAIC's over 70 years of technology accumulation, opening a new era for new energy vehicles' "New Three Major Components". It is equipped with next-generation chassis technology, full wire-steer four-wheel steering launching in its class; next-generation intelligent driving hardware, 520-line super vision LiDAR + NVIDIA Thor chip, next-generation three-electrics — global 800V high-voltage platform and Stellar Super Range Extender. It comprehensively pre-embedded redundancy capabilities for continuous evolution towards L3 and higher autonomous driving. Meanwhile, the IM LS9 Hyper features the SAIC Gold Badge Hurricane Three-Motor for the first time, calmly entering the 3-second performance club; it also co-developed with Purple Mountain Laboratories to launch the "Intrinsic Security" technology globally for the first time, expanding the automotive safety boundary from "Physical Security" to "Information and System Security", serving as a necessary security cornerstone for the AI era.
The 100 millionth user, Momenta CEO Cao Xudong, is indeed SAIC's core strategic partner in the field of intelligent driving. The intelligent driving technology co-created in depth by both parties has empowered multiple independent and joint-venture brands. "Partners become owners" is not only a satisfactory delivery between manufacturers and users but also a deep resonance between smart car ecosystem partners.
System Strength: Global Relay Delivery of SAIC's Full Brand Matrix
Behind the 100 million vehicles lies SAIC's full value chain closed loop covering six major sectors: passenger vehicles, parts, mobility and services, finance, international operations, and innovative technology. From January to April 2026, SAIC's cumulative sales reached 1.302 million units, ranking first among Chinese automakers for four consecutive months. Among them, independent brand sales were 910,000 units, accounting for nearly 70%; new energy vehicle sales were 412,000 units; overseas market sales were 459,000 units, a surge of 50.2% year-on-year.
At the delivery ceremony scene, SAIC's full brands and full product matrix worked together. Independent brands launched fully:Shangjie Z7, Huajing S, Roewe M7, MG4 semi-solid-state battery version, Wuling Starlight 560, Maxus eDeliver5, Hongyan heavy truck, Yuejin Dannan T1, Sunwin pure electric bus, Iveco Juxing EV, etc., were successively delivered, covering multiple scenarios such as personal travel, family life, commercial operation, and logistics transportation. Joint venture brands showcased "Joint Venture 2.0" results: Volkswagen ID. ERA 9X will globally premiere with the Momenta R7 Reinforcement Learning World Model, with delivery breaking 7,000 units one month after launch; AUDI E7X plans to become Audi's first model globally to implement L3-level autonomous driving landing; Buick Zhijing E7 is built based on the "Xiaoyao" super fusion architecture, breaking 10,000 units delivery one month after launch.
Starting from the Shanghai main venue, the delivery scenes were successively lit up in many domestic cities such as Nanjing, Liuzhou, Taiyuan, as well as countries like the UK, Indonesia, and Singapore, creating a new narrative method for Chinese automotive brands. Behind this lies the deep foundation of SAIC's global layout. SAIC is a pioneer among Chinese automotive enterprises in "Going Global": It owns over 100 parts production bases and over 3,000 dealer networks overseas, has built 3 major R&D innovation centers such as London, and 4 production and manufacturing centers in Thailand, Indonesia, India, and Pakistan; Anji Logistics possesses 42 ro-ro ships of various types, with 8 international routes covering Southeast Asia, Europe, and the Americas. Now, SAIC's products and services are spread across more than 170 countries and regions, with cumulative overseas sales breaking 7 million units. SAIC MG has ranked first in European sales among Chinese brands for 11 consecutive years; in 2025, annual sales in Europe broke 300,000 units, becoming the first Chinese automotive brand to accumulate sales of over 1 million in Europe and the UK. This March, MG held a technology day in Frankfurt, Germany, globally premiering semi-solid-state batteries and Hybrid+ hybrid technology; the Hybrid+ family's overseas single-month sales have already broken 20,000 units. In 2025, SAIC released the overseas "Glocal Strategy" (Global + Local), accelerating the shift from "Product Export" to "Value Chain Export", letting "Made in China" go further to the world.
From "Know Cars" to "Know You": A Delivery Gala Where Users Take the Lead
The ultimate focus of "Know Cars, Know You Even Better" is the travel life of every real user. Dedao APP founder Luo Zhenyu, as the 001 Test Officer for Huajing S, went from praising Huawei Qiankun Intelligent Driving at the New Year's Eve speech to walking into the factory to witness the line-down; Former German footballer Yang Chen chose ID.ERA 9X, as its golden range extender and long-termism coincided perfectly; After Cao Kailiang ordered a car for his whole family, his idol Jay Chou happened to become the spokesperson for the Buick MPV family; Public welfare blogger Liu Jia cut hair and sent companionship to left-behind children in Guangxi mountains for five consecutive years, Buick provided assistance immediately, and he was moved by Zhijing E7's "Full Score Cabin". From self-media bloggers to village secretaries, from public welfare guardians to logistics enterprises — every user is a microcosm of real life, which is the most vivid interpretation of "Know Cars, Know You Even Better".

100 million vehicles are a phased answer sheet for SAIC's over 70 years of development, and more importantly, a new starting line for SAIC facing the smart-electric future's "Second Entrepreneurship". In 2014, SAIC actively implemented the important instruction of "Developing new energy vehicles is an inevitable path for China to move from a major automotive country to a strong automotive country", taking the lead in comprehensive transformation. Twelve years later, from "leading the way" in smart-electric transformation to the "thousands of horses galloping" in independent and joint ventures, passenger and commercial vehicles, and domestic and overseas, SAIC will continue to use "Know Cars, Know You Even Better" as its user philosophy, letting technological innovation truly benefit every user.
From 1955 to 2026, from the first user to the 100 millionth user, from initial exploration to industry leadership — SAIC will continue to journey 100 million miles together with global users and global partners, co-creating a new future for beautiful travel.
港交所網站掛出一咗一份熟悉嘅招股書。
5 月 28 日,繼去年 10 月首次遞表失效後,智能駕駛解決方案提供商蘇州天瞳威視電子科技股份有限公司(天瞳威視)再次向港股主板發起重衝,由匯豐及華泰國際聯席保薦。
喺智能駕駛賽道從「講故事」轉向「拼量產」嘅 2026 年,天瞳威視嘅二次遞表唔單止係一次資本試探,更係一場關於中國智駕供應商生存現狀嘅集中檢閱。
呢間被認為係「算力效率派」代表嘅公司,一邊連住從采埃孚到上汽、北汽嘅豪華產業資本陣營,一邊卻面臨住現金流緊繃、海外明顯回落嘅現實困境。喺呢場 IPO 嘅博弈中,光鮮同陣痛並存。
01
邊個係「天瞳威視」?
天瞳威視嘅創辦人王曦係一位典型嘅「回國」技術派。佢畢業於北京航空航天大學,後喺英國雷丁大學攻讀計算機科學博士學位。
喺決定創業之前,王曦曾經喺汽車零部件供應商天合汽車(TRW)及采埃孚擔任算法工程師同技術負責人,深度參與咗早期 ADAS 系統嘅開發。
2016 年,王曦捕捉到國內汽車智能化嘅風口,回國喺蘇州創立咗天瞳威視,定位係「以軟件算法驅動智能駕駛」嘅本土解決方案提供商。
公司嘅名字「天瞳」寓意「天之眼」,意在打造車輛感知萬物嘅視覺中樞。佢從最初嘅視覺感知算法起步,逐步擴展至行泊一體域控制器、L4 級自動駕駛系統等軟硬件結合嘅整體方案。
天瞳威視融資情況。資料來源:企查查
成立後不久,天瞳威視就獲得德聯資本、盛世投資嘅天使輪融資。此後十年時間,天瞳威視累計完成咗超過 10 輪融資,融資總額近 10 億元。
從招股書披露嘅股權結構嚟睇,天瞳威視構建咗深度綁定嘅「產業 + 資本」生態圈。
一方面,產業夥伴站台,全球汽車零部件巨頭采埃孚唔單止係其 C 輪領投方,亦係其戰略合作夥伴,持有天瞳威視 6.93% 嘅股份,位列第四大股東;國內方面,上汽集團通過上汽北美產投持股,北汽集團通過北汽產投佈局其中,地平線同商湯科技亦係戰略投資者。
另一方面,地方國資護航,唐山機器人基金、吳中金控等國資背景基金喺 D 輪及 D+ 輪入場,提供咗約 5.23 億元嘅資金支持。
截至最後實際可行日期股權架構
截至目前,王曦透過直接持股同員工持股平台合共控制公司約 40.84% 嘅權益,依然保持住對公司嘅控制權。
02
「兩條腿」行路
天瞳威視喺業務佈局上採取咗「雙軌並行」嘅策略。
喺 L2-L2+ 級輔助駕駛領域,天瞳威視嘅選擇非常務實。佢並冇盲目追逐算力堆疊嘅「軍備競賽」,而係走咗一條高性價比路線。
作為典型嘅視覺派智駕供應商,佢喺 L2 量產方案上以視覺感知為主,融合毫米波雷達同超聲波雷達,能夠喺較低算力平台上實現高級功能。例如,基於地平線 J6B 芯片(約 20TOPS)嘅方案即可支持行泊一體、高速 NOA。
呢種打法擊中咗 10 萬 -20 萬級主流車款對成本敏感嘅痛點。根據灼識諮詢嘅數據,按 2024 年裝機量計,天瞳威視係中國第二大同時提供行車同泊車解決方案嘅以軟件為核心嘅 L2-L2+ 級方案提供商,市場份額為 14.3%。
2024 年中國具備行泊一體能力嘅以軟件為核心供應商格局
截至最後實際可行日期,天瞳威視獲得 23 個汽車品牌嘅 198 款車款嘅 L2-L2+ 級解決方案定點函,並實現 6 個汽車品牌嘅 105 款車款嘅量產;獲得定點函嘅 198 款車款中有 87 款覆蓋海外市場,其中 59 款已實現量產。
但值得注意嘅係,L2-L2+ 市場正在經歷劇烈嘅「紅海化」。
一方面,經緯恆潤、福瑞泰克等本土 Tier1 正在加速追趕;另一方面,部分頭部車廠開始將低階智駕方案從外購轉為內部集成。
天瞳威視能否維持佢喺「性價比方案」領域嘅領先地位,取決於佢能否持續保持算法對低算力平台嘅優化能力,而這需要喺研發投入上持續加碼。
喺高級 L4 級自動駕駛領域,天瞳威視更多扮演「先鋒」角色。這亦係佢近兩年增長最快嘅板塊。
早在 2019 年,佢就參與咗上海洋山港嘅 5G 智能重卡項目。目前佢嘅 L4 方案覆蓋 Robobus、Robotaxi 同 Robotruck。其中,Robobus 係佢最具代表性嘅產品線,已喺蘇州、天津等城市嘅公開道路投入常態化試營運。
2025 年,天瞳威視從 L4 級解決方案產生收入 3.75 億元,佔公司總收入嘅 68% 以上,大部分收入來自 L4 級軟件解決方案。
然而,硬幣嘅另一面係商業化嘅曲折。雖然 L4 業務營收暴增,但佢嘅交付形態目前以「軟硬件一體解決方案」為主,呢種模式本質上接近「項目制交付」或「小規模車隊部署」,與 L2 業務中「純軟件授權 + 白盒交付」嘅高毛利、大規模複製邏輯存在顯著差異。
呢就直接導致 L4 業務毛利率嘅大幅波動:喺部分自研硬件佔比较高嘅項目中,毛利率一度低至 15%。
截至遞表日,公司雖手握超 10 億元嘅 L4 意向訂單,涵蓋 2500 架車,但呢啲訂單預計要喺未來三至五年內先會陸續交付,短期內對現金流嘅改善作用有限。
此外,天瞳威視仲有部分應收來自工程服務,主要涉及道路測試、數據收集支援及數據標註服務以及公司嘅專有工具鏈。
03
財務嘅雙面鏡
招股書嘅財務部分,展現咗智駕行業最真實嘅「B 面」:規模同虧損嘅極限拉扯,同埋賬面現金同營運消耗之間嘅緊張博弈。
營收高增長,但結構劇烈波動。
財務數據顯示,公司嘅營收呈現爆發式增長,從 2022 年嘅 1.72 億元增長至 2024 年嘅 4.83 億元,複合年增長率高達 67.7%。2025 年全年營收進一步增長至 5.5 億元。
但收入結構嘅變化明顯。2023 年,公司依賴 L2-L2+ 業務,佔比 90.2%;去到 2024 年,L4 業務佔比升至 50.2%;2025 年,L4 業務佔比進一步拉高至 68%。呢種「斷崖式」嘅結構切換,雖然證明佢 L4 技術搵到咗落地場景,但亦令市場質疑佢 L2 業務係咪已觸及天花板。
毛利率同純利潤嘅背離,呢係天瞳威視面臨嘅最大挑戰。
從毛利睇,整體毛利率喺 30% 左右徘徊,喺呢個技術密集型嘅智駕行業屬於中等水平。但細拆睇嚟,L2-L2+ 業務嘅毛利率通常能維持喺 40% 以上,純軟件授權模式,而 L4 業務嘅毛利率則因「軟硬件一體」交付中硬件佔比提高而被顯著拉低。
從純利潤睇,雖然表面虧損額較大,2024 年虧損 4.63 億、2025 年虧損約 2 億,呢度包含大量因優先股公平值變動帶來嘅「紙面虧損」。剔除呢個因素後嘅經調整純利潤更能反映公司嘅真實經營狀況:2024 年已收窄至 -438 萬元,但 2025 年並未如市場預期實現轉正,而係錄得約 -1086 萬元,虧損較 2024 年有所擴大。
呢個背後有一個不可回避嘅關鍵前提:調整後嘅「減虧」乃至「接近盈虧平衡」,係喺公司持續壓縮研發投入嘅基礎上實現嘅,研發費用從 2024 年嘅 1.17 億元降至 2025 年嘅 9231 萬元,研發費用率從 2024 年嘅 24.3% 進一步降至 16.8%,而 2022 年呢個數字曾高達 108.7%。對於一家科技公司嚟講,研發強度嘅「退坡」是否會影響未來嘅技術護城河,係一個潛在風險點。
現金流持續告急,最令人擔憂嘅信號。
根據最新招股書,截至 2025 年 12 月 31 日,公司賬上嘅現金及現金等价物為 2.35 億元,較 2025 年 6 月 30 日嘅 3.74 億元淨減少 1.39 億元,現金消耗速度較快。
更值得警惕嘅係經營現金流由正轉負且缺口持續擴大嘅趨勢。2023 年,公司經營活動現金流淨額為正向流入 1.15 億元,但 2024 年迅速轉為淨流出 1.89 億元,2025 年進一步惡化至淨流出 2.93 億元。
與此同時,應收賬款周轉急劇惡化。公司嘅貿易應收款項從 2023 年嘅 0.89 億元升至 2025 年嘅 5.48 億元,三年增長超過五倍,而同期營收增幅僅約 2.7 倍。
更令人擔憂嘅係應收款項周轉天數從 2023 年嘅 191 天同 2024 年嘅 166 天,到 2025 年驟升至 300 天,意味著公司從完成交付到收回款項平均需要接近一年時間。呢相當於變相為客戶提供長期無息墊資,喺資金本就緊張嘅情況下進一步加劇咗流動性壓力。
此外,雖然天瞳威視係首家出海嘅中國智駕軟件供應商,但 2025 年佢嘅海外業務遭遇咗明顯回落。2023 年天瞳威視海外收入為 1.27 億元,佔總營收比重達到 62.2%;到 2025 年海外收入降至 1100 萬元,佔比僅 2.0%。
喺而家全球地緣政治複雜、部分國家對智能汽車數據監管趨嚴嘅背景下,為佢嘅全球化故事增添咗一絲不確定性。
04
結語
天瞳威視嘅二次闖關,係智能駕駛行業進入「淘汰賽」階段嘅一個縮影。
從好嘅方面睇,佢踩準咗 L2 性價比同 L4 場景化落地嘅雙重節奏,且經調整純利潤喺特定口徑下已接近盈虧平衡,呢啲都畀投資者提供咗「有亮點可講」嘅故事線。
但從風險嘅角度睇,情況遠比首次遞表時更為嚴峻。業務重心嘅急速漂移、L4 業務商業化初期嘅盈利磨難、研發投入嘅被動收縮,呢啲此前就已存在嘅問題並未緩解。
天瞳威視 L4 級智能巴士
而真正令此次 IPO 帶「求生」色彩嘅,係現金流數據嘅實質性惡化:2.35 億元嘅賬面現金,面對每年近 3 億元嘅经营性現金淨流出,安全邊際已不足一年。疊加 300 天嘅應收賬款周轉天數,意味著公司每交付一筆訂單,都要墊付近一年嘅資金成本。
換言之,天瞳威視正處喺一個危險嘅財務窗口期:賬上嘅錢僅夠維持唔足一年嘅正常運作,而 L4 業務嘅大規模交付同回款卻需要更長時間。喺呢個智駕資本熱潮退去、一級市場融資邊際收緊嘅時刻,公司已冇太多等待嘅餘地。
首次遞表失效後僅隔半年便再次衝擊港股,對天瞳威視而言,與其話係戰略選擇,唔如話係現金倒逼下嘅必然之舉。


