首頁Merchants

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
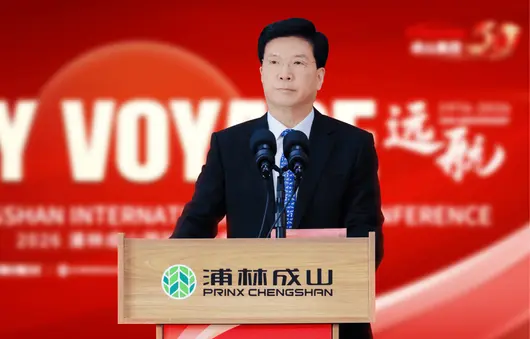
In the golden month of October, the 2026 Pulin Chenshan International Dealer Conference was grandly held in Rongcheng, Shandong. China Tire Business Network (tirechina.net) learned that this conference coincided with the 50th anniversary of the founding of Chushan Group. Over 100 international dealer representatives from Europe and America, Asia-Pacific, Latin America, and the Middle East and Africa gathered together to exchange ideas on topics such as product innovation, market expansion, and supply chain synergy. This fully conveyed Pulin Chenshan's grand vision of deeply cultivating the global market, building high-end brands, and creating a win-win cooperation future.
Deeply Cultivating Cultural Roots, Joining Hands with Partners to Expand International Markets
Fifty years of hard work, culture casts the soul. Mr. Che Hongzhi, Chairman of Chushan Group, pointed out that 50 years of relentless progress have forged Chushan's unique corporate culture and deep brand heritage. This cultural gene with integrity as the cornerstone, craftsmanship as the soul, and win-win as the goal supports the company in walking steadily and going far in the global market; while the companionship and persistence of partners have endowed Pulin Chenshan with the courage and boldness to gallop around the world. The company is willing to join hands with partners to build a deeper-level, higher-quality international market landscape.

Culture precipitates inward and transforms into market competitiveness outwardly. Mr. Jiang Xizhou, President of Pulin Chenshan, analyzed Chushan's core competitive advantages accumulated over 50 years from dimensions such as products, services, and supply chain construction, elaborating on the company's development ideas of moving from price competition to value competition in the future, and truly transforming the "Product + Service" concept into cooperation benefits at the market end. Mr. Che Jing, Vice President of Pulin Chenshan, emphasized that Pulin Chenshan and partners have endured hardships together for 50 years, not only precipitating unique cultural heritage but also accumulating development practices well-versed in customer needs. The company will continue to move towards high-end direction relying on five major business growth engines such as new energy tires and special tires, providing full-link empowerment for international dealer partners.

Strengthening Product and Supply Chain Support, Docking with Overseas Market Demands
This conference provided a precious opportunity for international partners to fully perceive Pulin Chenshan's R&D strength, product matrix, and supply chain system. Mr. Li Chongbing, Director of the R&D Center, shared Pulin Chenshan's advanced R&D and production capabilities, pointing out that continuous innovation is the only solution to drive future development. Mr. Wang Hongdian, Director of the Marketing Center, elaborated on the company's system solutions and follow-up product planning in the fields of passenger cars, commercial vehicles, and special tires. Ms. Sun Yaping, Director of the Supply Chain Management Center, directly addressed three pain points of international trade, verifying the company's supply chain risk resistance and fulfillment reliability with detailed cases and data.

These topics also addressed the actual concerns of international dealers in market operations: whether products can adapt to local demands, whether supply can remain stable, and whether service can keep up timely. Discussing product planning and supply chain guarantee within the same cooperation framework helps both parties dock market demands and resource input more clearly, establishing more stable expectations for subsequent business expansion.
Deepening Two-Way Exchange, Promoting Global Channel Synergy
In the cooperation representatives speech session, dealer representatives from Brazil, Thailand, and U.S. Puerto Rico took the stage in succession. Combining local market promotion practical results, they told the deep friendship of walking side by side with Pulin Chenshan, vividly demonstrated the company's strong competitive momentum in the overseas market, and offered sincere blessings for the 50th anniversary of Chushan Group's founding.

During the conference, international dealers visited the company showroom in groups, visited six major laboratories on site including the noise laboratory and static performance laboratory, and conducted deep thematic seminars on topics such as product iteration development, regional market expansion, supply chain synergy guarantee, and after-sales system upgrade. This helps further break communication barriers, congregate development consensus, and lay a solid foundation for subsequent global business synergy implementation.
Industry Comments
To build long-term competitiveness in the overseas market, tire enterprises need to transform product performance, delivery capability, and local service into customer-perceived value together. Dealers are close to the terminal, and their understanding of usage scenarios, consumption preferences, and after-sales demands is also an important basis for enterprises to optimize products and services. The implementation key of the value competition idea proposed at this conference lies in making R&D, supply chain, and channels form closer cooperation, enabling market feedback to enter product iteration, so that enterprise capabilities truly serve terminal operations.
Building on 50 years of accumulation, we look forward to Pulin Chenshan and global partners further deepening synergy, converting product and service advantages into more solid market performance, and accumulating more practical experience for the high-quality going global of Chinese tire brands.
In July, the Chu Energy Automotive ET test vehicle rolled off the line in Wuhan, behind which is the owner of China's second-largest 4S group — Hengxin Automotive Group, Dai Deming, holding 10 billion in self-owned funds, gripping three cards: batteries, channels, and qualifications, looking to move up from the downstream channel to manufacture complete vehicles.

This matter hasn't made much of a splash in the automotive industry yet, but in the more 'grassroots' tire industry, the strategy of 'dealers entering the product business' has actually been in play for 20-30 years.
Currently, the replacement market for tires accounts for over 70%, dealers hold a complete grassroots network ranging from county-level repair shops to roadside tire stores, more fragmented than 4S channels and closer to real demand.
But currently, the capacity utilization rate for the entire industry is less than 70%, price wars have driven prices down to the cost line, dealers entering tire manufacturing, are they copying Chu Energy's playbook, or jumping into another fire pit?
Several Real Examples of 'Dealers Making Tires' in the Tire Industry
Let's list a few representative examples first. Qin Long, Chairman of Qingdao SenQilin, founded Sendatai in 1999. Earlier, he was an agent for Huanghai, Shuangqian, and Linglong, later also represented Michelin and Continental. Started fresh in 2007 to make SenQilin, targeting high-end passenger car tires, built a factory in Thailand, positioned in Spain. Now is an A-share listed company, revenue exceeded 4 billion in the first half of 2024, one of the representatives of domestic high-end tires.

Father and son Zhao Jianbin and Zhao Ruilong originally worked with Qingdao Ruilong Tire Technology, mainly engaging in tire import and export, owned brands 'Maibote' and 'Jingnai' under them. In 2019, Zhucheng Guopeng Rubber went bankrupt, they purchased the entire assets for 117 million, renamed Yousheng Tires to enter manufacturing; in 2024, invested another 5.16 billion to launch a new Shandong Youyue Rubber project.
Shenyang Ruihua Group Jin Penghui started in the 1990s, doing motor oil, batteries, tires, was a core agent for Toyo Tires in China, absolute channel advantage in the three northeastern provinces. In August 2025, Liaoning Hengdasheng (controlled by Ruihua) acquired with 91.59 million USD 86% equity of Tongyio Zhangjiagang, a subsidiary of Japan Toyo, renamed 'Hengdasheng Toyo Tires' — dealing for thirty years, turned around and swallowed the original manufacturer.
In 2024, Qingdao Sunset Tire Co., Ltd. planned to build a new factory in Brazil. When the news broke, the industry was shocked, this unknown dealer not only changed industries to build a factory, but also went straight overseas, likely to become the first domestic company to build a factory in Brazil.

Of course, there have been many failed attempts in recent years. In 2017, a provincial Michelin agent in East China launched a private label, commissioned a small factory in Shandong, focusing on e-commerce and partner repair shops, resulting in 2019, because the factory substituted materials, a batch of tires showed bulging and falling pieces, compensated over 2 million, the brand went bust immediately.
A large dealer in Nanjing started a private label in 2018, for 3 years, sold only 100,000 tires a year, not even as much as a big brand agent sold in a quarter, finally gave up...
Advantages of Dealers Making Tires
First is ready channels, dominating the replacement end. Over 70% of tire sales are in the replacement market, dealers already deal with hundreds of thousands of repair shops and tire stores nationwide, even sinking to county and township outlets, distributing their own brand is almost zero cost, no need to throw money at investment promotion and promotion like new brands.
Even 4S cannot match this point — 4S shops only cover new cars and warranties, tire dealers' terminals are more scattered and closer to replacement scenarios, promoting their own tires just requires giving repair shops a few percent rebate, and can expand quickly.
Second is understanding terminal pain points, products stay on track. Dealers receive feedback from repair shops every day, knowing which patterns are wear-resistant, which specs sell well in the Northeast, whether new energy vehicle owners care more about low rolling resistance or quietness, product positioning is more accurate than marketing departments of pure manufacturers.
Third is controllable capital and risk. Top dealers have stable cash flow, no need to seek financing like new forces and watch faces, first try OEM/ODM, expand if selling well, stop if not, loss is not big.
Disadvantages are equally prominent, failures far outnumber successes
First is technical and production shortcomings. Tires look simple, but formula, structure, process thresholds are not low, especially now with EV tires, silent foam, self-healing, etc., dealers lack technical accumulation, either find OEM or build factory themselves, need to hire R&D, buy equipment, high investment, long cycle, currently full industry capacity utilization is less than 70%, building a factory is like throwing money into a red ocean.

Second is conflict with agency brands. Dealers originally represent big brands like Linglong, Sailun, Michelin, starting own brand is like stealing big brands' business, big brands will definitely squeeze rebates, or even cancel agency rights, left hand fighting right hand.
Third is difficult to break brand recognition. Tires are safety parts, car owners replace tires by recognizing big brands or repair shop recommendations, own brand has no endorsement, can only take mid-to-low end cost-performance route, cannot sell at high prices, no one recognizes top end, thin profits, poor risk resistance.
Fourth is the dividend period is over. The bosses before caught the 2000-2010 window of capacity shortage and demand explosion, now capacity is overstocked, price wars driven to cost line, if you do mid-low end again, you can't make money, cannot do high end, stuck.

Now tire industry dealer profits are getting thinner and thinner, rebates for agency big brands are lower every year, some really want to integrate upwards to make their own brands, but don't blindly copy Chu Energy's 'full-chain closed loop' for car manufacturing.
The logic of tires is simpler: first OEM, avoid direct competition, use channel advantages to earn stable money, much more reliable than throwing money to build a factory and be a manufacturer. After all, even the top players in the tire industry are competing fiercely now, dealers have no technology or capacity reserves, forcing in means likely being a cannon fodder.