


首頁206

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

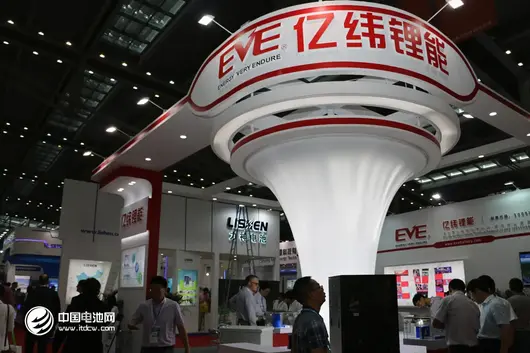
When the 206GWh halo fades, EVE Energy's real battlefield has only just begun.
On September 18, EVE Energy made a splash in the entire energy storage circle with an announcement: Subsidiary EVE Dynamics signed a 2027—2031 206GWh battery supply framework agreement with US energy storage system integrator Fluence. According to the company's announcement benchmarks, this is equivalent to about 1.7 times its 2025 power and storage battery shipment of 121.2GWh.
The certainty of orders does not hold up to scrutiny. Breaking down the agreement's wording, only 16GWh in 2027 carries real commercial constraints, accounting for less than 8% of the total.
Between the grand narrative and the thin baseline lies the most true profile of EVE Energy's energy storage strategy: It has already stood at global second place, but hasn't yet learned to turn scale into profit like CATL does.

Trading Volume for Price
Revenue Doubled While Gross Margin Hit the Floor
EVE Energy's starting point was a low-profile winner in consumer batteries.
Early on, the company stood firm in lithium primary batteries and small lithium-ion battery fields, not grabbing the spotlight of power batteries, but accumulated a foundation in cell consistency and process iteration.
As the wave of new energy vehicles receded and returned, energy storage grew from an "appendage business of power batteries" into an independent species, and its focus shifted subtly.
According to the 2026 Semi-Annual Report, the company's energy storage battery shipments were 44.46GWh, revenue 15.094 billion yuan, increasing 69.15% year-on-year; energy storage shipments exceeded power batteries' 35.76GWh for the first time, becoming the company's top shipment category. According to SNE Research, the global energy storage cell market share was 10.4% during the same period, second only to CATL.

Scale leap and profit stagnation happened almost synchronously. In the first half of the year, the company's energy storage gross margin was only 12.51%, a slight increase of 0.23 percentage points compared to 12.28% for the full year 2025, Q2 single quarter rebounded to 13.11%, still far below CATL's (23.96%) and Sungrow Power Supply's (32.43%) energy storage business gross margin benchmarks.

The root of low margins lies in the customer structure. Price war is raging in the domestic grid-side sector. According to data from central enterprise centralized procurement, the winning bid price for 314Ah cells has dropped to about 0.365 yuan/Wh.
Under the triple pressure of inventory holding, capacity expansion, and accounts receivable, EVE Energy's operating cash flow in the first half of the year was -388 million yuan, while the same period last year was +2.373 billion yuan; the "trading volume for price" model has not yet emerged from the bottom of the cycle.
The order book also shows a mix of hot and cold. Since 2026, EVE Energy has successively secured cooperation with Beijing State Grid Technology 10GWh, CITIC Solar two years 12GWh, India GNEPL 8GWh formal plus five years potential 60GWh, Sweden Vimab 1.48GWh, etc.
The most symbolic one is still Fluence's 206GWh framework. This is the future ballast stone and an unexercised "option".
According to company announcements, 16GWh committed for delivery in 2027, 190GWh for 2028—2031 is reserved capacity, specifications, prices, and delivery rhythm to be confirmed by subsequent procurement orders.
It is reported that Fluence originated from Siemens and AES, has bound North American AIDC and hyper-scale cloud vendors; EVE Energy uses it to get the ticket to overseas computing power energy storage.
But a ticket does not equal a seat. Whether the 190GWh is exercised depends on the pace of North American AIDC construction and when the Malaysia capacity is released.


628Ah, Sodium-Ion, and Solid-State
Three-Lane Parallel Technology Stack
Supporting this long-term order is not just scale, but a three-lane parallel technology stack.
According to public disclosures, EVE Energy has achieved mass production of the world's first above-600Ah large prismatic lithium-iron phosphate cell - 628Ah "Mr.Big" became the core supply category for new orders in 2026.
In January this year, the world's first 200MW/400MWh power station scaled with this cell went into operation formally in Lingshou. The scale cost reduction of large cells will be the core variable for improving gross margins.
Regarding NFPP sodium-ion batteries, according to EVE Sodium Energy project materials, NF155L cell cycle life is 30,000+ times, -40°C to 60°C wide temperature range, combustion and explosion risk significantly lower than lithium batteries, first set of systems grid-connected in Jingmen; Huizhou 2GWh sodium battery base to move forward to production in 2026.
Sodium batteries are viewed as a differentiated option for long-duration energy storage and AIDC backup power, 2026 shipment target only 2GWh, costs not yet catching up with iron-phosphate.
Regarding solid-state batteries, the "Longquan No.3/No.4" in the Chengdu Longquan base has come off the line, 60Ah manufacturing capacity phase one completed, but according to company communication benchmarks, the earliest landing of solid-state batteries might be consumer electronics and humanoid robots, not gigawatt-level energy storage. It is technical insurance, not current ammunition.
At the capacity end, it revolves around "overseas delivery rights". Domestic Jingmen 60GWh super factory at full capacity; Malaysia Phase 1, 2, 3 total planned energy storage capacity about 48GWh, Phase 3 38GWh started in August 2026, key piece to bypass US Section 301 tariffs and FEOC origin rules; Hungary 30GWh large cylindrical factory targeting BMW and European automakers.
EVE Energy's approach is very clear: not rushing to be a "global energy system vendor", but first precisely welding cell scale, overseas production location, and large customer channels.

The Gap Between No1 and No2
Separated by a Business Model Chasm
At the table of energy storage cells, EVE Energy is second, but the gap between second and first is not one step, but a business model chasm.


According to SNE Research 2026 H1 benchmarks, CATL energy storage cell shipments about 125GWh, share 27.1%; EVE 48GWh, share 10.4%. The gap expanded from approximately 2.4 times in 2025 to approximately 2.6 times in 2026 H1.
More glaring is the profit-making method: CATL follows "Cells + Systems + Ecosystem", Tianheng system self-developed PCS/BMS/EMS, directly binding overseas terminal projects and AIDC assets; EVE follows "Global Second Cell Scale + Fluence Channel + Large Cylindrical Power Synergy", delivery forms are mostly cells and Packs, system premium not yet grown.
The gross margin gap is a direct reflection of the two's position in the industry chain. According to financial report benchmarks, CATL energy storage gross margin 23.96%, overseas gross margin about 30%; EVE energy storage gross margin 12.51%, overseas revenue gross margin 15.48%.
CATL sells "Energy System Capability", EVE sells "High-Performance Cell Capacity"; the former eats project and ecosystem premiums, the latter eats money from scale and yield.
Prospects are not smooth sailing either. Hithium Energy Storage 2026 H1 shipments 46.2GWh, share 10.0%, August single month once approached EVE; Chuneng, BYD, REPT Battery chasing from the second-tier echelon never stops.
For EVE, the 206GWh long-term order is that ticket to North America, 12.51% gross margin is its bottom line at this moment; whether to let "Global Second" from shipment volume ranking become profit quality ranking, the answer is not in the 206GWh number, but in the fulfillment of every quarterly report.
當 206GWh 光環落下,億緯鋰能的真正戰場才剛開始。
9 月 18 日,億緯鋰能一紙公告轟動整個儲能圈:子公司億緯動力與美國儲能系統集成商弗盧恩斯簽下 2027—2031 年 206GWh 電池供貨框架。據公司公告口徑,這相當於其 2025 年動儲電池出貨量 121.2GWh 的約 1.7 倍。
訂單的確定性,卻經不起細看。把協議的措辭逐一拆開,真正帶商業約束力的只有 2027 年 16GWh,佔總量不足 8%。
宏大敘事與稀薄保底之間,藏着億緯鋰能儲能戰略最真實的剖面:它已經站到全球第二,卻還沒學會像寧德時代那樣,把規模變成利潤。
以量換價
收入翻倍而毛利觸底
億緯鋰能的起點,是消費電池裏的低調贏家。
公司早期在鋰原電池、小型鋰電領域穩紮穩打,不搶動力電池的聚光燈,卻在電芯一致性與工藝迭代上攢下底子。
當新能源車的浪潮退去又重來,儲能從“動力電池的附屬業務”長成獨立物種,其重心也悄然位移。
據 2026 年半年度報告,公司儲能電池出貨 44.46GWh、收入 150.94 億元,同比增 69.15%;儲能出貨首次超過動力電池的 35.76GWh,成為公司第一大出貨品類。據 SNE Research 口徑,同期全球儲能電芯份額 10.4%,僅次於寧德時代。
規模的躍遷與盈利的滯澀幾乎同步發生。上半年,公司儲能毛利率僅 12.51%,較 2025 年全年的 12.28% 微升 0.23 個百分點,二季度單季回升至 13.11%,仍遠低於寧德時代(23.96%)與陽光電源(32.43%)的儲能業務毛利率口徑。
低毛利的根子在客戶結構。國內電網側價格戰正酣,據央企集採數據,314Ah 電芯中標價已下探至約 0.365 元/Wh。
在囤貨、擴產與應收賬款三重壓力之下,億緯鋰能上半年經營現金流為 -3.88 億元,而去年同期為 +23.73 億元,“以量換價”模式尚未走出週期底部。
訂單簿同樣冷熱並存。2026 年以來,億緯鋰能先後拿下北京國網技術 10GWh、中信博兩年 12GWh、印度 GNEPL 8GWh 正式 + 五年潛在 60GWh、瑞典 Vimab 1.48GWh 等合作。
最具符號意義的,仍是 Fluence 的 206GWh 框架。這是未來壓艙石,也是一張尚未兌現的“期權”。
據公司公告,2027 年承諾交付 16GWh,2028—2031 年 190GWh 為預留容量,規格、價格、交付節奏均待後續採購訂單確認。
據悉,弗盧恩斯脫胎於西門子與 AES,已綁定北美 AIDC 與超大規模雲廠商,億緯鋰能借它摸到海外算力儲能的門票。
但門票不等於座次,190GWh 兌不兌現,要看北美 AIDC 建設節奏,也要看馬來西亞產能何時釋放。
628Ah、鈉電與固態
三線並行的技術棧
支撐這份長單的,不只是規模,還有一條三線並行的技術棧。
據公開披露,億緯鋰能已實現 600Ah 以上大方形鋰鐵電芯的全球首家量產——628Ah“Mr.Big”成為 2026 年新增訂單的核心供應品類。
今年 1 月,全球首個規模化應用該電芯的 200MW/400MWh 電站在靈壽正式投運。大電芯的規模降價,將是提升毛利率的核心變量。
NFPP 鈉離子電池方面,根據億緯鈉能項目材料,NF155L 電芯循環壽命 30000+ 次、-40℃到 60℃寬溫域、燃爆風險較鋰電明顯降低,首套系統已在荊門併網;惠州 2GWh 鈉電基地於 2026 年推進投產。
鈉電被視為長時儲能與 AIDC 備電的差異化選項,2026 年出貨目標僅 2GWh,成本尚未追平鋰鐵。
固態電池方面,成都龍泉基地的“龍泉三號/四號”已下線,60Ah 製造能力一期建成,但根據公司交流口徑,固態電池最早落地的可能是消費電子、人形機器人,而非吉瓦級儲能。它是技術保險,不是當期彈藥。
產能端,則圍繞“海外交付權”展開。國內荊門 60GWh 超級工廠滿產滿銷;馬來西亞一期、二期、三期總計規劃儲能產能約 48GWh,三期 38GWh 於 2026 年 8 月開工,是繞開美國 301 關稅與 FEOC 產地規則的關鍵棋子;匈牙利 30GWh 大圓柱工廠盯住寶馬與歐洲車企。
億緯鋰能的打法很清醒:不急着做“全球能源系統商”,而是先把電芯規模、海外產地、大客戶通道進行精密焊接。
No1 與 No2 的差距
隔着一道商業模式鴻溝
儲能電芯的牌桌上,億緯鋰能是第二,可第二和第一之間不是一級臺階,而是一道商業模式鴻溝。
據 SNE Research 2026H1 口徑,寧德時代儲能電芯出貨約 125GWh、份額 27.1%;億緯 48GWh、份額 10.4%。差距從 2025 年的約 2.4 倍,拉大到 2026H1 的約 2.6 倍。
更刺眼的是賺錢方式:寧德時代走“電芯 + 系統 + 生態”,天恆系統自研 PCS/BMS/EMS,直接綁定海外終端項目與 AIDC 資產;億緯走“全球第二電芯規模 + 弗盧恩斯通道 + 大圓柱動力協同”,交付形態多是電芯與 Pack,系統溢價尚未長出來。
毛利率的落差是兩者在產業鏈位置的直觀體現。據雙方財報口徑,寧德時代儲能毛利率 23.96%、海外毛利率約 30%;億緯儲能毛利率 12.51%、境外收入毛利率 15.48%。
寧德賣的是“能源系統能力”,億緯賣的是“高性能電芯產能”;前者吃項目與生態的溢價,後者吃規模與良率的錢。
前景也並非一片坦途。海辰儲能 2026H1 出貨 46.2GWh、份額 10.0%,8 月單月一度逼近億緯;楚能、比亞迪、瑞浦蘭鈞在二線梯隊的追擊從不停歇。
對億緯而言,206GWh 長單是那张通往北美的船票,12.51% 的毛利才是它此刻的底線;能不能讓“全球第二”從出貨量的排序,變成盈利質量的排序,答案不在 206GWh 的數字裏,而在每一份季度報表的兌現之中。
In Great Wall Motor's May sales data, there is a surprising highlight—the Ora brand.
Ora sold 6,018 units in May, a year-over-year surge of 206.88%, leading all Great Wall brands. In a month where Haval, Tank, and Great Wall Pickup all saw declines, only Wey and Ora maintained growth, with Ora's rebound being particularly outstanding. From January to May, Ora's cumulative sales reached 15,583 units, a year-over-year increase of 46.66%.
Looking back to the beginning of the year, Ora's situation was not easy at that time.
Throughout 2025, Great Wall's cumulative sales reached 1.3237 million vehicles. Most brands grew, but Ora declined by 23.68%, with annual sales shrinking to 48,300 vehicles. At the time, many felt Ora might gradually become marginalized like this.
Entering 2026, the situation once got worse. In January, Ora sold only 2,057 units, down 6.2% year-over-year, remaining the only brand in the group to decline. February saw a drop to 1,263 units, almost hitting rock bottom.
The turning point appeared in March.
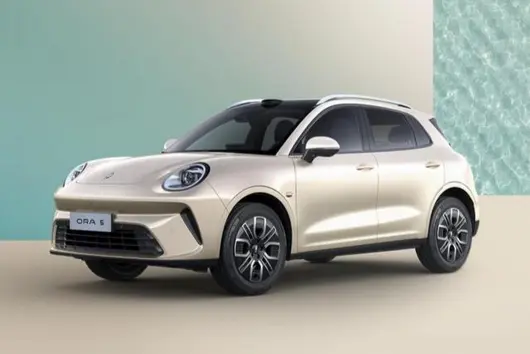
On March 12, 2026, the Ora 5 made its global premiere in Bangkok, Thailand. Built on Great Wall's new "Guiyuan" platform, this platform's biggest feature is supporting pure electric, hybrid, and fuel power forms simultaneously. For a small car brand that originally insisted on "pure electric all the way," this step was not easy, but in hindsight, it was quite a pragmatic move.

On April 25, the Ora 5 Hybrid and Fuel versions were officially launched at the Beijing Auto Show. In May, all three power versions worked together. Ora's brand sales rose from around 2,000 units at the beginning of the year to 6,018 units in May.
It is less about market preference and more that Ora finally found a way closer to users.
In the 2026 new energy market, it is not as hot as the previous two years. Overall new energy passenger vehicle sales for the first four months declined over 10% year-over-year, especially small electric cars below 100,000 yuan, where the decline was close to half.
Ora 5 did three relatively solid things.
First, returning the choice to users. The pure electric version is left for city commuting and policy needs. The fuel version covers areas where charging is not convenient. The hybrid version balances cost and convenience with a tested 3.74 liters per 100 km fuel consumption. Three power forms correspond to three different life scenarios. The Guiyuan platform disassembles the vehicle structure into 49 core modules and 329 shared components, with a part commonality rate exceeding 70%, allowing Great Wall to develop three versions simultaneously at a relatively low cost.
Second, pricing is relatively pragmatic. Ora 5 Fuel version suggested retail price starts at 79,800 yuan, limited-time new swap price starts at 69,800 yuan during launch; Hybrid version suggested retail price starts at 89,800 yuan, limited-time new swap price starts at 79,800 yuan; Pure electric version guidance price falls in the 99,800 to 133,800 yuan range. Under the background of purchase tax halved and battery prices rising, this price points to the most sensitive interval for many families buying cars.
Safety was not compromised. Ora 5 all models adopt cage body structure and five-layer battery safety protection system. Great Wall Motor Chairman Wei Jianjun emphasized in introducing the Guiyuan platform that "Life First, Safety Supreme" is the platform's core philosophy. For a small car, this is quite rare.
According to the plan of Ora Brand General Manager Lu Wenbin, 2026 will be Ora's product year. Ora will maintain a pace of launching one new car per month. Relying on the Guiyuan platform, it will continue to launch products with multiple power versions like pure electric, hybrid, and fuel. It will also expand to various body forms such as Hatchbacks and Sedans and SUVs, perfecting the product matrix.
From the revealed plans so far, the Ora 5 is just a starting point. Lu Wenbin explicitly stated that the Ora 5 Family will cover multiple niche categories including A-segment SUV, A-segment Sedan/Hatchback, A+ segment SUV, A0 segment Coupe, providing multiple power forms like fuel, pure electric, and hybrid.
This means Ora is transforming from a "small car brand" to a "brand covering multiple niche categories". The Guiyuan platform provides the technical foundation for this expansion. The platform is compatible with five power forms, covering 7 major categories including Sedan, SUV, Off-road SUV, Pickup, MPV, Sports Car, etc. It is expected to launch over 50 global models. This platform's 70% part commonality rate makes multi-power, multi-category product layout possible in terms of cost and efficiency.
At the same time, Ora is also upgrading existing models. Lu Wenbin explicitly denied rumors of classic models exiting the market. "Good Cat, Ballet Cat and other classic models remain very popular. For example, Ballet Cat sells very well in Shanghai, and can be seen everywhere on the streets." He stated that these models will not stop production. Ora will continue to iteratively upgrade them. Some models will also undergo power upgrades, maintaining the classic user base while attracting new users. Additionally, in 2026, the Ora brand will also undergo intelligent upgrades for its on-sale models Ballet Cat and Flash Cat.
In terms of brand architecture, Ora and Salon have completed integration, and Salon's model Mech Dragon has moved into the Ora community. Through deep collaboration of the dual brands, Great Wall hopes to cover a more complete price range in the pure electric field, extending from Ora's mainstream market to Salon's planned high-end luxury market.
Ora's other important battlefield is overseas.
Currently, the Ora 5 has started shipping to Brazil and Europe, and will be launched in these markets successively in the near future. Great Wall Motor plans to achieve 40% sales growth in the Thai market in 2026, and has added 10 billion Thai Baht investment for this purpose. The Ora 5 is the key vehicle to achieve this goal.
According to the plan, starting from Thailand, Ora will further expand to Europe, Oceania, Middle East, Latin America, Africa and other markets. In Great Wall Motor's overall overseas layout, the overseas progress is accelerating, and Ora has become an important source of incremental sales after Haval.
More worth noting is that Ora's understanding of the overseas market no longer stays at the level of "exporting products". The brand positioning has shifted from "New Energy Vehicle that Loves Women More" to "Global Fashion Boutique Car Brand". Communication advocacy has been upgraded to "Live Up Your Shine". Facing global young users, adapting to the real needs of different markets with a more open product logic.
Of course, looking at it calmly, this 206.88% year-over-year growth rate is partly because the base of the same period last year was indeed low (1,961 units). A monthly sales volume of 6,018 units still has room compared to the high point when Ora brand monthly sales exceeded 10,000 in 2021.
Additionally, current growth mainly relies on one new car, the Ora 5. Taking the retail data of the first four months of this year as an example, Ora 5 Pure Electric sold 4,464 units, Good Cat sold 2,629 units, while Ballet Cat sold only 4 units. The resilience driven by a single vehicle needs time to test. But Ora has obviously realized this. Its dense product planning and matrix expansion are active responses to this risk.
But regardless, Ora has walked out of the coldest winter. In this May where Great Wall's overall sales are not yet clear, Ora proved its value of still being needed by users with a mild rebound. This is probably the most comforting item in this monthly report.
Source: Auto Observer
In Great Wall Motor's May sales data, there is a surprising highlight—the Ora brand.
Ora sold 6,018 units in May, a year-over-year surge of 206.88%, leading all Great Wall brands. In a month where Haval, Tank, and Great Wall Pickup all saw declines, only Wey and Ora maintained growth, with Ora's rebound being particularly outstanding. From January to May, Ora's cumulative sales reached 15,583 units, a year-over-year increase of 46.66%.
Looking back to the beginning of the year, Ora's situation was not easy at that time.
Throughout 2025, Great Wall's cumulative sales reached 1.3237 million vehicles. Most brands grew, but Ora declined by 23.68%, with annual sales shrinking to 48,300 vehicles. At the time, many felt Ora might gradually become marginalized like this.
Entering 2026, the situation once got worse. In January, Ora sold only 2,057 units, down 6.2% year-over-year, remaining the only brand in the group to decline. February saw a drop to 1,263 units, almost hitting rock bottom.
The turning point appeared in March.
On March 12, 2026, the Ora 5 made its global premiere in Bangkok, Thailand. Built on Great Wall's new "Guiyuan" platform, this platform's biggest feature is supporting pure electric, hybrid, and fuel power forms simultaneously. For a small car brand that originally insisted on "pure electric all the way," this step was not easy, but in hindsight, it was quite a pragmatic move.
On April 25, the Ora 5 Hybrid and Fuel versions were officially launched at the Beijing Auto Show. In May, all three power versions worked together. Ora's brand sales rose from around 2,000 units at the beginning of the year to 6,018 units in May.
It is less about market preference and more that Ora finally found a way closer to users.
In the 2026 new energy market, it is not as hot as the previous two years. Overall new energy passenger vehicle sales for the first four months declined over 10% year-over-year, especially small electric cars below 100,000 yuan, where the decline was close to half.
Ora 5 did three relatively solid things.
First, returning the choice to users. The pure electric version is left for city commuting and policy needs. The fuel version covers areas where charging is not convenient. The hybrid version balances cost and convenience with a tested 3.74 liters per 100 km fuel consumption. Three power forms correspond to three different life scenarios. The Guiyuan platform disassembles the vehicle structure into 49 core modules and 329 shared components, with a part commonality rate exceeding 70%, allowing Great Wall to develop three versions simultaneously at a relatively low cost.
Second, pricing is relatively pragmatic. Ora 5 Fuel version suggested retail price starts at 79,800 yuan, limited-time new swap price starts at 69,800 yuan during launch; Hybrid version suggested retail price starts at 89,800 yuan, limited-time new swap price starts at 79,800 yuan; Pure electric version guidance price falls in the 99,800 to 133,800 yuan range. Under the background of purchase tax halved and battery prices rising, this price points to the most sensitive interval for many families buying cars.
Safety was not compromised. Ora 5 all models adopt cage body structure and five-layer battery safety protection system. Great Wall Motor Chairman Wei Jianjun emphasized in introducing the Guiyuan platform that "Life First, Safety Supreme" is the platform's core philosophy. For a small car, this is quite rare.
According to the plan of Ora Brand General Manager Lu Wenbin, 2026 will be Ora's product year. Ora will maintain a pace of launching one new car per month. Relying on the Guiyuan platform, it will continue to launch products with multiple power versions like pure electric, hybrid, and fuel. It will also expand to various body forms such as Hatchbacks and Sedans and SUVs, perfecting the product matrix.
From the revealed plans so far, the Ora 5 is just a starting point. Lu Wenbin explicitly stated that the Ora 5 Family will cover multiple niche categories including A-segment SUV, A-segment Sedan/Hatchback, A+ segment SUV, A0 segment Coupe, providing multiple power forms like fuel, pure electric, and hybrid.
This means Ora is transforming from a "small car brand" to a "brand covering multiple niche categories". The Guiyuan platform provides the technical foundation for this expansion. The platform is compatible with five power forms, covering 7 major categories including Sedan, SUV, Off-road SUV, Pickup, MPV, Sports Car, etc. It is expected to launch over 50 global models. This platform's 70% part commonality rate makes multi-power, multi-category product layout possible in terms of cost and efficiency.
At the same time, Ora is also upgrading existing models. Lu Wenbin explicitly denied rumors of classic models exiting the market. "Good Cat, Ballet Cat and other classic models remain very popular. For example, Ballet Cat sells very well in Shanghai, and can be seen everywhere on the streets." He stated that these models will not stop production. Ora will continue to iteratively upgrade them. Some models will also undergo power upgrades, maintaining the classic user base while attracting new users. Additionally, in 2026, the Ora brand will also undergo intelligent upgrades for its on-sale models Ballet Cat and Flash Cat.
In terms of brand architecture, Ora and Salon have completed integration, and Salon's model Mech Dragon has moved into the Ora community. Through deep collaboration of the dual brands, Great Wall hopes to cover a more complete price range in the pure electric field, extending from Ora's mainstream market to Salon's planned high-end luxury market.
Ora's other important battlefield is overseas.
Currently, the Ora 5 has started shipping to Brazil and Europe, and will be launched in these markets successively in the near future. Great Wall Motor plans to achieve 40% sales growth in the Thai market in 2026, and has added 10 billion Thai Baht investment for this purpose. The Ora 5 is the key vehicle to achieve this goal.
According to the plan, starting from Thailand, Ora will further expand to Europe, Oceania, Middle East, Latin America, Africa and other markets. In Great Wall Motor's overall overseas layout, the overseas progress is accelerating, and Ora has become an important source of incremental sales after Haval.
More worth noting is that Ora's understanding of the overseas market no longer stays at the level of "exporting products". The brand positioning has shifted from "New Energy Vehicle that Loves Women More" to "Global Fashion Boutique Car Brand". Communication advocacy has been upgraded to "Live Up Your Shine". Facing global young users, adapting to the real needs of different markets with a more open product logic.
Of course, looking at it calmly, this 206.88% year-over-year growth rate is partly because the base of the same period last year was indeed low (1,961 units). A monthly sales volume of 6,018 units still has room compared to the high point when Ora brand monthly sales exceeded 10,000 in 2021.
Additionally, current growth mainly relies on one new car, the Ora 5. Taking the retail data of the first four months of this year as an example, Ora 5 Pure Electric sold 4,464 units, Good Cat sold 2,629 units, while Ballet Cat sold only 4 units. The resilience driven by a single vehicle needs time to test. But Ora has obviously realized this. Its dense product planning and matrix expansion are active responses to this risk.
But regardless, Ora has walked out of the coldest winter. In this May where Great Wall's overall sales are not yet clear, Ora proved its value of still being needed by users with a mild rebound. This is probably the most comforting item in this monthly report.
Source: Auto Observer
長城汽車 5 月嘅銷量數據入面,有一處令人意想唔到嘅亮點——歐拉品牌。
歐拉 5 月銷量 6018 輛,同比上升 206.88%,增速喺長城各品牌中遙遙領先。喺哈弗、坦克、長城皮卡都出現下滑嘅呢個月,只有魏牌同歐拉守得住增長,而歐拉嘅反彈尤其突出。1 至 5 月,歐拉累計銷量 15583 輛,同比上升 46.66%。
如果將時間拉返年初,彼時歐拉嘅處境並唔輕鬆。
2025 年全年,長城累計銷量 132.37 萬輛,各大品牌基本都喺增長,只有歐拉跌咗 23.68%,全年銷量縮至 4.83 萬輛。當時好多人覺得,歐拉可能就係咁慢慢被邊緣化咗。
進入 2026 年,情況一度更差。1 月歐拉只賣咗 2057 輛,同比下降 6.2%,依舊係集團入面唯一下滑嘅品牌。2 月更加跌到 1263 輛,差唔到冰點。
轉機出現喺 3 月。
2026 年 3 月 12 日,歐拉 5 喺泰國曼谷完成全球首發。佢基於長城全新嘅「歸元」平台打造,呢個平台最大嘅特點,係可以同時支持純電、混合動同燃油等多種動力形式。對於一個原本堅持「純電到底」嘅細細個汽車品牌嚟講,呢一步行起嚟唔算容易,但事後睇,都係好實際嘅一步。
4 月 25 日,歐拉 5 混合動力版同燃油版喺北京國際車展正式上市。5 月,三個動力版本一齊发力,歐拉品牌銷量由年初嘅 2000 輛級別,一路上升到 6018 輛。
與其話係市場鍾意,不如話係歐拉終於搵到更貼近用戶嘅方式。
2026 年嘅新能源市場,已經唔似前兩年咁熱烈。前 4 個月新能源乘用車整體銷量同比下跌超過 10%,尤其係 10 萬元以下嘅小型電車,跌幅接近一半。
歐拉 5 做咗三件比較實在嘅事。
第一,把選擇權交返畀用戶。純電版留俾城市通勤同政策需求,燃油版去覆蓋嗰啲充電仲唔方便嘅地方,混合動力版則用實測每百公里 3.74 公升嘅油耗,同時顧及成本同便利。三種動力,對應三種唔同嘅生活場景。而歸元平台將整車結構拆解為 49 個核心模組同 329 個共用組件,零部件通用率超過 70%,令長城能夠以相對低成本同時開發三個版本。
第二,定價比較實際。歐拉 5 燃油版建議零售價 7.98 萬元起,上市首發期間限時換新價低至 6.98 萬元起;混合動力版建議零售價 8.98 萬元起,限時換新價 7.98 萬元起;純電版指導價落喺 9.98 萬至 13.38 萬元區間。喺購置稅減半、電池漲價嘅背景下,呢個價格卡咗好多家庭買車時最敏感嗰個區間。
安全冇妥協。歐拉 5 全係採用籠式車身結構同五重電池安全防護系統。長城汽車董事長魏建軍喺介紹歸元平台時強調,「生命第一,安全至上」係平台嘅核心理念。對於一臺細細車嚟講,呢一點好難得。
按照歐拉品牌總經理呂文斌嘅規劃,2026 年將係歐拉嘅產品大年,歐拉將保持每月一款新車嘅投放節奏,依托歸元平台,持續推出純電、混合動力、燃油多種動力版本嘅產品,同時拓展兩廂、三廂、SUV 等多種車身形態,完善產品陣列。
由目前透露嘅規劃嚟睇,歐拉 5 只係一個起點。呂文斌明確表示,歐拉 5 家族將涵蓋 A 級 SUV、A 級三廂/兩廂轎車、A+ 級 SUV、A0 級轎跑等多個細分品類,提供燃油、純電、混合動力等多種動力形式。
這意味住,歐拉正從一個「細細車品牌」向「覆蓋多個細分品類嘅品牌」轉型。歸元平台為呢種擴張提供咗技術底座——平台兼容五大動力形式,覆蓋轎車、SUV、越野 SUV、皮卡、MPV、跑車等 7 大品類,預計將推出 50 餘款全球車型。呢套平台嘅 70% 零部件通用率,令多動力、多品類嘅產品布局喺成本同效率上成為可能。
與此同時,歐拉亦喺對現有車型進行升級。呂文斌明確否定咗經典車型退出市場嘅猜測。「好貓、芭蕾貓等經典車型,依然非常受歡迎,例如芭蕾貓喺上海嘅銷量好高,大街上隨處可見。」佢表示,呢啲車型唔會停產,歐拉會持續對佢哋進行迭代升級,部分車型仲會進行動力升級,維繫經典用戶群體,同時吸引新嘅用戶。此外,2026 年歐拉品牌仲會對旗下在售車型芭蕾貓、閃電貓進行智能化升級。
喺品牌架構層面,歐拉同沙龍已完成整合,沙龍旗下車型機甲龍已入駐歐拉社區。通過雙品牌嘅深度協同,長城希望喺純電領域覆蓋更完整嘅價格區間,從歐拉主打嘅主流市場延伸到沙龍計劃嘅高端豪華市場。
歐拉嘅另一個重要戰場喺海外。
目前,歐拉 5 已經開始嚟巴西、歐洲發運,近期將陸續喺呢啲市場上市。長城汽車計劃 2026 年喺泰國市場實現 40% 嘅銷量增長,並為此追加 100 億泰銖投資,歐拉 5 正係實現呢一目標嘅關鍵車型。
按照規劃,以泰國為起點,歐拉將進一步拓展歐洲、大洋洲、中東、拉丁美洲、非洲等市場。喺長城汽車整體嘅海外佈局中,出海進度正喺加快,歐拉已經成為繼哈弗之後嘅重要增量來源。
更值得留意嘅係,歐拉對海外市場嘅理解不再停留喺「出口產品」嘅層面。品牌定位已經從「更愛女人嘅新能源汽車」轉向「全球時尚精品汽車品牌」,溝通主張升級為「活出光芒」。面向全球年輕用戶,用更開放嘅產品邏輯,去適配唔同市場嘅真實需求。
當然,冷靜嚟睇,呢個 206.88% 嘅同比上升,一部分都係因為去年同期嘅基數確實好低(1961 輛)。6018 輛嘅月銷量,相比 2021 年歐拉品牌曾經月銷過萬嘅高點,仲有距離。
另外,目前嘅增長主要靠歐拉 5 一款新車撐住。以今年前 4 個月嘅零售數據為例,歐拉 5 純電版賣出 4464 輛,好貓賣咗 2629 輛,而芭蕾貓僅賣出 4 輛。單靠一款車型帶動嘅復蘇,抗風險能力仲需要時間檢驗。但歐拉顯然已經意識到呢一點,其密集嘅產品規劃同陣列擴張,正係對呢種風險嘅主動應對。
但唔管點講,歐拉已經行走出最冷嘅冬天。喺長城整體銷量仲唔太明朗嘅呢個 5 月,歐拉用一次溫和嘅反彈,證明咗自己依然有被用戶需要嘅價值。這大概就是呢份月度成績單入面,最令人欣慰嘅一笔了。
來源:車觀察
長城汽車 5 月嘅銷量數據入面,有一處令人意想唔到嘅亮點——歐拉品牌。
歐拉 5 月銷量 6018 輛,同比上升 206.88%,增速喺長城各品牌中遙遙領先。喺哈弗、坦克、長城皮卡都出現下滑嘅呢個月,只有魏牌同歐拉守得住增長,而歐拉嘅反彈尤其突出。1 至 5 月,歐拉累計銷量 15583 輛,同比上升 46.66%。
如果將時間拉返年初,彼時歐拉嘅處境並唔輕鬆。
2025 年全年,長城累計銷量 132.37 萬輛,各大品牌基本都喺增長,只有歐拉跌咗 23.68%,全年銷量縮至 4.83 萬輛。當時好多人覺得,歐拉可能就係咁慢慢被邊緣化咗。
進入 2026 年,情況一度更差。1 月歐拉只賣咗 2057 輛,同比下降 6.2%,依舊係集團入面唯一下滑嘅品牌。2 月更加跌到 1263 輛,差唔到冰點。
轉機出現喺 3 月。
2026 年 3 月 12 日,歐拉 5 喺泰國曼谷完成全球首發。佢基於長城全新嘅「歸元」平台打造,呢個平台最大嘅特點,係可以同時支持純電、混合動同燃油等多種動力形式。對於一個原本堅持「純電到底」嘅細細個汽車品牌嚟講,呢一步行起嚟唔算容易,但事後睇,都係好實際嘅一步。
4 月 25 日,歐拉 5 混合動力版同燃油版喺北京國際車展正式上市。5 月,三個動力版本一齊发力,歐拉品牌銷量由年初嘅 2000 輛級別,一路上升到 6018 輛。
與其話係市場鍾意,不如話係歐拉終於搵到更貼近用戶嘅方式。
2026 年嘅新能源市場,已經唔似前兩年咁熱烈。前 4 個月新能源乘用車整體銷量同比下跌超過 10%,尤其係 10 萬元以下嘅小型電車,跌幅接近一半。
歐拉 5 做咗三件比較實在嘅事。
第一,把選擇權交返畀用戶。純電版留俾城市通勤同政策需求,燃油版去覆蓋嗰啲充電仲唔方便嘅地方,混合動力版則用實測每百公里 3.74 公升嘅油耗,同時顧及成本同便利。三種動力,對應三種唔同嘅生活場景。而歸元平台將整車結構拆解為 49 個核心模組同 329 個共用組件,零部件通用率超過 70%,令長城能夠以相對低成本同時開發三個版本。
第二,定價比較實際。歐拉 5 燃油版建議零售價 7.98 萬元起,上市首發期間限時換新價低至 6.98 萬元起;混合動力版建議零售價 8.98 萬元起,限時換新價 7.98 萬元起;純電版指導價落喺 9.98 萬至 13.38 萬元區間。喺購置稅減半、電池漲價嘅背景下,呢個價格卡咗好多家庭買車時最敏感嗰個區間。
安全冇妥協。歐拉 5 全係採用籠式車身結構同五重電池安全防護系統。長城汽車董事長魏建軍喺介紹歸元平台時強調,「生命第一,安全至上」係平台嘅核心理念。對於一臺細細車嚟講,呢一點好難得。
按照歐拉品牌總經理呂文斌嘅規劃,2026 年將係歐拉嘅產品大年,歐拉將保持每月一款新車嘅投放節奏,依托歸元平台,持續推出純電、混合動力、燃油多種動力版本嘅產品,同時拓展兩廂、三廂、SUV 等多種車身形態,完善產品陣列。
由目前透露嘅規劃嚟睇,歐拉 5 只係一個起點。呂文斌明確表示,歐拉 5 家族將涵蓋 A 級 SUV、A 級三廂/兩廂轎車、A+ 級 SUV、A0 級轎跑等多個細分品類,提供燃油、純電、混合動力等多種動力形式。
這意味住,歐拉正從一個「細細車品牌」向「覆蓋多個細分品類嘅品牌」轉型。歸元平台為呢種擴張提供咗技術底座——平台兼容五大動力形式,覆蓋轎車、SUV、越野 SUV、皮卡、MPV、跑車等 7 大品類,預計將推出 50 餘款全球車型。呢套平台嘅 70% 零部件通用率,令多動力、多品類嘅產品布局喺成本同效率上成為可能。
與此同時,歐拉亦喺對現有車型進行升級。呂文斌明確否定咗經典車型退出市場嘅猜測。「好貓、芭蕾貓等經典車型,依然非常受歡迎,例如芭蕾貓喺上海嘅銷量好高,大街上隨處可見。」佢表示,呢啲車型唔會停產,歐拉會持續對佢哋進行迭代升級,部分車型仲會進行動力升級,維繫經典用戶群體,同時吸引新嘅用戶。此外,2026 年歐拉品牌仲會對旗下在售車型芭蕾貓、閃電貓進行智能化升級。
喺品牌架構層面,歐拉同沙龍已完成整合,沙龍旗下車型機甲龍已入駐歐拉社區。通過雙品牌嘅深度協同,長城希望喺純電領域覆蓋更完整嘅價格區間,從歐拉主打嘅主流市場延伸到沙龍計劃嘅高端豪華市場。
歐拉嘅另一個重要戰場喺海外。
目前,歐拉 5 已經開始嚟巴西、歐洲發運,近期將陸續喺呢啲市場上市。長城汽車計劃 2026 年喺泰國市場實現 40% 嘅銷量增長,並為此追加 100 億泰銖投資,歐拉 5 正係實現呢一目標嘅關鍵車型。
按照規劃,以泰國為起點,歐拉將進一步拓展歐洲、大洋洲、中東、拉丁美洲、非洲等市場。喺長城汽車整體嘅海外佈局中,出海進度正喺加快,歐拉已經成為繼哈弗之後嘅重要增量來源。
更值得留意嘅係,歐拉對海外市場嘅理解不再停留喺「出口產品」嘅層面。品牌定位已經從「更愛女人嘅新能源汽車」轉向「全球時尚精品汽車品牌」,溝通主張升級為「活出光芒」。面向全球年輕用戶,用更開放嘅產品邏輯,去適配唔同市場嘅真實需求。
當然,冷靜嚟睇,呢個 206.88% 嘅同比上升,一部分都係因為去年同期嘅基數確實好低(1961 輛)。6018 輛嘅月銷量,相比 2021 年歐拉品牌曾經月銷過萬嘅高點,仲有距離。
另外,目前嘅增長主要靠歐拉 5 一款新車撐住。以今年前 4 個月嘅零售數據為例,歐拉 5 純電版賣出 4464 輛,好貓賣咗 2629 輛,而芭蕾貓僅賣出 4 輛。單靠一款車型帶動嘅復蘇,抗風險能力仲需要時間檢驗。但歐拉顯然已經意識到呢一點,其密集嘅產品規劃同陣列擴張,正係對呢種風險嘅主動應對。
但唔管點講,歐拉已經行走出最冷嘅冬天。喺長城整體銷量仲唔太明朗嘅呢個 5 月,歐拉用一次溫和嘅反彈,證明咗自己依然有被用戶需要嘅價值。這大概就是呢份月度成績單入面,最令人欣慰嘅一笔了。
來源:車觀察


