首頁都市

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。

然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。

要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。

高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。

《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。

如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.

BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.

The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.

From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.

Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.

The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
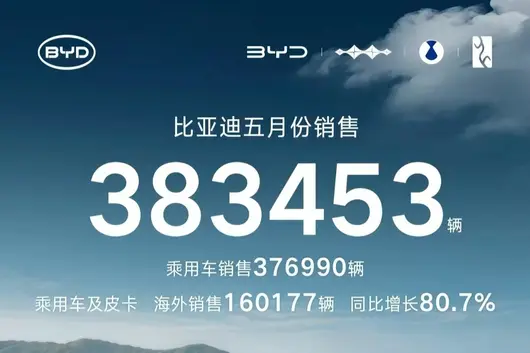
In May, China's automotive market overall presented a gentle recovery trend, with domestic brands still being the sales backbone of the market. Recently, BYD, Geely, Chery, Changan, and Great Wall, the top 5 domestic automakers, successively released their monthly performance reports. From the data, these five companies show a general characteristic of "stable total growth, divergence between domestic and international markets, and accelerated new energy penetration". Overseas exports and new energy vehicles have become the most core growth engines; export business has evolved from a "bonus item" to the "core foundation" for some companies. BYD's "dominant leader" status is further consolidated, Chery achieved high growth via exports, Geely's new energy penetration rate broke 56%, Changan focused steadily on balanced development, while Great Wall appeared slightly under pressure during structural transformation.
BYD: Export Hits New High Becomes Biggest HighlightIn May, BYD stood firmly at the top of domestic brands with a monthly sales volume of 383,500 vehicles, maintaining positive growth both year-on-year and month-over-month under a large base. Its two main brands, Dynasty and Ocean, sold a combined 330,200 vehicles, contributing 86.1% of total sales; Fangchengbao's monthly sales broke 30,000 units to reach 30,200, a year-on-year increase of 139.7%, setting a new high for the year; Denza sold 16,300 vehicles, and Yangwang delivered 286 vehicles. From a model perspective, BYD had eight models in May with monthly sales exceeding 20,000 vehicles. The Song Family and Yuan Family both broke 50,000 units, selling 51,370 and 56,691 vehicles respectively. The Sea Lion Family followed closely with 42,615 vehicles, and Seagull sales were also close to 40,000 vehicles.
BYD's biggest highlight in May was exports. Overseas new energy vehicle sales reached 160,600 units, an 80.4% year-on-year increase, accounting for about 42%. The sharp expansion of export scale effectively countered the phased weakness in domestic demand. Cumulative exports from January to May exceeded 620,000 vehicles. High export growth mainly benefited from continued ramping up of overseas factory capacity, improved ocean shipping capacity, and accelerated channel network expansion. In the domestic market, BYD promoted Megawatt Super Charging and intelligent strategies simultaneously—Megawatt charging achieved about 90% charge in 9 minutes; 20,000 super charging stations are planned to be built by 2026; all series models are available with Sky Eye B intelligent driving solutions and city navigation safety fallback plans, accelerating the popularization of high-level intelligent driving. As Gen 2 Blade Battery capacity gradually releases, the company's orders are expected to continue rising.
Chery: Sales Growth Leads the Top 5Chery Group's total sales volume in May was 247,800 vehicles, a significant year-on-year increase of 20.5%, ranking first in growth speed among the top 5. Exports remained its most core growth engine—May exports reached 181,900 vehicles, an 80.5% year-on-year increase, accounting for 73.4% of total sales that month, continuously breaking the single-month export record for Chinese brands for three months. In terms of new energy, Chery New Energy sold 100,300 vehicles, a 58.8% year-on-year increase. April and May consecutively saw monthly new energy sales breaking 100,000 vehicles.
The strong performance in exports benefited from Chery's long-term deep cultivation of overseas channel advantages and localized operation capabilities. While overseas orders continued to rise, high export growth formed a sharp contrast with domestic sales—Chery's domestic sales in May were only 60,000 vehicles, accounting for one-quarter of total sales. From cumulative data, Chery Group accumulated 1.101 million sales from January to May, but against the annual goal of 3.2 million vehicles, monthly averages need to reach about 420,000 vehicles later, and pressure remains significant.
Geely: New Energy Penetration Rate Breaks 56%Geely Auto's total sales volume in May was 237,600 vehicles, a 1% year-on-year increase, achieving month-over-month double growth for three consecutive months. In terms of structure, Geely's "New Four Transformations" transformation showed significant results: new energy vehicle sales reached 133,400 units, accounting for 56% of total sales, with new energy share exceeding 50% for four consecutive months.
From sub-brands, performance was significantly divergent. Zeekr brand sales in May reached 34,400 vehicles, a 82% year-on-year increase; Zeekr 9 Series and 8 Series models combined sales approached 50% of total sales, showing bright performance in the high-end market; Galaxy brand sales were 81,700 vehicles; Geely brand sales were 182,500 vehicles, among which China Star Series sales reached 100,800 vehicles; Lynk & Co brand sales were 20,700 vehicles, with new energy vehicle sales share rising to 71%.
In terms of exports, Geely's overseas vehicle exports in May reached 85,100 vehicles, a explosive 184% year-on-year increase, setting a brand single-month export record high. Among exported products, new energy vehicles reached 40,800 units, accounting for nearly half; hybrid and pure electric products have successively landed in Southeast Asia, Middle East, Latin America, and other markets, highlighting the results of global strategy implementation.
Changan: Multi-brand Matrix Balanced EffortChangan Auto's delivery volume in May was 209,100 vehicles, among which new energy deliveries were 92,400 vehicles, a 5.8% year-on-year increase, with new energy share about 44%. In terms of exports, overseas deliveries reached 70,700 vehicles, a 38% year-on-year increase, becoming another major growth highlight for Changan in May.
In the sub-brand matrix, Changan Qiyuan delivered 34,500 vehicles in May; All-New Q05 delivered 15,800 units, with orders breaking 3,000 units within three days of listing in Thailand; Deepal sales in May were 33,200 vehicles, a 30% year-on-year increase; January to May overseas cumulative sales were 28,700 vehicles, a significant 167% year-on-year increase; Avatr delivered 7,336 vehicles in May; Changan Auto (Gravity) delivered nearly 49,000 vehicles in May.
Changan Auto's balanced layout was fully reflected in May: the fuel car base remained stable, new energy brands Deepal and Qiyuan accelerated volume growth, high-end brand Avatr continued to break through in technical cooperation, and overseas markets simultaneously achieved breakthrough growth. The pattern of five brands working together, driven by both new energy and exports, is initially taking shape.
Great Wall: Overseas Sales Growth Year-on-Year 46.75%Great Wall Motor's sales in May were 100,400 vehicles, slightly down compared to last May's 102,200 vehicles, making it the only company among the top 5 to show a year-on-year negative growth. From sub-brands, Haval brand sales in May were 55,500 vehicles, remaining Great Wall's most important sales pillar; Tank brand sales were 17,100 vehicles; both Haval and Tank brand sales showed year-on-year declines; Wey brand sold 8,119 vehicles, a 31.78% year-on-year increase, achieving growth against the trend; Ora brand performance was most stunning, with sales of 6,018 vehicles, a significant 206.88% year-on-year increase. In terms of new energy, Great Wall sold 30,400 new energy vehicles in May, with new energy vehicle transformation gradually accelerating.
The overseas market became Great Wall's biggest highlight in May, with overseas sales growing 46.75% year-on-year. Against the background of pressure on the domestic market, strong growth in overseas business effectively made up for the decline in the domestic market. Great Wall Motor's current core contradiction lies in: Haval and Tank, the two traditional main-selling brands, face weak growth, while Wey and Ora brands, although growing notably, have relatively small volume and are not yet enough to support overall growth. How to complete the "relay" between old and new brands is the key issue Great Wall must solve subsequently.
Final ThoughtsFrom May data, the growth pattern of the top 5 domestic brands has clearly diverged, but there are three common trends worth noting: First, exports have become a key engine for domestic brands to seek stability and growth. Second, new energy transformation is still accelerating, but paths differ among enterprises. Third, technological innovation continues to deepen brand moats. Looking ahead to the second half of the year, competition in the automotive industry will continue to upgrade around these three trends. Although everyone has a common direction, these three trends are all competing for the entire enterprise's industrial chain strength, and the strong will remain strong, which has almost become an inevitable outcome.
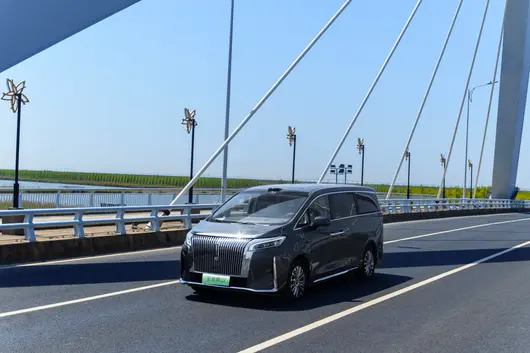
天氣越嚟越熱,係時候帶家人去山入面避暑啦,一台裝得下一家三代嘅 MPV 亦都成為家庭用戶嘅剛需。咁 MPV 點解揀?大家都揀嘅車肯定唔會錯,最新數據顯示,魏牌高山攞咗 2026 年前四個月細分市場嘅累計銷量冠軍,累計獲得超過 10 萬 + 家庭用戶嘅認可,而且 84% 都係個人家庭用戶。除咗國內熱賣,魏牌高山喺泰國、馬來西亞等地同樣反響熱烈,連巴西總統都試乘讚好,真係令人唔禁感慨:以前總覺進口先高級,而家輪到中國車令老外叫好!不知不覺間,魏牌高山唔單止成為家庭 MPV 買車首選,亦令 MPV 成為一種新時尚。

從國內銷冠到圈粉全球,魏牌高山點樣做對咗啲咩?其實答案就藏喺實際用車嘅細節入面:
智能體驗夠慳心,安全配備夠放心,空間設計又令全家人坐得舒心,每一處都令人安心。

魏牌高山嘅含金量,首先來自每日都用得著嘅智能體驗。好多人對輔助駕駛嘅態度係「有也好,冇都好」,可魏牌高山偏偏係佢變成每日出門都會用到嘅功能。早晚高峰接送細路,走走停停之間自動跟車同主動煞車讓你唔使一直緊繃住神經;週末帶全家跨城自駕,車道維持配合自適應巡航,一個人開三四個鐘都唔會太累。佢唔玩花巧嘅噱頭,就踏踏實實幫你分擔最累嗰部分操作,令開車嘅人能夠慳返不少精力,呢種輕鬆感,恰恰係家庭用戶最在意嘅。

而除咗令開車更省力,家用 MPV 嘅安全性能更加係重中之重。魏牌高山用高強度車身、全維主被動安全,再加埋 Hi4 性能版,構築起一套實打實嘅防護牆。遇上濕滑路面或者需要緊急避讓嗰陣,呢啲平時唔顯眼嘅安全配備就會出嚟幫你分憂,揀魏牌高山,圖就係一份由出發到抵達嘅全程安心。

更加難得嘅係,魏牌高山將呢份貼心延續咗去每一排座位入面,真係做到令全家人都有好位置。二三排共軌搭配純平地板,細路喺車入面輕鬆走動,老人家上車都唔使費力彎腰;零重力座椅一鍵就能瞓平,後排娛樂屏幫手哄細路,長途落嚟都唔會覺得累;Hi4 性能版嘅動力輸出特別平順,連平時容易暈車嘅家人,坐喺車入面都唔咁難受啦。唔論係日常接送、週末露營定係假期自駕,魏牌高山基本上實現咗「細路唔鬧、老人家唔累、大人唔崩」。一台車輕鬆搞定三代人嘅需求,將家庭友好做到呢份上,賣得好亦都順理成章啦。

由今年前四個月嘅累計銷量冠軍,到 10 萬 + 家庭嘅口碑驗證,再到海外市場嘅成功,魏牌高山冇去卷價格、卷配備表,而係踏踏實實將「全場景安心體驗」做成自己嘅專屬標籤。如果你而家正為一家人搵一部邊個坐都滿意、開去到邊度都安心嘅車,不妨去體驗下魏牌高山,開上你就能感受到佢家用 MPV 人氣王嘅魅力,唔止舒服仲型,全家人都鍾意!
比亞迪正式發布 2026 年 5 月產銷快報,全品牌新能源汽車單月銷量 383453 輛,同比微增 0.26%,時隔十個月實現單月銷量同比轉正;其中乘用車交付 376990 輛,環比大漲 19.4%,一掃前期車型換代陣痛,呈現國內基本盤穩固、海外銷量狂飆、高端品牌全線放量的全新格局,在國內新能源內捲加劇、特斯拉 FSD 入華、自主新品密集上市的市場環境中,走出獨有的結構性增長路線。

王朝 + 海洋兩大主力品牌 5 月合計售出 330215 輛,佔據集團總銷量超八成,仍是比亞迪銷量壓艙石,全系列共 8 款車型單月銷量突破 2 萬台,產品從 5 萬入門代步到 20 萬家用 SUV 實現全覆蓋。

王朝網內部,元家族 56691 輛、宋家族 51370 輛。雙雙跨過五萬門檻,成為品牌兩大銷量支柱,兼顧家用代步與城鄉出行需求;秦家族緊隨其後交出 28360 台穩定表現,漢、唐系列月銷維持六千級體量,深耕中大型家用轎車、SUV 細分市場;全新車型夏處於市場培育期,單月交付 1810 台,後續隨渠道鋪開有望穩步上量。
海洋網增長勢頭更為迅猛,全系五款車型跨入兩萬俱樂部:海獅 42615 台、海豹 34117 台、海鷗 39919 台、海豚 22260 台、宋 PLUS 27755 台。其中海鷗憑藉 6-8 萬親民定價穩居入門代步銷冠,海獅作為全新走量車型上市即站穩四萬量級,補齊海洋網中型 SUV 產品空白,完善海洋產品梯隊佈局。從代步小車到緊湊 SUV,兩大主品牌依托 DM-i 混動與純電雙線技術,牢牢鎖住 15 萬以內國內主流家用市場份額。
方程豹同比暴漲 139.7% 品牌向上落地見效騰勢、方程豹、仰望組成的高端矩陣 5 月合計銷售 46489 輛,正式擺脫小眾定位,成為比亞迪品牌溢價與利潤增長新支點,打破自主品牌高端化難破局的行業魔咒。

越野品牌方程豹單月 30186 輛,同比暴漲 139.7%,創下品牌上市以來月度銷量新高,旗下鎦 7 單月 18280 台,豹 5、豹 8 穩定輸出,在 25-40 萬硬派越野細分市場持續擠壓合資、進口車型生存空間。

騰勢 5 月交付 16303 台,MPV 標桿 D9 售出 6721 台,Z9 系列近 6000 台,MPV、中大型轎車雙線發力,站穩豪華新能源賽道;百萬元級超豪華品牌仰望穩步爬坡,當月交付 286 台,同比增幅 105.8%,完成自主品牌天花板產品的市場驗證,形成從十幾萬家用、三四十萬越野、五十萬豪華 MPV 到百萬元級旗艦的全價格帶產品佈局。

5 月比亞迪乘用車和皮卡海外銷量 160177 輛,同比大漲 80.7%,出口佔全系總銷量突破 42%,創下品牌出海歷史新高,成為穩住 5 月整體銷量、實現同比轉正的核心驅動力。
東南亞、歐洲、拉美成為主力增量市場,海鷗、宋 PLUS、元系列持續登頂多國新能源熱銷榜單,SHARK 皮卡連續兩月單月出口突破 4000 台;依托泰國、巴西、匈牙利、烏茲別克斯坦四大海外整車工廠落地投產,本地化生產持續落地,規避關稅同時快速下沉終端渠道。在國內車市存量競爭、價格戰常態化背景下,高速擴容的海外市場有效對沖國內車型換代帶來的銷量波動,正式從補充市場升級為比亞迪核心增長引擎。截至當前,比亞迪新能源汽車全球累計銷量已經突破 1650 萬輛,全球化版圖持續拓寬。
智駕賦能產品迭代 下半年新品蓄力衝量5 月比亞迪智能化落地迎來關鍵節點,天神之眼智駕系統成為車型核心加分項:全品牌搭載高級智駕車型保有量突破 315 萬輛,日均路測數據超 2 億公里;當月比亞迪落地城市領航、智能泊車雙安全兜底服務,成為全球首家實現兩項智駕兜底的車企,政策落地三天後,搭載天神之眼系統車型的城市 NOA 激活率暴漲 50%,智能化體驗升級直接拉動終端到店訂單轉化,為後續車型持續走量築牢產品競爭力,直面 FSD 入華帶來的智駕市場衝擊。
從數據細節來看,2026 年 1-5 月比亞迪累計銷量 1405039 輛,同比下滑 20.32%,核心誘因是全系主力車型集中換代、第二代閃充刀片電池產能爬坡受限。新款閃充電池升級快充與低溫性能,全系換代車型優先換裝新電池,但產線改造拖累產能釋放,熱門車型訂單積壓、交付延後,一定程度壓縮 5 月交付體量。
隨著二季度末二代刀片電池產能持續釋放,疊加騰勢 N8L、方程豹鎦 7 純電版、海獅 05、夏 L 等多款新車陸續登陸市場,業內普遍預判比亞迪 6 月全品牌銷量有望突破 40 萬輛。依托低端走量鎖份額、高端提利潤、海外衝增量、智能化提產品力的四維發展邏輯,在國內新能源淘汰賽加劇的當下,比亞迪全品類佈局優勢持續放大,坐穩國內新能源龍頭,加速向著全球頭部車企穩步邁進。