首頁Wang Chuanfu

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
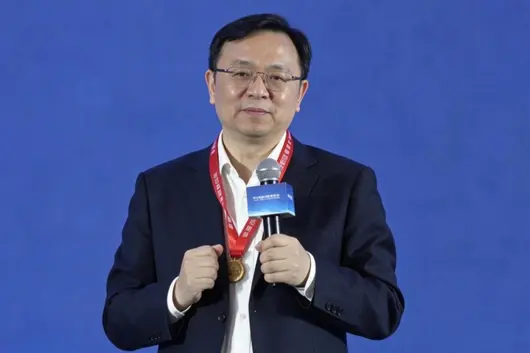
October 28, 2026, Suzhou, Wang Chuanfu accepted the highest honor of China's automobile industry—the Rao Bin Award.
On this awards stage known as the "Nobel Prize" of China's automobile industry, he looked back on the hardships BYD has come through and mentioned the achievements made today.

But in the end, he folded the storms, grievances, and glory of these twenty years into a single sentence:
"I wanted to solve a proof problem, to prove that Chinese new energy is viable, and Chinese automobiles are viable."
It was still him, the one who once shouted "Together, we make the Chinese Auto Industry", today still speaking in the same language.
(1) Backbone and Responsibility
Wang Chuanfu has a very friendly nickname, called Brother Boatman.
This nickname started as a pun, but later also symbolized his early days on the small boat of BYD, which was in turbulent times, gritting his teeth and rowing desperately.
Today, this small boat has grown into a giant ship with an annual sales volume of 4.6 million vehicles, entering the first tier of global automakers.
Wang Chuanfu has also changed from a boatman to a captain.
And between the boatman and the captain, there is more than just time.
To see why Wang Chuanfu speaks and chooses routes like this today, we must first turn the ship back, to the time when he was just a young man being repeatedly questioned at the customs.

In his early years, he did battery exports and frequently traveled to Europe and the United States. At customs, the counterparts repeatedly asked him to show return tickets, fearing he would refuse to leave, which made him very angry and felt unjust.
He said: "We Chinese people are not stupid, nor lazy, why do we not have corresponding status?"
That spirit became the strongest keel of BYD's small boat later on.
After starting car manufacturing, he insisted on changing all the physical buttons in the car to Chinese.
Others advised him, it's too earthy, it will affect sales.
But he said: "For things involving the foundation of Chinese culture, we must persist."
This persistence has continued to this day.
So BYD has product naming unique to Chinese culture, and the distinctive "Dragon Face Design" aesthetics.
He wants a Chinese car to reveal Chinese confidence from the inside out, from name to appearance, from bone structure to soul.

This is Wang Chuanfu's fiery spirit, but it goes beyond that.
In 2020, during the most serious part of the epidemic, masks became lifesaving materials.
Wang Chuanfu gave an order, more than 3,000 technicians drew more than 400 mask machine blueprints in three days, and the first equipment was built in seven days.
In less than a month, they accomplished the world's largest mass-produced mask factory.
Later in interviews, he said: "If the country has difficulties, we will manufacture."
This is Wang Chuanfu's sense of social responsibility and accountability.
(2) Foresight and Ace Card
However, a small boat becoming a big ship, a boatman becoming a captain, blood and responsibility are not enough.
A captain must look up at the sky, the wind direction, and the routes others cannot see.
At this time, we can see Wang Chuanfu's foresight.
In 2014, joint-venture brands were at their peak in the Chinese market; paying premiums for cars was the norm.
He predicted that joint-venture cars were too comfortable, and sooner or later would be beaten by Chinese automobiles.
At that time, everyone thought he was bluffing. Now facts prove he was right.

In 2015, at the BYD Fans Conference, he said that future electric vehicles would run even after the front wheel burst and was thrown away.
In 2023, DiSus-X allowed a Yangwang U9 to drive steadily with a missing wheel.
What explains him choosing routes in the fog even more clearly is the battery lifeline.
From the beginning, Wang Chuanfu targeted Lithium Iron Phosphate (LFP).
Because what he calculated was not temporary parameters, but the lifeline: Nickel-Manganese-Cobalt (NCM) relies on cobalt and nickel, which are extremely scarce in China and can be choked at any time; while Lithium Iron Phosphate has independent resources and is extremely safe.
But reality quickly slapped him in the face. In those years, subsidy policies chased energy density, and the whole industry疯狂ly swung towards NCM, forcing Lithium Iron Phosphate into a corner.
To survive, BYD also compromised, and the main models switched to NCM on a large scale with the industry.
Those were the most dangerous years for BYD. By 2019, subsidies were cut, and sales slumped. Wang Chuanfu later recalled that at the time, there was only one goal: to survive.
But compromise was temporary; Wang Chuanfu did not completely stop the R&D of Lithium Iron Phosphate.
At the 2019 "Qinghai Conference", he led the team to ask a different question: Since we cannot compete on energy density in materials, let's compete on structure. Thus, the Blade Battery was born.

Why can he accomplish this? It is because BYD has always had an ace card that others do not have—Vertical Integration.
Others rely on buying to build cars; from the first day of making batteries, BYD was used to making whatever is missing themselves.
This vertical integration foundation is also the hardest ace card for BYD in later price wars.
In the second half of electrification, the routes Wang Chuanfu chose were still very "precise".
In intelligence, he did not treat intelligent driving as a premium chip for high-end cars, but turned it into a universal standard.
And in terms of energy replenishment, releasing the second-generation Blade Battery and Megawatt Flash Charging, planning to build 20,000 flash charging piles by the end of this year.
(3) Grand Vision and Open Ocean
However, the quality of a captain is ultimately not only judged by where he drives the ship alone, but also by how he treats other ships in the vast sea.
In 2023, when BYD's 5 millionth new energy vehicle rolled off the line, he placed models from thirteen partner companies in front of the big screen.
That promotional video "Together, We Make the Chinese Auto Industry" began with "This year is the 70th anniversary of China FAW's establishment", starting from the first "Jiefang" car, paying tribute one after another to FAW, Dongfeng, Changan, SAIC, GAC, Chery, Geely, Great Wall, and also paying tribute to NIO, XPeng, and Li Auto.

Later, the public opinion in the Chinese automobile market became complex, with open and hidden attacks. However, at the shareholder meeting, he said: "We are the leader, we can be bullied a bit, but we cannot bully others."
"Practicing only Wing Chun cannot make a martial arts world. Only BYD cannot make the Chinese Auto Industry."
This is Wang Chuanfu's grand vision.
Today, the Chinese automobile fleet jointly composed of various car companies with BYD as one of the flagship ships has entered the open ocean.
In the first half of 2026, BYD's overseas revenue share exceeded domestic for the first time; export sales approached 800,000 vehicles, and business covers 121 countries and regions.
In the UK, sales exceeded 50,000 in 2025, and in the first four months of 2026, it once topped the pure electric sales list; in Brazil, sales were about 110,000 in 2025, and the pure electric market share once reached 78% in February 2026; in Thailand, as of July 2026, the factory had cumulatively delivered more than 130,000 vehicles.

And the entire Chinese automobile fleet is also going further. In the first half of this year, the total export of Chinese automobiles reached 5.096 million vehicles; June even achieved a single-month export sales breakthrough of one million vehicles.
(4) Kung Fu Verdict
Back to the Rao Bin Award stage.
From the young man being questioned at customs back then to today, standing on stage as a leader of China's automobile industry.
What Wang Chuanfu wants to prove is never just how many cars BYD can sell.
He wants to prove that cars built by Chinese people can not only price themselves but also set their own rules.
He wants to prove that this fleet named "Chinese Automobile" can not only go out, but also let the whole world see, and get used to the presence of Chinese automobiles.
In the past, he became the captain of the BYD giant ship, a boatman gritting his teeth in the wind and rain.
Today, he is the flagship captain sailing the entire Chinese automobile fleet into the open ocean.
In September just passed, BYD stood on the sales champion podium again.
However, behind the crown's glory, the comparison of data is striking: domestic sales dropped nearly 13%, overseas sales surged over 153%. BYD's growth engine, from the fierce red ocean competition domestically, shifted to the high-risk blue ocean market overseas.
Wang Chuanfu steers BYD towards the deep blue, but ahead waiting for him are two major challenges that must be overcome.

In September just passed, BYD sales remained very hot.
Sales and production bulletin shows, in this year September BYD new energy vehicles sold 463,600 units, compared to 396,300 units of the same period last year, a year-on-year surge of 16.99%.
Such dazzling achievements keep BYD far ahead in the industry. At the same time, SAIC Group 406,000 units, nearly 60,000 units less than BYD.
Also Chery 292,300 units, Geely 292,200 units, Changan 228,900 units, Great Wall 114,900 units, all are far from BYD.

It is worth noting that, among BYD's 463,600 units total sales, domestic sales 282,900 units, year-on-year decline 12.97%; overseas sales 180,700 units, year-on-year surge 153.59%.
CPCA data shows, domestic car market September sales year-on-year decline about 25%.
Although BYD domestic sales ran ahead of the general market, the strong contrast of their domestic and overseas sales rise and fall also indicates, when domestic price war sees no end, and plug-in hybrid bonus accelerates to vanish, overseas is no longer a "side plot" to add icing on the cake, but a "main quest" concerning future survival.
Sales growth focus shifts outward, BYD enters a new battlefield.
2. From Making Cars to Making ShipsLeading BYD into this new overseas battlefield, Wang Chuanfu faces two challenges. The first challenge, ships are not enough. Who would have thought, BYD's biggest bottleneck going overseas currently is not cars but ships.
BYD is very hot overseas, if not for transport capacity limits, sales could be increased significantly. To some extent, this is a sweet burden.
As early as 2022, Wang Chuanfu invested 5 billion yuan to order Ro-Ro ships, building a proprietary fleet. January 2024, the first "Pioneer 1" made first voyage to Europe.
Since then, Changzhou, Hefei, Shenzhen, Xi'an, Changsha, Zhengzhou, Jinan ships joined sequentially. A total of 8 ships, annual capacity over 1 million units.

But for today's BYD, such capacity is already far from enough.
This year BYD car export target, jumped from 1.5 million units to 2 million units, next year is as high as 2.5 million units. Existing capacity is like a small boat crossing a river, hard to carry massive volume.
So BYD added again, ordered 10 more Ro-Ro ships, 2027 to 2029 batch delivery.
At that time, BYD's own car transport fleet will expand to 18 ships, annual transport capacity from current 1 million level, jump to 2.5 million level. Export sales constrained by capacity limits, BYD must win this "capacity battle".
3. The Road to Globalization is Still LongTransport ships transport cars manufactured domestically to overseas markets, building factories abroad means directly making cars locally and selling directly.
With Chinese cars becoming more and more powerful, causing certain impact on car markets in multiple overseas countries, they started requiring Chinese car companies to build factories locally, make cars locally and sell locally, keeping jobs, taxes, etc., also locally.
BYD and other Chinese car companies, while transporting Chinese cars out overseas, also need to invest heavily in building factories overseas.
Toyota with annual sales exceeding 10 million units, why becoming the world's largest car company, mainly rooted in it having factories, suppliers, dealers, financial services and after-sales networks everywhere in the world.

Including Europe, Japan, India and other multiple major car markets, currently all have obvious entry barriers for Chinese cars.
They mainly target vehicles entering local markets from China in export form, surrounding and intercepting Chinese cars through tariffs and other measures.
Japanese car companies like Toyota, when going global back then, also encountered such entry barriers. In the 20th century Japanese cars entered the US at the beginning, also encountered huge political resistance.
So Toyota no longer stuck to the old path of "Made in Japan, Sold Globally", but spread production lines overseas, completing manufacturing and sales locally.

BYD currently also walks this path, accelerating overseas factory investment and construction, such as Thailand and Indonesia factories in Southeast Asia, Hungary factory in Europe, Brazil factory in the Americas, etc.
This is letting BYD take root locally, from "Chinese export car company" changing to "Local car manufacturer". Of course, investing and building car factories is just the first step.
Whether R&D management can integrate, whether after-sales can keep up, whether products can adapt to regulations, unions and consumption habits... BYD has many more things to do.
From "BYD of China" to "World BYD", BYD's globalization speed is fast, but compared to giants like Toyota, there is still a long road to go.
On September 29, the first meeting of the 9th Board of Directors of BYD concluded. Wang Chuanfu was elected Chairman unanimously and will continue to concurrently serve as President.
This marks a new three-year board term for Wang Chuanfu. The 8th Board of Directors, whose term just expired, served from September 2023 to September 2026. For this rotation, the 9 votes of the Board unanimously passed key personnel appointments: Lyu Xiangyang appointed as Vice Chairman, Li Ke, He Zhiqi, and 10 others appointed as Vice Presidents, Zhou Yalin serving concurrently as Vice President and Financial Director, Li Qian serving as Board Secretary.  The core executive team largely continues without drastic personnel changes, confirming shareholder approval of the operational performance report for the 8th term.
When the 8th Board took office, BYD was already standing on the results of the explosive electric growth era. During the 7th Board term, from 2021 to 2023, BYD completed the most critical sprint for scale transformation. In 2021, BYD revenue was 216.142 billion yuan, net profit attributable to shareholders 3.045 billion yuan; by 2022, BYD new energy vehicle sales surpassed Tesla, topping the global new energy sales list. This vertically integrated system built by Blade Battery, DM-i hybrid, and e-Platform 3.0 released huge dividends in this phase, supporting rapid domestic capacity expansion. The Denza, Yangwang, and Fang Cheng Bao high-end brand matrix also began laying out plans sequentially.
Entering the 8th Board term, after taking over in September 2023, the company continued to fulfill the expansion rhythm. In 2024, BYD revenue grew to 777.1 billion yuan, net profit attributable to shareholders 40.254 billion yuan, with gross margin reaching up to 19.44%. In four years, revenue and profit achieved several-fold growth. Strong cash flow supported nationwide capacity expansion and early overseas layout.
The sales curve, without a doubt, is the most impressive report card of the 8th term. In 2024, BYD new energy vehicle sales reached 3.024 million units. During that period, overseas business was still in the starting stage of product export. In 2024, overseas vehicle exports reached 420,000 units, and the proportion of overseas revenue was still not high.
R&D investment continued an upward trend during the 8th term. In 2024, R&D investment was 53.195 billion yuan. Funds were used to consolidate electric hardware foundations such as Blade Battery, DM-i hybrid, and e-Platform 3.0 on one hand; on the other hand, resources began shifting to frontier fields like automotive grade semiconductors and self-developed intelligent driving chips. Talent construction focus was initially on manufacturing and supply chain engineers, hiring in large batches to quickly fill capacity gaps and handle explosive domestic orders.
After the dividend window closed, the underlying market logic has completely switched. In 2025, the closing year of the 8th term, financial report data already reflected cycle changes. Full-year revenue was 803.96 billion yuan, only growing 3.46% year-on-year; net profit attributable to shareholders was 32.62 billion yuan, a year-on-year drop of 18.97%, gross margin fell back to 17.74%. Net cash flow from operating activities was 59.135 billion yuan, significantly down year-on-year. Funds were consumed heavily in overseas factory building, intelligent R&D, and continuous high-end brand investment. Fortunately, cash reserves were sufficient, leaving enough capital to continue adding.
Comparing the income statement, changes in the sales structure are more worth examining. In 2025, BYD new energy sales were 4.6 million units; overseas exports 1.05 million units, breaking the 1 million mark for the first time, with a significant increase in the proportion of overseas revenue. Domestic market growth slowed significantly, and the growth focus completely shifted to overseas localization production. Denza, Yangwang, and Fang Cheng Bao high-end brands continued to expand volume, and structural improvement for brand elevation is happening, but high-end brands are still in the investment ramp-up phase, and it is difficult to significantly pull overall profit margins in the short term.
The R&D focus also underwent a fundamental shift in the second half of the 8th term. In 2025, R&D investment was 63.4 billion yuan, with R&D personnel reaching 120,000. Funds were no longer focused solely on three-electric hardware; the focus extended to automotive grade semiconductors, self-developed Xuanji A3 intelligent driving chips, whole vehicle software stack, flash charging system, and second-generation Blade Battery. Overseas localization layout accelerated, with Thailand and Brazil factories put into production, and the Hungary European factory under construction. The model upgraded from simple export sales to heavy-asset globalization involving local factories, local supply chains, and local channels. Along with this came EU carbon tariffs, anti-subsidy investigations, trade barriers in various countries, and geopolitical risks.
The brand matrix also showed a differentiated pattern typical of a transition period. Denza steadily increased volume, with losses continuing to narrow; Yangwang and Fang Cheng Bao completed product launches, opening up brand visibility, but high-end brand R&D and channel construction investment was huge, making it difficult to contribute positive profits in the short term.
Talent and governance structures also adjusted synchronously with globalization and intelligent transformation. The 9th Board revised the Rules of Procedure for the Strategy and Sustainability Committee and formulated the President's Work Rules in this session, institutionalizing the flexible management model during the high-speed expansion period. Talent recruitment directions shifted from absorbing manufacturing engineers in large batches to composite talents in software, intelligent driving, overseas compliance, and local operations. The market competition for high-end talent in software and intelligent driving is fierce, and building overseas local management teams also requires a long cycle.
Looking at the industry overview, the market environment has entered a saturated competition stage. Domestic new energy market growth has slowed, and price wars continue to compress profit per vehicle; in the intelligent driving track, BYD has a strong hardware foundation, and whole vehicle software and advanced intelligent driving capabilities are still in the process of continuous improvement. 
As early as the starting stage of electric transformation, Wang Chuanfu released clear medium-to-long-term goals: relying on vertical integration to gain new energy cost advantages, quickly seizing market share, pushing for the global new energy sales leadership, and steadily promoting passenger vehicle exports. At the 2025 Shareholders' Meeting, Wang Chuanfu further clarified long-term goals: achieving number one in global automotive scale by 2030.
Looking back at the fulfillment of the 8th term: the status as the global new energy sales leader was continuously consolidated, overseas exports started from a low level and broke through 1 million units at once; the high-end brand matrix was built; R&D investment fulfillment intensity even exceeded expectations. However, when setting goals early on, the industry had not yet entered deep saturated competition. Continuous domestic price wars and large-scale long-term investment in the intelligent track were variables not fully predicted at the time.
The nearly 20% drop in net profit attributable to shareholders in 2025 was not a collapse of traditional whole vehicle business. Profits were consumed in two directions: one is large capital expenditures brought by overseas localization factory building and channel layout; the other is continuous R&D investment in intelligent chips, software, and high-end brands. Management defined the profit pressure as necessary investment during the globalization and intelligent transformation period. Whether the investment can be converted into stable profit increments will be the core observation item of the new 9th term.
The strategic framework for the new term has been clarified: dual drive for domestic and overseas, continuously increasing the proportion of overseas sales; relying on Denza, Yangwang, and Fang Cheng Bao to increase average price per vehicle, hedging against domestic price wars; promoting the landing of self-developed intelligent driving chips and flash charging ecosystem, expanding the second growth curve of energy storage, laying the foundation for achieving global automotive sales number one in 2030.
Focusing on short-term operating goals, the focus is very clear: continuously landing overseas localization capacity, expanding overseas market share; making up for whole vehicle software and advanced intelligent driving capabilities; optimizing high-end brand profitability, balancing capital expenditure and cash flow. In the next three years, R&D investment will continue to maintain a high level, continuously investing in intelligent platforms, overseas capacity, and new generation battery technology.
Wang Chuanfu continues to serve concurrently as Chairman and President. This highly unified decision-making model proved extremely high execution efficiency during the past industry explosion period. But for these three years of the 9th term, it is no longer a stage of simply "expanding total volume" during the industry dividend period.
In past board cycles, BYD grew from a domestic manufacturer selling 600,000 new energy vehicles annually to a car company with 4.6 million units scale and number one in global new energy sales. Domestic market profits are under continuous pressure, while overseas heavy asset investment and long cash-burning cycle of intelligent R&D officially commenced. Over the next three years, BYD needs to continuously verify: relying on vertical integration, global layout, and continuous investment in self-developed technology, stabilizing profit levels, making up for intelligent shortcomings, steadily promoting the long-term plan of being number one in global scale by 2030, and continuously optimizing operational quality beyond sales.
Holding sufficient cash reserves, two major long-term investment blueprints of globalization and intelligence are spread out before. For this new term of Wang Chuanfu, the core task is to continuously polish the profitability of the BYD technology system after scale dividends gradually peak, and calmly respond to the complex trade and technology competition cycles of the global automotive industry.
Source: Car Observer

Snatching Toyota.
Writer|Hu Chengxu Editor|Mao Shiyang
Auto Pixel (ID:autopix)Original
June 9, like in previous years, BYD held its 2025 Annual Shareholders' Meeting at its headquarters in Pingshan, Shenzhen.
More people came than in previous years, so the company temporarily moved the venue from a meeting room to the hall usually used for press conferences. Wang Chuanfu said on stage that nearly 1,000 people attended today, the most in history.
During the Q&A session, a long-term shareholder with heavy stakes stood up. He wanted to know where the company would head next.
In Wang Chuanfu's answer, a word appeared for the first time: "Global No. 1". He said that in the next three to five years, BYD will continue to grow. After five years, in terms of scale, it will achieve "true Global No. 1".
Not No. 1 in New Energy, not No. 1 in China, but No. 1 in total vehicle scale including Toyota, Volkswagen, Hyundai Kia, etc.
When saying this, BYD was experiencing the biggest deceleration since the New Energy era. In the first five months of 2026, BYD sold 788,000 vehicles domestically, down 43.3% year-on-year. The Chinese market is becoming increasingly difficult to provide the incremental growth it enjoyed in the past.
So Wang Chuanfu's goal truly points to overseas.
Take a closer look at what BYD has done in the past two to three years, this goal is not strange. Its playbook no longer resembles that of a company only wanting a seat at the table overseas.
01
What BYD Wants to Grab,
is the Base of Toyota, Hyundai, et al.
To understand how far BYD is from its goal, one must first look at the gap.
Today, the global No. 1 in auto sales is Toyota, selling a bit over 10 million a year; BYD sold 4.6 million vehicles in 2025, ranking sixth globally. There is a gap of more than 5 million vehicles in between, roughly equivalent to creating another BYD of today's scale on top of its existing volume.
As for this extra 5 million-plus vehicles, what is certain is that most of it will not come from the domestic market.
In 2025, China's New Energy penetration rate reached 53.9%, approaching the ceiling; BYD's domestic sales that year fell instead of rose, down by over 300,000 vehicles compared to 2024.
Geely, Chery, and Changan are all chasing, and this local board is nearly at its peak, with limited incremental growth left to extract. The growth gap is thus pushed overseas as a whole. Outside China, the global New Energy penetration rate is still just over 11%.
But "overseas" is never a single block; its biggest chunks happen to be where BYD cannot enter. The US uses tariff and regulatory barriers to seal off the world's largest and most profitable market; Japan and South Korea are fortresses of local brands, hard for outsiders to pry open; India blocks Chinese cars out with high tariffs and entry barriers.
What remains available are South America, Southeast Asia, Central Asia, Australia, the UK, Gulf States, as well as parts of Europe and Mexico. The market set is smaller, and the share burden for each location to reach is heavier.
And these open markets are none of them empty fields.

Southeast Asia is Toyota's home court, where it holds nearly 40% share; BYD has only just squeezed into the top 3 in Thailand. Australia is even more extreme, with Toyota holding sales No. 1 for 23 consecutive years, sales at two and a half times the second place; Gulf States are the common dominion of Toyota and Hyundai Kia, where Toyota's market share is champion in countries like Saudi Arabia, UAE, and Oman.
Only in Brazil is the stock held by Stellantis, Volkswagen, Hyundai Kia, and Renault.
List the owners of these markets one by one, names will repeat constantly; the most frequent is Toyota, followed by Hyundai Kia, then Volkswagen, Stellantis, and other European automakers.
So the overseas granary BYD wants to grab is a very specific existing stock, the base built up over decades of fuel cars by Japanese and Korean automakers.
What it truly wants to replace is RAV4, Corolla, Elantra, Creta and similar economy, durable, high-volume cars sold for decades, using its own DM-i PHEV and Blade Battery EV to replace them one by one within the highest-volume price bands in each market.
Straighten out the chain, and the slogan "Global No. 1" landing on the ground is actually a simpler sentence: BYD must take the home base they've sold for decades within the Toyota and Hyundai Kia base.
This is a ruthless fight; how many opportunities does it have?
02
Wang Chuanfu Writes Growth into a Production Schedule
Faced with questions like "how to go from sixth to first", Wang Chuanfu's habit is to rewrite it as a supply-side arithmetic problem.
On June 9, what he talked about most was not the market, but production capacity. He said how many cars can be sold this year depends on how many batteries can be built; the capacity of the 2nd Gen Blade Battery is climbing month by month, adding 20,000 to 30,000 sets each month; production capacity will be released on a large scale by 2027, and both domestic and overseas markets will see volume increases.
An issue that should be about market and product was interpreted by him as "how much I can make". In his narrative, demand seems assumed sufficient, and the bottleneck lies on his production lines.
Wang Chuanfu seems to believe that if the technology curve of domestic New Energy in the past three years reenacts overseas, the remaining problems can be left to the production schedule.
This logic can explain BYD's overseas layout over the past two years.

It has at least six factories under construction or planned overseas: the Brazil Camaçari plant is a renovation of an old factory exited by Ford, secured in 2023, with the first car rolling off the line in July 2025, targeting 300,000 capacity by end of 2026; the Thailand plant started production in 2024, with an annual capacity of 150,000; the Hungary Szeged plant serves as Europe HQ; Turkey plans to invest 1 billion USD (potentially delayed); Uzbekistan and Indonesia each have points set up.
BYD's playbook's starting point is a bet on speed.
Looking back at BYD's rise domestically, it relied on technology first. In 2021, the 4th Gen DM-i made PHEV the same price as same-level fuel cars with lower fuel consumption; the Blade Battery simultaneously solved safety and cost, with PHEV annual sales jumping from 270,000 to over 2 million vehicles in two or three years.
During those years, China's New Energy market was almost empty; whoever put electric cars that were easy to use and cheap on shelves first could capture whole chunks of incremental growth.
This playbook continues to now. At this year's shareholders' meeting, Wang Chuanfu said "I spend about half my time every week swimming in the ocean of technology", believing he is "one of the 120,000 engineers inside BYD".
But now this playbook's process of converting to sales is not so smooth. Geely, Chery, Leapmotor have caught up one by one; DM-i is no longer a secret technique; not just BYD makes Flash Charge.
Technology is becoming more homogeneous, approaching the physical ceiling further; taking half a step forward brings less and less sales.
Overseas is another matter. Outside China, New Energy is still at the starting point BYD faced years ago: low penetration, few good cars, high prices, most markets still dominated by fuel cars.
The technology curve that once lifted BYD to sixth globally has barely started climbing overseas. What BYD wants to do is take the most advantageous position before this curve rises, copying the success already verified domestically exactly onto a larger plate.
This explains why the overseas game is played heavily and urgently. BYD judges the window period is limited; once overseas New Energy also ramps up, pursuers will flood in as they did domestically, and the time left for first movers might not be longer.
It is unwilling to spend time waiting for the market to mature, and even less willing to hand over initiative.
This June, foreign media claimed BYD is considering acquiring an old European factory, having looked at "many factories" in Europe and is talking with automakers including Stellantis.
BYD prefers independently operated factories; it wants to take over brownfield factories that can be quickly renovated and operated independently with clear ownership and operational boundaries, rather than getting stuck again in existing European auto JV, leasing, or multi-party interest structures.

Key factories and supply chain self-led; distribution and brand also controlled by self as much as possible, serving efficiency and speed. It would rather not have risk-sharing partners first, and have a decision chain that can drive the fastest.
The Brazil old factory renovation took only 16 months from groundbreaking to first car off the line. Export modules are the same; a 6 to 8-ship fleet brings overseas logistics into its own hands. On the channel end, BYD took an equity stake in a Thai local dealer, bound a dealer group with over 100 stores in Latin America; UK authorized stores increased from 52 to 125 in one year, and signed a 100,000 unit deal with Uber.
Following this logic, overseas moves connect into a line. The strategy Wang Chuanfu launched is a replicable template; this is why when asked about sales, he answers with "production schedule" logic.
Whether it holds ultimately rests on that most fundamental judgment: the technology-pulled market curve, how steep it was domestically in recent years, will be equally steep in many overseas markets in coming years.
As long as this judgment holds, simplifying the problem into a production schedule is the fastest solution.
03
BYD VS Geely
Same Overseas Expansion, Different Betting Methods
A easily occurring misunderstanding is summarizing BYD's overseas expansion as "more valued" than Chery or Geely.
In terms of aggressiveness, all three are actually neck and neck. In terms of overseas volume, Chery sold 1.34 million vehicles overseas in 2025, nearly 300,000 more than BYD, sitting on the Chinese passenger vehicle export champion spot for over 20 consecutive years; in terms of capital courage, Geely has bought all the way from Volvo, Lotus, Polestar to a powertrain JV with Renault.
The real difference is not in the degree of aggressiveness, but in the strategic judgment behind the aggressiveness.
Chery bets on export breadth: complete vehicle export plus semi-knocked-down assembly, spreading cars to corners others can't reach, essentially an asset-light playbook.
Geely bets on capital and alliances; Li Shufu is more like an allocator. He grabs core capabilities on one side, polishing smart and New Energy tech to optimal; on the other side, he takes shares and makes allies, seeking leverage at the factory and channel levels.

▍Li Shufu
This year, Geely's Qianli Haohan G-ASD obtained EU UN R171 certification, becoming the first Chinese ADAS system to pass this regulatory certification; equipped models can be sold in the EU without country-by-country re-certification.
At the same time, Geely integrated Gothenburg and Frankfurt R&D teams, established Geely Technology Europe, planning to compress the launch time gap between China and overseas models from over a year to within 6 months.
Also this year, Lynk & Co's Europe sales reuse Volvo resources; Geely in South Korea and South America reuses Renault resources. Gan Jiayue of Geely Automobile has said, Chinese brands going overseas is not to "conquer", but to "walk in", local JVs, reusing local resources to make win-wins, this is the natural expression of this logic.
Behind the three choices are three strategic judgments, and also three judgments on where the moat should be built.
Geely's judgment on tech replacement is not so anxious. In March this year, at the Geely Holding FY2025 performance press conference, CEO Gui Shengyue said the future economy passenger car market will likely be replaced by robotaxis. Shortly after, Geely became one of Nvidia's automotive partners.
This judgment shows Geely does not see today's New Energy competition as the final outcome. It believes there will be longer tech rearrangements after the auto industry, so it is more willing to keep elasticity using cooperation and capital allocation.
Because of this difference, Geely is not anxious to raise "No. 1", nor will it compress the time to first to five years. It is more like betting on the future rather than pressing all chips on this current New Energy replacement round. So Geely's choices overseas are almost the opposite of BYD's: willing to accept slower, more dispersed, more complex.
BYD wants to maximize scale with batteries, factories, fleets, and channels; Geely is more willing to take more positions in tech routes, regional markets, and partnership relationships.
04
The Other Side of the Production Schedule
Reaching No. 1 in scale is a goal setting, a strategic judgment, and will eventually become a structure.
In 2026, Geely, Chery, Changan, Great Wall almost all offered oil-electric hybrids, to grab Toyota THS share in markets with inconvenient charging,唯独 BYD absent.
Technically it is not incapable. This round of HEV by Chinese automakers is not replicating Toyota THS. It bypasses engines, planetary gears, and long-term calibration that old auto giants are good at, pulling the battlefield back to electric drive systems more familiar to Chinese automakers, downsizing batteries, removing external charging, keeping the PHEV low fuel logic, becoming a hybrid that doesn't need charging.
But BYD chose not to do it, turning to laying charging facilities overseas.

In March this year, BYD booked a stadium with 18,000 seats to launch the 2nd Gen Blade Battery, simultaneously launching the plan "Flash Charge China, Change the World". Wang Chuanfu spoke alone for an hour and a half; the press conference dragged from two hours to three hours; it set a year-end goal to build 20,000 flash charge stations domestically, with capital expenditure in the billions, and changed flash charge stations to integrated storage and charging solutions with built-in storage cabinets, bypassing the trouble of applying to the grid for capacity expansion, deploying on three parking spots.
From year-end, these piles will start spreading overseas; the MW-level network in Europe has already been demonstrated at the Munich Auto Show.
Building charging piles in target markets is the latest chapter in BYD's overseas line, possibly the most money-burning chapter. BYD bets that once the charging network is laid out, the transitional form matters less. Others keep hybrids; BYD chooses not to bet on multiple fields, pressing all chips on this New Energy transition round.
Put these together, it is a consistent logic: growth is punched out section by section from factories, technology, and charging piles.
BYD is almost the only domestic automaker highly controlling everything from supply chain vertical integration to overseas assets. This heavy asset model makes scale a must-do; in this dimension, sales "No. 1" is just a byproduct.
Vertical integration is only worth it when spread to world-class scale; maintaining a fleet requires enough exports to fill it; building cell capacity at that level requires enough whole vehicles to digest it; investing billions to lay 20,000 charging piles requires enough installed base to feed it.
Chery can stop at export champion; Geely can be a large enough multi-brand group; if BYD's scale is not larger than them, the efficiency of this setup cannot be guaranteed.
This gives BYD the possibility to challenge for Global No. 1, and makes it very hard to accept a "not big enough" result.

This article is original content of Auto Pixel (autopix)
Unauthorized reproduction is prohibited