首頁Tires

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
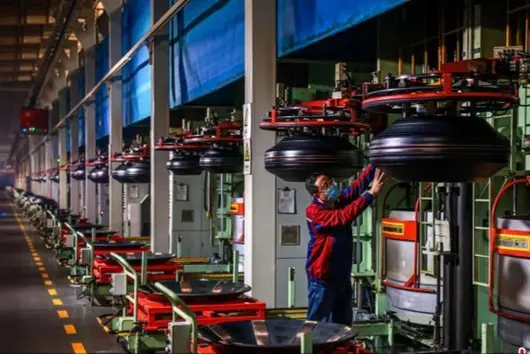
On October 19, the European Commission issued pre-disclosure on final countervailing duties regarding Chinese passenger car and light truck tires. Combined with previous anti-dumping tariffs, the comprehensive "dual anti-dumping" tax rate for Chinese tire exports to the EU ranged from a high of 57.09% to a low of 27.50%, while companies cooperating with both investigations faced a rate of 28.76%. The final countervailing duty ruling is expected to be released on December 5, leaving enterprises with only a month and a half window for adjustment.

Tariff Rate Split: Gap Between Responding and Non-Responding Nearly 30 Percentage Points
According to the disclosure, Linglong Group's combined dual anti-dumping rate totals 57.09%, Hankook Tire Group 28.76%, while non-cooperating enterprises are subject to the highest rate. The good news is, this ruling will not be applied retroactively, so goods already shipped are relatively safe. The China Rubber Industry Association has requested enterprises to submit comments before October 29 and has applied for a hearing on behalf of Chinese responding enterprises.

The European market is crucial for tire companies: In 2024, EU PCR tire consumption was about 330 million pieces, with a market size exceeding 18 billion euros, and China's import volume accounts for a 28% share — for every four passenger car tires in Europe, one comes from China. Once the 57% tariff rate is implemented, the price advantage of mid-to-low-end products will be greatly compressed.

Exports Plummeted 46.5%, But Orders Didn't Leave, Production Origins Changed
Pressure has already shown in the data: From January to August, Chinese exports of light passenger car tires to the EU reached 333,500 tons, down 46.5% year-on-year, with the EU dropping from the largest export region to third. However, the total export volume did not collapse; exports of light passenger car tires in August were 285,100 tons, up 3.84% month-on-month.
More importantly, "Chinese tires" have not truly left. The Astutus Research report shows that China's semi-steel radial tire share in the EU 27 countries plus the UK dropped from 71.8% to 58.1%, but during the same period, ASEAN share rose from 7.6% to 19.9% — Thailand's exports to Europe rose from about 2 million to 6 million pieces, Vietnam grew 130%, Cambodia rose from nearly zero to 2.3 million pieces, and new sources mostly come from overseas factories of Chinese tire companies.

Orders didn't leave, production origins changed. Goods shipped directly from domestic factories were blocked by high tariffs, while Southeast Asian factories entered the EU with local manufacturing status, circumventing dual anti-dumping taxes. Sailun's capacity in Vietnam and Cambodia, and Linglong's base in Thailand, are all taking on such orders.

Tariffs Cannot Block "Chinese Brands"
The EU is not an isolated case: The US Section 201 petition and Canada's dual anti-dumping investigation on Chinese truck and bus tires are also advancing concurrently. Ironically, EU tariffs are personally driving Chinese tire globalization layout — from Southeast Asia to North Africa, China's tire capacity map is larger than ever. But the cost is equally real: The average price to Saudi Arabia was only $2,198/ton, $3,798 to Japan, and enterprises are under pressure on both ends.
As Yuan Zhongxue, honorary chairman of Sailun Group, stated, Chinese tires are at the turning point of moving from "getting bigger" to "getting stronger". Going overseas is not just about capacity going out, but also about brands going up. Every dual anti-dumping investigation is an industry reshuffle — those who survive are not necessarily the largest, but must be the ones adjusting fastest.
Recently, PowerChina Sichuan Engineering Co., Ltd. announced that it successfully won the bid for the Phase II civil engineering project of Sailun Egypt factory, marking that the Phase II project of this large-scale tire manufacturing base located in the Suez Canal Economic Zone has officially entered the implementation stage, adding new achievements for Chinese enterprises participating in the "Belt and Road" overseas industrial infrastructure.

Core Workshop Construction Starts First
According to bid information, the construction scope this time includes the heavy-duty tire mixing workshop and raw material warehouse civil engineering. Construction content covers earthwork excavation, foundation treatment, equipment foundation, and upper main structure construction.
The heavy-duty tire mixing workshop is a core process workshop for tire manufacturing, with strict technical standards for foundation settlement control and structural construction accuracy, directly testing the industrial workshop construction level and overseas project comprehensive performance capability of the construction unit. PowerChina Sichuan Engineering stated that the project team will strictly adhere to safety control, strictly control engineering quality, and make every effort to guarantee high-quality project performance.
It is worth mentioning that this company is a long-term strategic partner of Sailun Group, and has previously cooperated to build projects such as Phase I and II thermal power plants in Cambodia, Phase III mixing workshop in Cambodia, etc.

Total Investment for Three Phases 11.5 Billion Yuan
Sailun Egypt factory is located in the Teda Industrial Park in Suez Governorate, Egypt, with a total investment of approximately 1.717 billion US dollars (approximately 11.5 billion RMB), promoted in three phases:
Phase I: Investment 291 million US dollars, planned annual production of 3.6 million radial tires;
Phase II: Investment 285.43 million US dollars, planned annual production of 7.05 million radial tires (6 million passenger car tires + 1.05 million heavy-duty tires), construction period 18 months;
Phase III: Investment 1.141 billion US dollars, planned annual production of 27 million passenger car tires, 1.65 million heavy-duty tires, and 20,000 tons of off-road tires.
After Phase III is fully completed, Sailun Egypt base will form a comprehensive capacity of 36 million passenger car tires, 3.3 million heavy-duty tires, and 20,000 tons of off-road tires annually, becoming the largest tire production base locally in Egypt.

Another Move in Global Capacity Matrix
From a locational perspective, Egypt is at the intersection of Europe, Asia, and Africa. Relying on the Suez Canal, a global shipping hub, it can radiate to European, African, and Middle Eastern markets nearby. This base coordinates with Sailun Vietnam, Cambodia, Mexico, and Indonesia factories, jointly building a global tire capacity layout.
As the Chinese tire enterprise with the largest overseas production capacity, Sailun's global layout effectiveness has been reflected in performance. In the first half of 2026, the company achieved operating revenue of 20.027 billion RMB, up 13.88% year-on-year; net profit attributable to parent company of 2.160 billion RMB, up 17.97% year-on-year; overseas market revenue 15.242 billion RMB, accounting for about 76% of main business revenue.
With the full launch of Egypt Phase II project, Sailun's "close to end markets, multi-base coordination" global industrial layout will be further solidified, providing a new model for Chinese tire industry chains to "go global."
Recently, the Internal Market Protection Department of the Eurasian Economic Commission released Announcement No. 2026/514/AD44, disclosing the final results of the anti-dumping investigation on new pneumatic rubber tires originating from Thailand and Vietnam, recommending the imposition of anti-dumping duties on the products concerned for a period of five years, with tax rates ranging from 11.31% to 22.37%.

This investigation involves new pneumatic rubber tires used on trucks, buses, trailers, etc., with rim diameters ranging from 17.5 to 24.5 inches, with tariff codes 4011201000 and 4011209000. It is worth noting that several Chinese-owned tire enterprises with factories in Thailand and Vietnam also appear on the proposed tax list.
Highest Tax Rate 22.37%, Many Chinese Enterprises Affected
Based on the disclosed proposed tax rates, the applicable rates for Thai and Vietnamese enterprises differ.
Regarding Thailand, the recommended tax rate for listed companies such as Prinx Chengshan Thailand, LLIT (Thailand) under Linglong, and Maxxis Thailand is 17.05%, while other Thai producers or exporters are 22.37%.

Regarding Vietnam, the recommended tax rate for Jinyu Vietnam is 11.31%; Sailun Vietnam and ACTR are 16.48%; Triangle Tyres is 17.25%; COFO Vietnam, Dacang Rubber, and Wuhua Vietnam are 14.99%, while other Vietnamese producers or exporters are 17.25%.
This means that when relevant enterprises export the concerned heavy-duty tires to the Eurasian Economic Union in the future, they may need to recalculate product costs, export quotes, and profit margins.
Taking a product worth 1 million USD as an example, if an anti-dumping tax of 17.05% applies, the corresponding tax amount is 170,500 USD; if a tax rate of 22.37% applies, the tax amount reaches 223,700 USD.

For heavy-duty tire enterprises with limited profit margins relying on price competition to win orders, such additional costs cannot be ignored.
It needs to be emphasized that the currently public information belongs to the final ruling disclosure and proposes tax collection suggestions, which cannot be directly equated to the relevant tax rates having officially taken effect. Specific effective dates and implementation methods still need to follow up on subsequent formal decisions.
Thailand and Vietnam Are No Longer Natural Trade Safe Havens
In the past few years, facing trade barriers from markets such as Europe and America, some Chinese tire enterprises accelerated capacity layout in Southeast Asia, hoping to reduce logistics costs, get closer to customers, and diversify trade risks of a single market through overseas production. Thailand and Vietnam have thus become important regions for the global layout of Chinese tire enterprises.
But this investigation shows that trade remedy measures are gradually extending from solely targeting products originating from China to similar products in other countries or regions.
Southeast Asian production bases are not natural trade safe havens, enterprises cannot judge market access risks solely based on factory location.

In the future, anti-dumping investigations may pay more attention to product origin, production process, cost structure, and affiliation between enterprises.
Overseas factories must have real, compliant, and verifiable production and business activities, cannot treat simple transshipment or nominal changes in place of origin as a way to evade trade barriers.
For Chinese tire enterprises, the decision logic for building factories overseas needs further upgrading, shifting from mainly considering labor, land, transportation, and raw material costs to simultaneously evaluating target market policies, rules of origin, and long-term trade risks.
What Should Chinese Tire Enterprises Do Next
Facing changes in trade barriers, Chinese tire enterprises need to do several things well.
First, establish a regular trade policy tracking mechanism. Focus on the Eurasian Economic Union's subsequent formal decisions, rules of origin determination, and progress on China's heavy-duty tire anti-dumping measures, timely verify applicable tax rates for different factories, products, and customers, do not arrange exports solely based on industry rumors.

Second, re-evaluate overseas investment and capacity layout. Production bases such as Thailand and Vietnam still have industrial support and logistics advantages, but enterprises need to consider tariff risks, market capacity, local operating costs, and supply chain stability together. The value of overseas factories will ultimately be determined by real production capacity and comprehensive operating income.
Third, increase product value-added and cost management capabilities. By improving product quality, developing high-performance heavy-duty tires, strengthening brand building, and optimizing procurement systems, reduce reliance on low-price competition. At the same time, fully consider possible tariff changes in quotes and sales contracts, reasonably agree on price adjustment and risk sharing mechanisms.
Fourth, strengthen industry synergy and compliance response. Relevant enterprises should prepare production records, cost data, export documents, and certificates of origin in a timely manner, express opinions through legal and industry channels within the scope allowed by the investigation procedures, protect their legitimate rights and interests.

Overall, this anti-dumping investigation on Thai and Vietnamese heavy-duty tires does not mean that Chinese tire overseas expansion loses its significance, but reminds enterprises that the rules of global competition are changing.
Building overseas factories is just the first step. True global capability is that regardless of where a company produces, it can accurately judge trade risks, control comprehensive costs, and continuously provide competitive products for the target market.
Thirteen-year overseas journey, 17 overseas plants, 282 million annual capacity -- the globalization expedition of Chinese tires is arriving at the golden moment for profit realization.
As of October 2026, seven leading enterprises: Zhongce, Sailun, Linglong, Sincere, Triangle, Aeolus, and Double Star, have deployed 17 plants across four continents, with total overseas capacity of approximately 282 million tires/year, equivalent to 38% of total domestic capacity. Moving from the factory construction phase to the profit phase, the globalization of Chinese tires has entered a new stage.


Layout Map: Four Continents Strategically Deployed
Sailun leads with 5 locations: Vietnam (launched in 2013, the first overseas greenfield factory in the Chinese tire industry), Cambodia, Indonesia, Mexico (four already in production), Egypt (under construction). Zhongce owns 4 bases; Thailand's 15 million passenger car tires + 4 million all-steel tire capacity is continuously expanding; Indonesia, Vietnam, Mexico are advancing in steps. Linglong has a trinity of Thailand, Serbia, and Egypt; Serbia is the first Chinese-funded greenfield tire factory in Europe. Sincere deepens in Thailand and locates in Morocco; Morocco Phase I took only 11 months from start to first tire production. Triangle, Aeolus, and Double Star each hold a city: Triangle bets on Cambodia; Aeolus deepens in Egypt engineering tires; Double Star achieves cross-level upgrade via Cambodia Factory + Kumho Global Brand.

Profit Realization: Overseas Factories Become Growth Engine
Financial reports from H1 2026 show concentrated release of overseas base profitability:
Sailun Cambodia became an industry benchmark -- half-year revenue 4.405 billion yuan, net profit margin as high as 21.6%, net profit increased by about 101% YoY. Under its drive, Cambodia tire export value Jan-Aug exceeded 1.497 billion USD, surging 72.14% YoY, products sold to US, Brazil, Europe and other global markets.
Sailun Vietnam's 2024 single-plant revenue reached 8.644 billion yuan, first-mover advantage continuously consolidated; Zhongce Thailand's 2025 net profit 1.014 billion yuan, accounting for 24.5% of company's attributable net profit, a stable profit ballast; Sincere Morocco turned losses to profit in H1, secured Renault and Stellantis global supplier qualifications, joined European high-end OEM supply chain; Linglong Serbia passed Volkswagen, Audi, BMW audits and obtained Ford Q1 certification, European localization strategic value highlighted.

Strategic Upgrade: From Single-point Factory Building to Full-Chain Globalization
Unlike the first round of globalization, the biggest highlight of this round is Chain Globalization: Egypt has attracted 5 tire plants to cluster investment, driving upstream and downstream collaboration including Zhongtian Steel (steel cord), Link Technology (carbon black), Hoyma Group (molds), forming a complete cluster of Tire + Material + Equipment; Morocco leverages zero tariff advantage facing EU, gathering high-end capacity like Sincere, Guizhou Tire. Egypt focuses on scale and clusters, Morocco focuses on high-end and market access, Chinese tire global supply chain system is improving.
Facing trade variables like EU anti-dumping duties, multi-base layout shows strong resilience: Sailun 5-point support, Zhongce 4-country coordination, diluting policy risks into manageable costs; OEM supply continues to break through, Zhongce entered AITO M6 and Maextro S800 supply systems, order structure upgraded towards high value-added.

Conclusion: Second Half Competes on Profit Speed
In thirteen years, Chinese tires completed the leap from product globalization to industry globalization. Industry consensus is clear: Tariffs decide where to ship from, Net profit margin decides whether it's viable. The second half of going overseas compares not on factory construction speed, but on the speed of converting capacity into profit.
Capacity has gone overseas, profits are catching up. In this major globalization exam, Chinese tires are turning in an increasingly impressive answer sheet.
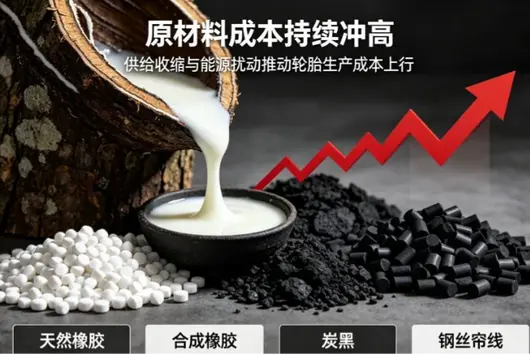
Wave after wave of raw material price hikes are pushing the tire industry to high cost levels. Carbon black hits a 6-year high, natural rubber returns to the 20,000 yuan threshold for the first time in 9 years—the price hike spreads from factories to distributors, from domestic markets to the global stage. On October 8, CCTV Business News focused on the collective price hike by over 60 tire enterprises in China. According to statistics, since September, over 60 tire enterprises have collectively issued 114 price hike letters, covering all categories of all-steel tires, semi-steel tires, and engineering tires, with adjustment amplitudes generally between 2%-5%.

Raw Material "Double High": Carbon Black Rises, Natural Rubber Takes Over
Carbon black is the first link to be ignited. On October 1, the carbon black benchmark price was quoted at 11,692.86 yuan/ton, a year-on-year increase of about 59.74%, still at the highest level in 6 years; in September, the entire carbon black industry is expected to incur losses exceeding 120 million yuan, and Cabot has already announced a special carbon black price increase of 5,800 yuan per ton.
Natural rubber followed closely. On October 9, the Shanghai rubber main contract closed at 20,645 yuan/ton, setting a new high in nearly 9 years; the average spot price of natural rubber increased by 31% year-on-year.
Supply contraction is the main cause: floods in eastern Thailand affected about 23,000 hectares of rubber plantations, compounded by the 6-8 years required for rubber trees to start tapping, and the increased proportion of aging trees in main producing areas, resulting in severe lack of supply elasticity.

Over 100 Price Hike Letters Issued, Full Chain Transmission
In September alone, over 100 price hike letters were issued, becoming the densest price hike month in history. The pace of price increases accelerated significantly: mainstream in September was about 3%, generally jumping to 6% in October. During the National Day holiday, over 20 enterprises continued to issue letters, 9 of which were for a second price hike.
New changes appeared in the channel end: distributors such as Jilin Lunda and Shandong Zhenghe'an followed the price hike actively for the first time, changing the price hike from one-way transmission by manufacturers to full-chain transmission; Wanda Baotong, Guizhou Tire and other enterprises refused prepayment price locking, cutting off the distributor's price locking path. The price hike also spread globally; Hankook, Bridgestone, and Yokohama successively raised prices; Goodyear and Nexen followed suit in the Chinese market.

Cost-Selling Price Scissors Gap, Enterprises Take Multiple Measures for Self-Rescue
Enterprise comprehensive cost increases have exceeded 20%, while price hike letter amplitudes are generally only 3%-5%, the difference is fully digested by the manufacturing end, many products "produce one order, lose one order". The factory response is to reduce production in advance: by the end of September, the capacity utilization rate of semi-steel tires and all-steel tires dropped to 52.60% and 48.68% respectively.
More enterprises are turning to diversified strategies: changing from production scheduling based on quarterly total to production scheduling based on orders; locking raw material costs through futures hedging; increasing R&D to launch tires compatible with new energy vehicles, focusing on the high-end matching market to hedge cost pressure.

"Involution" Attracts Attention, Industry Reshuffling Will Accelerate
Behind the price hike wave is the industry's dilemma of "increasing revenue without increasing profits". According to statistics from the China Rubber Industry Association, industry output value grew by 5.48% year-on-year from January to August, while total profit fell by 10.84%. Low-price vicious competition has already attracted high-level attention, and the meeting of the Central Finance and Economics Committee clearly proposed to "govern enterprise low-price disorderly competition according to laws and regulations".
Association President Xu Wenying pointed out that structural imbalance, blocked exports, "winning bids solely on low price", etc., are the roots of involution, urging enterprises to break through with differentiation and branding, and the industry to shift from "competing on price" to "competing on quality and innovation".
Industry insiders expect, high costs may last through the fourth quarter, small and medium enterprises will accelerate capacity clearance, and industry concentration is expected to rise in the reshuffling. The most pressure is still on those small and medium tire enterprises that have neither overseas capacity nor bargaining power.
On October 8, Qingdao Sentury Tire Co., Ltd. (002984.SZ) issued an announcement to partner with top Turkish tire distribution enterprise TATKO Group, investing $272.82 million (equivalent to 1.824 billion RMB) to build a high-performance passenger and light truck radial tire project with an annual output of 7 million tires. This is Sentury's third overseas intelligent manufacturing base after Thailand and Morocco, and the first Chinese tire enterprise to officially launch operations in Turkey, adding a critical move to its "833Plus" global strategy.

Stable Accounts, Promising Returns
The project is held 90.1% by Sentury and its wholly-owned subsidiary (approx. $246 million), with TATKO holding 9.9% (approx. $27.01 million). Funded entirely by internal resources, the low debt structure ensures controllable financial risk. Construction period is 18 months. After reaching full capacity, normal operations are expected to generate annual revenue of $204.62 million, net profit of $42.11 million, with a net profit margin reaching 20.58%. The break-even point is only 39.75% — operating at 40% capacity is enough to break even. Combined with Turkey's 2025 new investment incentive policy (equipment imports qualify for duty and VAT exemptions, 60% income tax reduction), actual returns still have room for upward revision.
Especially notable are the efficiency indicators: For a factory producing 7 million tires annually, total workforce is only about 400 people, meaning 17,500 tires per person annually. Intelligent central control, production execution, warehousing logistics, inspection scanning, and dispatch warning systems run through the entire process — this intelligent manufacturing template, validated twice in Thailand and Morocco, will be fully transferred to Turkey this time.

A "Zero-Tariff Ticket" to Enter the EU
The consideration of selecting Turkey strikes at industry pain points. In July this year, the EU's anti-dumping final ruling on Chinese passenger and light truck tires took effect, with tax rates ranging from 4.3% to 45.3%, Sentury subject to a 24.4% rate. Chinese tire exports to Europe saw a significant decline. However, according to the EU-Turkey Industrial Goods Customs Union, industrial manufactured goods taxed in Turkey can be exempt from tariffs and enter the EU directly with an A.TR certificate. Interestingly, the surrogate country used for EU anti-dumping calculations is exactly Turkey — producing in Turkey equals exchanging domestic manufacturing status for EU market access.
At the same time, Turkey is a major European complete vehicle base: 2025 car production is about 1.42 million units, export rate about 74.5%, with automakers such as Ford, Toyota, Hyundai, Renault gathered. Chery and BYD have also announced building factories. There are about 1,100 parts supporting enterprises. The new factory can achieve a closed loop for both original equipment and replacement tire markets.

9.9% Equity, Nationwide Shelves Secured
Partner TATKO was founded in 1927, is one of Turkey's largest independent multi-brand tire distributors, network covers 81 provinces nationwide, 850 sales points, and holds cross-border export channels facing the Balkans and Central Asia. Products can reach target markets directly via its distribution system from the day they leave the line. The cold start problem of "who to sell production capacity to" is readily resolved.

Tripod Stance, Global Synergy
With the Turkey base landing, Sentury will form a pattern where Thailand serves North America and Asia-Pacific, Morocco radiates Europe and Africa, and Turkey connects the EU and Central Asia, effectively dispersing trade policy risks. Referencing Morocco base's trajectory of turning profit within two years of production and obtaining Renault and Stellantis supplier qualifications, the Turkey project outlook is promising.
From Thailand to Morocco to Turkey, Sentury uses the strategy of "holding control + equity for channels + location positioning" to write another benchmark sample for Chinese tires moving from "product going overseas" to "overseas manufacturing + local service".
During the National Day holiday, the tire industry didn't take a break, and neither did price hike notices — more than 20 companies issued price hike notices collectively during the holiday period, with 9 of them being short-term second adjustments. Previously, single-month price hike notices in September exceeded 100, involving over 80 companies, making it the most intensive price hike month in history.
Carbon Black Ignites, Natural Rubber Takes Over
Carbon Black raised prices first. According to data from Business China, on October 1st, the benchmark price for carbon black was reported at 11,692.86 yuan/ton, a year-on-year increase of approximately 59.74%, reaching a 6-year high; in September, the entire carbon black industry is expected to incur losses exceeding 120 million yuan. Natural Rubber followed closely: On September 30th, the main Shanghai Rubber contract closed at 20,095 yuan/ton, rising 5.54% in a single day, marking the first time since March 2017 that it crossed the 20,000 yuan threshold, setting a 9-year high.
Supply contraction is the main cause. The direct trigger was the flooding in Thailand — at the end of September, approximately 23,000 hectares of rubber plantations in four eastern provinces of Thailand were affected. Deeper down, it is insufficient supply elasticity: Rubber trees take 6 to 8 years to start tapping, the previous low-price cycle suppressed replanting, and the proportion of aging trees in major producing areas continues to rise.

One Notice Letter Covers Two Price Hikes
This round of price adjustments covers mainstream categories such as truck and bus tires, passenger car tires, and engineering tires, with mainstream increases of 2%—5%, and some specifications reaching up to 6%. Well-known brands such as Triangle, Double Coin, Linglong, and General Shares are all listed. It is worth noting that Zhongce Rubber increased its all-steel tire products by 2%—5% on September 16, and then increased by another 3%—5% on October 1st — one notification letter scheduled for two price hikes, showing that enterprises' judgment on raw materials has shifted from "short-term fluctuations" to "long-term highs".


New changes also appeared on the distribution channels: Distributors such as Jilin Lundah and Shandong Zhenghean actively issued letters to adjust prices, and the price hike first became a full-chain transmission; Wanda Baotong, General Shares, Guizhou Tire, etc. clearly stated they do not accept prepayment locking prices. Jiangsu Hu'an's price hike notice plainly stated: "Tire prices will not only gradually rise, but there will also be shortages." The price hike has also spread globally, with Hankook, Bridgestone, and Yokohama adjusting prices successively, and Goodyear and Nexen following up for the Chinese market in late October.

Losing 80 Yuan per Tire Sold, Factories Reduce Production in Advance
The scissors difference between cost and selling price best illustrates the problem: according to Chuo Chuang Information, the production cost for a single all-steel tire in August was approximately 989.44 yuan, while the market selling price was only 908.66 yuan — losing 80 yuan per tire sold. The comprehensive cost increase has exceeded 20%, while price hike notices are generally only 3%—5%, with the difference entirely absorbed by the manufacturing end. The factory response was to reduce production in advance: In the week at the end of September, the capacity utilization rate for semi-steel tires decreased by 10.44 percentage points month-on-month, and all-steel tires decreased by 9.79 percentage points.

Turning Point Not Yet Seen, Industry Shakeout Accelerates
Flooding in Thailand continues, and crude oil remains at a high level; high costs may prevail throughout the fourth quarter. Industry insiders point out that raw materials rising but not falling will accelerate the capacity clearance of small and medium-sized enterprises, and industry concentration is expected to rise during the shakeout — the biggest pressure is on small and medium-sized tire companies that have neither overseas capacity nor bargaining power.
The end of this price hike depends on the turning points for oil and rubber. But as for the turning point, it has not appeared yet.
Recently, Wanli Tire's overseas expansion strategy has achieved substantial progress. According to reports, Wanli Tire plans to invest approximately 1.37 billion Ringgit (equivalent to about 2.273 billion RMB) in Selangor State, Malaysia, to establish "Wanli Tire (Malaysia) Co., Ltd." and build its second overseas factory. This move marks Wanli Tire advancing on two fronts simultaneously through "overseas capacity expansion + domestic capital operations," comprehensively accelerating its global layout.

Total Investment 2.27 Billion, Planned Capacity of 6.2 Million Units
The new factory will be located in Ulu Selangor District, Selangor State, with a planned annual capacity totaling 6.2 million tires, covering 5 million passenger car radial tires and 1.2 million truck radial tires. The project is not merely a capacity output but focuses more on technology transfer and talent localization. It is expected to create 1,350 job positions locally, covering high-skill positions such as engineers, quality control experts, and management personnel.
Selangor State Executive Councilor Huang Sihan stated that Wanli Tire's final choice of Selangor after evaluating the entire Southeast Asia region proves the locality's international competitiveness in industrial ecology, logistics, and policy stability. As a natural rubber production base, Malaysia's implementation of Wanli Tire has achieved localization in three links: resources, production, and export, keeping the industrial added value locally.

IPO Application Accepted, Fundraising to Support Globalization Layout
Wanli Tire's factory construction plan aligns closely with its recent capital operations. On June 23, Wanli Tire's IPO application for the Shenzhen Stock Exchange Main Board was formally accepted, with a proposed fundraising of 2 billion RMB. The prospectus shows that the raised funds will be invested in five major projects, with the Malaysia production base being a crucial part of them. Other projects also include a new Cambodia project, expansion of the Conghua base, and upgrade of the R&D center, etc.
With the intensification of domestic market competition and the complexification of the international trade environment, Chinese enterprises going overseas to build factories has become a trend. Wanli Tire takes Malaysia as a new overseas pivot, combined with the progress of the Cambodia project, aiming to optimize the global capacity layout. Introducing capital market liquidity through IPO will provide solid financial security for its vast overseas expansion plan.

Empowering Local Industrial Chains, Going Overseas Towards High-Quality Development
Wanli Tire's Malaysia project not only focuses on capacity expansion but also emphasizes quality improvement and efficiency enhancement. It is reported that the new factory will adopt intelligent production lines, significantly improving production efficiency and achieving full-process environmental monitoring, aligning with Malaysia's "Green Industry 4.0" strategy. Meanwhile, the establishment of an international-level manufacturer also means significant technology transfer, and the skills mastered by local employees will remain in Malaysia.
With the in-depth layout of Chinese enterprises such as Wanli Tire, Selangor State is expected to become an important industrial hub for automotive parts in Southeast Asia. Wanli Tire taking Malaysia as a new overseas pivot, combined with the progress of the Cambodia project, not only optimizes the global capacity layout and effectively avoids trade barriers but also injects new momentum into the Chinese tire industry in international supply chain cooperation.
Recently, the Qingdao Eco-Environment Bureau approved the aircraft tire project of Gubo (Shandong) Aviation Technology Co., Ltd.

Next to it is Sailun Group's annual production project of 12.6 million sets of high-performance radial tires, with a total investment of 2.342 billion yuan. The EIA was approved in April 2026, planned for production at the end of this year.
These two projects stand side by side on the same road, exactly marking the clearest dividing line in Qingdao's tire industry in recent years: the production capacity of industry leaders is moving overseas, and the spots freed up locally are being taken up by a batch of SMEs.
The production capacity of industry leaders has moved overseas in recent years
The capacity increase of these listed companies in Qingdao is mainly overseas. This is not a new move, but the proportion and intensity in the past two years have increased by a level.
In Sentinel's layout in three locations, Thailand and Morocco bear the main increase. In the first half of 2026, overseas revenue accounted for nearly 93%, and the net profit of the Thailand factory was about 411 million yuan, comparable to the net profit attributable to shareholders of the listed company of 420 million yuan — in other words, its current profit is almost contributed by overseas production capacity.

Sailun's overseas bases are more spread out, with projects in Mexico, Indonesia, and Egypt succeeding one after another in addition to Vietnam and Cambodia.
Double Star took another route, completing the acquisition of 45% equity in Kumho Tire at the end of March 2026, gaining control, and obtained ready-made overseas production capacity and channels through a capital operation.
The reason for moving production capacity overseas is not complicated: to cope with trade barriers, get closer to overseas customers, and utilize local raw materials and labor costs. But for Qingdao, the direct result is that local production no longer needs to bear scale increases.
What stays in Qingdao are high-end production lines and R&D platforms
The projects of industry leaders remaining locally are not large in quantity, but the positions are very high. Inside Sailun's Dongjiakou 12.6 million set project plant area, a functional new material project with an annual output of 500,000 tons is being built synchronously.
Sentinel's aircraft tire expansion and renovation project in Jimo has a total investment of 277 million yuan, without adding new land. It will add 4 million sets of high-performance semi-steel tires and restart the 50,000 set aircraft tire retread production line that has been stopped for five years.

The next level up is R&D. The National Rubber and Tire Engineering Technology Research Center, jointly built by Qingdao University of Science and Technology, Soft Control, and Sailun, plans to be put into use in Shibei District in 2027, with an R&D team size of more than 3,000 people.
Policy is also pushing in the same direction. The work plan for stable growth in the petrochemical and chemical industry issued by Qingdao in March 2026 lists new-generation high-performance radial tires, aircraft tires, new energy vehicle tires, and giant engineering radial tires as support directions; among the 600 municipal key projects in the city in 2026, 6 tire-related projects have a total investment of over 7 billion yuan, some of which are R&D platforms and research centers.
These investments remaining locally yield technology, equipment, and people, not production volume. The positions freed up by production volume are filled by others.
The list of new local projects has changed names
Listing the tire projects newly started in Qingdao in 2026, the investment subjects are almost all SMEs. Gubo's investor Qingdao Guobo Tire was established in 2013, and at the end of 2024, the registered capital was just increased from 10 million yuan to 50 million yuan.
Maishijia in Mingcun Town, Pingdu, invested 3 billion yuan, planning an annual tire production of over 11 million sets, with new energy passenger tires accounting for 90%. The company was also established in 2024.
In the same area, Aonuo Tire's semi-steel tire expansion project has a total plan of 1.074 billion yuan, divided into three phases; Qizhou Rubber invests 715 million yuan, Wangyu Rubber invests 567 million yuan, and both make high-end off-road tires.

Honghua Rubber Factory invested 220 million yuan to add 160,000 sets of all-steel engineering tires, while reducing bias tire capacity from 2.6 million to 1.42 million sets. At the same time, three motorcycle tire projects were launched in Huangdao District, among which Runing Industry invested 150 million yuan.
The single investment of this batch of projects is mostly in the hundreds of millions of yuan level, not on the same scale as industry leaders' projects of hundreds of millions or billions, and the categories made do not overlap.
This batch of projects makes another type of tire
The common point of the above projects is not touching ordinary tires; they make aircraft tires, ground special tires, off-road tires, engineering tires, agricultural radial tires, and motorcycle tires.
This choice has its reason: ordinary passenger tires and truck/bus tires rely on scale. A production line investment goes down to hundreds of millions, SMEs simply cannot enter; aircraft tires, engineering tires, these categories have small volume, but high certification barriers and thick gross margins, as long as qualifications are obtained, they can stand.

Pingdu is the farthest on this road. Among 27 tire enterprises in the city, 23 are in Mingcun Town. The output value in 2024 was 3.46 billion yuan, and bias tire capacity once accounted for nearly half of the province.
Therefore, the division of labor is already laid out: industry leaders' production capacity continues to move outward, locals keep technology, equipment, and high-end production lines, while SMEs fill in those categories with small volume and high barriers.
Whether this path holds depends on three things — whether certification and channels for specific categories can be built, whether upstream and downstream supporting can be completed, and the capacity utilization rate after new projects are put into production.
The shortcomings listed by Pingdu itself are also very clear: there are only 2 enterprises with output value over 500 million yuan, the industrial chain is not complete, and the conversion rate of scientific research achievements is not high. The local goal is to break through 5.5 billion yuan in the total output value of the tire industry by 2027. Placing this number next to Sailun's 20.027 billion yuan revenue in the first half alone, one can see the actual scale of this new pattern.
September 16, Thai authorities jointly carried out law enforcement and dismantled a large cross-border money laundering network hidden in Samut Sakhon Province. The "Tire Empire" involving assets worth 600 million Baht collapsed, and behind it was a corruption suspect wanted by China who had been on the run for 13 years. This case not only shocked the industry but also sent a strong signal that Thailand is implementing piercing scrutiny on foreign investment "nominee holding".

"Disguise" Hiding and Puppet Shareholders
Thai police announced that the core suspect is 37-year-old Chinese national Li. He fled China in 2013, illegally obtained a Myanmar passport in 2018, and lived under an alias in Thailand for over 10 years. During this period, Li set up 3 companies with a total registered capital of 191 million Baht, owning 7 land plots under its umbrella, with total assets of about 600 million Baht.

These assets were actually carried by a company engaged in tire manufacturing, with products sold not only in Thailand but also exported overseas. To avoid Thailand's "Alien Business Act", Li meticulously designed the equity structure. The foreign shareholding of the 3 tire-related companies was superficially below the 49% red line, but police piercing cross-shareholding found that 100% actual control belonged to foreigners. Astonishingly, the shareholders registered as Thai were several local taxi drivers—they were formerly Li's employees and, without actual capital contribution, became "nominee puppets" for the foreign-controlled tire factory.

Buying and Selling Identities and Asset Transfers
Apart from corporate structure fabrication, Li's money laundering network also extended to identity trading. In the investigation, Li attempted to transfer massive assets to his 19-year-old son. The man held a Chiang Mai birth certificate and Thai ID card, but DNA tests confirmed that his registered Thai parents were imposters. Behind this lay black market transactions: agents used the identity of a 5-year-old deceased son of a Thai woman whose household registration was not cancelled, issuing a Thai ID card to this Chinese child for only 500 Baht. Police suspect this move was paving the way for future transfer and holding of illegal assets such as tire factories.


Currently, the Thai Anti-Money Laundering Office (AMLO) has fully intervened. If it is confirmed that Chinese corruption proceeds were transferred to Thailand for investment and factory setup, Thai authorities will freeze and seize in accordance with the law and may initiate cross-border recovery procedures through judicial channels.

Regulatory Upgrade: The Storm of Piercing Verification
This shocking case sounded an alarm for foreign enterprises in Thailand. Industry analysis points out that this case marks a fundamental shift in Thailand's regulatory model: from previously only looking at "superficial compliance of company registration documents" to "piercing verification of actual controllers, fund sources, and shareholders' true identities".

For legitimate Chinese-funded enterprises, "Thai shareholder ratio superficially meeting standards" is no longer a shield. If Thai shareholders are merely employees with no actual capital contribution and economic rights, enterprises still face extremely high risks of illegal nominee holding. Industry calls urge Chinese merchants in Thailand, especially in restricted industries such as manufacturing and real estate, to immediately launch special legal reviews, checking shareholder actual capital contribution flows, Ultimate Beneficial Owners (UBO), and directors' actual control rights to cope with Thailand's gradually tightening piercing regulation.
September 14 evening, Lianke Technology (001207) issued two announcements consecutively: The company plans to invest approximately 1 billion yuan in Egypt's Suez Canal Economic Zone to build the "Silica-Carbon Black Circular Economy Integrated Project"; it will also redirect the approximately 236 million yuan of unused funds from the original fundraising project to this new overseas project, outlining a strategic picture of accelerating globalization and moving towards high-end from both domestic and foreign perspectives.

Follow Tire Customers, Seize the North African Opportunity
According to the announcement, Lianke Technology will establish a platform company through its wholly-owned subsidiary in Singapore, and then jointly invest to register the project implementation entity in Egypt. The new base is located in Suhna Industrial Zone, and after completion, it will form a capacity of 100,000 tons/year of silica and 100,000 tons/year of carbon black, with a construction cycle of approximately 18 months.
This move is timely. China's tire leaders are accelerating layout in North Africa: Sailun Tire invests over 1.1 billion USD in Egypt, Linglong Group plans to invest about 2 billion USD, Zhongce Rubber, Langma, Fengshen successively invest in Egypt, Guizhou Tire, Senqilin etc. layout in Morocco, upstream Zhongtian Steel also builds steel cord project locally. Lianke Technology's products have long been certified by Linglong, Sailun, Goodyear, Triangle, etc. - customers' capacity expansion will directly translate into strong supporting demand. Setting up factories locally not only shortens delivery cycles and reduces logistics and tariff costs, but also leverages Egypt's advantage of being adjacent to Europe and having a free trade agreement with the EU to cover Eurasian and African markets.
After full production, the project is expected to have annual revenue exceeding 1.272 billion yuan, net profit exceeding 188 million yuan, and internal rate of return of 22%. In the first half of 2026, the company's overseas income increased by 45.03% year-on-year, providing ample order reserves for project production.

Fundraising Change, Aiming Higher
The original fundraising project "Nano Carbon Material Project (Phase II)" is progressing smoothly, Line 7 was already put into production in May 2026. This time only the 236 million yuan not yet invested is changed, which still needs shareholder meeting deliberation. The primary reason for the change is the upgrade of the technology route to a higher level: the downstream offshore cable industry continues to raise performance requirements for shielding materials. The higher-end route requires more comprehensive technical verification and process debugging, making the original timeline difficult to match. The company will direct the temporarily unused funds to the Egypt project with a shorter payback period and more clear benefits, avoiding capital sinking.

The Egypt project will form a "Domestic + Overseas" dual-drive model with the Shandong base, meeting overseas customer localization supply needs while diversifying single-region risks. With the continuous improvement of green tire penetration rate, Lianke Technology shifts from single product export to localized production supply. Egypt is expected to become an important manufacturing base for Chinese-funded tire upstream and downstream collaborative support, facing European and African markets. This "Downstream Factory, Upstream Support" cluster export path is worth watching.
The US trade restrictions on Chinese tires are escalating from "sniping" to "global sweep".
On September 14, the United Steelworkers (USW) wrote to the Office of the United States Trade Representative (USTR), formally requesting a global safeguard investigation on all categories of imported tires under Section 201 of the Trade Act of 1974. Unlike previous anti-dumping and countervailing duty cases or special safeguards targeting individual countries, this investigation covers passenger tires, truck and bus tires, off-road tires, and aircraft tires, regardless of origin—tire factories established by Chinese enterprises overseas are explicitly included in the scope of the crackdown for the first time.

Overseas Factory Building Route Named
USW explicitly named them in the letter: Since 2013, Chinese enterprises have built 17 new tire factories in 7 countries including Cambodia, Indonesia, Malaysia, Morocco, Serbia, Thailand, and Vietnam, leading to a long-term surge in US tire imports between 2021 and 2025. The highest increase in tires exported to the US from some transit countries reached 429%.
This is the core strategy for Chinese tire enterprises going overseas over the past decade: "building factories overseas, bypassing barriers." The potency of Section 201 lies in its low threshold; there is no need to prove unfair trade practices, only that import growth is a substantial cause of industry injury to initiate it. Once implemented, it will be a global safeguard measure, and Chinese-funded overseas bases and local exports will be "swept up in one net".

Excuse is "Industry Crisis", Core is Trade Protection
Data listed by USW shows US domestic tire production has declined by about 40% since 2000, and factory closures in the past two years have led to over 6,000 union members losing their jobs. However, it is worth noting that the US tire market itself suffers from weak demand; the US Tire Manufacturers Association predicts shipments will drop 1.8% year-on-year in 2026, while import volume in the first seven months of this year has already declined by 3.9% year-on-year.
History will not forget that the 2009 tire special safeguard case and the 2014 passenger car tire "anti-dumping and countervailing" cases were all initiated by USW. This time is merely a repeat of the same script.

Shadow of Triple Barriers Emerges
If this Section 201 investigation is filed, the US will form a triple trade barrier architecture of "Section 232 Tariffs + Section 301 Tariffs + Section 201 Safeguard Measures". Coupled with new regulations such as the US Customs strengthening Importer of Record (IOR) verification and deep origin tracing effective September 18, compliance and cost pressures for exports to the US will rise comprehensively.
Of course, currently it is only a union application, still requiring USTR evaluation, ITC industry injury investigation, and presidential ruling, with uncertainties existing. But the signal is clear: the era of regarding "changing origin" as an all-purpose risk avoidance solution is coming to an end. For Chinese tire enterprises deeply globalized, only technical upgrades and deep localization are the long-term strategies to navigate trade barriers. Whether the USTR files the case in the next 30 days is worth the close attention of the entire industry.
Recently, the Federation of Industry and Commerce of Shandong Province, in conjunction with multiple departments, released the "Announcement on the Public Notice of the Shortlisted Names for the 2026 Shandong Private Enterprise 100 Strong Series List". Qingdao Sentury Tires Co., Ltd. successfully made it to the 2026 Shandong Private Enterprise Top 200 List.


Joint Organization by Nine Departments, Standardized Process for Evaluation
This list was jointly organized and implemented by nine departments including the Shandong Federation of Industry and Commerce, the Provincial Development and Reform Commission, and the Provincial Department of Science and Technology. The shortlisted public notice list was formed according to standardized procedures such as enterprise declaration, city recommendation, expert review, and soliciting opinions from various member units. The public notice period is 5 working days (September 4, 2026 — September 10, 2026). The list adheres to the principles of openness, fairness, and impartiality, serving as an important reference for measuring the development level of private enterprises in Shandong Province.

Overseas Revenue Proportion 92.98%, Global Layout Formed
Sentury was founded in 2007 and is a private tire enterprise in the domestic tire industry with the "earliest overseas expansion and highest export proportion". In the first half of 2026, the proportion of the company's export and overseas income reached 92.98%, and products are exported to over 150 countries and regions.
The company primarily produces semi-steel radial tires, all-steel radial tires, and aircraft tires, with global production bases built in Qingdao, Thailand, Morocco, etc. In recent years, the company has continued to increase investment in scientific research and innovation, building intelligent manufacturing factories, and continuously breaking through in areas such as product R&D, intelligent manufacturing, and brand globalization.

High-End Product Expansion and Renovation Project Launch Public Notice
Recently, an expansion and renovation project of Sentury focusing on high-end tires completed its first public notice on the Shandong Province approval platform. The plan is for an annual production of 6 million semi-steel radial tires and 80,000 aircraft tires (including 50,000 retread tires), with a total investment of about 1.313 billion yuan.
As of the end of 2024, the aircraft tire sub-project has been completed first. The company has the production capacity to equip mainstream aircraft models such as Boeing and Airbus, and has signed R&D agreements with relevant aircraft manufacturing companies, entering their supplier lists.
However, as the "pearl on the crown" of the tire industry, aircraft tires have high technical barriers and long certification cycles. The company admitted that the annual production capacity of 80,000 aircraft tire projects has not yet achieved the expected benefits, and customer and market expansion still need to be steadily promoted. In addition, the "R&D Center Upgrade" project related to the main business has been delayed twice, with the latest plan postponed to the end of 2025. As of the end of June 2025, the project has cumulatively invested 216 million yuan, with an investment progress of 86.4% and a construction progress of 76%.

Listed is Affirmation, Also a New Starting Point
This entry into the 2026 Shandong Private Enterprise Top 200 public notice list is an affirmation of the company's operating results. Sentury stated that in the future it will continue to take root in Shandong, deeply cultivate the real economy, continuously strengthen technological innovation, focus on quality improvement and efficiency enhancement, accelerate the high-quality development of the enterprise, strive to build a world-class tire brand, and contribute to the development of the private economy in Shandong Province.
The US is getting serious again. This time, it is not just targeting China. An import investigation covering the globe and spanning all tire categories is being pushed to the negotiation table. For domestic tire companies regarding "overseas factory construction" as a tax evasion scheme, this might be the most dangerous hurdle in the past decade.
US Gunpoint Targets Chinese Overseas Tire Factories
September 14, Roxanne Brown, International President of the United Steelworkers (USW), wrote to US Trade Representative Jamison Greer, formally proposing a major application: launching a global safeguard investigation on all categories of imported tires pursuant to Section 201 of the "Trade Act of 1974".
Unlike the familiar anti-dumping and special safeguards of the past, the biggest change in this application is breaking away from the traditional thinking of "targeting a specific country", incorporating passenger car&light truck tires, truck/bus tires, off-road engineering tires, and aircraft tires entirely into the investigation scope.
The union stated bluntly that past scattered and fragmented trade remedy measures could no longer keep up with the reality of industrial relocation.

Simply put: Previously, when the US imposed tariffs on tires from Country A, companies would transfer capacity to Country B, not subject to tariffs, changing the origin to continue exporting to the US. Tariff barriers were easily circumvented by relocating capacity.
Letter data shows, the highest increase in tire exports to the US from countries like Serbia, Cambodia, Peru reached 429%. This is the "loop of loopholes" that USW fears most.
Especially many Chinese tire companies chose to build factories overseas, to avoid existing trade barriers. And this Section 201 application aims precisely at this circuitous route to go global.
The Industry Crisis Mentioned by the US Union
USW repeatedly emphasized in the open letter that the US domestic tire industry has fallen into crisis, even elevating tire manufacturing to the national security level. Tires are the basic guarantee for transportation, agriculture, mining, and industrial operations. Continuous decline in domestic capacity will directly impact supply chain security.
A set of core data warrants attention:
China is the core of the union's argument. According to USW letters, Chinese capacity continues to expand—2025 automotive tire production is about 865 million units, total capacity exceeds 1 billion units.

Looking back at history, USW pushed for the "421 Special Safeguard" case targeting Chinese tires as early as 2009, also the only successful case of this clause, but measures expired in 2012. Subsequent multiple anti-dumping cases all encountered the same problem: restricting exports of one country, capacity transfers rapidly, trade restriction effects are greatly diminished.
Also for this reason, the union is no longer satisfied with single-point strikes, demands upgraded to global tiered import restrictions, while supporting local industry plans, including domestic production capital subsidies, government priority procurement of domestic tires, etc.
Imported Tires Slightly Decline, But Risks Are Not Short-term
Latest customs statistics, in the first 7 months of 2026, US imported tires totaled 162.34 million units, down 3.9% year-on-year.
Passenger Car Tires: 98.02 million units, year-on-year -2%
Truck/Bus Tires: 34.52 million units, year-on-year -8%
Aircraft Tires: 183,000 units, year-on-year +18%
Motorcycle Tires: 2.07 million units, year-on-year -9%
Bicycle Tires: 4.67 million units, year-on-year +20%
American Tire Manufacturers Association (USTMA) July forecast, 2026 US total tire shipments 330.3 million units, down 1.8% year-on-year, market demand itself is weak.
USW also knows, short-term import data has declined, but they are concerned about the long-term supply shock brought by capacity transfer, rather than fluctuations in a single year. As long as global excess capacity can continue to transfer to barrier-free countries, the trend of US domestic factory shutdowns is hard to reverse.
The Impact on Domestic Tire Enterprises, Must Understand
Currently, this investigation is only a union application, not officially filed yet. Subsequently, it needs USTR evaluation, ITC injury investigation, final measures implementation ruled by the US President, overall carrying significant uncertainty.
But once filed and measures implemented, impact will far exceed past trade frictions. Unlike country-specific anti-dumping, special safeguards, Section 201 is a global safeguard measure, regardless of origin, Chinese domestic tires, tires produced by Chinese-funded overseas bases in Thailand/Cambodia/Serbia, exports to US will be uniformly constrained, completely impacting the industry's core model of overseas factory construction, transshipment tax avoidance followed for over ten years.
Domestic tire factories were already restricted by high tariffs on China, this time direct impact is limited; Chinese-funded overseas capacity will become the main bearing subject.

More critically, this Section 201 investigation is after Section 232 (25% tariff), Section 301 tariff, the third core tool of US tire trade barriers. If USTR accepts filing, it will form 232+301+201 triple tariff barrier structure, letting domestic and overseas tire exports to US fall into systematic risk.
Meanwhile Mexico, Canada rely on USMCA agreement enjoying trade exemption advantages, North American tire supply pattern may welcome reshaping. The USTR filing result in the next 30 days is the core key variable determining the direction of global tire trade.
Conclusion
From 2009 single country special safeguard, to now seeking global scope all categories tire safeguard investigation, to possible landing "Triple Tariff Structure", the net of US tire trade protection is getting tighter and tighter.
This is no longer simple trade friction targeting a certain country, but trying to build a global coverage protection net, plugging loopholes in capacity transfer. For domestic tire industry, this is a major warning. Going overseas layout, can no longer only take "changing origin" as a panacea for risk avoidance.
Market negotiations continue, every step of filing, investigation, and ruling is worth tire industry professionals closely monitoring.
Recently, the "Malaysia High-Performance Green Rubber Tire Production Base Construction Project" of Wanli Tire Co., Ltd. has seen new progress. The procurement bidding for the steel cord calender of this project has been concluded. RODOLFO COMERIO S.R.L, a globally renowned Italian calender equipment manufacturer, successfully won the bid, with a winning amount of 2.1 million Euros. This marks that Wanli Tire's plan to establish factories overseas is steadily advancing.

It is reported that the steel cord calender won in this bid is core key equipment in the tire manufacturing process, directly relating to the quality of tire carcass material and overall performance. The winning party RODOLFO COMERIO was founded in 1878. As a leading enterprise in the global calender field, it possesses profound technical expertise in the design and manufacturing of complete calender production lines such as rubber fabric and steel cord fabric.

According to the plan, this core equipment will be put into Wanli Tire's Malaysia production base, providing solid support for the project's annual production capacity target of 1.2 million all-steel radial tires and 5 million semi-steel radial tires.

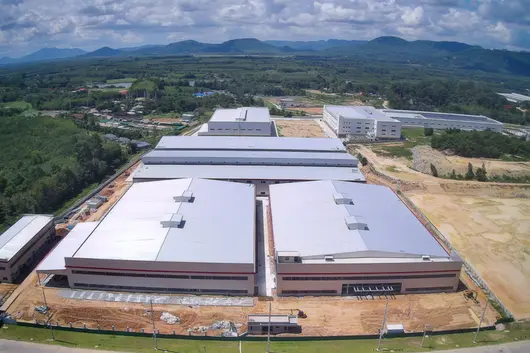
The Malaysia base is an important link in Wanli Tire's global strategic layout. The project is located in Bukit Daraka, Selangor, Malaysia, covering an area of about 67.9 acres, with a total investment scale of about 2.2 billion RMB. After the project is completed, Wanli Tire will leverage the location advantages of Malaysia to effectively expand overseas production capacity and build a tire export hub radiating globally. This investment in introducing top international manufacturing equipment also demonstrates Wanli Tire's determination to deepen cultivation in the international market and build a high-quality green tire industrial chain.
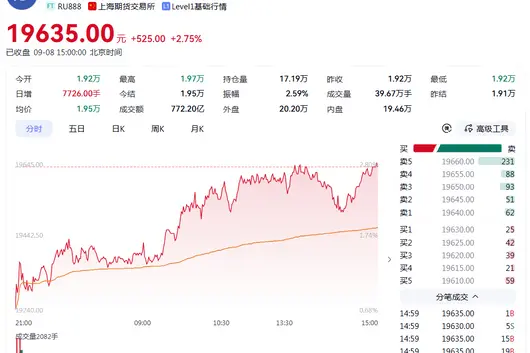
September 8, two "heavy bombs" landed simultaneously: Brent crude approached $100/barrel intraday, natural rubber main contract closed up 2.75%, quoted at 19,635 Yuan/ton, both hitting new phase highs. Under the surge of raw materials' "dual engines", two tire companies announced price hike letters on the same day. The third round of price hikes in the tire industry this year is now unstoppable.

Rubber Approaches 20,000 Yuan, Rubber Series "Three Brothers" Surge Together
September 8 closing, Shanghai Futures Exchange natural rubber main contract quoted at 19,635 Yuan/ton, up 2.75%, intraday high touched around 19,700 Yuan, one step away from the 20,000 Yuan threshold, single day turnover reached 77.22 billion Yuan.
The day before (September 7), the rubber series had already staged a collective surge: Natural rubber main contract closed at 19,180 Yuan/ton, up 2.18%; No. 20 Rubber main contract set a new record since listing, closed at 16,345 Yuan/ton; Synthetic rubber intraday approached 8%, closed at 15,605 Yuan/ton, up 4.59% for the day. Three varieties surged collectively and broke through the high-level oscillation zone within a day, which is rare in the past two years.

Guotai Junan Futures Analysts Point to Three Drivers:
First, synthetic rubber fundamentals are relatively strong. High oil prices pushed up the core raw material butadiene price, synthetic rubber processing profits continued to decline, some private enterprises operated at reduced capacity, supply side shrank, and market anxiety over spot liquidity intensified.
Second, natural rubber raw material side is firm. Hat Yai main producing areas had excessive rainfall and tapping was hindered, Hat Yai rubber glue prices rose from 75 Baht at the start of the month to 77.7 Baht; El Niño production cut expectations continued to ferment, impact intensity expected to peak in September-November, production cut logic difficult to disprove in the short term.
Third, the price hike atmosphere in the industrial chain is formed. Around September 1, over 25 tire enterprises such as Triangle, Double Star, Aeolus centrally adjusted prices by 2%-3%, strengthening bullish sentiment.
Different from the price hike wave in March-April, this time natural rubber and synthetic rubber resonated synchronously. According to Zhuochuang Information data, comparing September 3 with August 3, Shandong STR20# Blended Rubber rose 8.75%, Styrene Butadiene Rubber 1502 rose 16.67%, Polybutadiene Rubber rose 20.65%, Carbon Black N330 rose 16.89% — the four major core raw materials all surged heavily, none were "gentle".

Oil Price Nears $100, Goldman Sachs Forecasts $120
September 8, Brent crude intraday high touched $99.42/barrel, one step away from the $100 threshold, year-to-date gain nearly 100%; NY crude futures rose over 3%. On the same day, A-share oil and gas sector surged, Huajin Shares, Heshun Petroleum, Zhongman Petroleum hit limit up, Tongyuan Petroleum, Guanghui Energy and other stocks rose over 5%.
The direct trigger is the rapid escalation of the Middle East situation: Saudi energy facilities attacked by Houthis, partial facility operations interrupted, causing 73 injuries; meanwhile, US-Iran standoff over the Strait of Hormuz continued, US military required 94 commercial ships to alter course in blockade actions.
Goldman Sachs warned that if attacks escalate further, oil price may rise to $120/barrel; China Merchants Futures pointed out that if Yanbu Port exports continue to be hindered, supply reduction could expand to 3-4 million barrels/day. Plus OPEC+ announced October production halt — this is the first since production increase started in April this year, oil price upside risk is significant.

Price Hike Letters Land Again, Another "3% Hike"
Under cost pressure, two tire companies announced price hikes simultaneously on September 8:
Fangxing Rubber announced that due to continued rise in raw material prices such as rubber, carbon black, steel cord, starting from September 12, semi-steel, full-steel, and engineering tire series prices were adjusted upward by 3%;

Shandong Weihai Rubber announced that "Hongying", "OPALS", "HIMALAYA" brand full-steel radial tires increased by 3% starting from September 12.

This is the third centralized price hike in the tire industry since late August this year. But the gap between cost and selling price remains glaring: Zhuochuang Information calculates that on September 3, production cost of a single full-steel tire was about 984.97 Yuan, up 9.21% in one month, up 13.87% year-on-year. Cost rose nearly 10 points, selling price only rose 2-3 points, some economic tires already showed real losses like "losing 80 Yuan per tire sold". Some enterprises said frankly: Tire prices need to rise at least another 16% to cover costs, and 20% increase is needed to achieve profitability.
Industry insiders point out that raw materials are unlikely to fall in the short term, but weak demand constrains transmission, price hikes will show a pattern of "multiple batches, small amplitude" rotation, industry reshuffling accelerates. For dealers, the dense period of price hike letters is both opportunity and trap, reasonable stocking, cash flow is king, maintain flexibility to navigate the cycle.
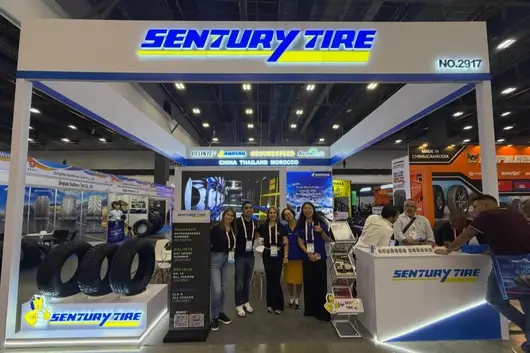
Recently, the 2026 Latin America Tire & Auto Parts Expo (Latin Tyre & Auto Parts Expo) grandly opened at the Panama Convention Center. Qingdao Sentinel Tire Co., Ltd. brought its three major brands, Sentinel, Landmark, and Deline, to Booth 2917, deeply connecting with the Latin American market with a full product matrix and global capacity advantages, taking a solid step into Latin America.

Full product lineup showcased, attracting attention from day one
At this exhibition, Sentinel showcased multiple core products such as passenger tires and off-road tires. The tread design and performance configuration are precisely adapted to the complex road conditions and travel needs of the Latin American region. With exquisite craftsmanship and outstanding product design, on the first day of the exhibition, the Sentinel booth attracted many local purchasers and industry clients to stop and observe, understanding product details up close.


Business team efficient coordination, multiple cooperation intentions reached on-site
There was a bustling exchange atmosphere at the exhibition. The Sentinel business team conducted in-depth negotiations with merchants from multiple Latin American countries on core issues such as product parameters, customized solutions, and supply cycles with professional technical explanations and efficient coordination services. Many customers expressed high recognition for Sentinel's product quality and brand strength, reaching multiple cooperation intentions on-site, laying a good foundation for subsequent cooperation between the two parties.


Three major production bases as support, delivery capabilities win customer confidence
For Latin American customers, supply chain stability and response speed are crucial, and this is exactly Sentinel's source of confidence. Relying on the global capacity layout of "China-Thailand-Morocco" three major production bases, Sentinel possesses stable and efficient global delivery capabilities, fully responding to the bulk procurement and localized supply needs of the Latin American market. The prominent global capacity signage at the exhibition also gave visiting merchants more confidence in its supply chain guarantee capabilities.


Representative of going global takes another step, Latin American market prospects promising
As a representative enterprise of Chinese tire brands going global, Sentinel has always taken technological innovation as its core, steadily promoting its global strategy. Panama is located at the confluence of North and South America, serving as a natural hub radiating the entire Latin American market. This exhibition is regarded as an important step for Sentinel to layout Latin America.
Industry insiders point out that the Latin American tire market is huge and continues to grow, with Chinese brands accelerating penetration with solid quality and efficient supply. In the future, Sentinel will continue to focus on overseas user needs, create more value for global travel with high-quality tire products and services, and deeply cultivate the Latin American market.
In the first half of 2026, the domestic tire industry showed a very obvious stark contrast.
From the latest semi-annual report, it is clearly visible: Leading enterprises that built factories overseas in advance saw their performance rise to new records year after year; small and medium manufacturers that stubbornly stuck to domestic capacity for export were basically passively under pressure and losing market share.

Those Who Go Global Early Enjoy the Dividends
The 2026 semi-annual report data plainly exposed the industry gap: Whether an enterprise can make money and stabilize its overseas market depends on whether its overseas capacity layout is fast and large enough.
Sailun Tyre is a solid benchmark for industry globalization, presenting its best ever half-year performance: Semi-annual revenue broke through 20 billion yuan for the first time, up 13.88% year-on-year; net profit was 2.16 billion yuan, up 17.97% year-on-year. More than 60% of the company's assets are laid out overseas (62.88%), the Vietnam and Cambodia bases continue to produce and earn steadily, forming the core profit backbone. Relying on the linkage of multiple bases in Southeast Asia, the Americas, and Africa, Sailun perfectly avoided trade barriers in Europe and the US, European orders are perpetually in high demand. Even with multiple price adjustments, customer demand remains firm. Over the next three years, there will be a concentrated release of overseas capacity, with strong confidence in growth.
Zhongce Rubber's overseas capacity expansion dividends have also been fully realized. In the first half of 2026, semi-steel tire production at the Thailand base increased by 38% year-on-year, while full-steel tire production at the Indonesia base surged by 249%. After the EU anti-dumping measures took effect, exports for many domestic enterprises were blocked, but Zhongce, relying on normal supply from its overseas bases, not only steadily held the European market but also took over a large volume of spillover orders. Meanwhile, relying on Indonesia capacity to take US orders, it successfully dodged tariff shocks. Currently, the company's new Vietnam base with a 1.04 billion yuan investment is progressing steadily, and the global capacity map is still expanding.

General Shares is a typical representative of benefiting from this round of going global, with performance taking a dramatic turnaround. In the first half of the year, net profit surged 114.84% year-on-year, gross profit margin increased by 3.31 percentage points, and profit quality improved significantly. The company's Thailand and Cambodia dual bases had booming production and sales. Seizing the EU trade policy window, semi-steel tire orders were perpetually in high demand. Overseas non-US market revenue rose steadily, successfully opening up a brand new growth space.
In addition, Zhengdao Tyres stated recently that the Cambodia base went into smooth production, tens of millions level of scaled capacity landed, completely reconstructing its overseas supply chain, and firmly standing in the international market under high barrier pressure.
Comprehensive Encirclement, Traditional Export No Longer Works
The eye-catching performance of leading enterprises is, simply put, the result of early risk avoidance and early planning. Nowadays, trade restrictions in the tire industry are no longer just about single tariffs, but comprehensive suppression including tariffs, dual anti-dumping, origin verification, and green compliance, which completely locks down domestic export paths.
The United States not only maintains high tariffs on Chinese tires but also ferociously investigates the origin in Southeast Asia, completely plugging loopholes for tax avoidance via transshipment; The EU is implementing semi-steel tire anti-dumping and pushing for anti-subsidy investigations, while stacking the EUDR zero-deforestation new regulations, raising entry barriers from tax, environmental, and compliance aspects.
Not only Europe and the US, Brazil, the Eurasian Economic Union, and many other economies are also increasing trade protection, with trade friction sweeping the globe.
On August 31, Canada officially joined the game, launching anti-dumping investigations on Chinese truck and bus tires. At this point, the three major mainstream markets of the US, EU, and Canada have comprehensively encircled, continuously squeezing the space for domestic tire exports, directly ramping up the urgency for enterprises to go global.

Why Must We Go Global Immediately?
Combining the latest financial reports and the global trade situation, there is no longer a need to hesitate about going global. It is necessary to go global as soon as possible and land capacity as soon as possible. This is the only way out for the industry to break through.
First, avoid trade barriers and protect core overseas markets. Now all major global markets are tightening policies. Without local overseas capacity, it is equivalent to directly losing export qualifications. Only by building factories overseas and local production can enterprises avoid anti-dumping tariffs, origin verification, and green compliance restrictions, safeguarding global sales channels.
Second, seize the huge market dividends left vacant by the industry. A large number of small and medium tire enterprises are being forced to exit overseas markets due to export restrictions, causing a significant global supply contraction. Meanwhile, leaders with overseas capacity like Sailun and Zhongce, taking advantage of industry supply gaps, continue to take over spillover orders and increase market share. The barriers instead become expansion opportunities for leaders.
Third, reduce costs and increase efficiency, improving profit advantages. Southeast Asian bases can purchase natural rubber locally, greatly compressing raw material and logistics costs; meanwhile, Vietnam and Thailand belong to CPTPP member countries, bringing tariff advantages. Exporting to Europe, the US, and Southeast Asia offers maximum cost-performance ratio, with profit space much higher than domestic exports.
Finally, widen the industry competition gap. The current industry reshuffle has already reached a fever pitch: Enterprises with overseas capacity continue to make money and expand share; those without overseas capacity can only stick to the domestic market and continue to shrink. In the future competition of the tire industry, the race is no longer about price, but about global capacity layout and supply chain risk resistance.

Overseas Capacity Has Become the Industry's Ultimate Moat
2026 is the decisive year for the globalization of China's tire industry.
Under the global trade pattern of encirclement by multiple countries, the old model of "Domestic Production, Global Export" has officially concluded, and localized production with regional supply has become the only path to break through.
The semi-annual report data has solidly proven: Enterprises that laid out globally in advance are continuously enjoying policy dividends, market dividends, and cost dividends.
In the next phase, industry concentration will continue to rise. Leading enterprises with a perfect global capacity network will continue to reap global market share. The era of globalization for China's tire industry has already fully arrived.
On August 13, the US White House released the report "The Great Transshipment Scam (Large-Scale Transshipment Scam)", placing Thailand on the Level 2 Risk Nation list, compounded by Thailand's continued ramp-up of tire market enforcement.
The gray path previously prevalent among some domestic tire traders and small-to-medium enterprises to evade US tariffs via "Thailand Transshipment Origin Laundering" has officially been declared invalid, sounding a compliance alarm for the entire tire export industry.
Thailand-origin gray transshipment has been officially classified
For a long time, suppressed by the high US dual anti-dumping tariffs on Chinese tires, domestic direct tire exports to the US have been costly. Some market players chose two completely different export routes: leading enterprises invested heavily in physical factories in Thailand, completing the full tire manufacturing process of rubber mixing, calendering, and vulcanization, obtaining a legal "Made in Thailand" status.
While another group of traders and small enterprises shipped finished domestic tires to Thailand, only changing packaging, tampering with sidewall labels, simple warehousing and assembly, and forging certificates of origin, exporting to the US under the name of Thai products to circumvent high tariffs, becoming a public gray operation in the industry.

US AI Full-Chain Strict Inspection
The American report this time directly classified such false transshipment as a systemic abuse of international trade rules. After Thailand was listed as a Level 2 Risk nation, US Customs upgraded inspection of tires exported from Thailand to the US from random sampling to normalized in-depth traceability verification.
The newly launched Detective Border AI inspection system is no longer limited to auditing paper customs declaration documents. It can cross-reference freight trajectories, corporate equity, and cargo characteristics, locking in high-risk containers before cargo arrives at the port.
More critically, the scope of accountability has expanded. Source factories, traders, overseas warehousing and processing parties, freight forwarders, and all subjects in the supply chain must bear compliance responsibilities, no longer just penalizing declaration enterprises.
Thailand Strict Crackdown on Tire Origin Fraud
Not only is there US pressure, local Thai regulations are also tightening simultaneously.
On August 20, a special investigation team from the Thai Ministry of Industry raided tire warehouses in Nonthaburi Province, seizing 408 defective tires. The case value was nearly 2.5 million Baht. Many tires lacked certification labels, and labels were manually tampered with. The involved brands have not yet been disclosed publicly.

Thai officials clarified that they will strictly check tire sources from both import and manufacturing ends. Violating entities face fines up to 500,000 Baht, 6 months imprisonment per Sina Finance.
At the institutional level, the Trade Department of the Thai Ministry of Commerce (DFT) completed the upgrade of rules of origin. All certificates of origin have been migrated to the e‑Service digital platform for online processing, divided into two major categories: General Certificate of Origin, Preferential Certificate of Origin.
To obtain genuine and valid "Made in Thailand" qualifications, tire products must meet one of five major conditions: Completely originated, substantive change in tariff classification, Regional Value Content (RVC) meets standards, meets tire category specific standards, adapts to differentiated requirements of the export destination country. Simply changing cardboard boxes or pasting labels cannot meet substantive processing standards, and legal origin status cannot be obtained. Enterprises using false certificates will face risks of cargo seizure and heavy fines.
Export Capacity Structure Accelerates Differentiation
The tightening of dual regulation by the US and Thailand will have a disruptive impact on the domestic tire export landscape. The industry formally welcomes compliance-driven reshuffling, with the differentiation between good and bad further exacerbating. This is mainly reflected in three dimensions:
First, the gray transshipment model has reached its end. Traders relying on warehousing and origin laundering arbitrage find their survival space sealed shut. For subsequent exports to the US, paper documents can no longer guarantee customs clearance. AI penetrative checks will trace the entire supply chain source of goods. Relying on luck makes it highly likely to face serious consequences such as cargo seizure, repayment of huge tariffs, and companies being placed on the US blacklist.
Second, distinguish "true factory construction" from "fake processing", further highlighting the value of overseas physical production capacity. Chinese tire factories that truly complete the full tire production process in Thailand, meeting hard standards for origin such as local value addition and tariff classification change, are not impacted by this rectification. Meanwhile, pseudo-overseas projects that only build warehouses without core production processes, merely relabeling and repackaging, will continue to face dual inspection pressure from both the US and Thailand.
Third, industry compliance costs rise, increasing pressure on small and medium foreign trade tire enterprises. Enterprises need to fully retain material procurement, production process, and cost accounting ledgers to respond to customs traceability verification at any time. Certificates of origin must be applied for through the Thai official system, eliminating third-party false certificates. In the future, tire exports will not just compete on price, but on supply chain compliance capabilities.

Core Points for Enterprise Compliance Export
CheYuanCheChe reminds, facing the new situation of current industry regulation, combining the latest rules of the US and Thai parties, tire foreign trade enterprises need to comprehensively adjust their export models, strictly adhere to compliance bottom lines. Core practical points are as follows:
1. Completely abandon the arbitrage thinking of origin laundering. The US AI inspection system can penetrate logistics, equity, and capital flow to identify false transshipment. The risk has been transmitted to the entire chain;
2. For Thai tires exported to the US, corresponding HS codes need to be verified, clarifying the applicable Tariff Change (CTC) or Regional Value Content (RVC) standards, fully retaining complete production, procurement, and cost archives;
3. All certificates of origin must be applied for through the Thai DFT official e‑Service platform. Reject non-formal false certificates of origin circulating on the market;
4. Even if local Thai origin rules are met, they must also adapt to the strict verification standards the US imposes on Level 2 Risk Nations. Be prepared to face on-site verification in advance.
The journey of Chinese tyre expansion has evolved from single-point breakthroughs to full-scale booms.
Since Sailing Group invested in Vietnam in 2012, building the first overseas factory for Chinese tyres, officially opening the overseas curtain, it has now formed a scaled, globalized industrial landscape.
A recent set of major revenue data disclosed by the China Rubber Industry Association directly confirms this decade-spanning overseas wave: 14 key tyre enterprises achieved a total overseas base revenue of 79.913 billion yuan in 2026, compared to 54.082 billion yuan the previous year, a year-on-year surge of 47.76%; the average proportion of overseas base revenue accounting for the total enterprise revenue reached 40.24%.

2025-2026 Annual Overseas Tyre Base Revenue Situation
Nearly 40% of revenue comes from overseas local factories. Core industry growth of nearly 80 billion has firmly secured the overseas capacity as the main engine of performance for the Chinese tyre industry, becoming the core pillar for companies to hedge against domestic involution and resist global trade risks.
Top players widen the gap, distinct tier differentiation
From the industry revenue rankings, the leading enterprises that went overseas first, leveraging their first-mover advantage to complete global layouts, have significantly widened the gap with SME brands, making industry tier differentiation increasingly clear.
Sailing Group leads far with 28.226 billion yuan overseas revenue, a year-on-year increase of up to 104.54%, overseas base revenue accounts for 77.54% of total enterprise revenue, fully releasing the dividends of globalized capacity layout, becoming a benchmark for industry overseas expansion.

Linglong Tires and Zhongce Rubber ranked second and third respectively with 11.93 billion yuan and 10.380 billion yuan. Jiangsu General and Sentinel follow closely, with both overseas revenues breaking 6.3 billion yuan, revenue proportions both exceeding 73%, deeply binding to overseas bases, and globalized layouts continuing to deepen.
Besides the old brand top enterprises steadying themselves, the industry's second tier has full explosive power. Changfeng Tires' overseas revenue skyrocketed 126.87% year-on-year; Haohua Tires and Fumas Tires achieved a breakthrough in overseas revenue from 0 to 1. A new batch of enterprises followed the industry's overseas wave, completed overseas capacity landing, formally joined the global battlefield, making the Chinese tyre overseas matrix increasingly strong.
Behind the Revenue Surge: Blooming Globally
Nowadays, the overseas revenue scale of nearly 80 billion is certainly not the work of one day.
Currently, 26 tyre enterprises in China are setting up overseas factories, and once completed, the number of overseas bases will exceed 40, production bases are distributed across Southeast Asia, North Africa, Central and Eastern Europe, Latin America, and other global core markets, completely bidding farewell to the past single export trade model.
Southeast Asia remains the core hotbed for factory construction: Thailand gathers giants like Zhongce, Linglong, Sentinel, General, etc.; Vietnam relies on early industrial foundations to become the core profit town for enterprises like Sailun, Guizhou Tyre, etc.; Cambodia has become a new investment lowland for the industry, with 10 enterprises clustered landing.
At the same time, countries such as Mexico, Egypt, Morocco, Serbia, Russia, etc., have all landed Chinese tyre factories, and the globalized capacity map is fully unfolded.
The overseas logic has completely iterated: Upgrading from the past 'production in China, sales globally' product output to a 'capacity + market' dual-output globalized layout, building factories on-site, producing on-site, supplying nearby, becoming the industry's main business model, and also the core confidence for continuous overseas revenue explosion.
Overseas Bases: Bolstering the Profit Bottom Line
Nowadays, overseas factories have completely reversed their role, transforming from initial cost investment items into the ballast stone that bolsters enterprise profits.
Flipping through the 2025 listed company financial reports, among 11 sample tyre companies, only 2 achieved positive net profit year-on-year growth, domestic market involution intensifies, profits continue to bear pressure, most enterprises' local business increases revenue but not profit.

The core breakthrough for growth against the trend all comes from overseas capacity: 7 enterprises' overseas factories contributed over 25% to the parent company's net profit, and the value of profitability is increasingly highlighted.
Among them, Sailun's two major Vietnam bases contributed 67% of the group's profit with 43% revenue proportion; Guizhou Tyre Vietnam base leveraged 56% profit with only 21% revenue proportion, overseas capacity's profit-making efficiency far exceeds domestic production lines.
Asset proportion data also confirms this deep transformation: General Shares and Sailun Tires overseas asset proportions reached 68.44% and 63.46% respectively, Sentinel and Linglong follow closely, industry average overseas asset proportion exceeds 20%.
After more than a decade of development, overseas bases have completely completed the transformation from 'cost centers' to 'value creation centers', becoming the confidence to cross industry cycles.
After 80 Billion: Overseas Dividend Peaks
But behind the eye-catching performance, the era of the industry's barbaric growth has already ended, and hidden risks and challenges continue to be highlighted.
A large number of enterprises cluster and expand production in core areas like Southeast Asia, homogeneous capacity is released centrally, overseas base early tariffs, cost excess returns are gradually falling back, Blue ocean markets are gradually turning red, industry involution spreads from domestic to overseas.

At the same time, production base transfer cannot permanently avoid trade barriers, the former tax haven, now also faces increasingly strict trade investigations, overseas risks continue to climb.
In addition, the overseas heavy-asset factory construction model poses extremely high requirements for enterprise capital strength, geo-risk control, supply chain management, and localization operation capabilities, the drawbacks of blind expansion and extensive layout gradually emerge, and industry reshuffling accelerates.
Second Half: From Grabbing Land to High-Quality Overseas Expansion
80 billion overseas revenue marks that Chinese tyre overseas expansion has entered the second half. With overseas thresholds constantly increasing, Matthew effect intensifies, top advantages continue to expand, SME brands face increasing pressure, the industry will bid farewell to the land-grabbing model of barbaric expansion, shifting to refined high-quality operations.
Breaking out of low-price capacity involution, industry competition will upgrade to a comprehensive strength contest of channels and brands.
The only way out for the future industry breakthrough is to break free from scale involution, from extensive capacity overseas expansion to high-value brand overseas expansion leapfrog breakout, completely bidding farewell to volume stacking, achieving true high-quality value growth.