首頁Sylphy

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

Written by | Du Yongfang
Editor | Huang Dalu
Design | Zhen Youmei
Cover Image | XY-AI
In 2016, under the leadership of then-chairman Carlos Ghosn, Nissan Motor acquired newly issued shares of Mitsubishi Motors for about 237.4 billion yen, securing a 34% stake to become the largest shareholder.
At that time, Mitsubishi had just admitted to fuel consumption data falsification, stock prices plummeted, and this cash infusion allowed it to breathe. Nissan intended to make both companies stronger by sharing technology, parts, and plants.

In October 2016, then Nissan Motor Chairman and President Carlos Ghosn (left) and then Mitsubishi Motors Chairman and President Osamu Masuko (right) after attending a press conference in Tokyo.
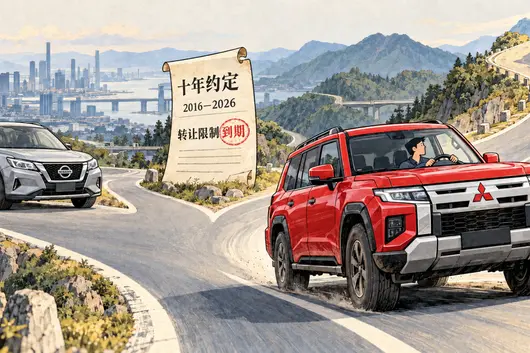
The transaction included a clause: for ten years from October 20, 2016, Nissan must obtain prior consent from Mitsubishi to transfer Mitsubishi shares. On October 20, 2026, this transfer restriction expired.
The initial savior itself fell into restructuring. In fiscal 2025, Nissan reported a net loss of about 533 billion yen, marking the second consecutive year of losses.
Although Mitsubishi maintained profitability, its financial situation is tight. For the same fiscal year, operating profit was about 75.5 billion yen, down 45.6% year-on-year; net profit was about 10 billion yen, down 75.6%.
More notably, sales: global sales dropped from 1.244 million units in fiscal 2018 to 797,000 units, a decrease of over one-third over seven years. Competition from Chinese brands in the Southeast Asian market, US tariffs, and the Middle East conflict are all adding pressure.
With both companies' situations deteriorating simultaneously, their capital relationship naturally needed re-evaluation.
Before the transfer restriction expired, Nissan stated it would maintain the existing capital relationship. According to a Kyodo News report on September 25, Nissan leans towards continuing to hold 26.67% of Mitsubishi's shares.
The reasons not to sell are realistic: shared lightweight car development is still needed for Nissan's reconstruction; factory restructuring is progressing as planned, with no pressure to cash out immediately; Mitsubishi's stock price is below the investment level, selling now might result in a loss.
The shareholding being 26.67% instead of 34% is related to a reduction in November 2024. At that time, Nissan's performance plunged, announcing layoffs of 9,000 people, while selling back about 149 million shares of Mitsubishi to Mitsubishi Motors, equivalent to 10.02% of Mitsubishi's then issued shares (excluding treasury shares). The selling price was 460.6 Yen per share, lower than the entry price of 468.52 Yen eight years ago.
Since Mitsubishi's buyback also changed the share base used to calculate shareholding, Nissan's shareholding dropped to 26.67%. In other words, before the transfer restriction expired, the capital tie between both parties had already loosened once.
Product relations are also changing. Mitsubishi is giving its own answer: The new-generation Outlander is preparing to switch to an independent platform, the Pajero is returning at a higher price, while establishing product cooperation with Honda and Honghua Advanced.
Nissan remains a major shareholder, but Mitsubishi is taking back more decision-making power in product development and re-selecting partners.

10-Year Alliance, Shared Benefits Come with Costs
The alliance has indeed left visible results. The Outlander shares a platform with the Nissan X-Trail; Nissan Sakura and Mitsubishi eK X, two lightweight pure electric vehicles, were co-developed by both sides.

The Mizushima Plant located in Okayama Prefecture used to produce the Lancer Evolution; now about 80% of output is lightweight vehicles, including models of Nissan brand. Nissan provides some core development capabilities, Mitsubishi undertakes manufacturing, so both sides share investments and utilize existing capacity.
But outside of lightweight vehicles, the cost advantages of shared development are not always realized.
A Mitsubishi executive believes some Nissan part specifications are higher than the demand of Mitsubishi's target markets, which actually weakens the cost advantage brought by sharing.
Mitsubishi's main markets are emerging economies like Southeast Asia. Specifications developed by Nissan according to North American and European demands, placed in price-sensitive Southeast Asia, may not make consumers pay more, but could drive up Mitsubishi's costs.
The premise for platform and part sharing is that product requirements between the two are close enough. Facing different customers and price ranges, after sharing they need to re-adapt and validate, and the development fees originally intended to be saved could be offset by these extra costs. The division of labor that works on lightweight vehicles is hard to replicate verbatim across the entire product line.
The next step for Outlander reflects Mitsubishi's adjustment to development methods. The new-generation Outlander expected to be launched around 2028 will switch to an independently developed Mitsubishi platform; the company judges this can bring higher profitability.
Independent development means bearing more development expenses and sales risks. In fiscal 2025, Mitsubishi's R&D expenses were 116.8 billion Yen. To allow limited budgets to undertake more tasks, the company plans to integrate platforms from five to three, shortening the development cycle from 45 months to 36 months.
Mitsubishi hopes to digest potentially increased investment after reducing alliance sharing through internal reuse and faster pace. Whether the independent platform is ultimately cost-effective depends on how many models it can support and how many vehicles it sells.

Elevate Brand with Niche Products
Mitsubishi places hope for the new round of growth on its strengths: four-wheel drive, off-roading, and durability, hoping consumers pay for these capabilities.
Behind this is a lesson. Mitsubishi once expanded scale by rushing sales, but deep discounts damaged brand value; after shocks like the pandemic arrived, it had to close factories and contract business. The new round of product plans needs to find reasons that better support selling prices.
The Pajero undertakes this task. On October 19, the new-generation Pajero launched in Thailand, produced by Mitsubishi's Thailand Laem Chabang plant; Japan and Australia plan to start sales in mid-December, and the Middle East, Central and South America, etc., will be targeted from the next fiscal year.

Mitsubishi Motors positions the new Pajero SUV as a flagship model in the Japanese market, thereby demonstrating its new strategy of creating niche models.
Pricing in the Japanese market best illustrates Mitsubishi's intent. The new Pajero is expected to start at 6.19 million Yen in Japan, the previous generation started at 4.53 million Yen.
Although the specs and cost environment of the two generations differ and cannot be simply compared, the new car is clearly striving for a higher price segment. Japanese pre-order bookings have reached 4,000 units, showing the Pajero still has brand appeal.
Mitsubishi also prepares to launch mid-size and compact Pajeros. The mid-size version is expected to launch in Japan around 2028-2029, sharing some parts with Outlander; the compact version targets around 2030. Large cars build brand image, smaller cars expand coverage, and shared parts help share investment.
The Japanese market provides a realistic basis for this approach. The Delica D:5 MPV and the light vehicle Delica Mini drove Mitsubishi's sales growth in Japan. The performance of the two cars indicates that Mitsubishi's niche products still have demand in the home market; the company hopes to replicate this experience to the Pajero family.
The Japanese market is also one of the export directions for Mitsubishi to reduce dependence on Southeast Asia. Southeast Asia accounts for about 30% of Mitsubishi's global sales, but operating profit in the region dropped from 63.6 billion Yen in fiscal 2019 to 22.9 billion Yen in fiscal 2025.
Competition from Chinese brands, plus weak demand in Thailand and Indonesia, is eroding Mitsubishi's original profit sources.
However, product upgrade does not equal unlimited price hikes. Some dealers are already worried that prices are rising too fast for some rural customers to afford.
Flagship models can attract new customers but may also keep existing familiar Mitsubishi customers at bay. After the first batch of Pajero orders, the more important question is whether demand will sustain.
Mitsubishi also incorporated used car business into growth plans. Previously, trade-in cars were mainly purchased and resold by individual dealers, with some circulating via auctions, at lower prices. In the future, HQ plans to strengthen centralized management and sell high-quality used cars through its own channels.
For old car owners, the higher the trade-in price, the less the price difference to pay for a new car; for customers with limited budgets, used cars are also an entry point to this brand. Whether this arrangement can support new car sales depends on whether Mitsubishi can improve vehicle residual value and circulation efficiency.
By fiscal 2029, Mitsubishi hopes to raise global sales from 797,000 units to 900,000 units, operating profit from about 75.5 billion Yen to 160 billion Yen, and operating profit margin to 4.5%.
Sales grow by only about 13%, but profits more than double.
Reversing from a 4.5% operating profit margin, 160 billion Yen operating profit corresponds to about 3.6 trillion Yen in revenue.
Mitsubishi needs to improve model structure and revenue per vehicle while increasing sales to support larger revenue scale. Reducing development and manufacturing costs helps turn increased revenue into profit.
Whether the Pajero can maintain its selling price, family models can share investment, and used car business can support new car trade-ins will affect how far this goal can go.

Build Core Independently, Borrow Shortcomings from Partners
Striving for more autonomy does not equal breaking up with Nissan. The product cooperation between the two has instead seen a clearer two-way division of labor.
Mitsubishi produces Rogue PHEV models for Nissan, and Nissan's mid-size pickup Navara developed based on Mitsubishi Triton; conversely, Mitsubishi prepares to use Nissan to return to the North American pickup market.

The US business needs this complementarity the most. Mitsubishi has no complete vehicle factories in the US, relying on exports from Japan, and faces tariff pressure.
Mitsubishi plans to introduce a pickup around 2029, based on products from Nissan's Canton plant in Mississippi, and continuously launch new cars, expanding the North American model lineup from 4 in 2024 to 8 around 2030.
Borrowing from partners to complete the product lineup can first stabilize the dealer network, buying time for independent model generations.
Honda has also entered this division of labor network. At the end of 2024, Honda and Nissan started business integration negotiations, Mitsubishi once considered joining; negotiations broke down in early 2025, but specific business cooperation continues.
Now, Honda and Mitsubishi are planning a pickup supply cooperation for the Southeast Asian market, with timing pointing to around 2028.
Mitsubishi's pickup products and manufacturing experience can help Honda expand business, and Mitsubishi has the opportunity to increase supply volume and share production costs.
Pure electric products reflect another trade-off of Mitsubishi: independent R&D focuses on hybrids, plug-in hybrids, and vehicle driving performance, while some pure electric models are purchased externally.
The pure electric version of Eclipse Sportback for North America is supplied by Nissan; the ASX VR-e announced in August is provided by Honghua Advanced, a joint venture electric vehicle company between Hon Hai Precision and Yulon Group. ASX VR-e is planned to launch in Australia and New Zealand within 2026, Mitsubishi conducted local road tests and exclusive suspension tuning for it.
This saves some investment from developing from scratch, filling the product lineup faster. But after putting the Mitsubishi badge on it, consumer expectations for driving feel, quality, and after-sales still need to be fulfilled by Mitsubishi.
For Mitsubishi with annual sales of less than 800,000 units, the direction is clear: master core models and key technologies independently, and supplement missing products, capacity, and development resources through cooperation.
Whether this path works depends on business results. From April to June 2026, Mitsubishi's operating profit increased by 80% year-on-year, but global sales dropped by 8%. Part of the profit improvement comes from exchange rates and selling prices.
Whether the Pajero family can expand sales, whether the independent platform can lower costs, and whether cooperative models can bring sustained revenue will determine if the goal of doubling profits can be realized.
Ten years ago, Mitsubishi first needed Nissan's money. Ten years later, it needs to make its four-wheel drive, plug-in hybrid, and manufacturing capabilities reasons for partners to want to procure and invest long-term.
The transfer restriction expiration opens up capital choices. Ultimately, what decides Mitsubishi's next chapter is what it can present in its own hands.
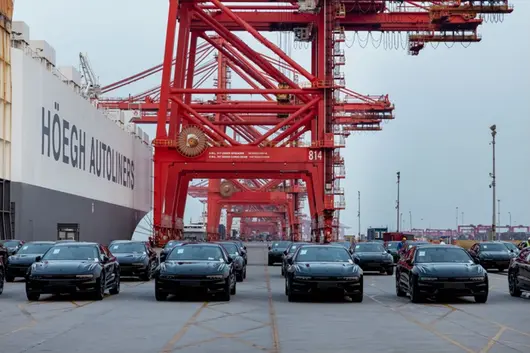
Early August, car makers typically "show off their results". BYD July sales 419,211 units, among them overseas sales 179,841 units, year-on-year increase of 124.3%, accounting for 43% of total sales; Chery Group sales 276,820 units, exports 202,533 units, year-on-year increase of 70.1%, becoming the first Chinese car company to exceed 200,000 monthly exports; Geely Automobile July sales 250,161 units, overseas exports 106,663 units, year-on-year increase of 202%.
Looking at these three sets of data and three representative car companies together, it is not difficult to find that going global has accounted for more than 40% of sales of top car companies.
From the performance of various car companies in the past, the features of going global reflected by this data are not accidental. BYD Chairman Wang Chuanfu has expressed on multiple occasions that BYD's goal is to become a "global new energy enterprise". The 43% proportion in overseas sales in July simply made this goal start to change from a slogan to reality. Chery Holdings Chairman Yin Tongyue also said: "Chery does not want to make easy money at home, but if Chinese cars only run within their own backyard, they will never produce world-class enterprises."

As for the reasons, there are several points worth paying attention to that might explain this. July new energy penetration rate created a historical high of 64.5%, but the retail scale of 1.52 million units itself was at a low level in the off-season. Fuel cars still have about 540,000 monthly sales, accounting for 35.5%. In addition, pure electric continues to strengthen internally within new energy, while plug-in hybrid/extended-range growth has slowed down. The incremental space in the domestic market is narrowing.
Considering the broader context, the attention given by top players to going global can be considered forward-looking preparation. And by this time, going global for more Chinese car companies has no longer been a "choice".
Behind the volume, the change of main battlefield is the general trend
The data of top car companies has raised the volume of going global, which also means that overseas has undoubtedly become the "main battlefield". BYD July overseas sales 179,841 units, accounting for 43% of total sales. January to July overseas cumulative 969,000 units, one step away from 1 million units. 8 RoRo ships fully deployed, annual capacity 1 million units, Thailand, Brazil, Hungary factories started production one after another, Spain's second European factory is under investigation. BYD's going global plan is huge, with the meaning of "going all in".
Chery Group July exports 202,533 units, accounting for 73% of total sales. Refreshing single-month export records for five consecutive months, January to July cumulative exports 1.146 million units, year-on-year increase of 71.2%. According to General Administration of Customs data, Chery is also a "big user" of going global. In 2025, the total export volume of Chinese automobiles is about 8.32 million units, Chery alone contributed 1.344 million units, accounting for more than 16%.

July data this year is even more pointed. Chery Automobile Co., Ltd. (9973.HK) July sales 261,876 units, year-on-year increase of 24.1%, entered the Fortune Global 500 List with the identity of a listed company for the first time, ranking 383rd, Return on Equity (ROE) 36.5%, ranking 30th among globally listed companies, and ranked first among Chinese enterprises. This shows that going global has become a key link for Chery to stand globally.
Geely's setup is also huge. Geely Automobile July exports 106,663 units, year-on-year increase of 202%, exceeding 100,000 units for two consecutive months, overseas proportion 42%. New energy exports 62,604 units, year-on-year surge of 616%, accounting for 59% of total exports. Zeekr brand July deliveries 35,837 units, year-on-year increase of 111%, winning the luxury pure electric sales champion in markets such as Australia, Malaysia, Mexico, etc.

The three top car companies combined went global by about 490,000 units, while the entire domestic narrow passenger car market July retail was also only 1.52 million units. This shows that going global for top car companies is no longer a "supplement", but the "top priority". Li Auto July deliveries 30,468 units, slight decrease of 0.9% year-on-year, but L9 still started local production in Kazakhstan. This is the first step it took overseas, showing that even new forces feel the pressure of "go global or perish".
Of course, trend is one thing, and reality issues cannot be ignored either. Does the "half of the sky" in volume equal the "main battlefield" in quality? This is a question worth further thinking. For example, Chery export proportion is 73%, but domestic monthly sales is only 74,000 units, overseas is three times domestic data. There is a risk here. If policies change suddenly in overseas markets, the impact will be huge.
Going global is really making money, or changing places to "compete"?
Volume is explicit, looking at sales proportion can tell. Profit is implicit, no matter which battlefield, this is an unavoidable issue. From the pricing space perspective, overseas markets indeed have more advantages than domestic. The price war in domestic car market has been fought for several years. July terminal average discount narrowed month-on-month, but overall is still in price competition. BYD Dynasty and Ocean series domestic main sales 100,000-200,000 yuan interval, price pressure is huge, but sold for good money abroad.
Chery's first complete financial report after listing also shows that Chery's average selling price per car overseas is 15,000 yuan more expensive than domestic. In Middle East, Jetour Traveler high-spec version sells to 450,000 yuan, twice as expensive as domestic. BYD's Fang Cheng Bao, Denza and other high-end brands are also accelerating going global, overseas single car average price far higher than domestic.

Geely's situation is also similar. Zeekr brand average price exceeds 300,000 yuan, positioning as luxury brand in Australia, Malaysia and other markets, premium pricing power far higher than domestic. Behind the new energy exports surging 616% year-on-year, it is high value-added products supporting, not low price walking volume. This shows that actually high-quality models overseas still have profit space.
However, hidden costs are also fierce. European Union imposing anti-subsidy duties on Chinese electric vehicles, United States market basically closed to Chinese car companies, tariff barrier costs should be calculated. So far, overseas is indeed worth fighting, but laying out overseas now might become more difficult, costs will also be higher.

After all, going global input is not a small number. BYD self-built 8 RoRo ships, built factories on three continents, input is billions level. Chery South Africa Roslin plant launched, Spain cooperation re-activated EBRO brand; Geely reached Ford Spain Valencia factory joint venture agreement and other operations behind, also money paving the way.
Currently mainstream car companies tried three going global modes, benefits and risk performance are completely different. For example, early Chery was pure product export model, profit margin medium, front investment low, but risk high, tariff and policy fluctuations could disrupt rhythm at any time. BYD walked product + capacity localization model, long term view profit margin higher, but front investment extremely high, testing global supply chain management and cross-cultural operation capabilities. Geely used technical cooperation + capacity sharing model, path lightest, but control ability will also correspondingly weaken.

New forces now have their own understanding. NIO July deliveries 35,934 units, year-on-year increase of 71%, battery swap station network in Europe continued to layout. Leapmotor July deliveries 101,267 units, year-on-year increase of 102%, first time breaking 100,000 units threshold, first half year overseas exports nearly 100,000 units, already exceeded last year full year. XPeng July deliveries 38,027 units, year-on-year increase only 4%, but in Germany completed XPeng Turing AI Smart Driving localization acceptance testing. Overall, new forces walk mostly differentiated route.
Can only say, going global has "profit" to earn, but absolutely not a smooth path. Overseas also need to "compete", but worth it depends on profit.
"Main battlefield" conversion behind, or domestic market incremental "not enough to share"
Going global why being pushed to "main battlefield" position, domestic market incremental space narrowing is fundamental factor. July new energy retail about 980,000 units, among them pure electric proportion about 60%, pure electric internal to new energy continues to strengthen, plug-in hybrid/extended-range growth slowed down. This means, "oil and electric" market share is being squeezed by pure electric quickly, pure electric acceptance is continuously improving.
New forces differentiation also proves this. Leapmotor July deliveries break 100,000 units, becoming domestic first single month deliveries exceed 100,000 units new force brand. Its success relies on covering 60,000-300,000 yuan full price product matrix, and overseas market simultaneous explosion. Li Auto July deliveries 30,468 units, slight decrease of 0.9% year-on-year, decrease of 1.4% month-on-month, only double decrease brand among top new forces. There indeed exists i6 due to supply chain issues reduced production about 4,000 units special situation, showing brand dependence on single model is still risk. NIO July deliveries 35,934 units, decrease of 11.5% month-on-month, even three brands collaboration exerting force, but still did not achieve effective complement between brands.

Another aspect, fuel car toughness is still there. July fuel car retail about 540,000 units, market share 35.5%. Sylphy, Lavida still firmly stable in sedan top three, Japanese SUV year-on-year decline over 10%, but not "cliff-like drop". Fuel car stock user replacement cycle still there, short term will not disappear. All this points to one core contradiction: domestic market "cake" is getting bigger, but cake stealing car companies do not yield to each other, competition is continuously intensifying.
BYD domestic monthly sales 239,000 units, already approaching single car company domestic share limit. Leapmotor at 100,000 unit level volume continue to climb, will face capacity bottleneck and supply chain pressure. XPeng July deliveries 38,027 units, new model MONA L03 orders hot but capacity ramp-up is its next biggest test. Xiaomi Auto July deliveries over 30,000 units, fourth consecutive month stuck at this threshold, Peng Cheng series September only listed deliveries, real volume pushing to fourth quarter.

Domestic auto market incremental space narrowing, stock competition new stage arriving, current Chinese auto market, "domestic demand pressure, foreign trade strength" structure or will be future relatively long term trend. Simply put, domestic market this piece of cake, already not enough to share. Not going global, wait to die; going global, maybe still have live road.
Conclusion
From July sales overseas data view, going global now is already car company "main battlefield". Domestic market growth slowing, fuel car won't die fast, stock competition intensifying, going global is inevitable choice. But overseas pricing space larger is fact, but tariffs, building factories, logistics costs not low, different mode profit structure difference huge. Who can win this "main battlefield" battle, now hard to say. Regardless of next battle situation how, Chinese car companies must be clear is, going global is not picking up money, more does not represent domestic market can relax vigilance, how to balance internal and external relations, choose suitable going global mode, is the key.