首頁Power Battery

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
"Taking safety as the cornerstone and leading global new energy technology" is Yinpai Battery's vision. Under this vision, Yinpai creates industry benchmark products with excellent lithium battery manufacturing capabilities, and its cells remain smokeless, fireless, and explosion-proof under conditions of nail penetration, 360° torsion, and triple folding.
Nail penetration testing simulates the extreme working condition of internal short circuits in batteries, which is a high-difficulty safety test recognized by the industry; 360° torsion and triple folding test the stability of cells under deformation conditions from the perspective of mechanical abuse. Passing multiple stringent tests simultaneously indicates that Yinpai possesses systematic safety control capabilities in terms of cell material systems, structural design, and manufacturing processes, rather than point optimizations.
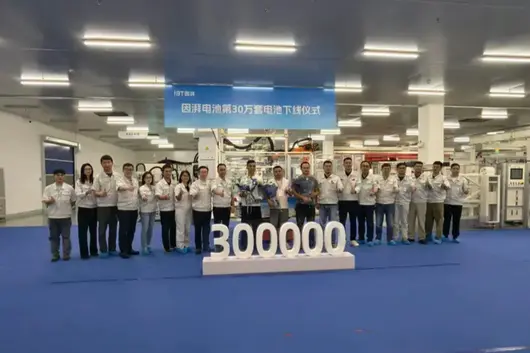
The reason safety is placed in the cornerstone position by Yinpai is closely related to its industrialization positioning. Yinpai Battery is the battery industrialization entity of GAC Group, with a total investment of 10.9 billion RMB. Power and energy storage batteries are fully self-developed and self-produced, covering two major fields: new energy vehicles and energy storage. Whether for passenger cars or energy storage scenarios, battery safety is directly related to user life, property, and system stability. With the 300,000th set of power batteries rolling off the production line and the Thailand factory about to open, Yinpai's safety capabilities will also undergo market testing on a larger scale and in more scenarios.

On the evening of November 3, Gasgoo learned from GAC Group that the opening ceremony of the GAC EnPower Thailand factory and the off-line ceremony of the first set of power batteries was held on October 29 in Chonburi Province, Thailand. This is GAC Group's first overseas independent power battery PACK factory, marking its realization of whole vehicle manufacturing and power battery PACK local supply in Thailand.

Image Source: GAC Group
According to the introduction, the factory's Phase 1 planned annual capacity is 7,000 battery packs, mainly supporting the AION Y Plus models produced in Thailand; Phase 2 reserves expansion space, and after reaching capacity, the annual output is expected to increase to 20,000 sets.
In terms of production and manufacturing, the Thailand factory will introduce the battery PACK manufacturing processes and quality management systems of EnPower in China to meet local vehicle production needs. GAC stated that local battery supply helps shorten delivery cycles and improve the stability of the overseas supply chain.

Image Source: GAC Group
EnPower batteries are an important part of GAC Group's power battery business. GAC started R&D of battery systems and Battery Management Systems (BMS) in 2011, subsequently expanding to cell R&D, production, and PACK manufacturing. In 2023, the EnPower domestic factory was completed and commenced production. On the eve of the Thailand factory's launch, EnPower's 300,000th battery set went off the line in Guangzhou.
In recent years, Thailand has continued to promote the new energy vehicle industry through policies such as EV3.5 and encouraged car companies to expand local production. With Chinese automakers accelerating their Southeast Asian market layout, overseas manufacturing is extending from vehicle assembly to core component support.
For GAC, the launch of the Thailand PACK factory further improved the local manufacturing system. However, currently the factory mainly serves AION's existing models; future capacity expansion and the scope of local supply will still depend on Southeast Asian market demand and the development of GAC's overseas business.
【AutoDao Industry】Let's review the major events that occurred in the automotive circle on October 16, 2026.
Automotive Event 1: JAC Motors Hits Limit Up
On October 16, the automotive sector saw volatile rebounds, with JAC Motors hitting the limit up, quoted at 22.37 CNY/share, a rise of 9.98%, with the latest total market value exceeding 50 billion CNY.


On October 15, Zunjie Automotive issued a statement, stating that Zunjie Automotive actively responded, fully obeyed, and would fully cooperate with the work of the joint investigation team, resolutely safeguard the legitimate rights and interests of consumers, and resolutely safeguard the overall situation of the development of the new energy vehicle industry. That evening, the Ministry of Industry and Information Technology and two other departments released a joint investigation report on the relevant vehicle brake pedal bracket fracture problem.
Subsequently, on the evening of October 15, Huawei Executive Director, Chairman of the Product Investment Review Committee, and Chairman of the Terminal BG, Richard Yu, responded on his personal WeChat Moments, "Justice may be late, but it will never be absent!"
Automotive Event 2: September 2026 Domestic Power Battery Capacity Installed 87.2GWh, Month-on-Month Increase of 10.4%


On October 15, the China Automobile Power Battery Industry Innovation Alliance released the September 2026 Power Battery Monthly Information. Regarding September production, the combined output of power and energy storage batteries in China was 237.8GWh, a month-on-month increase of 0.3%, and a year-on-year increase of 57.3%. From January to September, the cumulative output of power and energy storage batteries in China was 1833.1GWh, a cumulative year-on-year increase of 63.4%.
Automotive Event 3: Denza Dual Flagship Models Debut in Indonesia
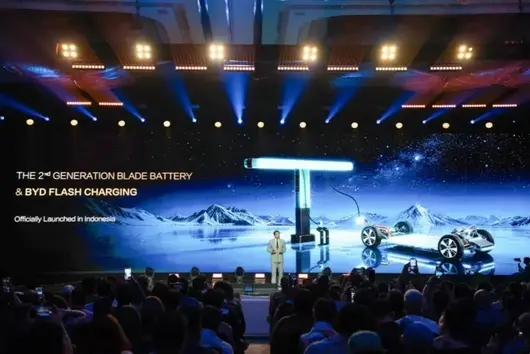
Recently, Denza Automotive officially released the second-generation Blade Battery and Flash Charge Technology in Indonesia, and announced that Denza Z9GT and Denza D9 have officially landed. Relying on two disruptive technological innovations, it has achieved a globally leading ultra-fast charging speed, truly achieving "Charge fully in 5 minutes, charge completely in 9 minutes", making charging as convenient and efficient as refueling.

Liu Xueliang, Vice President of BYD Company Limited and General Manager of the Asia-Pacific Auto Sales Division, stated: "True technical passion is believing in a future and firmly turning it into reality. Up to now, BYD's thinking on technological innovation has long transcended the simple category of 'making cars, selling cars'. We have always believed that a company's value lies not only in how strong it is itself, but more in whether it can create greater value for society through technological innovation, so that advanced technology truly benefits more people. It is this belief that drives BYD to constantly break through technical boundaries and gradually turn what once seemed like a distant technical vision into reality. Taking the second-generation Blade Battery and Flash Charge Technology to Indonesia this time is the specific realization of this concept. We hope to let more Indonesian consumers truly feel the changes brought by technological progress, and let advanced technology truly enter people's daily life."
Automotive Event 4: Changan Automobile Senior Personnel Adjustment

Recently, AutoDao reported, On October 16, Chongqing Changan Automobile Co., Ltd. (hereinafter referred to as "Changan Automobile") latest announcement disclosed, Zhu Furong continues to serve as the Party Secretary and Chairman of China National Chang'an Automotive Group Co., Ltd. (hereinafter referred to as "China National Chang'an Automotive"), coordinating the overall planning and long-term development of the automotive business under the group from a group level, no longer holding any position in the company and its holding subsidiaries. Original Changan Automobile President Zhao Fei promoted to Chairman, Original Executive Vice President Ye Pei promoted to President.

(Zhao Fei)
In addition, Ye Pe no longer serves as Changan Automobile Executive Vice President, will serve as Director, President, Deputy Party Secretary. Yang Dayong no longer serves as Changan Automobile Executive Vice President, will serve as Executive Vice President. Deng Chenghao no longer serves as Changan Automobile Vice President, will serve as Executive Vice President.
Changan Automobile stated that this adjustment aims to give full play to the role of China National Chang'an Automotive Group as a professional automotive industry group in "strategy setting, resource allocation, synergy promotion, risk control, and incentive strengthening", which is conducive to the company's further optimization of market-oriented mechanisms, focusing on global operations, and promoting high-quality development of listed companies.
"Daily Car News", here are the latest car news of the day, please continue to follow "AutoDao".


In the first half of 2026, Sunwoda's power battery delivery volume and revenue both grew significantly. Power and storage batteries have already become the company's main source of revenue, surpassing consumer batteries. However, the subsidiary Sunwoda Power, which serves as the core carrier of the power battery business, is still losing money. Coupled with exchange losses in overseas markets, Sunwoda's non-recurring net profit for the first half of the year was less than 100 million yuan. The new growth engine has just arrived but is yet to exert force.
Written by | “Caijing” Special Contributors Yang Zheng, Zhao Cheng
As a globally leading consumer battery supplier, Sunwoda (300207.SZ)'s main growth engine is shifting towards power batteries.
Recently, Sunwoda Electronic Co., Ltd. disclosed its 2026 semi-annual report. The company achieved operating revenue of 38.179 billion yuan in the first half of the year, a year-on-year increase of 41.48%, setting a new record for the same period. Net profit was 468 million yuan, a year-on-year increase of 91.1%. Net profit attributable to shareholders of the listed company was 603 million yuan, a year-on-year decrease of 29.59%. The difference between the two comes from minority interest, specifically the loss of the non-wholly-owned subsidiary Sunwoda Power.
The change in performance mainly stems from two aspects: First, power battery deliveries surged 76.37% year-on-year to 28.36GWh, driving rapid expansion of revenue scale; Second, financial expenses surged 345.33% to 882 million yuan, mainly due to increased exchange losses.
From a business structure perspective, Sunwoda, which used to be mainly focused on the consumer battery business, has shifted its core growth engine to the power and energy storage sectors. Electric vehicle (power battery) business revenue reached 14.134 billion yuan, a year-on-year increase of 85.87%, with gross margin improving by 8.59 percentage points to 18.36%. Energy storage system business revenue reached 1.77 billion yuan, a year-on-year increase of 76.21%. In comparison, traditional advantageous consumer battery business revenue was 14.452 billion yuan, a year-on-year increase of 4.04%, with gross margin declining by 4.95 percentage points to 14.68%. It is evident that Sunwoda's profit growth in the first half of this year mainly came from power batteries and energy storage systems, and the main growth engine has shifted to the power battery sector.
However, the contradiction lies here. Sunwoda Power Technology, the core of the power battery business, achieved operating revenue of 15.529 billion yuan in the first half of the year, a year-on-year increase of 90.1%, but still incurred a loss of 129 million yuan calculated on a net profit attributable to the parent company basis.
This means that although Sunwoda has found new growth momentum in the face of weak growth in the traditional consumer market, its profit quality still needs improvement. The real test may not lie in how many orders are won, but in how much money can be earned from those orders.

(Chart: Yang Zheng | Data Source: Corporate Financial Report)

Power Battery Becomes the Main Engine of Revenue Growth
Power battery business is Sunwoda's main growth pole in the first half of the year. Financial reports show that electric vehicle battery revenue in the first half of the year reached 14.134 billion yuan, a year-on-year increase of 85.87%, with gross margin at 18.36%, nearly doubling the 9.77% of the same period last year. In the first half of 2026, the company's electric vehicle battery delivery volume reached 28.36GWh, a year-on-year increase of 76.37%.
The rapid growth in the power battery field comes from both internal and external dynamics. First, Sunwoda's leading position in the HEV (Hybrid Electric Vehicle) battery field. In 2018, Sunwoda passed the review of the Renault-Nissan Alliance and obtained HEV battery specifications. Products were equipped on models like Sylphy and X-Trail e-POWER, and entered the hybrid supply system of many main models of SAIC Volkswagen and FAW-Volkswagen. SNE Research data shows that in the second quarter of this year, Sunwoda's HEV lithium battery installed capacity ranked first globally.
European market demand for HEV batteries continues to drive related business growth. According to official data released by the European Automobile Manufacturers Association (ACEA), the market share of HEV in new car registrations in the EU was 37.3% in the first half of this year. This proportion ranked first among all power types and increased from 34.8% in the same period of 2025. Accordingly, Sunwoda planned a 15GWh power battery base in Hungary to meet the needs of large customers like Renault and Volkswagen. This factory will become the first wholly-owned battery factory built by a Chinese second-tier manufacturer in Europe.
The domestic market also shows a development trend favorable to Sunwoda. Many vehicle enterprises are striving to promote the diversification of power battery suppliers, providing entry space for second-tier manufacturers. Zhongshang Industry Research Institute data shows that CATL's market share in the power battery market showed a downward trend overall in the first half of the year, dropping from 49% in February to 42.7% in June. CITIC Securities analysis stated that against the backdrop of continuous intensification of competition in the automotive industry chain, the power battery supply system is gradually evolving from single supply to dual supply and multi-supply, and diversified procurement will become a long-term industry trend.
In the second half of 2025, Sunwoda and Li Auto established a power battery joint venture, Shandong Li Auto Battery Co., Ltd., in Shandong with equity ratios of 50% each. Sunwoda stated in its financial report that Shandong Li Auto is managed by the Sunwoda dispatched management team. In addition, according to local media reports, in Xiaomi Auto's independent sub-brand "Xuntian" series, Sunwada became the primary supplier with a supply proportion of 60%. Hongmeng Intelligent Mobility's Luxeed brand also officially introduced Sunwada, with two models Luxeed V9 and Luxeed R7 to be equipped with its ternary battery packs. At the same time, mainstream automakers such as SAIC Motor, Geely, and Wuling maintain close cooperation with Sunwada. The Phase I products of Sunwada's Yiwu base are directly supplying Volvo and Geely.

(Chart: Yang Zheng | Data Source: Corporate Financial Report)
Cooperation with many vehicle manufacturers effectively pulled Sunwada's power battery market performance. According to Gasgoo Automotive Research Institute data, Sunwada's power battery installed capacity reached 7.24GWh in the first half of the year, with a market share of 3.1%. Installed capacity increased by 32% year-on-year, and market share increased by 0.6 percentage points compared to the full year of 2025.
Accordingly, the release of scale effects and improvement of profitability in the power battery field were expected. Western Securities research report pointed out that Sunwada's power battery is equipped with vehicle companies such as Li Auto, Dongfeng, Geely, Renault, and Nissan, and is expected to achieve the release of shipment scale effects and drive the company's annual performance to break even. Huachuang Securities also believes that the company's power battery and energy storage business volume drive high revenue growth, and profitability has been significantly repaired.

New Energy Storage Products Land, Second Curve Appears
The incremental business of energy storage is mentioned frequently by brokerage firms along with the power battery sector. Financial reports show that Sunwada's energy storage business revenue in the first half of the year was 1.77 billion yuan, a year-on-year increase of 76.21%, with delivery volume of 14.7GWh, a year-on-year increase of 64.98%.
The highlight of new products this year is large-capacity cells and AI backup power. In May, Sunwada put into production 588Ah energy storage cells, and officially released them in August. The cell energy density reached 417Wh/L. At 25 degrees Celsius and when the battery health drops to 70%, the cycle life can reach 10,000 times, theoretically matching the 20-year operation cycle of the power station. The full life cycle of a single 200MWh power station is expected to save 10 million kWh of power loss. Before this, its 684Ah stacked cells achieved mass production of millions of units. The two products are based on winding and stacking routes, forming a capacity ladder covering different system designs.
Financial reports show that Sunwada's energy storage system revenue mainly comes from overseas markets, with over 70% of overseas customers. In the field of home energy storage and industry and commerce, it has covered core markets in Europe, the Middle East, and South Asia. Europe is the main battlefield, becoming a major industrial and commercial energy storage brand in the German-speaking region, with core channel coverage exceeding 95%. In the field of network energy, with the high-speed expansion of the global AI (Artificial Intelligence) computing power industry, Sunwada's AIDC (Artificial Intelligence Data Center) energy storage business orders increased nearly 30 times year-on-year in the first half of the year. Relying on full-stack self-developed capabilities, its AIDC lithium battery solutions have been implemented in multiple key projects at home and abroad.
CICC research report stated that data center energy storage backup power demand is expanding, and Sunwada can provide a full-stack solution, so it is optimistic that energy storage business will become the company's second growth curve along with power battery business.

(Image Source: Yang Zheng)

Quality of New Engine Needs Improvement
In the first half of the year, consumer battery revenue, as Sunwada's traditional main business, reached 14.452 billion yuan, a year-on-year increase of only 4.04%, with gross margin declining by 4.95 percentage points to 14.68%. This is not a problem unique to Sunwada. Brokerage firm research reports show that global smartphone shipments declined year-on-year in the first half of the year. Although high-end phone sales grew, it could not change the overall pressure on the sector, and the profit space for consumer cells was squeezed.
However, for Sunwada, consumer batteries are the company's main products sold overseas. With limited growth in the consumer battery business compared to the previous year, the urgency of the power and storage sector continuing to expand its overseas layout became more obvious.
Currently, Sunwada's overseas bases are still in the investment phase. Financial reports show that Sunwada's Thailand battery production base Phase I project officially started production in the first half of the year. Currently, the company still has Thailand Phase II project, Hungary power battery production base, and Vietnam consumer cell production base under construction in overseas. The cost of the investment phase is directly reflected in the financial end. In the first half of the year, exchange loss was 538 million yuan, among which the US dollar was hedged through hedging. Tether, Indian rupee and other currency hedging tools are limited. The financial expenses surged more than 300%, largely due to this.
Therefore, Sunwada's growth prospects in the second half of the year still need to return to the domestic power and storage market. Brokerage structure analysis believes that Sunwada's power and storage product deliveries for the second half of the year are fully booked. As raw material price adjustments gradually land and production line yield rates continue to improve, future profitability is expected to improve. According to Dongwu Securities' calculation, Sunwada's annual power and storage delivery volume will reach 90GWh, of which power batteries are 55GWh and energy storage systems are 35GWh. This means that the company has about 62GWh to be delivered in the second half of the year. If the profit per Wh improves by one cent, there will be an additional 620 million yuan of profit space, and vice versa. The company's profitability curve for the second half of the year and even the full year will largely be determined by the power and storage business, especially the profit quality of the power battery sector.
Looking at power battery performance horizontally within the industry, among the few power battery listed companies that recently disclosed financial reports, Sunwada has the advantages of fast growth rate and large gross margin improvement, as well as the disadvantage of not yet achieving profitability in the power sector. Besides CATL which leads in scale and profitability, Gotion High-Tech achieved 1.386 billion yuan of net profit attributable to the parent company in the first half of the year while achieving power battery installed capacity ranking in the top three. EVE Energy's net profit attributable to the parent company in the first half of the year was 3.3 billion yuan with 45.7 billion yuan in revenue, with a net profit increase of 105.66%, and power and storage entered a stable profitability zone. In comparison, although Sunwada's power battery business achieved high revenue growth and significant gross margin improvement, it still recorded a small overall loss in the first half of the year, and the overall net profit attributable to the parent company was not commensurate with its revenue scale of over 38 billion yuan.
Growth rate not losing to peers, profit quality still catching up, is Sunwada's true position in the power battery industry. In other words, the growth engine has completed the switch, but there is still distance from the new engine being in place to exert force on growth.

Fu Rong, Interns Fang Weibo, Cheng Siyu
On the evening of August 26, Sunwoda (300207.SZ) released its 2026 Semi-Annual Report. In the first half of the year, the company achieved revenue of 381.79 billion yuan, a year-on-year increase of 41.48%, setting a historical high for the same period; however, net profit attributable to shareholders was 6.03 billion yuan, a year-on-year decline of 29.59%, and deducted non-recurring net profit was only 0.97 billion yuan, a sharp year-on-year drop of 83.32%. The company exhibited the characteristic of "revenue growth without profit growth", and the profitability of the battery main business is under pressure.

From the perspective of business structure, Sunwoda is accelerating the shift away from dependence on a single business. As the core business, consumer batteries achieved revenue of 144.52 billion yuan in the first half of the year, up 4% year-on-year, firmly ranking first in global mobile phone battery market share. However, affected by weak global consumer electronics demand and rising upstream material prices, the gross margin of this sector declined year-on-year.
Power battery and energy storage businesses have become the core engines driving revenue. Regarding power batteries, the company's HEV hybrid battery installation volume jumped to first place globally in the second quarter, with 28.36GWh shipments in the first half of the year, revenue reaching 141.34 billion yuan, a year-on-year surge of 85.87%. The energy storage business is also in a period of accelerated scale release, benefiting from the explosion of global AIDC backup power demand, with relevant orders reaching a historical high. However, despite the significant increase in shipments of the power and storage businesses, profits are yet to be realized in the future, affected by industry price wars and high capital expenditures during the scale expansion period.
In the first half of the year, the company's R&D investment reached 23.63 billion yuan, with an R&D expense ratio exceeding 6%, continuously delving into electrochemical basic research and material innovation. At the same time, Phase I of the Thailand base has been put into production, and Phase II has also been launched simultaneously. The Hungary and Vietnam bases are currently in the orderly construction phase, the proportion of overseas customers continues to increase, and the company's profit elasticity is also expected to be released further. However, high R&D investment and globalization layout also test the company's cash flow.
Looking ahead to the second half of the year, Liang Rui, Vice President and Chief Sustainability Officer of Sunwoda Electronics Co., Ltd., stated in an interview with media that the consumer market is basically saturated, and the combined proportion of Sunwoda electric vehicle batteries and energy storage system businesses will exceed that of consumer batteries.
Under industry cycle fluctuations, whether Sunwoda can improve deducted non-recurring net profit, convert the high market share of HEV into more pure electric design wins, and whether AIDC energy storage orders can continue to land, will be the key points to watch for its subsequent breakthrough.
Profited massively, these three words can only describe CATL's performance in the first half of 2026.
On July 24, CATL released its semi-annual financial report. For the first half of 2026, CATL reported operating revenue of 276.917 billion yuan, a year-on-year increase of 54.80%; net profit attributable to shareholders was 43.284 billion yuan, a year-on-year increase of 41.98%; net profit after deducting non-recurring gains and losses was 39.013 billion yuan, a year-on-year increase of 43.44%. This means that regarding the core net profit attributable to shareholders, CATL earned 12.8 billion yuan more than the previous first half! In CATL's hands, cash and equivalents total approximately 340.58 billion yuan.

Looking at business segments, CATL achieved rapid growth in all three business segments. Among them, power battery systems generated revenue of 192.125 billion yuan, a year-on-year increase of 46.02%, accounting for 69.38% of total revenue; energy storage battery system revenue was 53.261 billion yuan, a significant year-on-year growth of 87.54%, accounting for 19.23% of total revenue; battery materials and recycling, mineral resources business revenue was 18.811 billion yuan, a year-on-year increase of 67.23%, accounting for 6.79% of total revenue. It can be seen that energy storage is the engine of CATL's growth this year.

From the perspective of gross margin, the gross margin of the power battery system segment was 20.63%, a decrease of 1.78% compared to the same period last year. The gross margin of the energy storage battery system was 23.96%, also down 1.56% from last year. The gross margin of battery materials and recycling, mineral resources business was 27.04%, an increase of 5.81% compared to last year. From the perspective of domestic and international markets, CATL's gross margin in the domestic market is declining, with a gross margin of 21.16%, down 1.78%. From the international market perspective, the gross margin is far higher than the domestic market, reaching 29.97%, an increase of 0.95% compared to last year.
From a market perspective, CATL's global leading position in power batteries is further strengthened. From January to May 2026, the global power battery market share was 40.2%, an increase of 2.2 percentage points year-on-year; domestic passenger vehicle installation share was 46.7%, an increase of 5.6 percentage points year-on-year, with domestic ternary battery market share reaching as high as 75.2%. Overseas markets broke through simultaneously, with overseas revenue accounting for 31.46% of total revenue, and overseas share steadily rising. Production capacity at overseas bases in Hungary, Spain, Indonesia, etc., continues to be established.

In the energy storage field, according to data from Xinlun Information, the company's energy storage battery shipments ranked first globally from January to June 2026. This is mainly due to AI computing power and new energy grid connection driving the concentrated landing of overseas and domestic energy storage projects. The energy storage side launched the 9MWh ultra-large capacity TENER, 6.25MWh Tianheng liquid-cooled energy storage cabin, and sodium-ion complete station system. Signed a three-year 60GWh sodium-ion energy storage long-term order with Hopeson, and landed large-scale independent energy storage benchmark projects.
Meanwhile, emerging businesses such as battery swapping, low-altitude eVTOL, and ships are being promoted in an orderly manner. Approximately 2,000 "Chocolate" passenger vehicle battery swapping stations have been built nationwide. The company's 5-ton class eVTOL has entered the airworthiness certification phase. Overseas heavy-duty truck battery swapping joint ventures have been established. Overall, currently CATL has sufficient capacity reserves. Existing battery system capacity is 525GWh, under-construction capacity is 764GWh, and capacity utilization rate is 94.86%.

Of course, for CATL, its growing profitability will inevitably attract criticism. This is because, looking at the current industry, the profitability of car companies is relatively too weak. In the first half of 2026, the average profit margin of the whole vehicle manufacturing industry was about 1.5%, creating a new low in nearly ten years. From the disclosed 2026 semi-annual performance forecast, the days of whole vehicle enterprises are clearly not good.
Except for BAIC BluePark forecasting a net profit increase of 14.65%-23.32% year-on-year, several other mainstream car companies showed significant declines: Haima Automobile (000572.SZ) forecast net profit decreased 0.64% to 47.61%, Changan Automobile, Great Wall Motor forecast decline both exceeded 57%, GAC Group forecast decline approached or even exceeded 60%, Seres forecast net profit year-on-year decline was between 151%-161.2%, turning from profit to loss. According to calculations, currently a terminal-priced model costing about 200,000 yuan, net profit per vehicle is only about 3,000 yuan.
Against this background, CATL will undoubtedly once again face the questioning of "car companies working for CATL". In 2025, CATL's operating revenue was 423.702 billion yuan, net profit attributable to parent company was 72.201 billion yuan. In the same year, the combined net profit of the five top car companies BYD, Geely, SAIC, Great Wall, Changan was 73.5 billion yuan, only 1.3 billion yuan more than CATL alone. And in the first quarter of 2026, CATL's net profit attributable to parent company was 20.738 billion yuan, while the combined total of the seven car companies Chery, Geely, BYD, SAIC, Great Wall, Seres, Changan was 17.5 billion yuan, the sum of the seven being less than CATL alone.

In June 2026, CATL Chairman and General Manager Zeng Yuqun, in a media interview, used the photovoltaic industry as a comparison to respond to car companies' complaints about its prices. He stated, "Now the lithium battery industry hasn't met the disastrous result that the photovoltaic industry has now, because CATL is propping up this price. As long as CATL brings the price down, it will be even worse than photovoltaic. Of course, this has not fully quelled outside doubts."
However, CATL also has grievances about the industry status quo. Zeng Yuqun previously stated that many people want to enter the battery industry. The first thing they do is come to CATL to poach talent or steal a bit of technology; then go to equipment manufacturers and material manufacturers, see what formulas they have, then combine them and say they have money to invest, and they get in. Zeng Yuqun pointed out that the imitation level of others (other manufacturers) might only be 60-70 percent, but they use low-price competition.
For example, in the procurement process of some enterprises, some decision-makers are only oriented towards completing current KPI (Key Performance Indicators), while the verification cycle for battery quality is long, and potential defects often appear only after the vehicle has been used for three to five years.
Zeng Yuqun believes that the reason why this low-price competition works is rooted in the impatient mindset and short-sighted behavior of some market participants. He believes that without CATL holding the front, the battery industry would be very chaotic. And looking at it from this perspective, it is actually not unreasonable for CATL, as the leader, to make money. What is scary is that if the leader doesn't make money, then this industry will be in danger.