首頁Pickup

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
According to the latest data from the Thailand Department of Land Transport, in September 2026, Thailand pickup registrations were 11,596, up 4.51% year-over-year; cumulative for Jan-Sept was 112,855, up 5.35% year-over-year, higher than the 107,129 from the same period in 2025. Overall, the pickup market is recovering moderately, but in the face of near 90% year-over-year growth for Pure Electric BEVs, this growth rate is not fast, with its market share dropping to 20.42%.

Most notably, the top two pickup players not only maintained their positions but also expanded against the trend. Toyota Hilux registrations in September were 6,171, up 8.49% year-over-year; cumulative for the first three quarters was 57,769, up 11.21% year-over-year, firmly ranking first in the overall vehicle list. Isuzu D-Max registrations in September were 3,866, up 13.01% year-over-year; cumulative 40,080, up 6.62% year-over-year. Combined, these two models accounted for 86.70% of the pickup market, with concentration increasing further compared to 2025.


The only incremental volume in the industry was mostly taken by the top two. The channel depth, diesel technology reputation, and used car value retention barriers of Japanese brands were strengthened in the existing market competition.

Contrasting with the top two, traditional secondary tier brands almost shrank across the board. Ford Ranger cumulative 7,477, down 11.67% year-over-year; Mitsubishi Triton cumulative 4,562, down sharply 31.65% year-over-year, September single month drop close to 40%; Nissan Navara cumulative 1,044, down 13.86%; MG Extender dropped sharply from 606 to 93, down 84.65% year-over-year; Mazda BT-50 cumulative 61, slight drop 3.17%. The shrinkage of the secondary tier camp is essentially the market space being squeezed continuously by the top two, with the middle ground rapidly hollowing out.

Chinese brands are the only high-growth variable in the rankings. Geely Radar RD6 registrations in September were 178, up 270.83% year-over-year; cumulative 1,549, up 195.05%, rising to fifth in the overall pickup ranking. Great Wall Shanhai Pao POER Sahar cumulative 199, up 503.03% year-over-year; Changan Deep Blue Hunter K50 cumulative 21, up 250%. Combined, Chinese brand pickup registrations for the first three quarters increased from 564 in 2025 to 1,769, up 213.65% year-over-year; September single month increased from 77 to 203, up 163.64%. However, this high growth rate is built on an extremely low base. The combined market share of Chinese brands is only 1.57%, with a huge gap compared to the top two, not yet forming a substantial challenge.

Final Thoughts: The core logic supporting Chinese brand breakthroughs remains electrification. In the first three quarters, Thailand Pure Electric BEV registrations with a 30.04% share surpassed diesel vehicles for the first time. The RD6, which is currently selling well, is exactly a Pure Electric Pickup, competing in a differentiated manner with Hilux and D-Max which still rely mainly on diesel, bypassing their most solid diesel technology barriers. With the increasing acceptance of new energy commercial vehicles, Chinese brands are expected to convert their first-mover advantage in electrification into continuous incremental volume.

However, it must be clearly seen that pickup users highly value reliability, load capacity, and after-sales networks, which are exactly the strengths Japanese brands have developed over decades; whether the high growth rate of Chinese brands can continue requires dual verification from subsequent monthly data and local service capabilities.
Recently, the South African Motor Industry Association (Naamsa) released new car sales data for September 2026. The overall sales of new cars in the South African new car market reached 61,645 units that month, a year-on-year increase of 12.7%; among them, the light commercial vehicle (LCV) sector sales were 14,361 units, a year-on-year increase of 9.6%. As the "basic foundation" of South African car consumption, pickups have the dual attributes of production tools and family vehicles, and their monthly sales rankings have always been regarded as a barometer of the car market.

In September, the total sales of the top 20 pickups in the South Africa sales ranking were about 12,390 units, a month-on-month increase of about 6.1% compared to 11,675 units in August, with market enthusiasm further enhanced compared to August. The biggest highlight of the ranking is that the Isuzu D-Max surpassed the Ford Ranger again after half a year, and the top three positions saw a rare swap.

At the top level, although Toyota Hilux sales dropped 2.9% month-on-month to 3,769 units, it still firmly held the top spot with an absolute advantage of leading the second place by more than 1,200 units. The currently available Hilux is produced by the Durban Prospecton plant, where the eighth and ninth generation models are sold together, and its status as the "King of South African Pickups" remains hard to shake in the short term.

The real contest is between the second and third places. Isuzu D-Max increased by 27.2% month-on-month to 2,551 units, rising to second, including 516 units of government procurement orders, accounting for about two-tenths of its total sales; this is the second time this year it has surpassed Ranger since March. Ford Ranger manufactured by Silverton plant sold 2,502 units, increasing 5.4% month-on-month, setting a new monthly high for many years, but still placed third with a slight gap of 49 units. The two locally made pickups are showing a close combat situation.

In the second tier, Mahindra Pik Up dropped 14.9% month-on-month to 521 units, holding fourth; Great Wall P-Series (including P300 and P500, P500 equipped with all-new 3.0T diesel power) decreased 12.1% month-on-month to 517 units, following closely with a difference of only 4 units, and has firmly held the top spot for Chinese brand pickups for several consecutive months. Volkswagen Amarok rose sharply by 22.5% month-on-month to 430 units, surpassing Toyota LC79 to rise to sixth; Land Cruiser 79 dropped slightly by 3.5% month-on-month to 419 units, falling to seventh.

The competition among other top 10 models is also fierce. JAC T Series increased 3.7% month-on-month to 255 units, rising to eighth; its 360 kW T9 plug-in hybrid version will also be launched soon; Mahindra Bolero increased by 46.8% month-on-month to 226 units, Peugeot Landtrek soared by 55.6% month-on-month to 207 units, both of which have entered the top 10.

Those falling out of the top 10 are Nissan Navara and Foton Tunland. Affected by the suspension of production at Rosslyn plant in May and the production line being handed over to Chery, Navara plummeted 37.2% month-on-month to 184 units, ranking only 11th, resulting in one less seat for Japanese brands in the top 10; and Chery taking over the Rosslyn plant also means that Chinese automakers in South Africa are moving from product exports to production capacity localization. Foton Tunland sales were 179 units, increasing 13.3% month-on-month, ranking 12th.

Other Chinese brands performed steadily overall. BYD Shark 6 increased 23.6% month-on-month to 157 units, JMC Bus also increased 16.2% month-on-month to 151 units, SAIC Maxus T60 increased 6.7% month-on-month to 128 units. Changan Hunter surged 330% month-on-month to 99 units, with the highest increase among the entire ranking; Mitsubishi Triton manufactured in Thailand and Kia Tasman were 53 units and 30 units respectively, both refreshing their best achievements for the year. The 8 Chinese brand pickups listed totaled about 1,495 units, an increase of about 6.8% month-on-month, accounting for more than 12% of the total ranking sales, and are becoming an important force driving market expansion.

Final Thoughts: In September 2026, the South Africa pickup market presented a pattern of "overall recovery, top swap, Chinese brand advance". With Navara local production capacity exiting and plug-in hybrid pickups entering one after another, the ranking battle on this list in the fourth quarter will still be full of uncertainties.


It is worth noting that this new vehicle is not a product independently developed by Honda from scratch, but is expected to adopt Mitsubishi Group as a base, through OEM (Original Equipment Manufacturer) cooperation, with Mitsubishi responsible for production, followed by sales under the Honda badge. Although the official name and design details of the new vehicle have not been announced, for Honda which has long lacked traditional body-on-frame pickup products, this is undoubtedly a strategic shift worth monitoring.
According to information disclosed by Japanese media, Honda is coordinating with Mitsubishi Group to obtain OEM supply of Triton, expected to be produced by Mitsubishi's factory in Thailand and sold in Southeast Asia under the Honda brand. If the plan is successfully implemented, this new Honda pickup could be seen as early as 2028, and may further expand to other overseas markets in the future.

This cooperation method is actually not complicated. Simply put, Mitsubishi is responsible for providing existing mature models, while Honda utilizes its own brand influence and sales network to push the products to the market. For Honda, the biggest benefit is not having to invest a large amount of funds to develop a new pickup platform, while also shortening the time required for new vehicle R&D and market launch.
As for Mitsubishi, supplying Triton to Honda can also help the Thailand factory increase production volume and improve the utilization rate of existing production facilities. Therefore, this cooperation has practical commercial value for both parties. However, current related news still comes from Japanese media reports, and Honda and Mitsubishi have not yet officially announced the final specifications, exterior design, and launch countries of the new vehicle.

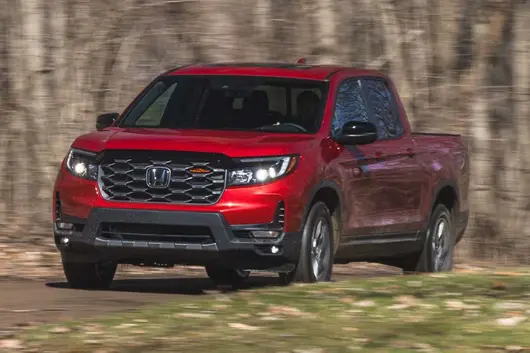
Actually, Honda is not completely without pickup products. The Ridgeline sold by the brand in the North American market is currently a quite special pickup, however, it adopts Unibody body construction design, which has obvious differences from traditional pickups like Toyota Hilux and Mitsubishi Triton.

Adopting Unibody construction design mainly emphasizes daily driving comfort and practicality, not the traditional Ladder Frame structure. The characteristic of Ladder Frame is that the body and chassis adopt a separate structure, which can be reinforced for load capacity, towing, and complex terrain. Therefore, it has long been the main design for traditional pickups. In the Southeast Asian market, especially in Thailand, Malaysia, and Indonesia, such models are popular among off-road enthusiasts and family users in addition to commercial use.
If Honda directly adopts the Mitsubishi Triton platform, it can obtain a ladder-frame chassis, suspension structure, and four-wheel drive technology that has already been validated by the market, without the need to rebuild a complete R&D system. In fact, Honda previously sold a pickup named Tourmaster in Thailand, which was also launched in cooperation with Isuzu. Therefore, this cooperation with Mitsubishi can also be seen as Honda's second attempt to enter the traditional pickup market.

The current Mitsubishi Triton belongs to the sixth generation model, which made its global debut in Thailand in 2023. The new vehicle adopts a newly developed Ladder Frame chassis structure and is upgraded in terms of body rigidity, suspension, and powertrain.
If Honda ultimately adopts the existing Triton powertrain combination, then the new vehicle theoretically has the opportunity to achieve performance that is quite close. However, since the product is expected to be launched as early as 2028, whether it will continue to use the same 2.4L diesel engine, whether power will be adjusted, or whether other power versions will be launched, there is no further news at present. What can be confirmed is that adopting an existing mature platform will allow Honda to significantly lower the threshold for developing traditional pickups, which is also the most important advantage of the cooperation between the two parties.

When talking about the pickup market in Southeast Asia, Toyota Hilux is definitely a name that cannot be ignored. For a long time, Hilux has established a very strong competitiveness in many markets relying on its durability, reliability, well-established after-sales network, and good used car residual value. Besides Hilux, there are also mature rivals such as Isuzu D-MAX, Ford Ranger, and Mitsubishi Triton on the current market. For Honda preparing to join this field, the challenge is obviously not small.
First, traditional pickup buyers attach great importance to the durability, maintenance cost, and long-term usage performance of vehicles. Even though Honda has established a good brand reputation in the passenger car field, it will still take time to let consumers accept a diesel pickup truck hanging the Honda badge.
Secondly, price will also become a key factor. Assuming the Honda version Triton adopts a very close mechanical structure to the original factory model, Honda must establish its own product characteristics through exterior design, interior equipment, driving assistance systems, and price positioning. Otherwise, consumers are likely to directly choose the Mitsubishi Triton.

On the other hand, Honda itself owns a large passenger car customer base, which may also become an advantage for the new vehicle. For consumers who already own Honda City, Civic, or CR-V, if they hope to purchase a vehicle more suitable for cargo, towing, or off-road purposes in the future, they will have another option to stay within the Honda brand.
Therefore, Honda's entry into the pickup market does not represent an ability to immediately shake Hilux's status, but if the product pricing is reasonable and is combined with existing dealer networks, there is indeed a chance to become a new competitor in this market.
August 2026, Australia new car market deliveries reached 108,760 units, up 4.9% year-on-year. Behind the stable figures lies a historic shift in powertrains: 27,078 Battery Electric Vehicles (BEVs) were delivered, surging 169.4% year-on-year. With a market share of 24.9%, BEVs surpassed petrol, diesel, and hybrid for the first time, becoming the top powertrain type in Australia; Plug-in Hybrid Electric Vehicles (PHEVs) also grew 171.1% to 10,591 units. The Tesla Model Y topped the overall model sales list, while BYD secured second place among brands with 8,231 units (+68.8%), making New Energy brands the biggest winners of the month.

As pickups bear heavy-load tasks such as hauling, towing, and off-roading, their requirements for range and power are far higher than ordinary passenger cars; consequently, their electrification lags significantly behind the overall market — but August data shows they can no longer stay isolated.

Toyota Hilux retained the pickup title with 4,833 units, but saw only a slight increase of 0.2% year-on-year, essentially standing still. Ford Ranger suffered a cliff-like drop, delivering only 2,440 units, plummeting 50.6% year-on-year — primarily due to a temporary delivery halt caused by safety concerns with side air curtains, resulting in a monthly loss of about 2,500 units, which is a supply-side shock rather than a demand collapse.

Isuzu D-Max delivered 1,708 units (-26.2%), Mitsubishi Triton 1,161 units (-23.8%), and Mazda BT-50 recorded 804 units (-29.4%); all three Japanese diesel pickups declined by double digits. Volkswagen Amarok 306 units (-27.7%), Nissan Navara 277 units (-53.2%), and Kia Tasman performed the worst with only 312 units, down 61.1% year-on-year.

Pickups manufactured in China continued to expand their presence. BYD Shark 6 led Chinese brand pickups with 1,385 units, followed closely by Great Wall Cannon with 827 units. Adding Maxus LDV pickups (T60 + Terron 9 totaling 423 units), Foton Tunland V7 (124 units), MG U9 (115 units), JAC T9 (77 units), and others, total Chinese pickups reached approximately 2,951 units, accounting for about 18.5% of the Australian pickup market. In contrast, vehicles manufactured in Thailand delivered 15,658 units in August, down 24.7% year-on-year, driven almost entirely by the contraction of the pickup segment — Thailand is the main production base for Japanese pickups.

Amidst the general decline, BYD Shark 6 grew 9.8% year-on-year, reaching a year-to-date total of 12,094 units, becoming one of the few mainstream pickups with positive growth. Its PHEV positioning balances electric driving experience with pickup utility needs, coupled with BYD's strong brand power and more competitive pricing, opening up new volume outside of traditional diesel pickups. Notably, New Energy itself is not a guarantee of growth; brand momentum, pricing, and supply rhythm are key.

The full-size pickup market showed clear divergence. Ford F-150 delivered 152 units (surged from a low base), Chevrolet Silverado 1500 delivered 148 units (-6.9%), and RAM 1500 fell 32.6% to 149 units. Premium pickups above A$100,000 overall grew 18.1% to 764 units, forming a contrast with mainstream market weakness.

Final thoughts: August data clearly shows that even in the pickup segment where electrification is inevitably lagging, traditional fuel powertrains are also feeling a clear chill. Ranger's delivery halt amplified the decline. BYD Shark 6's growth against the trend validated the viability of PHEVs in the pickup market. Chinese brands like Great Wall Cannon, Maxus LDV, and others became an undeniable force in the Australian pickup market through stable sales volumes and forward-looking new energy layouts. With Ranger resuming deliveries in September and more hybrids and EV pickups entering the market, how the Australian pickup landscape will change again remains to be seen.
Recently, an exclusive report from US media sent shockwaves through the global pickup community: Ford is developing a Bronco pickup, while the production prospects of the currently sold Ranger in the US are clouded.

According to the report, Ford "currently has no plans" to produce the next-generation Ranger at the Michigan Assembly Plant in Wayne, Michigan. This factory, which also produces the Bronco SUV and Ranger, is set to transform into an exclusive Bronco production base by around 2030. Taking over the Ranger production line will be a midsize pickup based on Bronco, expected to launch between 2029 and 2030.

However, there is disagreement among media outlets regarding whether Ranger will stay or go in the US. Some believe Ranger will be completely discontinued and directly taken over by the Bronco pickup; others believe Ranger will be relocated to the Blue Oval City plant in Tennessee and continue to exist in a new generation by 2029 - Ford has confirmed it will produce a fuel pickup with a size close to Ranger in Tennessee, but has not specified if it will still be called Ranger. Industry forecasting firms judge: A Bronco-styled midsize pickup will replace Ranger at the Michigan plant in fall 2029.

In response to the reports, Ford's official response was vague, stating only that they do not comment on "future product speculation, much of which is inaccurate".
In April 2026, Ranger US sales volume was only 5,245 units, a year-on-year plunge of 25%, even being surpassed by Mustang; while the Bronco brand's sales volume in Q3 2025 grew 41.3% year-on-year, achieving its best quarterly performance in history. Using a high-premium Bronco pickup to replace the weak-selling Ranger makes complete financial sense.

For overseas consumers, the biggest concern is whether US market changes will affect the global market. The answer is: Ranger is basically unaffected. Ranger is a true global model, with independent production lines set up in Thailand, South Africa, Argentina, etc., supplying Southeast Asia, Australia, Europe, Africa, and South American markets. The US Michigan plant only supplies North America; its production line adjustments have no direct relation to overseas Ranger.
However, the situation for the Bronco pickup is different. The Bronco brand has accelerated its global expansion in recent years, and Bronco SUVs have already entered markets like Europe and Australia. If the Bronco pickup succeeds in the US, Ford is very likely to push it overseas, forming a "two-car strategy" with Ranger - Ranger focuses on utility attributes and value for money, while the Bronco pickup focuses on off-road lifestyle and brand premium. The two cover different groups, rather than simple substitution.

Final Thoughts: The changes surrounding the Ranger and Bronco pickups are currently still in the rumor and prediction phase. What is certain is: the Bronco pickup is on the way, and the Michigan plant will turn into an exclusive Bronco base; what is not yet determined is whether Ranger will be completely discontinued in the US or continue at another plant. For overseas markets, Ranger's production line independence means it will not be impacted in the short term; but in the long term, the globalization of the Bronco pickup may change the global midsize pickup competitive landscape, complementing rather than substituting Ranger. In 2029, everything will be revealed.
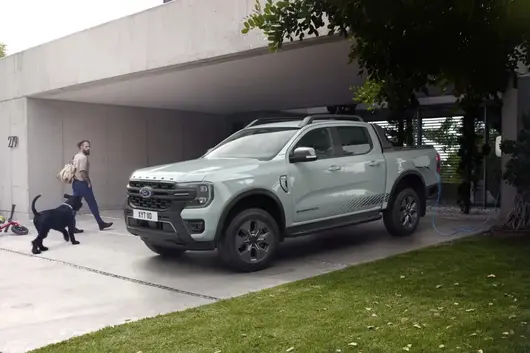
In July 2026, the Thailand pickup market totaled only 11,134 units for the month, continuing a weak trend. Toyota Hilux TRAVO/REVO secured the top spot with 5,358 units, holding a 48.1% share, accounting for nearly half the market; Isuzu D-Max sold 3,803 units, with a 34.2% share. The two Japanese brands combined accounted for over 82% share, and the dual oligopoly structure remains stable.

Internally, the Toyota Hilux series shows "concurrent operation of commercial and passenger lines": Travo commercial version sold 3,242 units, Revo passenger version sold 2,116 units; the former has a base advantage, while the latter's continued sales volume reflects that demand for high-end passenger pickups has not completely disappeared. Hilux Champ ranked fourth with 479 units, a 4.3% share, complementing Travo as a product.

Isuzu D-Max remains firmly in second place, locking the top 2 positions with Toyota. Ford Ranger sold 568 units ranking third, with a 5.1% share, securing its place among American pickups; Mitsubishi Triton sold 403 units ranking sixth, with a 3.6% share.

What is worth noting is the performance of new energy pickups. Geely Radar (GEELY Radar) ranked fifth with 409 units, a 3.7% share, surpassing Mitsubishi Triton to become the largest pure electric pickup in July sales. King Long Dracon sold 16 units, Foton e-Tunland sold 10 units, Deepal Hunter K50 sold 3 units. Chinese brands have formed a cluster effect in the pure electric pickup track. Although the overall share of pure electric pickups is still less than 4%, in the context of the continuous decline of traditional fuel pickups, electrification may be a key variable to break the Japanese monopoly.

July's slump was not accidental. Suwat, Vice Chairman of the Federation of Thai Industries and Chairman of the Automotive Industry Group (AIC), had previously warned: In 2025, the proportion of Thailand's pickup sales to the overall market dropped to 23%, a historic low. Between 2010 and 2022, this proportion remained at around 45% for a long time. In 2023, it dropped to 34% (about 265,000 units), in 2024 it fell to 23% (about 163,000 units), and in 2025 it remained at 23% but the absolute volume dropped to about 144,000 units.

High household debt, rising non-performing loans, and weak domestic purchasing power are the core reasons for the continuous pressure on the pickup market. AIC urged the government to introduce stimulus policies as soon as possible, because the localisation rate of the pickup industry is as high as 90%, covering more than 2,500 parts suppliers. Market contraction will have a chain impact on the entire supply chain.

Exports are also under pressure. Affected by the Middle East situation, Thailand's car exports declined by more than 20% in the past two months. From January to May 2026, Thailand exported 49,961 cars to the Middle East, a year-on-year drop of 30.4%. The Middle East is Thailand's third-largest export market, accounting for 20% of total exports in 2025. Four-door pickups and PPVs (pickup-derived SUVs) are their main demand products. Combined with weak domestic demand, Thailand's pickup industry is facing a dual squeeze.

Final Thoughts: July data once again confirms that the downward trend of the Thailand pickup market has not bottomed out. The dual oligopoly structure of Toyota and Isuzu is difficult to shake in the short term, but Chinese pure electric pickups represented by Geely Radar are quietly accumulating momentum. How to find a balance between domestic demand stimulus, export diversification, and electrification transformation will be the key to determining whether the Thailand pickup market can emerge from the valley.
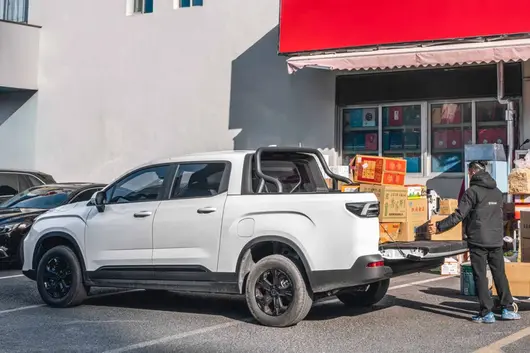
When we see overseas pickup modifications or designs, we always sigh, why haven't domestic pickup companies officially launched these cars? Actually, domestic car companies also have a deep understanding of pickup modifications, but constrained by various regulations, many very interesting models cannot be mass-produced, which is indeed a pity. However, I believe that with the progress and iteration of regulations, these types of vehicles will eventually gain recognition from the management and be legally allowed on the road. So today let's take a look at what very interesting but not mass-produced pickup products there are domestically.

3 Types of 6-Wheel Pickups:
BJ80 6x6 Pickup Version, Wuling Hongguang MINI EV 6-Wheel Pickup, Great Wall Cannon CYBERP!CKUP Chaojing Co-Creation Edition
In the past when domestic pickups were not blooming everywhere, when we saw high-definition large pictures of those overseas high-performance cars, Mercedes-Benz 6x6 often appeared. This pickup almost became the ultimate dream model for many people, little did we know that multiple 6x6 pickup products had also appeared in our country.
The earliest one is the BJ80 6x6 pickup from Beijing Automotive Group at that time. At the 2018 Beijing Auto Show, BAIC launched this tall and mighty pickup built on the BJ80. It added a rear axle on the original car basis, and the rear part was changed to an open cargo box style, becoming a 6-wheel pickup. The power part adopts a plug-in hybrid system. The last axle is driven by a motor, but there is also a drive shaft from the middle axle to the last axle. Moreover, all wheels of this car used portal axles to increase ground clearance. The rear two axles use a helical spring multi-link structure. The car attracted many people's attention at the auto show scene at that time, but based on the market situation at the time, it was destined to be just for display purposes and cannot be mass-produced.


At the 2020 Chengdu Auto Show, another 6x6 pickup product appeared, and this car was even less likely to be mass-produced than the previously introduced BJ80 6x6. It is the Wuling Hongguang MINI EV Special Edition. This is because Wuling Hongguang MINI EV was sold extremely hotly that year, it is an absolute internet-famous product. So Wuling took advantage of the heat and jointly launched this 6-wheel heavily modified pickup with a modifier, used for promotion and attraction at the auto show.


This small 6-wheel pickup added a cargo box design on the original car basis, and to carry this cargo box, an axle was added directly to the rear, forming the form of a 6-wheel pickup. From the chassis form, this car still retains the original drive form, "middle axle" motor drive. With such a small volume and load capacity, it is absolutely impossible to mass-produce.

The most hopeful mass production one is the Great Wall Cannon 6x6 model CYBERP!CKUP co-created with Chaojing launched by Great Wall Cannon at the 2023 Shanghai Auto Show. This car is said to come from the first Chinese 6X6 super off-road platform built by Great Wall, which will break the situation of foreign enterprises dominating 6x6. This car is equipped with a 3.0T V6+9HAT hybrid system, outputting 260kW/500N・m, pure electric range 110km (CLTC), comprehensive fuel consumption 8.5L/100km. In terms of off-road configuration, standard equipment includes 5 electronic differential locks, all-terrain adaptive system can realize 8 road conditions, and equipped with 33-inch Cooper AT3 tires. Because it is a hybrid model, considering battery safety, the battery group is 750mm off the ground to prevent collision, and the vehicle can also achieve 3.3kW external discharge to meet camping power consumption.


Whether looking from the publicity direction, or from the so transparent release of specific vehicle parameters, Great Wall obviously intended to mass-produce it; but to this day there is no specific mass production news, which is bound to make people regret.
Great Wall Cannon Hypercar Pickup
As the leader of domestic pickups, Great Wall Pickup is absolutely all-around in "showcasing creativity". Previously we introduced 6-wheel pickups, and at the 2021 Guangzhou Auto Show, a Great Wall Cannon Hypercar Pickup was also launched. So Great Wall Pickup has not only products in the "off-road performance direction", but also works in the "track performance direction".

This Hypercar Pickup also had a naming activity at that time, expected to be listed in the "Bullet" series. The car has an ultra-wide widebody kit, and the body height is reduced, presenting a low-slung style overall. This modification style has relatively faithful fans in Thailand, and its appearance in China is the top pickup modification. The engine hood middle part rises, with air intake holes. The front bar, wheel arches, side skirts, and rear are equipped with widebody kits, making the horizontal visual of the whole car look very wide. Front and rear wheels also adopted the multi-spoke style commonly used in performance cars, matched with 285/40R22 tires, and the front wheels have a slight outward angle, improving the cornering stability of the whole vehicle.


The rear cargo box of the vehicle has a sports roll cage, and there is also a spoiler commonly used in performance cars on the top and above the tailgate, plus a huge diffuser in the middle of the rear bar, giving the whole car better aerodynamic structure and also more aesthetically pleasing. The bottom of the cargo box has a huge dual-side dual-out exhaust, looking full of performance. If this car can be mass-produced, it will definitely be a very personalized product in the performance car field, and will definitely expand influence, bringing pickups into the market of track performance cars.


Jiangxi Isuzu Fulfiller (D-MAX Modified Crawler Vehicle)
In addition to domestic brands, joint-venture pickups have also launched some interesting products in China. D-MAX has always been a favorite of many off-road players. Even if the manufacturer does not launch modified cars, there are also many experts in the civilian sector modifying D-MAX that look very good. But the manufacturer still wants to build a brand image in terms of off-road, so D-MAX modified cars can often be seen at auto shows.

At the 2020 Chengdu Auto Show, Jiangxi Isuzu displayed a D-MAX track vehicle, named Fulfiller. The upper part of the whole vehicle basically has no big change, the shape still retains the factory design. A luggage rack was added to the roof, a gantry was added to the rear, and there is a snorkel on the right, very much off-road style. The place that makes it more "wild" is mainly the lower part.


The tire part was directly changed to tracks, increasing the contact area with the road surface, making the vehicle less prone to getting stuck. The track wheels are directly connected on the factory flange, with a huge gear shape driving the tracks to roll. The fixing device of the tracks is connected to the suspension. Such a design should have greater usage value in mud and snow, and the visual impact is also comparable to 6-wheel pickups. If this pickup can really be mass-produced, then this car should be often seen galloping in the winter of the northern grasslands.

Summary:
It is not that domestic enterprises do not have innovation and creativity awareness, from the above models, it can be seen that pickups still have huge potential in modification, and modifications in all directions can extend imaginative schemes. But due to restrictions in various aspects, it led to these cars not being able to go from the showroom to mass production, which is also a very regrettable thing. Do you think these pickups are interesting? Welcome to discuss with us in the comments section.
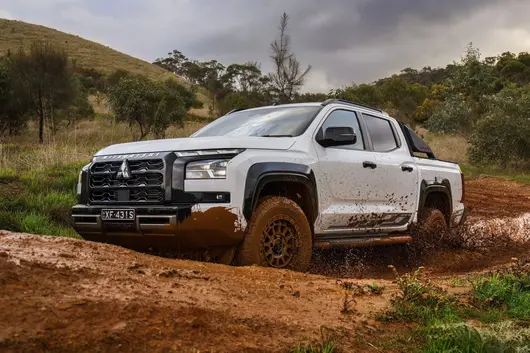
The electrification transformation of mainstream Japanese pickups has finally taken a substantial step. Recently, according to foreign media reports, Mitsubishi Motors has confirmed the launch of a hybrid version of the Triton pickup, this model will go into mass production along with the new Pajero hybrid SUV through the electrification upgrade of its Thailand production base. For this, Mitsubishi plans to add a 16 billion baht investment in the Thailand factory, aiming to build it into a global export hub for electrified pickups and rugged SUVs by 2030.

The first mass-produced version will be the HEV (Hybrid Electric Vehicle) version of the Triton, subsequently, further progress will be made on the R&D of PHEV (Plug-in Hybrid Electric Vehicle) and even fully electric pickups based on battery technology iterations and global market demand. Mitsubishi Global Engineering and Product Strategy Head previously clearly stated, the hybrid solution can be directly compatible with the existing body-on-frame platform, requiring no large-scale modifications to the chassis or underframe structure, resulting in lower short-term implementation costs, and better ensuring the heavy-load capacity and off-road reliability of the pickup models, making it the most pragmatic technical path at present.

Notably, Mitsubishi did not adopt the e-Power extended-range technology from alliance partner Nissan, instead choosing to independently develop a hybrid system exclusive to pickups, the core purpose is to retain the core performance attributes of rugged pickups, avoiding sacrificing load capacity, towing capability, and off-pavement adaptability due to electrification.

Mitsubishi's acceleration of pickup electrification is essentially a market choice forced by the wave of Chinese new energy pickups going overseas. Taking Australia, a global core pickup market, as an example, in 2025 the Mitsubishi Triton sales ranked 17th; while the BYD Shark 6 plug-in hybrid pickup caught up in just one year, ranking 18th. Apart from BYD, the Great Wall Cannon Alpha plug-in version has also landed in the Australian market, combined with the entry of the Ford Ranger plug-in version, the Australian pickup market originally monopolized by diesel power has seen electrification competition fully start.

Unlike Chinese brands that generally prioritize layouts of plug-in hybrids and pure electric routes, Mitsubishi chooses to enter the pickup track from hybrid electric, which fits the core demands of traditional pickup users for reliability and low operating costs, and also avoids the pain points of insufficient charging infrastructure in remote mining areas and off-road scenarios. However, this conservative route also faces challenges: current Chinese brand plug-in hybrid pickups have already achieved technical advantages of all-electric range over 100 km and combined range exceeding 1,000 km, price ranges continue to drop, further squeezing the survival space of traditional diesel pickups.

Conclusion: For Mitsubishi, electrification upgrades are not only a mandatory choice to respond to global emission regulations but also a core layout to resist the overseas expansion of Chinese pickups. With the promotion of the Triton hybrid version, the global mid-size pickup market will welcome a direct confrontation between Japanese hybrids and Chinese plug-in hybrids. The debate on pickup electrification technical routes will also extend from sales competition at the market end to the long-term game of technical paths.
Under the combined pull of new energy transition and growth in overseas demand, pickup market sales grew steadily. Wholesale data from China Passenger Car Association (CPCA) shows (including exports), from January to June 2026, cumulative pickup sales in China reached 343,000 units, a year-on-year increase of 11.9%, among which exports were 188,000 units, up 34% year-on-year. The overseas sales share rose to 55%, becoming an important engine driving overall growth; cumulative new energy pickup sales reached 45,000 units, a slight increase of 8% year-on-year.

In terms of corporate performance, the top 10 pickup manufacturers in the first half of 2026 showed distinct differentiation. Great Wall Motor sold a total of 92,512 pickups, a slight year-on-year decline of 3.9%, but remained number one in the industry. SAIC Maxus accumulated 36,804 units, up 28.1% year-on-year, rising from third place last year to second. Changan Automobile totaled 35,734 units, up 43.9% year-on-year, ranking rising to third in the industry. JAC and Zhengzhou Nissan had similar sales volumes, ranking fourth and fifth respectively. Among them, Zhengzhou Nissan led the top ten industry enterprises with a 51% year-on-year increase.
JMC ranked sixth with 28,704 units, and Foton ranked seventh with 23,288 units; BYD sales were 20,037 units, ranking eighth; Radar New Energy sales were 11,111 units, up 40.5% year-on-year, surpassing Jiangxi Isuzu to take ninth and tenth seats respectively.
Compared to the list from the same period last year, market positions showed significant adjustments. Companies that expanded overseas early and had complete new energy products achieved rapid growth. Brands focusing mainly on the domestic fuel market and with lagging transformation progress faced sales pressure. The pickup industry competitive landscape is undergoing a structural adjustment.
In the first half of 2026, pickup wholesale sales in China generally rose. As the industry leader, Great Wall Motor sold a total of 92,512 pickups in the first half. Despite a 3.9% year-on-year decline, it still ranks first in the industry with absolute advantage. As a leading domestic pickup brand, Great Wall Motor relies on a full series product layout in the 70,000-300,000 price range, advancing together in commercial, passenger, off-road, new energy, and export fields, building a systemic advantage.

SAIC Maxus, ranked second, sold a total of 36,804 pickups in the first half, up 28.1% year-on-year, rising from third place in the industry last year to second. The continuous expansion of export advantages was key to SAIC Maxus's ranking leap. In May, the pickup export scale reached first place in the industry. The monthly sales in June reached 7,871 units, up 83% year-on-year, leading the growth speed in the domestic pickup sub-sectors.
Changan Automobile's market performance was equally bright. Cumulative pickup sales in the first half reached 35,734 units, up 43.9% year-on-year, jumping from sixth place in the industry last year to third. In March, Changan pickup monthly sales exceeded 10,000 units, up 112.4% year-on-year; June sales reached 6,595 units, up 42.7%. The launch of new products such as Changan Hunter K50, combined with continuous expansion of the export market, jointly drove the rebound of Changan pickups.
JAC Pickup, ranked fourth, sold 33,188 units in the first half, a slight increase of 0.8% year-on-year. Long-term deep dive into agriculture, forestry, engineering, and commercial sub-sectors, stable existing customers, but new energy model iteration speed is relatively slow, insufficient new volume support, exiting the top three in the industry.
Zhengzhou Nissan ranks fifth in the industry. Sales were 32,987 units in the first half, up 51% year-on-year. The brand concurrently advanced off-road, new energy, and internationalization layouts. Updated King Ray and Navara fuel models within the year; launched Fengtian plug-in hybrid and Ruiqi pure electric pickups to perfect the power matrix; new energy model sales increase was prominent, Fengtian series went overseas in batches and secured orders from multiple South American countries. Products and overseas channels jointly drove sales growth.

JMC sold 28,704 pickups in the first half, up 1.0% year-on-year. Ranking dropped from fourth place last year to sixth. In the first half, JMC launched two core models: the brand new Baodian and Dadao. But it did not reverse the market landscape. The brand new Baodian faces intense price competition in the commercial tool vehicle market; although the Dadao series saw obvious product capability upgrades, the launch time was late, combined with poor export performance, overall sales faced pressure.
Foton Motor sold 23,288 pickups in the first half, up 21.6% year-on-year, ranking seventh. Exports became the main driver of Foton pickup growth. Public data shows that from January to May 2026, pickup exports exceeded 15,000 units, growing rapidly year-on-year, focusing on deepening regional markets such as Latin America, Africa, and Oceania.
BYD sold 20,037 pickups in the first half, down 25.8% year-on-year. Ranking dropped from fifth place last year to eighth. As a new entrant in the pickup industry, BYD previously relied mainly on overseas exports to drive sales, but since 2026, competition in export markets has intensified. Combined with its "Shark" pickup not yet scaling up domestically, overall sales faced pressure. However, from a new energy dimension, BYD remains an important force in the pickup market. In June, new energy pickup overseas sales reached 4,000 units, maintaining leadership in the new energy pickup sub-sector.

Radar New Energy, under Geely, sold 11,111 pickups in the first half, up 40.5% year-on-year, surpassing Jiangxi Isuzu to rise to ninth place in the industry. This year, Geely Radar launched the King Kong EV pure electric pickup, supplying nationwide markets for commercial scenarios such as agriculture, forestry, and urban-rural distribution. It simultaneously laid out Thailand and Philippines overseas markets, achieving continuous rise in sub-sector market share.
Jiangxi Isuzu sold 11,008 pickups in the first half, a slight decrease of 0.8% year-on-year, falling back to tenth place in the industry. Jiangxi Isuzu relies on diesel hard-core pickups to stabilize engineering and off-road fixed customers, but development has multiple constraints: vehicle iteration update rhythm is relatively slow, new energy model implementation progress lags behind peers, meanwhile product pricing lacks competitiveness, lacking effective volume support, overall growth space is hard to open.
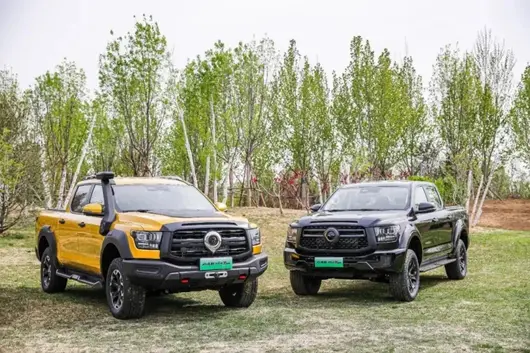

Owl Auto News (ID:owlauto) reported that recently, Geely Auto issued an announcement, stating an investment of approximately 218 million yuan to fully acquire Radar Auto (Shandong) Co., Ltd., Radar Auto Sales Co., Ltd., and the Thailand distribution company Radar Thailand. Among them, Zhejiang Jirun acquired 100% equity of Radar Auto (Shandong) for 159 million yuan, Geely Sales acquired all equity of Radar Auto Sales for 59 million yuan, and CIL and GAIL under Geely acquired all share capital of Radar Thailand totaling 490,000 yuan. After the transaction, the three companies officially became wholly-owned subsidiaries of Geely Auto, with financial performance merged into the listed company's reports, marking the formal transfer of Radar Auto from the Geely Holdings system to the unified control of the Geely Auto listed company.

It is reported that the three targets form the complete chain of the Radar brand from R&D and manufacturing to sales and distribution. Specifically, Radar Auto (Shandong) is the core operating entity of the brand, specializing in R&D and manufacturing of mid-to-high-end new energy pickups, with production bases located at Zibo Zichuan Smart Factory; Radar Auto Sales is responsible for domestic sales system operation and dealer layout; Radar Thailand was established in Thailand in July 2024, it is Radar's first independently operated overseas subsidiary, focusing on distribution in the Thai and Southeast Asian markets.
In terms of performance, the three companies showed significant divergence in 2025. Radar Auto (Shandong) turned from profit to loss, with a net loss of 8.646 million yuan, compared to a profit of 67.743 million yuan in the same period last year; Radar Auto Sales turned loss to profit, with net profit of 12.325 million yuan, compared to a loss of 118 million yuan in the same period last year; Radar Thailand expanded losses, with a net loss of 10.697 million yuan. Despite this, Radar Auto's full-year sales in 2025 still reached 13,040 units, achieving year-on-year growth, ranking high in market share in the domestic new energy pickup market. At the March 2026 Bangkok International Motor Show, Radar King Kong EV received 2,569 orders, a year-on-year increase of 283%.
For Geely, this integration is a key layout to cope with intense industry competition. Radar can share Geely's R&D system, Geely Thunder EM-P super electric hybrid technology, supply chain and manufacturing bases, effectively reducing costs; Geely can coordinate multi-brand planning, avoid internal competition, while integrating Radar's domestic and international full-channel resources, leveraging the opportunities in the new energy pickup sector, further perfecting its global new energy vehicle landscape. As for whether this acquisition will ultimately bring good results to Geely as expected, it will take time to give an answer.
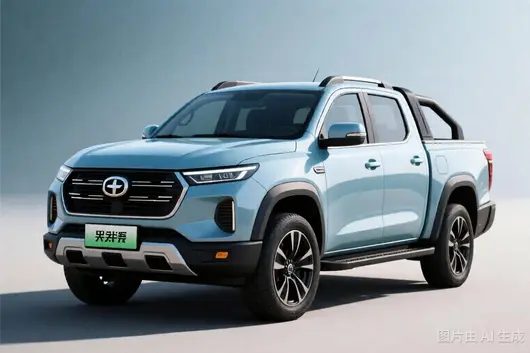
Owl Auto News (ID:owlauto) reported that recently, Geely Auto issued an announcement, stating an investment of approximately 218 million yuan to fully acquire Radar Auto (Shandong) Co., Ltd., Radar Auto Sales Co., Ltd., and the Thailand distribution company Radar Thailand. Among them, Zhejiang Jirun acquired 100% equity of Radar Auto (Shandong) for 159 million yuan, Geely Sales acquired all equity of Radar Auto Sales for 59 million yuan, and CIL and GAIL under Geely acquired all share capital of Radar Thailand totaling 490,000 yuan. After the transaction, the three companies officially became wholly-owned subsidiaries of Geely Auto, with financial performance merged into the listed company's reports, marking the formal transfer of Radar Auto from the Geely Holdings system to the unified control of the Geely Auto listed company.
It is reported that the three targets form the complete chain of the Radar brand from R&D and manufacturing to sales and distribution. Specifically, Radar Auto (Shandong) is the core operating entity of the brand, specializing in R&D and manufacturing of mid-to-high-end new energy pickups, with production bases located at Zibo Zichuan Smart Factory; Radar Auto Sales is responsible for domestic sales system operation and dealer layout; Radar Thailand was established in Thailand in July 2024, it is Radar's first independently operated overseas subsidiary, focusing on distribution in the Thai and Southeast Asian markets.
In terms of performance, the three companies showed significant divergence in 2025. Radar Auto (Shandong) turned from profit to loss, with a net loss of 8.646 million yuan, compared to a profit of 67.743 million yuan in the same period last year; Radar Auto Sales turned loss to profit, with net profit of 12.325 million yuan, compared to a loss of 118 million yuan in the same period last year; Radar Thailand expanded losses, with a net loss of 10.697 million yuan. Despite this, Radar Auto's full-year sales in 2025 still reached 13,040 units, achieving year-on-year growth, ranking high in market share in the domestic new energy pickup market. At the March 2026 Bangkok International Motor Show, Radar King Kong EV received 2,569 orders, a year-on-year increase of 283%.
For Geely, this integration is a key layout to cope with intense industry competition. Radar can share Geely's R&D system, Geely Thunder EM-P super electric hybrid technology, supply chain and manufacturing bases, effectively reducing costs; Geely can coordinate multi-brand planning, avoid internal competition, while integrating Radar's domestic and international full-channel resources, leveraging the opportunities in the new energy pickup sector, further perfecting its global new energy vehicle landscape. As for whether this acquisition will ultimately bring good results to Geely as expected, it will take time to give an answer.
In April 2026, the Thailand automotive market presented an extreme polarization pattern: total new car sales 48,394 units, year-on-year growth 2.54%, pure electric vehicle sales surged 90.61%, SUV year-on-year growth 23.91%, but one-ton pickup sales were only 9,950 units, plummeting 29.7% from March, down 5.84% year-on-year, becoming the only core sub-segment with negative growth. Thus, January-April 2026 Thailand pickup cumulative sales 48,802 units, the decline compared to the same period last year widened further, the annual target of 171,000 units (2024 new low) predicted by ttb analytics was precarious, actual sales are highly likely to drop below 165,000 units.

Although the duopoly structure has not shaken, the 'precipitous' drop of top models is no longer in doubt. Toyota Hilux Travo/Revo April sales 5,104 units, down 27.1% from previous month, January-April cumulative 23,098 units, market share slightly rose to 51.3%; Isuzu D-MAX followed closely, April sales 3,469 units, plummeted 25.2% from previous month, cumulative 17,760 units, market share 34.9%. The two Japanese brands combined still accounted for 86.2% of the share, but the significant shrinkage in absolute sales indicates that even top products with the most complete dealer networks and highest residual values cannot withstand systemic risks.

The rest of the traditional fuel brands suffered a complete defeat: Ford Ranger nearly halved month-on-month, Mitsubishi Triton plummeted 63.7%, Nissan Navara has basically withdrawn from mainstream competition.

Chinese brand performance showed significant divergence. Pure electric pickup leader Geely Radar RD6 April sales 85 units, down 24.8% month-on-month, but the drop was far smaller than most fuel models, January-April cumulative 327 units, continued to hold the top spot among Chinese brands and the first place in the pure electric pickup sub-market. Great Wall Cannon Sahar became one of the few models growing against the trend, April sales 34 units, surged 142.9% month-on-month, but the base was extremely low and scale has not yet formed. Other Chinese brands continued to face pressure: Foton e-Tunland down 61.5% month-on-month, MG Extender plummeted 71.4%.

This divergence between pickups and the overall Thailand car market is essentially the conflict between production tool attributes and consumption upgrade trends, compounded by multiple policy and economic shocks:


Final Thoughts: Looking forward, the turning point for the Thailand pickup market has yet to appear, the golden age of traditional diesel pickups has ended. Low-carbon transformation has become the only way out for the industry, and Chinese new energy pickups represented by Radar RD6, with differentiated product positioning and technical advantages, are expected to seize the initiative during the market restructuring process, becoming a key force to break the long-term Japanese monopoly structure.