首頁Navara

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
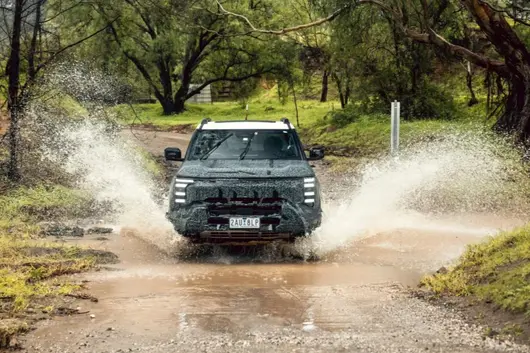
Nissan Australia officially confirms the all-new Navara Pro plug-in hybrid version will land in Australia in 2027. This is Nissan's first new energy pickup and first plug-in hybrid model locally, with Australasia being one of the first right-hand drive markets globally.

Although the new car retains the "Navara" name, it is almost unrelated to the diesel Navara currently on sale, jointly developed by Nissan and Dongfeng, with the domestic counterpart being the Zhengzhou Nissan Frontier Pro PHEV.

But Nissan emphasizes the Australian version is not simply imported from China: powertrain, suspension, driver assistance, terrain modes, tires, differential locks, and towing capacity were all evaluated by the Australasia team. Choosing the 2.0T instead of 1.5T was also a conclusion after local road testing. Five prototype cars completed approximately 20,000 kilometers of cumulative road testing in Australia. Nissan Oceania General Manager Millett stated: "Australia is not only where we test this car, but also one of the markets that help shape it."

Regarding power, the Frontier Pro currently sold in China is 1.5T; the 2.0T version was declared in the Ministry of Industry and Information Technology's 411th batch announcement in September, adopting P2 architecture, with the motor located between the engine and transmission, matched with a ZF 8HAT dedicated hybrid transmission, sharing the same origin as the Australian version. Under P2 architecture, the motor and engine drive in parallel, providing more persistent power for climbing with full load and long-distance towing, while the 8-speed gearbox balances creep and cruising. Battery capacity, pure electric range, and charging speed have not yet been announced.

Off-roading is another key focus: mechanical four-wheel drive plus mechanical differential locks, Nissan calls it "first and foremost a true four-wheel drive work vehicle". The vehicle offers four driving modes and seven terrain modes including deep snow, mud, sand, rocks, wading, etc., supports external discharge (V2L), allowing camping and work to take power directly. Whether the rear suspension uses leaf springs or multi-link coil springs will be finalized before launch.

Target payload and towing are 1000kg and 3500kg respectively, aiming at traditional diesel pickups; the domestic 2.0T declared version has a rated payload of only 490kg and a maximum trailer weight of 3300kg, with significant calibration differences.
Competitor power outputs are no weaker: BYD Shark 6 high-end version is 350kW, 700Nm, JAC Hunter up to 360kW, 1010Nm, Great Wall Cannon PHEV is 310kW, 750Nm, Ford Ranger Hybrid is 207kW, 697Nm; Competitor payloads are mostly between 685 to 901kg, 3500kg towing is already standard, one ton payload is precisely Nissan's breakthrough point.

The new car features a five-seat double-cab cabin, offering a large central control screen, full LCD instrument cluster, panoramic sunroof, and front seats with heating and ventilation; interior sound insulation and materials have been upgraded, positioning it towards passenger car use. The vehicle is manufactured in Zhengzhou and will be sold alongside the fourth-generation diesel Navara manufactured in Thailand. Authorized dealers offer 10-year or 300,000-kilometer conditional warranty for maintenance, with configurations and prices to be announced before launch.

Final Thoughts: Nissan's new plug-in hybrid pickup is not simply imported from China, but uses Dongfeng's new energy foundation to make up for shortcomings, while using local calibration to maintain towing and off-road capabilities. The 2027 Australian new energy pickup battle has just begun.
Under the combined pull of new energy transition and growth in overseas demand, pickup market sales grew steadily. Wholesale data from China Passenger Car Association (CPCA) shows (including exports), from January to June 2026, cumulative pickup sales in China reached 343,000 units, a year-on-year increase of 11.9%, among which exports were 188,000 units, up 34% year-on-year. The overseas sales share rose to 55%, becoming an important engine driving overall growth; cumulative new energy pickup sales reached 45,000 units, a slight increase of 8% year-on-year.

In terms of corporate performance, the top 10 pickup manufacturers in the first half of 2026 showed distinct differentiation. Great Wall Motor sold a total of 92,512 pickups, a slight year-on-year decline of 3.9%, but remained number one in the industry. SAIC Maxus accumulated 36,804 units, up 28.1% year-on-year, rising from third place last year to second. Changan Automobile totaled 35,734 units, up 43.9% year-on-year, ranking rising to third in the industry. JAC and Zhengzhou Nissan had similar sales volumes, ranking fourth and fifth respectively. Among them, Zhengzhou Nissan led the top ten industry enterprises with a 51% year-on-year increase.
JMC ranked sixth with 28,704 units, and Foton ranked seventh with 23,288 units; BYD sales were 20,037 units, ranking eighth; Radar New Energy sales were 11,111 units, up 40.5% year-on-year, surpassing Jiangxi Isuzu to take ninth and tenth seats respectively.
Compared to the list from the same period last year, market positions showed significant adjustments. Companies that expanded overseas early and had complete new energy products achieved rapid growth. Brands focusing mainly on the domestic fuel market and with lagging transformation progress faced sales pressure. The pickup industry competitive landscape is undergoing a structural adjustment.
In the first half of 2026, pickup wholesale sales in China generally rose. As the industry leader, Great Wall Motor sold a total of 92,512 pickups in the first half. Despite a 3.9% year-on-year decline, it still ranks first in the industry with absolute advantage. As a leading domestic pickup brand, Great Wall Motor relies on a full series product layout in the 70,000-300,000 price range, advancing together in commercial, passenger, off-road, new energy, and export fields, building a systemic advantage.

SAIC Maxus, ranked second, sold a total of 36,804 pickups in the first half, up 28.1% year-on-year, rising from third place in the industry last year to second. The continuous expansion of export advantages was key to SAIC Maxus's ranking leap. In May, the pickup export scale reached first place in the industry. The monthly sales in June reached 7,871 units, up 83% year-on-year, leading the growth speed in the domestic pickup sub-sectors.
Changan Automobile's market performance was equally bright. Cumulative pickup sales in the first half reached 35,734 units, up 43.9% year-on-year, jumping from sixth place in the industry last year to third. In March, Changan pickup monthly sales exceeded 10,000 units, up 112.4% year-on-year; June sales reached 6,595 units, up 42.7%. The launch of new products such as Changan Hunter K50, combined with continuous expansion of the export market, jointly drove the rebound of Changan pickups.
JAC Pickup, ranked fourth, sold 33,188 units in the first half, a slight increase of 0.8% year-on-year. Long-term deep dive into agriculture, forestry, engineering, and commercial sub-sectors, stable existing customers, but new energy model iteration speed is relatively slow, insufficient new volume support, exiting the top three in the industry.
Zhengzhou Nissan ranks fifth in the industry. Sales were 32,987 units in the first half, up 51% year-on-year. The brand concurrently advanced off-road, new energy, and internationalization layouts. Updated King Ray and Navara fuel models within the year; launched Fengtian plug-in hybrid and Ruiqi pure electric pickups to perfect the power matrix; new energy model sales increase was prominent, Fengtian series went overseas in batches and secured orders from multiple South American countries. Products and overseas channels jointly drove sales growth.

JMC sold 28,704 pickups in the first half, up 1.0% year-on-year. Ranking dropped from fourth place last year to sixth. In the first half, JMC launched two core models: the brand new Baodian and Dadao. But it did not reverse the market landscape. The brand new Baodian faces intense price competition in the commercial tool vehicle market; although the Dadao series saw obvious product capability upgrades, the launch time was late, combined with poor export performance, overall sales faced pressure.
Foton Motor sold 23,288 pickups in the first half, up 21.6% year-on-year, ranking seventh. Exports became the main driver of Foton pickup growth. Public data shows that from January to May 2026, pickup exports exceeded 15,000 units, growing rapidly year-on-year, focusing on deepening regional markets such as Latin America, Africa, and Oceania.
BYD sold 20,037 pickups in the first half, down 25.8% year-on-year. Ranking dropped from fifth place last year to eighth. As a new entrant in the pickup industry, BYD previously relied mainly on overseas exports to drive sales, but since 2026, competition in export markets has intensified. Combined with its "Shark" pickup not yet scaling up domestically, overall sales faced pressure. However, from a new energy dimension, BYD remains an important force in the pickup market. In June, new energy pickup overseas sales reached 4,000 units, maintaining leadership in the new energy pickup sub-sector.

Radar New Energy, under Geely, sold 11,111 pickups in the first half, up 40.5% year-on-year, surpassing Jiangxi Isuzu to rise to ninth place in the industry. This year, Geely Radar launched the King Kong EV pure electric pickup, supplying nationwide markets for commercial scenarios such as agriculture, forestry, and urban-rural distribution. It simultaneously laid out Thailand and Philippines overseas markets, achieving continuous rise in sub-sector market share.
Jiangxi Isuzu sold 11,008 pickups in the first half, a slight decrease of 0.8% year-on-year, falling back to tenth place in the industry. Jiangxi Isuzu relies on diesel hard-core pickups to stabilize engineering and off-road fixed customers, but development has multiple constraints: vehicle iteration update rhythm is relatively slow, new energy model implementation progress lags behind peers, meanwhile product pricing lacks competitiveness, lacking effective volume support, overall growth space is hard to open.