首頁Lexus LS400

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
喺馬來西亞嘅 SUV 市場,好多買家在揀車嗰陣都會拿 Mazda CX-60 同 BMW X1 嚟做比較。呢兩款車喺價位同定位上都幾接近,今日我哋就從多個方面做個詳細嘅比較,幫你節省做功課嘅時間。
Mazda CX-60 喺馬來西亞嘅 OTR 售價係 RM 200,510 - 252,873,總共 2 個版本,包括 2026 3.3T 4WD High Plus(RM 252,873)、2025 2.5L 2WD High(RM 200,510)等。
BMW X1 喺馬來西亞嘅 OTR 售價係 RM 252,800 - 252,800,總共 2 個版本,包括 sDrive18i(RM 220,000)、sDrive20i(RM 250,000)等。
從價錢睇,Mazda CX-60 嘅起跳價真係比 BMW X1 平咗 RM 52,290。如果你預算有限,Mazda 嘅入門版已經可以滿足日常需要。但都要留意,平嗰幾千蚊,可能喺配備上面會有取捨,具體要睇你嘅需求。

Mazda CX-60 配備 2.0L 4-cyl,馬力 170 hp。官方油耗 8.0 L/100km。
BMW X1 配備 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
動力方面,BMW X1 嘅 2.0L Turbo 比 Mazda CX-60 嘅 2.0L 4-cyl 多咗 50 匹馬力。不過日常喺市區開,兩款車嘅動力都夠用,唔會覺得唔夠力。

Mazda CX-60 車身長 4500 mm,行李箱 450 L。
BMW X1 車身長 4400 mm,行李箱 400 L。
空間方面,Mazda CX-60 嘅車身比 BMW X1 長咗 100 mm,車內乘坐空間會寬鬆啲,尤其係後座腳位空間。如果你經常載家人或者需要放手推車,車身大啲真係更實用。

Mazda CX-60 保用 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
BMW X1 保用 5 年/無限里程,保養間隔 每 10,000km 或 6 個月。

總括嚟講,Mazda CX-60 同 BMW X1 都係馬來西亞市場幾唔錯嘅車型。揀邊一部,關鍵都要睇你個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,先去試駕先做最終決定。買車係件大嚟嘅事,花少少時間做功課絕對無錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿 BMW X3 同 Land Rover Discovery Sport 嚟比較。呢兩部車喺價位同定位上都幾接近,今日我哋就從多個方面做一次詳細嘅對比,幫你省返做功課嘅時間。
BMW X3 喺馬來西亞嘅 OTR 售價係 RM 325,800 - 358,800,一共有 2 個版本,包括 xDrive20i(RM 320,000)、xDrive30e(RM 360,000) 等。
Land Rover Discovery Sport 喺馬來西亞嘅 OTR 售價係 RM 499,800 - 499,800,一共有 1 個版本,包括 Standard(RM 499,800) 等。
從價錢嚟睇,BMW X3 嘅起步價確實比 Land Rover Discovery Sport 平咗 RM 174,000。如果你預算有限,BMW 嘅入門版已經可以满足日常需求。但亦都要注意,平嗰幾千蚊,喺配備上可能會有取捨,具體睇你嘅需求。

BMW X3 配備 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
Land Rover Discovery Sport 配備 3.0L Turbo,馬力 350 hp。官方油耗 12.0 L/100km。
動力方面,Land Rover Discovery Sport 嘅 3.0L Turbo 比 BMW X3 嘅 2.0L Turbo 多咗 130 匹馬力。不過日常喺市區開,兩部車嘅動力都夠用,唔會覺得唔夠力。

BMW X3 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 Premium ADAS。
Land Rover Discovery Sport 嘅安全評級係 TBD,主動安全系統包括 Basic。
安全配備方面,兩部車都拿到唔錯嘅評級。不過 BMW X3 嘅 Premium ADAS 同 Land Rover Discovery Sport 嘅 Basic 喺功能上有少少差異,如果你比較重視主動安全嘅話,可以仔細比較下兩者嘅功能列表。

BMW X3 保養 5 年/無限里數,保養間隔 每 10,000km 或 6 個月。
Land Rover Discovery Sport 保養 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。

總計嚟講,BMW X3 同 Land Rover Discovery Sport 都係馬來西亞市場幾唔錯嘅車型。揀邊一部,關鍵都要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕先做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Chery Tiggo 8 PHEV 同 Ford Everest 嚟做比較。今日我哋由多個方面做一個詳細比較,幫你節省咗做功課嘅時間。

Chery Tiggo 8 PHEV 喺馬來西亞嘅 OTR 售價係 RM 159,750 - 159,750,一共有 2 個版本,包括 1.6L Turbo Standard(RM 130,000)、1.6L Turbo Premium(RM 145,000)等。
Ford Everest 喺馬來西亞嘅 OTR 售價係 RM 266,338 - 430,838,一共有 6 個版本,包括 2026 3.0T 4WD Platinum(RM 430,838)、2026 2.0T 4WD Platinum(RM 348,838)、2026 2.0T 4WD Sport(RM 316,838)等。
由價錢睇,Chery Tiggo 8 PHEV 嘅起步價確實比 Ford Everest 平咗 RM 106,588。如果你預算有限,Chery 嘅入門版已經可以滿足日常需要。但都要留意,便宜嗰啲錢,可能喺配備上會有所取捨,具體睇你嘅需求。

Chery Tiggo 8 PHEV 配備 Hybrid,馬力 170 hp。官方油耗 4.5 L/100km。
Ford Everest 配備 2.5L Diesel,馬力 187 hp。官方油耗 8.5 L/100km。
動力方面,Ford Everest 嘅 2.5L Diesel 比 Chery Tiggo 8 PHEV 嘅 Hybrid 多咗 17 匹馬力。不過日常喺市區開嘅話,兩款車嘅動力都夠用,唔會覺得唔夠力。

Chery Tiggo 8 PHEV 車身長 4400 mm,車尾箱 400 L。
Ford Everest 車身長 4400 mm,車尾箱 400 L。
兩款車嘅尺寸幾乎一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全夠用。
Chery Tiggo 8 PHEV 採用 FWD 驅動方式。
Ford Everest 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。
總括嚟講,Chery Tiggo 8 PHEV 同 Ford Everest 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵仲係要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,先至去試駕做最終決定。買車係件大事項,花啲時間做功課絕對唔會錯。

兄弟姐妹們,今日講一個出海嘅大新聞——唔係賣車,係賣「司機」。6 月 2 號,文遠知行同 Uber 聯合宣佈咗一件事:計劃喺西班牙馬德里推出該國首個商業化 Robotaxi 試點服務。意思就係:西班牙人好快就可以用 Uber 叫到一台冇司機嘅出租車。呢次係文遠知行同 Uber 第一次一齊進入歐洲市場。馬德里亦成為文遠知行 Robotaxi 駛入嘅全球第十二個城市。
官方消息話,喺馬德里自治區政府嘅支持下,呢項服務今年內就會正式啟動。到嗰陣,馬德里嘅朋友哋打開 Uber App,就有一鍵呼叫文遠知行嘅 Robotaxi。同叫普通網約車一樣,分別係嚟嘅車冇駕駛員——至少喺初期,仲係有分別嘅。運營初期,車入面會配備經過專業培訓嘅安全員,終究係剛上線,穩妥第一。
文遠知行呢間公司,你可能聽過,也可能冇聽過。簡單介紹下:2017 年成立,一直埋頭搞 Robotaxi 技術研發同商業化。而家佢嘅 Robotaxi 已經覆蓋咗廣州、北京、新加坡、阿布達比、迪拜、利雅得、蘇黎世……加埋而家嘅馬德里,一共 12 個城市。西班牙亦係文遠知行進入嘅第五個歐洲市場——之前已經入咗瑞士、法國、比利時、斯洛伐克。按照文遠知行同 Uber 喺 2025 年 5 月達成嘅規劃,佢哋要喺五年內新增 15 個國際城市部署 Robotaxi 服務,全球部署數萬輛 Robotaxi。隨著馬德里落地,目前已經完成咗 4 個城市嘅佈局,仲有 11 個會喺 2030 年前陸續覆蓋。
講真嘅,中國自動駕駛公司出海唔係頭一回,但中國技術 + 全球出行平台 + 歐洲市場呢個組合,定係好有意思。馬德里係歐洲最具商業潛力嘅 Robotaxi 市場之一,人口多、出行需求大,當地政策都好友善。喺呢個市場站穩腳根,對文遠知行嚟講係個唔小嘅里程碑。對 Uber 嚟講,引進 Robotaxi 都係為咗降低成本——終究司機唔使發人工。對馬德里市民嚟講,以後打車可能更平。

Is the Mixue-style approach really effective?
In 2026, the new energy poker table is undergoing drastic restructuring by the month.
The China Passenger Car Association predicts that the new energy penetration rate will exceed 62% in May, with the fuel vehicle share compressed to less than 40%.
More importantly, 30,000 vehicles—the figure once seen as the top-tier threshold—is now squeezed into 7 brands. And the top Leapmotor raised this threshold to over 80,000.
The landscape is thinning and thickening. Thinning, because the leaders are far ahead; thickening, because the chasing echelons have never been so crowded. Is there only one path to success? Who could know before the main drama ends?
Leapmotor's '80,000+' Moment
Leapmotor sold 81,500 units in May, up 81% YoY.

For a long time in the past, EV new forces loved to talk about high-end, smart, and brand upgrade. As if the higher you stand, the more story you have. However, Leapmotor took another path, almost adopting the 'Mixue Bingcheng' approach, focusing on family users in the 100,000 to 200,000 RMB price range.
Users in this price range have broader coverage but are more sensitive to price, and at the same time, it is hard to tell a particularly 'sexy' capital story. However, the operational logic must be very grounded. The return is that once costs, reputation, and channel efficiency reach a certain level, sales elasticity will also be larger.

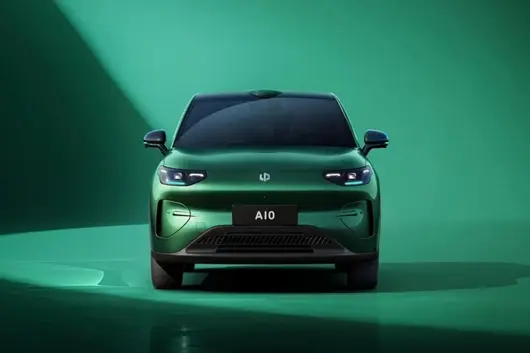
For example, A10 delivered over 20,000 units in a single month, squeezing LiDAR and Qualcomm 8295 chip into under 100,000; C Series global cumulative sales exceeded 800,000; D19 new orders maintained above 10,000. Three product lines, three price bands, precisely locking three key nodes of the mainstream family market.
For this reason, Leapmotor's lead is not 'single hit driving', but the result of 'matrix synergy'.
But the hidden worry lies in: should we still pursue brand upgrade? Should we still pursue high profits? In the high-end market, will the 'Mixue Bingcheng' approach still work? Actually, Leapmotor knows all this, otherwise it wouldn't have proposed the idea of 'launching a new brand independently'.
Nio approaches 40,000, Li Auto under pressure, Xpeng slight increase
May's second tier is worth detailed tasting.
Nio delivered 37,705 vehicles, up 62.3% YoY, and up 28.4% MoM, with the synergy effect of the multi-brand strategy beginning to materialize.
Among them, Nio brand 20,013, Onvo 12,029, Firefly 5,663. Three brands, three niche tracks, three-level ladder user acceptance.

But there is still one unresolved problem: Can Onvo's brand independence and user perception really work through? If it relies solely on main brand downward channel and resource funding, multi-brand might drag overall efficiency.
To a certain extent, Onvo must move volume, and with this wave of model refresh, let's see the results.
Li Auto delivered 33,350 vehicles in May, down 18% YoY, and down about 0.2% MoM.
Having said that, Li Auto's historical cumulative deliveries broke 1.7 million and is still one of the most substantial new forces. But there are two signals worth being vigilant: first, two consecutive months both YoY and MoM decline; second, with competitors' intensive launches in the same price band, Li Auto's differentiation barrier is being eroded.

i6 deliveries broke 20,000 for three consecutive months, L9 new model release 2 weeks orders broke 10,000, but whether incremental volume can timely fill the basement decline is still unknown.
More worthy of attention is the financial aspect: Li Auto turned from profit to loss in Q1, net loss of 2.276 billion RMB, vehicle gross margin plummeted from 19.8% to 6.1%. Loss of the profit benchmark may impact the capital market more than the sales slowdown.
Xpeng delivered 32,158 vehicles in May, up 3.6% MoM, setting the monthly high since 2026.

Among them, Xpeng GX launched on May 20, 12 hours large deposits 24,863, Ultra Flagship version proportion over 80%, after June mass delivery expected to pull overall data.
MONA Family will continue to introduce new members, including L03 and L05, having the opportunity to grow MONA's potential market together.
Xiaomi stood firm on the 30,000+ step for two consecutive months, from single car brand heat to multi-model product layout, Xiaomi is completing the role switch from 'topic creators' to 'market participants'.
This year's full year sales target is 550,000, Jan-May completed 140,000 to 150,000, estimated 400,000 'gap' remains,

So, in the remaining months, average monthly sales need to exceed 50,000, pressure is not small. Perhaps, after EREV products hit the market, there should be a chance to capture a new group of users again.
Harmony Intelligent Mobility delivered 46,122 vehicles in May, up 41% MoM, returning to the top of the list.
Special mention: AITO M6 first complete delivery month broke 20,000 units, Shangjie Z7 delivery started on May 30, 2 days delivery over 2,000. Huawei ecosystem brand call power plus multi-brand matrix approach is forming a unique competitive barrier.

Second-Gen Startups, Waist Explosion
First, let's look at a 'Second-Gen' May sales express:
Zeekr: 34,377, YoY surge 81.8%, consecutive 4 months both YoY and MoM growth, creating historical high. 9 Series and 8 Series flagship models sales share nearly 50%, single car transaction average price over 360,000 RMB; Zeekr 009 in Singapore market starting price as high as 409,900 SGD (then equivalent to 2.21 million RMB).

This group of numbers shows Zeekr has not only broken through of domestic brands, but entered global luxury car market mainstream view. Volume and price rise together logic is not complex: flagship builds reputation, mid-range moves scale. When 9X, 009 ultra-high ticket price anchors brand premium capability, 8X, 001 volume models user acceptance cost naturally declines.
Deepal: 33,243, YoY growth 30%, consecutive 3 months over 30,000, cumulative deliveries broke 850,000.
Deepal's path worth chewing repeatedly: its rhythm is not 'hit explosion', but 'three lines push'. S05, S07, S09 three models simultaneously hot selling, product lines cover 100,000 to 200,000 main range.

This approach has no hit one night godhood drama, but in stock competition, multi-product lines synchronous volume, supporting each other, system resilience is stronger.
GAC Aion: 33,140, YoY growth 23.8%, consecutive months YoY positive growth.
Aion N60 officially launched, full series standard equipped LiDAR, WeRide L4 shared algorithm, Zero Gravity Seats, Five-link rear suspension, price 109,800-129,800 RMB, first month sales broke 5,000. This 'Technology universality' approach, identical with Leapmotor A10 underlying logic.

Voyah: 13,003, YoY growth 30%. More important than sales numbers, Voyah offline touchpoint coverage over 100 cities, self-built charging stations reached 130. When energy replenishment system and channel network truly formed, sales ceiling naturally will be pushed open.

IM Motors: 10,023, consecutive 2 months broke 10,000, Jan-May cumulative sales YoY surge 115%. IM Motors LS8 post launch pulled a wave order volume recovery, let's see sustainable explosive power later.

Avatr: 7,336 created annual high, and showing month-by-month acceleration trend, overall is positive.

To be honest, 'Second-Gen' held their own positions, not completely overturned in landscape change, as for those who can carry the flag already diffused from Zeekr, Deepal two heads to multiple nodes at the waist.
Written at the end
2026 new energy market, experiencing drastic change from 'inclusive growth' to 'stock battle'. Price war normalized, most car companies contract front line, profit as first goal. Elimination round rules are simple: sell and live, can't sell and quit. And can't sell signal, often hidden in consecutive two or three months MoM decline.
May data, is this elimination round a clear report card: Leapmotor first to work through 'mainstream market scale' path, Nio multi-brand synergy saw first light, Li Auto facing replacement pain, Xpeng still looking for new incremental explosion points, Xiaomi continuously holding 30,000 level. And 'Second-Gen' collective volume increase, is building a wide moat at the waist of new energy market.
Electric competition second half, variables both from new forces aggressive acceleration, also from 'Second-Gen' steady advance. Multiple heads advance landscape once formed, future competition will not be single dimension speed race, but full chain system war covering R&D, manufacturing, channel, service.
And such competition, will evolve how, wait and see.
Author of this article is Ti Che Bang Xi Bei
你睇過印度嘅馬路嗎?
我喺網上見過。
畫面通常係咁,一輛轎車俾牛尾擋住,旁邊仲有亂竄嘅摩托,甚至周圍仲有賣奶茶嘅小夥,嗰叫一個“乾淨又衛生”。

然而,喺呢啲睇完好多人覺得生理不適嘅地方,豐田、鈴木、本田等日本車廠,卻決定將籌碼押落印度。
據印度“品牌質量基金會”網站顯示,三家車廠將喺印度投資近110 億美元建廠、提產能、搞出口。
對此有网友表示,三家日本車廠係咪錢多到無處花?
事實上,佢哋唔係錢多到花唔完,亦唔係被印度嘅咖哩蒙蔽咗心竅,呢啲日本車廠高層遠比我哋清醒。
而家嘅日系車,營業額、市場份額都喺下滑,原材料成本仲係升得飛起,打開世界地圖,搵一個能夠容納產能、拓充份額、競爭溫和嘅市場,唔係咁容易嘅事。
所以,唔係日本車廠選擇咗印度,而係因為冇得揀。
日本車廠之痛
曾經嘅日系車,嗰時妥妥係人哋個仔。
你問下十幾年前開過日系車嘅老司機,一提起日系車,幾乎就冇唔豎大拇指嘅,價錢平、省油、耐用又抵撞……
甚至好多日系車,仲要加價購買,但邊個諗到,呢個鐵打嘅江山,短短幾年時間就俾佢哋打得找唔著北。
隨著新能源汽車浪潮嚟到,電動化、智能化變成好多自主車廠“彎道超車”嘅目標,依托於中國強大嘅新能源汽車產業鏈優勢同車廠自身對研發、技術嘅堅持,中國自主品牌迅速實現咗“彎道超車”。
曾經被人吐槽嘅國產車,而家喺馬路越來越多人,甚至份額超越咗合資。
根據乘聯會嘅數據,喺2026 年4 月,自主品牌嘅份額已經高達62.5%,遠超日系嘅13.1%。

要知道,中國汽車市場係全球最大嘅汽車市場,喺中國市場失速,就相當於丟咗一塊巨大嘅蛋糕。
同時,中國市場近年嚟嘅主旋律依舊係價格戰,捲配置、捲價格、捲服務已經成為一種常態,亦對日系車嘅利潤產生咗巨大嘅影響。
除咗中國,日系車喺美國過得亦唔太好。
2025 年 1 月 20 日,特朗普宣誓就職第 47 任美國總統,自此開啟咗一連串搞搞震,其中就包括以國家安全為理由徵收額外嘅汽車關稅,導致進口日本汽車嘅關稅稅率一度高達 27.5%,雖然後嚟有所降低,但亦遠高於最初嘅稅率。
呢個操作,直接導致七大日本車廠喺2025 財政年度嘅關稅損失超2 萬億日元。
再睇日本本土,其實亦唔容易。
中東地緣衝突導致霍爾木茲海峽航運受阻,運輸成本、原材料成本暴漲,日本車廠都有苦難言。

高管們看著報表,背後發涼,只能尋找全新嘅增長曲線。
所以,日本車廠唔係愛上印度,係冇地方去。
揀選印度嘅深思熟慮
咁,印度點解咁有魔力,先至令日本車廠重資投入呢?
第一個優勢就係大。喺2025 年,印度汽車市場取得咗551.7 萬輛嘅新車銷量,同比增長 6%,刷新咗歷史紀錄,位居全球第三大汽車市場,已经连续四年超越日本,僅次於中國同美國。
呢個含金量唔使多講啦,而印度取得呢一成績,主要係因為印度一直喺推動減稅政策,促進消費,這導致國內消費意願出現咗明顯增強。
第二個優點係近,就係離日系車賣得動嘅地方近,如非洲等其他地區。
所以,印度對於日本車廠,更似一個建喺十字路口中央嘅便利店,你唔使將車分別運去八個國家,只需要喺印度呢站造好,然後一船一船甩去,就能削減唔少成本。

《日本經濟新聞》亦認為,印度有望轉變為佢哋全球嘅汽車供應中心。
第三個優點係穩。要知道,日系車嘅優勢就係燃油車,畢竟引擎、變速箱、底盤三大件,佢哋已經玩咗好多年,技術積累喺全球都係數一數二。
但係中國汽車市場已經全力推動電動化、智能化發展,導致日系車嘅優勢越來越弱,根本無法發揮出嚟,但印度唔一樣,佢擁有充電樁少、電動化進程緩慢嘅特點,印度老百姓買車,都仲係盯住平、省油、易修,而呢三點正係日系車嘅老本行。
尤其係鈴木,一直係印度汽車市場嘅常青樹,幾乎年年穩坐暢銷車型寶座,口碑好,勝過任何廣告。
所以,日本車廠大力佈局印度市場,顯然是經過深思熟慮嘅。
但,印度市場真係咁好混咩?
難啃嘅印度市場
當然,印度亦唔係完美得似個香口格,佢嘅缺點同佢嘅優點一樣明顯,而且每一個都夠日本車廠喝一壺。
先講電動化,冇錯,眼睇下印度充電樁少、電動車賣唔動,確實係日系燃油車嘅避風港。但你得諗諗,呢個“避風港”能避幾耐?
印度此前可係喊出咗 2030 年電動車佔新車 30% 嘅口號,雖然聽落似吹水,但抵唔住人哋真補錢、真建充電站。
試諗下,萬一有日印度突然開竅,開始大力推動電動化、搞基建,充電樁似雨後春筍咁冒出來,嗰日系車唔就傻眼?
呢唔係泰國市場嘅翻版咩?
當年日系車喺泰國都係躺贏,整個東南亞市場,都被稱為日系車嘅後花園,結果泰國率先推動電動化,中國電動車一嚟,直接就成咗香口格,再睇日系車,喺泰國嘅市場份額嘩嘩嚟咗落。

如果印度係電動化一加速,歷史大概率會重演,而而家呢次,日系車連逃嘅地方都快冇咗,點樣預防,將成為日本車廠嘅首要問題。
再講政策,印度嘅政策就似一鍋咖哩,你永遠唔知下一口食到係雞肉定係馬鈴薯。
呢個魔幻嘅國家,今日係低關稅鼓勵建廠,明日就可能罰你一筆巨款,更令人頭痛嘅係強制合資,外國車廠想喺印度賣車,要搵本地夥伴搭檔,等你工廠建好咗、供應鏈搭完咗,印度直接背刺你,到嗰陣無論係加錢定撤資,換嚟嘅都係心痛。
所以你看,印度呢個市場,就好似一個睇落好甜嘅芒果,咬落去第一口仲行,再啃幾口就摸著硬核。
日系車而家嘅算盤係,趁住核都未硌牙,趕緊多啃幾口,但核遲早會硌到,只係唔知係邊一日。
尾聲
日系車呢趟印度之旅,唔係去旅遊,係去搵食。
中國同東南亞嘅飯桌更擁擠,生產、運輸嘅成本又提高咗,放眼全球,就印度呢口鍋仲冒住熱氣,哪怕入面煮嘅係咖哩味嘅石頭,都要硬著頭皮啃落去。
日本車廠想擴大市場,印度想嘅係拉動經濟、解決就業,雙方都有各自嘅心思。
至於結局係日系車喺印度重新封神,定係好似當年嘅部分友商一樣灰溜溜走人,那就唔知啦。
但無論點樣,呢場戲先至開始,我哋慢慢睇就得啦。
反正印度嘅故事,從來唔會悶。
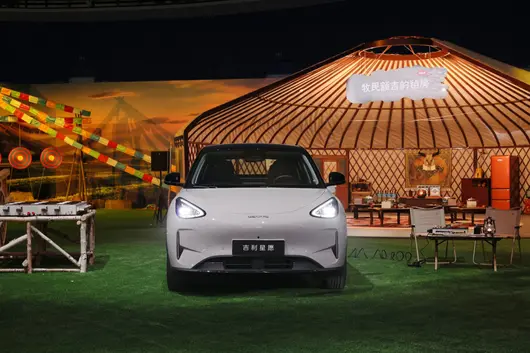
Recently, the all-new Geely Star Wish, a pure electric compact car under the Geely Galaxy brand, has officially launched. The new car offers four models: 410km Yearning Edition, 410km Riding Wind Edition, 480km Exploration Edition, and 480km Exploration+ Edition. The launch limited-time benefit price range is 61,800 yuan to 91,800 yuan. The all-new Geely Star Wish undergoes upgrades in driving control, three-electric systems, smart cockpit, assisted driving, and safety, with over 100 product capability improvements involved. Among them, over 25 features are unique configurations in the same class.

The all-new Geely Star Wish is built on Geely's first global native architecture. All trims feature rear independent suspension as standard, jointly tuned by China and Germany. It is equipped with G-TCS 2.0 all-weather anti-slip system, a new brushless steering system (response speed doubled), and G-CST 2.0 all-scene comfort braking system. Official data shows the vehicle passed the Elk test at 80.7km/h and successfully completed the Fishhook test at 130km/h.

All trims are standard with CATL cells, liquid cooling temperature control, and an 11-in-1 highly integrated electric drive. Cell energy density is 190Wh/kg, with a maximum range of 480km. Combined with active grille and low-drag wheels, aerodynamic drag is reduced by 15 counts, and actual range is increased by another 10km. Fast charging from 30% to 80% takes 19 minutes, equipped with Star Rui AI Cloud Power 2.0 for full-link energy management.

In terms of the smart cockpit, it is equipped with Galaxy Flyme Auto 2 system, based on the 7nm Dragon Eagle No. 1 chip and 16G+128G storage. It supports CarPlay phone connectivity. The voice assistant Hi EVA features fuzzy command understanding and context memory. The infotainment system includes Amap 850 version map and provides Invisibility Mode, Car Wash Mode, and One-key Car Find functions.

In terms of assisted driving, it is equipped with the Qianli Haohan H3 solution. Officially, it has accumulated over 1.38 billion kilometers of safe driving. Highway and elevated road NOA supports voice lane change, evasion, and auto on/off ramps. Full-scene MPI takeover mileage exceeds 200 kilometers. Parking functions include APA one-key parking, remote parking, and HPA memory parking (up to 2km route memory). Additionally, it is equipped with DMS fatigue monitoring and Sentry Mode.

The all-new Geely Star Wish adopts a Five Longitudinal, Eight Transverse Star Armor Cage Body, with roof crush strength reaching 3.4 times the vehicle weight. The battery system maintains 90.72% capacity after 1000 cycles; the validation standard is 2 times the National Standard. Officially announced on May 12, it passed front and side continuous collision tests witnessed by CCTV. The high-voltage system powered off timely, and the battery pack did not smoke or catch fire. Regarding active safety, it is equipped with AEB active braking and AES emergency steering, passing 120km/h static vehicle stop and 130km/h "Disappearing Lead Car" evasion tests.

Since launching in October 2024, Geely Star Wish cumulative deliveries have surpassed 700,000 units, becoming the fastest model in the industry to achieve this goal, and winning the 2025 China Auto Market Sales Champion. In Q1 2026, this model entered the top 3 global new energy sales for the first time, and is the only Chinese brand to achieve this ranking. Currently, Geely Star Wish has launched in over 30 countries and regions globally. In Brazil, sales exceeded 2,300 units within two months of launch. At the Thailand Auto Show, weekly orders reached 3,300 units, and it received international awards such as "Brazil Best Compact EV of the Year".