首頁Exports

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

Chinese auto overseas expansion has been the hottest topic in the industry in recent years. Now that China has become the world's largest auto exporter, what challenges does Chinese auto overseas expansion face?
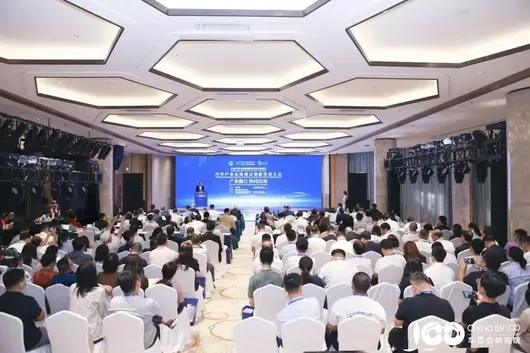
On November 1, 2026, the conference on innovation and development of auto industry overseas expansion models, jointly organized by the Chaihui Institute and Hainan Qinglan ZhiLian Technology Co., Ltd., was held in Chengmai, Hainan. From export situation, overseas after-sales, cross-border data to insurance pricing, the judgments of eight speakers point to the same conclusion: Chinese autos have passed the scale threshold. The next thing to prove is whether they can exist long-term overseas, while after-sales, parts, data, insurance and these 'invisible capabilities' determine this matter.
After 8 Million Units, A New Threshold Appears
Sun Xiaohong, former Secretary-General of the Automotive Branch of the China Council for the Promotion of International Trade in Machinery and Electronic Products, provided the following data: Customs data (excluding low-speed electric vehicles) showed China's auto exports reached 7.89 million units in 2025, nearing 8 million, with new energy vehicles accounting for over 35% of the total export volume. From January to September 2026, auto exports were about 8.63 million units, a year-on-year increase of over 50%; new energy passenger vehicles were nearly 4 million units, with an increase of over 70%; commercial vehicles were 1.15 million units, with an increase of 35%-40%.

However, if calculated by cargo value, Germany remained first in 2025, China second, surpassing Japan to move up one rank. Sun Xiaohong reminded that although Germany's quantity is lower than China's, its unit price is higher, and its overall strength is still stronger than China's. In terms of export region ranking (January to August), the EU, Latin America, Eurasian Economic Union, ASEAN, Africa, Middle East, US-Canada-Mexico, and Oceania were listed in order. He predicted that commercial vehicle exports in 2026 could reach 1.5 million units, and including passenger vehicles, total vehicle exports would exceed 10 million units.
Sun Xiaohong compressed the focus of the '15th Five-Year Plan' into six words: 'Stand Firm, Return Successfully'. 'Stand Firm' means holding onto the markets opened up during the '14th Five-Year Plan', not letting them slip and be regained; 'Return Successfully' means overseas revenue flowing back domestically to form a closed loop with R&D investment. Compared to 'Going Global 1.0' (2021-2025, from 1 million to 8 million), the new stage is shifting from selling products to whole industry chain overseas expansion and ecological overseas expansion.
Tariffs and Localization Under the Tripartite Balance
Trade barriers are cutting the global market into separate, non-interconnected blocks.
Mexico's tariffs rose to 50% this year, Brazil restored to 35% and required localization layout. Indonesia requires reaching an 80% localization rate before 2030 and must adopt nickel-containing batteries. Thailand's EV 3.5 regulation stipulates for every one imported, two must be locally produced, rising to three by 2027; the Gulf Cooperation Council six countries have tariffs around 5%, and Australia has zero tariffs due to free trade agreements.
Besides the 2024 EV countervailing duties, the EU formally filed an investigation on safeguard measures for hybrid cars on October 30, determining that hybrid exports to Europe grew 49% from 2023 to 2025, and feedback must be given within 21 days. China proposed three principles: using 2025 year-end export volume as the base, measures must not target only China, and retaining countermeasure capabilities under the WTO framework.
Sun Xiaohong stated that the greatest uncertainty impact comes from the Foreign Subsidy Regulation (FSR), 'investigation interference when business promotion is smooth, the situation is very serious'. He also reminded of the EU anti-evasion red line: relying on local assembly and OEM to avoid taxes, the origin country proportion must not exceed 60%.
After-sales is the First Link to Have Problems
Zhang Yanhua, President of the China Automotive Maintenance Industry Association, judged: the speed of after-sales capability accumulation lags behind the speed of sales expansion. This contradiction was previously covered up by the relatively stable initial quality of Chinese cars. As stock accumulates, pressure will concentrate and show up in two to three years.

The gap is significant: Chinese automakers have about 30 overseas spare parts warehouses, international brands have 600, a 20-fold difference; service network density is about 1/8 to 1/10 of major competitors, and the industry hopes to catch up in five years. He advocates exploring a multi-brand shared regional spare parts guarantee system, operated by professional supply chain service providers, and emphasizes that 'sharing does not mean merging', enterprises still need to bear product quality and service management responsibilities.

Wen Hua, Deputy General Manager of Dongfeng Liuzhou Automobile Import & Export Company, has years of overseas front-line experience. He added some details: the company shrank its overseas service radius from 160 kilometers to 102 kilometers over the past three years, 106 kilometers in 2026, with a goal to continue shrinking to 65 kilometers.
He opposes using one platform for the whole world. In Thailand, heavy rain and maximum A/C power will suck rainwater into the car. For Kuwait customers with A/C failure, designers need to go to the site to feel 60+ degrees high temperature to understand the problem. He mentioned Brazil has no more than 10 high-voltage charging stations nationwide, so they developed range-extender trucks; right-hand drive products are not modifications but redesigns.
He also proposed a common industry bottleneck: damaged parts need to be sent back to China for analysis, but importing old parts is controlled.

'Trust is never advertised, trust is cultivated.' Zhang Xiaodong, Deputy Director of the Technical Management Center of Geely Auto Group, stated that exports of 472,000 units in the first half of the year were already equivalent to the full year of last year. The first issues exposed were spare parts prediction and scheduling. The company responds with a Dutch central warehouse plus regional warehouses in key countries, and established Geely CARE service standards and technician certification systems.
Data Has Become the Second Supply Chain
Chu Huabin, General Manager of Qindarui (China) Information Technology Co., Ltd., proposed that the product supply chain determines whether cars can go overseas, and the data supply chain determines whether they can maintain continuous leadership.

Intelligent driving road tests in multiple Southeast Asian cities generate hundreds of G of street scene images and decision logs daily, which are key assets for optimizing overseas intelligent driving models. However, raw images of privacy data such as faces and license plates must not leave the country, requiring irreversible blurring and tokenization to be completed locally. The company's approach strings together local preprocessing, compliance assessment, cross-border transmission, Chengmai processing, and R&D feedback into a link. Currently, 8 types of trusted data subspaces in the automotive industry have been built locally, and 86 automotive industry data scenarios have been sorted out.

Hou Weiqiang, China Sales Vice President of LexisNexis Risk Solutions, provided insurance-side evidence: the UK market average premium is 646 pounds (about 5000-6000 yuan), insuring Chinese exported cars is 901 pounds (about 8000 yuan). The population and environment remain unchanged, the difference comes from insufficient information from overseas underwriting institutions.
He pointed out an anti-intuitive phenomenon: many intelligent driving hardware, computing power chips and complex cameras, overseas insurance companies will judge higher maintenance costs, the ability that could lower accident rates instead became a deduction point.
Hainan Free Trade Port 'One-Stop Bridgehead'
Zhang Xiaodong suggested Hainan build an auto overseas expansion service middle platform, a one-stop inspection and certification system, connect the Southeast Asia mutual recognition, cross-border data chain (including overseas OTA updates), and spare parts warehousing and bonded maintenance under zero tariff and low tax rates.

Linglong Tire President Zhou Lingkun proposed doing container splicing and value-added manufacturing centers, global service and compliance digital hubs, three-port linkage combining sea and air transport, and suggested building a global testing and certification center relying on Hainan's unique tropical region conditions.

Thailand's investment attraction logic has also shifted from complete vehicles to the whole value chain. Chen Weili, Director of the Guangzhou Office of the Thailand Board of Investment, introduced that from 2021 to the first half of 2026, China's investment declaration projects exceeded 2,700, with a total amount of 136 billion yuan. The number of projects increased from 108 in 2022 to 970 in 2025. She mentioned that the Thai local association is worried about an 'industrial cliff' appearing after EV policies expire in 2027, as automakers switch to import substitution causing local supply chains to idle.
The final judgment given by Sun Xiaohong is that price wars have no way out, competition must shift to whole lifecycle cost management, including residual value guarantee, TCO transparency, intelligent driving reducing accidents thereby lowering premiums, financial guarantees, etc.
Big Company Perspectives
Chinese autos have already proved they can sell to the whole world. The next thing to prove is that if cars break, there is someone to fix them, parts arrive quickly, data flows compliantly, and insurance pricing is clear. None of these four things can be completed independently by a single enterprise, which is also the reason this conference turns 'going overseas' from a trade topic into a systematic topic.
[Lead: From photovoltaics and power batteries to new energy vehicles, related industries for the "New Three Things" are gradually facing export tax rebate adjustments. The reduction of the export tax rebate rate for new energy vehicles marks a new watershed, not only affecting the profit margins and pricing of automakers in overseas markets but also further altering the competitive landscape of Chinese automotive exports.]
Author: Zhang Dachuan
Recently, the Ministry of Finance and the State Taxation Administration announced Announcement No. 29 of 2026, specifying that starting from April 1, 2027, the export VAT rebate rate for new energy vehicles will be reduced from 13% to 9%. Following photovoltaics and power batteries, new energy vehicles in the "New Three Things" also face adjustments to export tax rebate policies. This new policy will not only affect the costs and profit margins of Chinese automotive export enterprises but may also further influence automakers' overseas pricing, market layout, and the global competitive landscape.

△ Starting from April 1, 2027, the export VAT rebate rate for new energy vehicles will be reduced from 13% to 9%
Why was the export tax rebate rate for new energy vehicles reduced?
Reducing the export tax rebate rate for new energy vehicles is both a policy adjustment following the improved competitiveness of China's new energy vehicle industry and a realistic choice to respond to changes in domestic and international markets while optimizing the export policy system.
First, the scale of Chinese new energy vehicle exports has grown rapidly, and the industry has the conditions to gradually reduce policy support. From January to September 2026, China's new energy vehicle exports reached 4.006 million units, a year-on-year increase of 127.9%, of which pure electric vehicle exports were 2.449 million units and plug-in hybrid vehicle exports were 1.557 million units. As Chinese automakers have formed strong international competitiveness in technology, supply chains, and cost control, the reliance of export growth on policy preferential treatment is decreasing. Appropriately reducing the rebate rate helps push the industry further towards marketization.

△ In recent years, the scale of Chinese new energy vehicle exports has risen rapidly
Second, this policy adjustment will guide a shift in industry competition methods. In recent years, domestic automotive price competition has become increasingly intense. Some companies have extended low-price strategies to overseas markets. While this can quickly expand export scale, it easily compresses profit margins and intensifies international trade friction. Reducing the rebate rate helps reduce enterprises' reliance on price advantages and policy preferential treatment, pushing the focus of competition towards technological innovation, brand building, and localized operations. At the same time, against the backdrop of the EU imposing countervailing duties on Chinese pure electric vehicles and other factors, adjusting export tax rebate policies is also part of optimizing the export policy system and adapting to changes in the international trade environment.

△ Accelerating expansion of new energy vehicles overseas requires attention to avoiding trade friction
It is worth noting that this adjustment targets only new energy vehicles and does not involve fuel vehicles, mainly reflecting the different development stages and policy positioning of the two product categories. China's new energy vehicle industry has formed strong international competitiveness and has the foundation to gradually reduce policy support. Compared to new energy vehicles, the international competitive advantage of Chinese fuel vehicles is not yet prominent, and the trade friction faced is relatively small. There is still significant room for development in markets such as Russia, the Middle East, Africa, and Latin America, and brands such as Chery, Great Wall, and Geely are continuously expanding overseas business. Maintaining the original rebate rate helps maintain export price advantages. Therefore, differentiated adjustment is not only to push new energy vehicles to reduce policy reliance but also a policy consideration to balance the export competitiveness of traditional fuel vehicles.

△ The export tax rebate rate for fuel vehicles has not been adjusted
Export exit route for marginal automakers is narrowing
Domestic automotive market competition is becoming increasingly fierce, and some automakers lacking core competitiveness view overseas markets as the last retreat for digesting capacity and maintaining operations. However, with the reduction of the export rebate rate, the model of expanding exports solely relying on domestic cost advantages and policy preferential treatment will face greater challenges, and overseas markets are becoming increasingly difficult to serve as a haven for marginal automakers.
The reduction of the rebate rate accelerates industry reshuffling and will directly compress the profit margins of exported vehicle models, especially for companies with severe product homogenization, low profit margins, and reliance on low-price competition, making the low-price export model difficult to sustain. For example, some electric vehicle models in the 100,000 yuan price range mainly rely on price advantages to develop markets such as Southeast Asia. Their own profit margins are limited, and reduced tax rebates will further squeeze their profitability. For marginal automakers that lack core technology, brand competitiveness, and a stable domestic market foundation, relying solely on exports for operation, the survival pressure will increase further. In contrast, leading enterprises such as BYD and Geely, which have technology, brand, and scale advantages, have more ability to digest cost pressures, and industry resources will further concentrate on enterprises with long-term competitiveness.

△ Overseas markets will increasingly become difficult to serve as the "last retreat" for some automakers after setbacks in the domestic market
The reduction of the rebate rate will also accelerate automakers' overseas localization layout and promote the transformation of the overseas expansion model. With changes in the cost advantages of complete vehicle exports and increasing trade barriers in markets such as Europe and the US, the model of relying solely on domestic production and complete vehicle exports will face more challenges. Automakers need to further promote overseas factory construction, local procurement, and supply chain layout. For example, BYD's Thailand factory has achieved localized production and is gradually expanding overseas markets; Chery is also continuously expanding its overseas manufacturing network. In the future, the competition of Chinese automakers will no longer be limited to complete vehicle exports, but will gradually extend to overseas R&D, manufacturing, supply chains, and brand operations. Enterprises that truly possess global operational capabilities are more likely to establish advantages in the new round of industry competition.

△ Chinese automakers are setting up factories overseas on a large scale to avoid trade barriers
Small and medium-sized automotive exporters urgently need to transform
Compared to large automakers, the impact of this rebate rate reduction on domestic small and medium-sized automotive exporters may be more direct. Especially for companies whose main business is complete vehicle trade, agency export, and parallel export, profit margins are generally low, lacking brand premium and supply chain cost control capabilities. The reduction of the rebate rate from 13% to 9% will further compress their profit margins. If they cannot pass on the costs to overseas customers, some enterprises may even face a situation where order profits shrink significantly and no profit can be made.

△ The impact of this rebate rate reduction on domestic small and medium-sized automotive exporters may be more direct
Funds turnover pressure will also increase further. Some small and medium-sized exporters rely on the fund circulation between procurement, export tax rebates, and overseas payments to conduct business. If long-term export contracts were previously signed according to the original rebate rate, they may face issues such as difficulties in adjusting prices in the short term and actual profits falling short of expectations. In contrast, large automakers, relying on scale procurement, brand premiums, and mature overseas channels, possess stronger cost digestion capabilities and risk resistance.
From a long-term perspective, policy adjustments may drive automotive export resources to concentrate on scaled and standardized enterprises. The traditional trade model that relied on information gaps, low-price procurement, and tax rebate returns to obtain profits will become increasingly difficult to sustain. Small and medium-sized exporters need to gradually get rid of simple vehicle buying and selling and extend to high-value-added businesses such as overseas channel operations, after-sales services, logistics, and local resource integration to find new profit growth points.
Commentary
The reduction of export tax rebates is a cost pressure in the short term, but a test of the competitiveness of China's automotive industry in the long term. As the new energy vehicle industry gradually matures, the model of expanding exports solely relying on policy preferential treatment and price advantages is difficult to sustain. For leading automakers, the real challenge lies in how to enhance brand premiums and optimize overseas operating efficiency; for small and medium-sized exporters, they need to re-look for business models and profit margins. Chinese automotive exports are also entering a new stage: competition is no longer just about who exports more or at a lower price, but about who can truly take root in overseas markets and establish long-term, sustainable global operational capabilities.
(This article is original to "He Yan Car Review", unauthorized copying is prohibited)
China's automotive exports are entering the deep water zone. From early whole-vehicle trade to building factories overseas and exporting technology and supply chains today, the globalization path of Chinese automakers is undergoing profound reconstruction. For commercial vehicles that directly serve local logistics and passenger transport, simply selling cars abroad is just the first step. Whether they can truly bridge the gap in culture, regulations, and usage habits to achieve localized production and service synergy is the core proposition that determines how far the brand can go. In this wave of going global, Jinbei, with over 30 years of commercial vehicle manufacturing heritage, is relying on strong R&D and flexible manufacturing capabilities to complete the strategic advancement from "going out and going in" to "taking root".

Jinbei's export start was quite early. As early as 2006, Jinbei was recognized as a national-level whole-vehicle export base. As of now, its products have been exported to over 80 countries and regions, with a cumulative export of nearly 90,000 units. However, facing the changing dynamics of the global market, traditional trade models can no longer support the brand's long-term upward development. In recent years, Jinbei's overseas map has gradually expanded to Southeast Asia, Central Asia, Africa, Latin America, etc., establishing deep cooperation with customers in countries along the "Belt and Road" such as Vietnam, Egypt, Tanzania, and Turkmenistan. The model has comprehensively leaped to KD knock-down assembly, CKD completely knocked-down assembly, and deep technical cooperation, beginning to reshape its own export value chain.

In Southeast Asia, Jinbei reached a deep strategic cooperation with Vietnam Fangzhuang Group, covering whole-vehicle trade and new energy innovation. With the smooth rollout of Jinbei Great Sea Lion at the Vietnam KD factory, relying on the mature sales network of local partners, Jinbei quickly penetrated key nodes of this market. In Africa, Egypt has become a benchmark for Jinbei's localized deep cultivation. With the opening of the first standalone brand store in Cairo, the Jinbei Egypt CKD project is accelerating implementation. The three major production lines of welding, painting, and final assembly have entered the finishing stage. After mass production is achieved by the end of the year, Jinbei will truly achieve localized manufacturing and service closed-loop in the African market. From "shipping cars abroad" to "building factories to make cars", Jinbei is exporting mature production processes and supply chain systems overseas, deeply binding with local industries.

The confidence for going global stems from precise insights and rapid responses to global market demands. The globalization of commercial vehicles is essentially customized based on "local conditions". In right-hand drive markets like Malaysia, Jinbei customized the right-hand drive Great Sea Lion and Sea Lion King EV; in Central Asia, Jinbei Sea Lion King successfully won the bid for the Turkmenistan light bus procurement project and delivered smoothly. These precise adaptations rely on the support of Jinbei's "4.0 Quality Smart Factory" and the full-chain R&D system.
On the manufacturing side, the new commercial 4.0 Quality Smart Factory is equipped with over 150 industrial robots, 100% automation of key processes in the painting workshop, and the body workshop has flexible production capability for three major platforms and 28 vehicle models. It can quickly adjust capacity according to order requirements from different global markets. On the R&D side, the R&D center built and put into use in 2025 covers over 7,000 square meters, covering the full-process verification of traditional fuel and new energy, equipped with over 260 advanced devices. It has the testing capability to meet national standards, European standards, and other international standards, breaking through technical bottlenecks for the development and regulatory access of globally customized vehicle models.

Chinese commercial vehicles going global is not only an extension of product sales outward but also a global resonance of China's manufacturing standards and systems. Jinbei is using Chinese R&D as the cornerstone and global demands as the guide, cultivating deeply and working meticulously in broader overseas markets. In the future, Jinbei will continue to rely on the profound heritage of Chinese smart manufacturing, provide more efficient and reliable travel and transportation solutions for global users, make the "Chinese Commercial Vehicles" golden brand shine brighter overseas, and help "Shenyang Manufacturing" deeply integrate into the global industrial system.
October exports were 107,153 units, surging 158% year-on-year, standing at the 100,000 mark for 5 consecutive months. Even more exciting is the structure: new energy vehicle exports reached 82,565 units, a 506% surge year-on-year, accounting for a spike to 77% of exports. Cumulative exports for the first three quarters totaled 798,000 units, up 169% year-on-year. Domestically, price and configuration wars raged, so Geely has shifted its second growth curve overseas. But going global: early days relied on cost-effectiveness, now it is about depth of rooting — where channels are spread, whether brands can stand firm, and whether local systems can operate smoothly, that is the watershed.
1. 77% of Exports are New Energy, the Competition Strategy Has Changed
Previously, Chinese cars went global relying on low-priced fuel vehicles to move volume. This data from Geely tears up the old script — 77% of exports are new energy. Zeekr delivered 14,162 units overseas in October, exceeding 10,000 monthly sales for 3 consecutive months, with overseas share exceeding 40%. Zeekr took the top spot for luxury brand sales in Australia in Q3, and in September ranked second for electric brands in Malaysia. Geely International EX5 landed in the UK and Poland, Galaxy Starship 7 EM-i entered Australia, CITYRAY landed in the European Adriatic market, Lynk & Co entered Czechia, Austria, and Switzerland. It is not selling whatever is available; it is taking high-value products to bite into mature markets. This competition strategy has changed: from competing on price to competing on product power, from moving volume to moving value.

II. Methanol + Smart Driving, Planting Long-term Seeds
Sales reflect the present, technology determines the ranking two years later. Qianli Haohan assisted driving has accumulated 1.073 million owners, an activation rate of 93.9%, cumulative assisted driving mileage of 3.14 billion kilometers, year-on-year growth of 252.6%, with both installation scale growth and usage mileage growth ranking first in the industry. Geely did not just shove smart driving into high-end flagships, but used multiple brands and price bands to spread to the mass market, where volume growth feeds back into algorithm iteration. On the charging side, MW-level smart charging single gun power is 2.2 MW, building a battery swap network with NIO together, targeting 6,000 smart charging stations by end of 2026, and over 22,000 by end of 2027. Further plans are hidden — November 3rd release of new generation methanol electric hybrid technology, the world's first methanol electric hybrid family sedan Galaxy Starshine 6 EF is about to launch. Smart driving manages the present, charging manages the medium term, methanol manages the long term, three lines arranged into an echelon.

III. From Selling Cars to Rooting, Paris Auto Show Reveals Hand
2026 Paris Auto Show, Geely first appeared with the group lineup of Geely, Lynk & Co, and Zeekr, showcasing SEA-S Haohan architecture and intelligent electric drive. In September, sales of the three brands in Europe exceeded 10,000 units in a single month for the first time. Entering the UK market for only 11 months, the 100th retail outlet signed, cumulative registrations broke 10,000, September monthly sales exceeded 5,000 units. On October 9, it was announced entering Canada, first batch of models meet in 2027. Geely took the number one spot for Chinese brand passenger car sales in Panama in September. From outputting products to spreading channels, to settling local operation systems, Chinese brands going global have passed the stage of "whether there are cars to sell", entering the deep water zone of "whether they can root". That group lineup at the Paris Auto Show reveals the system's bottom card.

Conclusion
Exports broke 100,000 for 5 consecutive months, numbers look good, but what is truly valuable is that hidden line — 77% new energy share, high-end models moving volume overseas, dense channel network setup, technology echelon positioning ahead. Globalization 2.0 does not compete on who has more ships, but who can drive roots down locally. Geely's game is not the earliest, but the moves are dense and deep enough. Next quarter overseas nodes are still adding pressure, Canada market delivery in 2027, European channels continue to spread, methanol technology draws sword on November 3rd. 100,000 units is just a step, not the end point.

Data released by CPCA for September sales shows that retail sales in the passenger car market for September 2026 were 1.631 million units, a year-over-year decrease of 28.1%; even the new energy vehicle market that has always been growing rapidly saw a significant drop, with September NEV retail volume reaching only 1.084 million units, a year-over-year decrease of 16.7%.
Cumulative sales from January to September were 13.457 million units, a 21.9% decline compared to the 17.225 million units in the same period last year, with the absolute decline exceeding 3.8 million units. Meanwhile, new energy vehicles also declined by 12.8% in the first nine months, selling approximately 7.75 million units.
However, if only looking at wholesale data announced by automakers, it seems the Chinese automotive industry is not so "sluggish". According to September data, sales for brands like BYD, Geely, Chery, and Leapmotor all saw year-over-year increases, even reaching record highs. The "gap" here lies in export sales.
CPCA statistics show that Chinese automakers achieved 923,000 units in single-month exports for September, a year-over-year increase of 73.2%; domestic exports for the first nine months totaled 7.067 million units, a year-over-year increase of 75.2%. Moreover, the largest part of export growth was new energy vehicles. In September, NEV exports reached 558,000 units, with a year-over-year growth rate of 163.5%, while growth for January-September reached 3.887 million units, with an absolute increase of 1.2 million units.
01
Export Momentum Is Really Strong
The 3 million units of export growth basically filled the gap from the domestic market decline. To some extent, since the second half of this year, automakers have accelerated exports to overseas markets, equivalent to releasing domestic production capacity to overseas markets to avoid excess capacity.
Taking Chery Group as an example, Chery Group's exports reached 207,800 units in September, creating a new high for a single month's exports by Chinese automakers. In June, July, and August before this, Chery Group's exports also reached 191,000 units, 202,500 units, and 197,000 units respectively, almost sticking to exporting 200,000 units overseas, and as of September, Chery Group's annual export volume has reached over 1.55 million units.

BYD's export volume in the third quarter was also very considerable, reaching 180,000 units in July, nearly 190,000 units in August, and maintaining 180,000 units in September. It is expected that BYD's exports this year will also be around 1.5 million units, equally strong.
In terms of exports, Geely Automobile grew the fastest, with exports around 200,000 units in the first quarter, while by the third quarter this number had increased by more than 50%, exceeding 320,000 units. In addition, Leapmotor became the new force brand with the highest exports, with export data reaching around 160,000 units so far this year.
According to Jiasipai statistics, total sales of all Chinese brands in Europe's major markets (EU27 + European Free Trade Association + UK) for the first eight months of this year were approximately 864,000 units. The UK market alone reached 202,500 units. Sales in the five Southeast Asian countries during the same period were 293,000 units, and Australia had around 257,000 units. Additionally, sales in regional markets such as Mexico, Argentina, Brazil, and Uruguay were also very strong.

Jiasipai statistics showed sales performance of Chinese brands in 39 countries and regions. Among them, Chinese brands entered the top three in 11 countries and regions, and Chinese brands were present in the top ten car brands in 22 countries and regions. Additionally, the market share of Chinese brands exceeded 30% in Uruguay, Israel, Australia, Thailand, and Chile, with the share in Uruguay reaching as high as 57.6%. If we include joint ventures between Chinese brands and Russian local enterprises, the market share in Russia also exceeded 30%.
However, it is worth noting that the current 7 million units of Chinese automaker exports are not actually terminal sales truly realized in overseas markets, but rather the customs declaration perspective of automaker exports. In other words, 7 million units is a wholesale volume to overseas markets. It does not mean overseas markets can truly digest this sales volume; some may still be in ports and at sea, and it will take some time to truly convert into sales.

At the Paris Motor Show that just opened, nearly 20 Chinese complete vehicle brands participated, accounting for one-third of the total participating brands at the Paris Motor Show, and the scale of participation has expanded significantly compared to two years ago. It is worth knowing that even BMW did not participate in this Paris Motor Show, while some Japanese automakers such as Nissan, Suzuki, and Mitsubishi also absented themselves.
This "taking the lead" approach of Chinese brands made European media both excited and concerned. An article in Reuters wrote: "Like other Western motor shows, the Paris Motor Show has been in a state of decline until Chinese car manufacturers began to participate on a large scale four years ago."

02
Tariff Barriers and Trust Scrutiny
It is precisely because Chinese brands are rapidly "conquering" overseas markets that Chinese automakers have started to encounter more obstacles.
In 2024, the EU imposed countervailing duties on Chinese-made pure electric vehicles—added on top of the original 10% tariff, with the rate reaching up to about 35%, but hybrid models became a "gap", resulting in a significant growth in exports of Chinese brand plug-in hybrid models to the EU. After the conclusion of the second regular meeting of the China-EU Trade and Investment Consultation Mechanism recently, one of the results was that "both sides reached an understanding on hybrid vehicle trade in a manner consistent with World Trade Organization rules."
Although neither the China-EU side has revealed specific details about the reached memorandum of understanding, according to Maroš Šefčovič, EU Commissioner for Trade and Economic Security, new measures will reduce the number of hybrid vehicles imported from China by more than half, but this data is based on trade flow and forecasts for the next four years. According to Bloomberg, the quota for hybrid models exported from China may be around 350,000 units, which is indeed close to half of the previously stated figure.

At the same time, the Chinese side has made corresponding arrangements, one of which is "effective from April 1, 2027, the export VAT refund rate for new energy vehicles will be lowered from 13% to 9%." This means that the export profitability of Chinese automakers will be further compressed, and in a certain sense, it restricts the export of new energy vehicles.
More critically, products of Chinese automakers are facing stricter inspection by overseas regulatory authorities.
On October 6, a black Chery OMODA 5 in Malaysia broke its rear axle while driving, causing the wheels on both sides to detach together, luckily no one was injured.
Soon, on October 11, the Malaysia Land Transport Authority (JPJ) announced it would revoke relevant certificates and suspend the registration of new Chery OMODA 5 vehicles. Not only did it stop registration, but relevant Malaysian departments also required Chery to identify risky vehicles according to part numbers, production batches, VIN, and other information; to inspect complete vehicle production and assembly, as well as rear axle parts suppliers; and to verify production quality control, welding joint inspection procedures, and parts safety requirements. The Malaysian JPJ emphasized that only after completing corrective and preventive actions and having the risks properly controlled with JPJ technical confirmation will the suspension of registration measures be lifted.
Chery Automobile also announced the launch of a recall for the affected 8,878 OMODA 5 units to inspect relevant parts and replace them for free as appropriate. At the same time, Chery Automobile also emphasized that it would conduct a special risk investigation for the same batch of OMODA 5 models in domestic and relevant markets.

Of course, the above two cases are just typical examples of Chinese automakers facing obstacles in overseas markets in recent years. Previously, there were also cases such as the Australian Automotive Service and Repair Regulatory Agency (AASRA) issuing compliance warnings to five Chinese new energy automakers, and there were also requirements in places such as Turkey and Thailand for Chinese automakers exporting to local markets to build factories.
In the European market, the significant increase in sales by Chinese automakers has also attracted scrutiny from various parties. Reuters quoted François Roudier, Secretary General of the International Organization of Motor Vehicle Manufacturers, saying: "If they give up exports in Europe, they will die, because they cannot make money elsewhere."
Evidently, European media believe that due to the de facto closure of the US market to the Chinese automotive industry, Europe has become the primary priority market for Chinese automakers, which makes Chinese automakers consider further expanding their market share—some media expect the market share of Chinese automakers in Europe to reach 12% this year and 20% by 2030.
Therefore, for Chinese automakers, they cannot simply "shift sales volume" to overseas markets just because domestic market sales are declining. If the environment and capacity of overseas markets are not carefully considered, and the volume exceeding one-third of Chinese automotive production capacity is placed overseas, this will inevitably trigger "reactive measures" from other countries towards Chinese automakers and will directly create greater obstacles for Chinese automakers in overseas markets.
03
Export Peak Is Coming
Since restrictions on direct domestic exports are continuously increasing, Chinese automakers are also considering building factories locally more and more.
Leapmotor has started production at the Stellantis Spain factory starting in October and is fully prepared for overseas localization production.
BYD plans to start production at the new factory in Hungary in the fourth quarter. BYD Executive Vice President Li Ke became the focus of this Paris Motor Show. In interviews with multiple European media outlets, she revealed that BYD's commitment to Europe is "very deep".

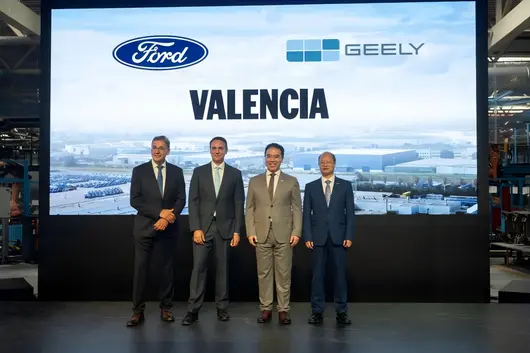
For Geely, the plan to acquire Ford's Spanish factory has been officially approved. Geely will invest €221 million to acquire 34% equity of Ford España, S.L. Afterwards, Ford and Geely will establish a joint venture company to operate the factory together. Geely Automobile plans to produce two pure electric vehicle models at this factory: one may be the EX2, which is the domestic Xingyuan. At the same time, both parties will have a cooperative model—a new Crossover model led by Ford's design and jointly developed by Geely.

Additionally, SAIC Group's first factory in Europe has been confirmed to be located in Spain, planned to start construction in 2027 and start production at the end of 2028, mainly producing MG brand pure electric models. Chery Automobile and the Spanish car company Ebro-EV Motors joint venture company started production earlier this year, allowing Chery to achieve localized production in Europe.
Actually, localized production has become the consensus among Chinese top automakers, after all, high tariffs are difficult for them to bear for a long time, and landing production of pure electric models in Europe is also a path to avoid traditional European automakers.
And with Chinese automakers landing in Europe, the domestic new energy vehicle supply chain will also start its localization process in Europe. The new cell factory of CATL Debrecen in Hungary officially started production, with an annual planned capacity reaching 100GWh, capable of supporting pure electric vehicle models on a million-unit level.

If we follow European media forecasts—if the market share of Chinese brands in the European market reaches over 12% in 2026, then the annual sales of Chinese automakers in Europe in the coming years will be at least over 1.2 million units. After deducting the export quota for hybrid models, the scale of localization can reach around 900,000 units.
From this inference, it is highly likely that Chinese automakers will also land to build factories in other regional overseas markets, including Southeast Asia, Mexico, South America, etc. This makes the nearly 10 million unit level of exports in China in 2026 highly likely to be a peak, afterwards it may stabilize around 6-7 million units. Adding the domestic market, the domestic production capacity demand for China's automotive industry is also in the 20-23 million units range.
Currently, the passenger car production capacity of Chinese automakers is at least 30 million units in scale, which means capacity reduction for domestic automakers is inevitable and must be completed as soon as possible.
(END)
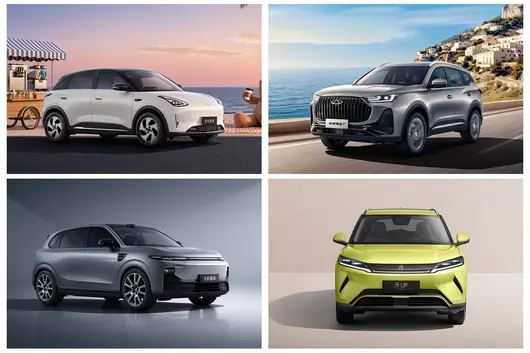
Zhiliao Auto/Chen Yi
Recently, Fortune Magazine released the latest Fortune Global 500 list, Chery Automobile ranked 383rd with revenue of 41.778 billion US dollars.

Actually, Chery was already on the Fortune 500 last year, with an even higher rank then, 233rd. The difference is that this year Chery was evaluated independently as a listed company entity. That is to say, although it has been on the Fortune 500 for two consecutive years, the value is different. This year, Chery needs to undergo comprehensive scrutiny from the capital market and the industrial system.
It is worth mentioning that there are 10 Chinese car companies and automotive parts companies that entered the Fortune 500 this year. In addition to Chery, there are BYD, CATL, Geely, SAIC, etc., all of which are well-known. Among them, BYD has the highest rank, with revenue of 111.853 billion US dollars, ranking 91st.

Domestically, BYD is now the truly deserved "number one". Cars sell well, and profits are high. Last year, BYD's new energy vehicle sales reached 4.6 million, topping global new energy vehicle sales for consecutive years, annual revenue was 804 billion yuan, net profit 32.6 billion yuan.
Moreover, it is willing to invest heavily in R&D. For example, in 2025, BYD invested as high as 63.4 billion yuan in R&D, ranking first among A-share listed companies for two consecutive years. So far, BYD's cumulative R&D investment has exceeded 250 billion yuan.

The key point is that BYD's batteries, chips, motors, electronic controls, etc., are all manufactured by itself. Previously, people thought this "doing everything yourself" model was too asset-heavy and too slow. But facts have proven that as long as you can weather the storm, you can use economies of scale to further reduce costs.
What is BYD's moat? Cost and scale. Others spend 100 yuan to build a car, BYD might only need 80; others sell 100 cars a year, BYD can sell 200.
What about Chery? It is another model.

Starting from 2001, Chery had already started selling cars overseas. At that time, most Chinese car companies were still competing domestically. So strictly speaking, Chery can be considered one of the first batch of "going global" Chinese car companies.
Of course, it was indeed difficult at first. In 2001, Chery's export volume did not even exceed 100 units. But it proceeded steadily, continuously expanding its overseas footprint. So far, Chery's business has covered more than 130 countries and regions worldwide, ranking first in export volume of Chinese brand passenger cars for 23 consecutive years.
Chery's "going global" is not a one-off deal. It has 16 production bases worldwide, with over 3,100 overseas dealer outlets. Local manufacturing networks for Chery exist in places like Brazil, Indonesia, Thailand, Malaysia, etc.

Foreign media summarize Chery's "going global" model as "encircling cities from the countryside", which is not wrong. After all, it first established brand awareness in markets with lower thresholds such as the Middle East, Latin America, and Southeast Asia, selling mature fuel vehicle models like Tiggo and Arrizo, before penetrating into high-regulation markets like Europe.
In 2025, Chery exported 1.344 million vehicles, equivalent to one Chery being sold overseas every 23 seconds on average. Total annual revenue was 300.29 billion yuan, breaking the 300 billion yuan threshold for the first time. Net profit was 19.51 billion yuan, overseas revenue was 157.42 billion yuan.
Simply put, Chery has become a Chinese car company where "half of the car sales rely on overseas markets".

More notably, Chery's overall average vehicle price is about 103,500 yuan, while the overseas average vehicle price is 121,600 yuan. For the same car, selling it overseas is nearly 20,000 yuan more expensive than domestically.
So you see, Chery's success logic is simple: if you can't compete domestically, sell it abroad. The path to success is never singular.
Zhiliao Auto original article, please contact us if you need to reprint.
*Images sourced from the internet, if infringed please contact the author for deletion*

In September, the situation in the Chinese auto market was more severe than expected. Although accurate September sales data hasn't been received yet, according to the China Passenger Car Association (CPCA) data for September 1-27, passenger car sales declined by 29%, with no hot sales scene similar to previous years' 'Golden September and Silver October'. Of course, the reason could also be that September last year was rushing to end subsidies, so sales were at a high level, so in the same period of 2026, it became a significant decline.
However, the good news is that although the domestic market performance was poor, car companies' sales in overseas markets continued to grow, especially the export sales of Chery, BYD, Geely, SAIC Group, Leapmotor, etc. continued to hit new highs, largely filling the domestic gap.
At least from the sales figures, the Chinese automotive industry maintained resilience.
01
BYD continues to sprint, can a monthly scale of 500,000 be achieved?
In September, the number one spot in the Chinese auto market was still held by BYD, with performance leading by a significant margin.
BYD's September sales reached 463,600 units, creating a monthly new high for 2026, with year-on-year growth of nearly 17%, data quite exaggerated. This also shows BYD's sales momentum is still robust, having formed a head effect, and this robustness mainly comes from exports to overseas markets. BYD's September export volume has reached 180,000 units, exceeding one-third of total sales, so overseas sales are an important strategic pivot for BYD.

From a structural perspective, BYD passenger car sales were 456,700 units, continuing the growth trend; among them, pure electric vehicle models were 273,000 units, plug-in hybrid 183,500 units. This data also reflects that 'selling more pure electric vehicles' is indeed a trend in 2026.
At the brand level, the Dynasty Series and Ocean Series totaled 395,000 units, mainly driven by the growth in Yuan UP and Yuan PLUS sales of the Dynasty Series. Regarding the Ocean Series, because the Seagull faces a generational change, the overall scale is slightly smaller. However, considering the all-new Seagull will become a five-seater model, body dimensions are fully increased, and fast charging is supported, it is expected that after listing it will put considerable pressure on Geely Galaxy Xingyuan, and may even allow the Ocean Series to gain growth of over 20,000 units.

Fangchengbao sales in September reached 43,200 units, this doesn't include Fangcheng S series. It is expected that Fangchengbao will move towards 50,000 units afterwards. Denza stabilized at 18,200 units, there was no previous Denza D9 one-time surge. Later N8L pure electric, all-new N8 listing, is also able to continue upward. Yangwang brand sales 389 units. It is said that Yangwang will also launch a flagship model similar to Rolls-Royce Ghost, 2 million level, worth looking forward to.
Clearly, BYD's current strategic focus is twofold: on the one hand to accelerate overseas market growth, on the other hand to push overall sales further up in the domestic market through new cars like Seagull, Fangcheng S, etc., and the popularization of fast charging technology. Currently, BYD is likely to make a push for monthly sales of 500,000 at the end of the year, with annual sales expected to be around 4.3 million units, which is quite difficult in such a tough year of 2026.
02
Geely and Chery: Who will break 300,000 first?
The battle for second place between Chery and Geely is still ongoing. The September sales data released by the two car companies differs by only 140 units. This data can even be ignored, because selling 300,000 units a month by a car company is equivalent to 10,000 units a day. Getting 140 units could be the difference of 10 minutes in working time.
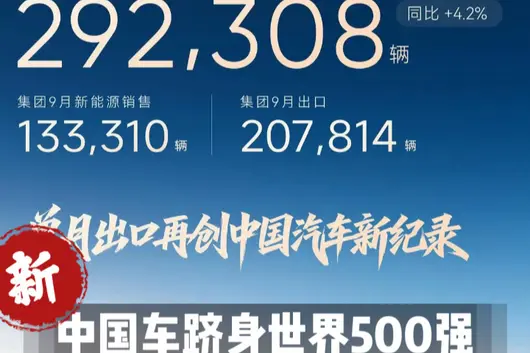
Chery Group September sales reached 292,308 units, but Chery's absolute main force in sales is exports. Chery Group September single-month exports were 207,814 units, up 51% year-on-year, creating a new record for Chinese car single-month exports, data is quite exaggerated. Overall, Chery's January-September cumulative sales reached 2.2068 million units, export sales were 1.5512 million units. Among them, new energy vehicle sales also exceeded 858,000 units. Based on this, Chery is expected to exceed about 3.1 million units this year, with quite excellent performance.

But the problem is also here, over 70% of Chery Group's single-month sales share comes from exports, domestic less than 90,000 units. Once the overseas market changes, such as insufficient transport ship capacity, or certain regions introduce restrictive measures, Chery's sales may fluctuate.
In Chery's brand structure, the Chery brand is the absolute main chunk, sales 198,681 units, mainly relying on Tiggo series and Arrizo series to support, and both domestic and overseas performance are relatively stable. Chery's hard-core off-road and personalized Jetour brand, September sales were 57,497 units, overall relatively stable, but should soon be caught up by BYD Fangchengbao. iCAR brand maintained at the 10,000 level, was 10,858 units, after launching V27 it at least stabilized the state of over 10,000, later there is iCAR V25 to see if it can advance further.

Exeed only has 4,905 units, basically ignorable domestically, this scale is even insufficient to support a press conference or new car R&D. The Luxeed brand September wholesale sales were 5,008 units. This may be related to the delivery rhythm shifting to Luxeed R7 and RX after the bulk delivery of Luxeed V9. As for whether Luxeed can return to the 10,000 level later still needs observation.
Regarding Geely, September sales were 292,200 units, also creating a new high for the year. Actually Geely Auto overall was only 140 units less than Chery Group, can be fully understood as a subtle difference in declaration scope. Such a gap is indeed fierce, but the sales structure of the two is completely different.

Geely Auto's domestic and overseas sales structure is relatively balanced. September domestic sales were about 180,000 units, and exports were 106,685 units. Export sales increased by 162% year-on-year, standing firm on the 100,000 unit stage for four consecutive months. Overall export scale is still only half of Chery's, you can also understand that Geely Auto has a lot of growth space overseas.
Looking by brand, Geely Galaxy sales were around 130,000 units, mainly benefiting from export growth, returned to the growth channel. And Geely fuel vehicle sales also maintained at a high monthly average of 106,000 units. Later there will be Xingyue L PLUS, Xingrui L PLUS and other new cars, estimated to further grow.
Zeekr brand sales 37,216 units, achieved year-on-year doubled growth, has stabilized in the second tier of New Forces, almost on the same line as NIO, Xpeng, Li Auto, and Harmony Intelligent Mobility Alliance. Compared to these brands exceeding 40,000 units, the gap between Zeekr and them is already very small, and Zeekr currently has no new models launched, perhaps in 2027 there will be further changes.

Lynk & Co brand sales 18,493 units, mainly still in the painful period of product transformation, needs to balance gasoline cars and PHEV, naturally not as focused as Zeekr.
Overall, Geely's development momentum is quite balanced and stable. Geely Auto's monthly sales scale this year has not yet broken through 300,000 units, but always can stabilize in the interval of 250,000 to 290,000 units moving upwards, unaffected by external environment, then the probability of breaking through 300,000 units in the fourth quarter is very high. If calculated by monthly average exceeding 300,000 units for the last three months, annual cumulative sales are expected to reach around 3.4 million units, overall on par with Chery, but better in balance. If overseas exports can continue to rise, the result will be more ideal.
It is worth mentioning that both Chery and Geely have recently adjusted their sales management. For example, Geely uses executive vice president level management to manage Lynk & Co brand sales, which may have a positive effect on Lynk & Co brand sales recovery.
Chery's adjustment is even more radical, overseas person-in-charge directly came to unify Chery domestic sales and marketing business. Previously responsible sales executive vice president then fully in charge of Jetour brand. This means Chery now is domestic and overseas one board game, Jetour wants to open a piece of market separately, also can see Chery's craving for the domestic market.
03
New Forces Leapmotor leads by a significant margin, 30,000 units scale to qualify for the list
Regarding New Forces, the number one sales position in September still belongs to Leapmotor Auto, monthly sales maintained at 100,000 level, belongs to leading by a significant margin.
Leapmotor's specific September sales figure was 105,656 units, up 59% year-on-year. This number is already at the same level as Toyota and Volkswagen in the domestic market sales, of course this data also includes export sales. Can also see Leapmotor pushing forward simultaneously on domestic and overseas two lines. As long as it can stabilize the 100,000 unit monthly sales, this year has a chance to impact 1 million units scale, can say Leapmotor's early layout won itself the first ticket on board for New Forces.

Second place is very unexpected - from the data perspective it is Changan Qiyuan. This brand has always been quite low-key, but September sales reached 46,507 units. If no unexpected sales best will still be Qiyuan Q05. This car's performance far exceeded expectations, already rushed up in the 70,000 to 100,000 yuan market interval, can even grab a part of Xingyuan's sales. There is also part of sales from overseas market, so Qiyuan's volume rise speed is quite fast.

Third place is Fangchengbao, September sold 43,181 units total, up nearly 80% year-on-year, data still considerable. After Titanium 7 launched Fast Charging version, pure electric vehicle sales increased very fast, next will launch Titanium 9, overall sales have further space. The information currently known is, Fangcheng S and Fangcheng S GT two car order situations are quite good, price interval in 180,000 to 240,000 yuan, aiming exactly at Xiaomi SU7 price belt. If monthly sales of these two cars can rush up to 8,000 to 10,000 units, it will help Fangchengbao overall sales stable at 50,000 units scale.

Fourth place is Xpeng Auto, September sales were 41,256 units. Currently Xpeng model data has not been released yet, but Xpeng MONA L03 sales are about 14,000 units, accounted for 1/3 of Xpeng's sales.
Xiaomi Auto September sales exceeded 40,000 units, specific data disclosure is limited. Known is Xiaomi Peng Cheng first month delivery exceeded 10,000 units. Actually Xiaomi Peng Cheng's first sales period sales are not as optimistic as expected, it is said Xiaomi internal has already positioned Peng Cheng as slow heating model. But overall, Xiaomi Peng Cheng two new cars still pushed Xiaomi 2026 since first time back to above 40,000, indicating Xiaomi sales still in upward channel.

September Harmony Intelligent Mobility Alliance sales were 37,490 units, among which includes Aito sales. In the fourth quarter Harmony Intelligent Mobility Alliance new car launch will obviously increase, including Luxeed New R7, Luxeed RX, as well as Stelato V8, and Aito M7, M8 new models will also be pushed to market. For Harmony Intelligent Mobility Alliance price is high problem in market feedback, at least Seres has already started for Aito M6 launch three-year interest free, perhaps next Harmony Intelligent Mobility Alliance will also have a volume selling strategy.
NIO company September delivery 37,408 units, only difference dozens of units with Harmony Intelligent Mobility Alliance. Among them NIO brand 21,318 units, Onvo 8,763 units, Firefly created high sales, reached 7,327 units. Now external expectations for NIO are all on end-of-year release of all-new generation ET5 and ES6.
Zeekr September sales 37,216 units, huge increase year-on-year, also narrowed the gap with NIO. However Zeekr quite a part of sales comes from overseas exports. Currently can see, Zeekr in overseas market sales share is very high, including in Malaysia, Thailand etc. all have very high visibility, this mainly benefits from Zeekr priority going overseas, priority develop right-hand drive models strategy.
Hyper Aion September sales 35,494 units. Aion after launching i60, N60 overall performance still quite stable. Later there will be Ray 7 such young car, perhaps can rush a wave again.

Li Auto 31,817 units, down 6.3% year-on-year, main reason is Li Auto i6 is about to switch new car, currently in clearing inventory stage, intermediate will have two months gap. In addition Li Auto i9 is said order situation quite good, almost has filled up Li Auto i8 market demand, expect subsequent Li Auto pure electric models有望 exceed 30,000 units.
Regarding other brands, Deepal Auto sales 30,185 units, MG sales 30,000 units, BAIC New Energy sales 24,080 units, performance stable.
Some brands are still at monthly sales 10,000-20,000 unit level, including Denza sales 18,198 units, Voyah sales 13,025 units, Avatr sales 8,183 units, still not over 10,000.
Overall, September New Forces performance was better than expected, this also squeezed traditional joint venture brand market. Need to note, on this New Forces list, if sales cannot exceed 30,000 units, actually pressure will be very big, including now Changan Auto aspect has started to integrate Deepal and Avatr, just hoping to pull through internal efficiency.
(END)

Chery exported 207,814 units in September. What does this mean — Chinese automotive enterprises exceeded 200,000 units in single-month exports for the first time. Chery's cumulative exports for the first three quarters reached 1.551 million units, already exceeding its own full-year target of 2025.

Data from CAAM: In January–August 2026, China's automotive exports reached 7.153 million units, a 66.7% year-on-year increase, surpassing the 7.098 million units of the full year of 2025. Single-month exports in August hit 1.01 million units, standing at the million-unit mark for three consecutive months; new energy vehicle exports were 526,000 units, a 1.3-fold increase year-on-year — for every two cars exported, one is a new energy vehicle. This proportion has exceeded 50% for three consecutive months.

(Correction on a frequently confused figure: The 52.4% figure represents the proportion of new energy vehicle sales to total vehicle sales from January–August, not the proportion of new energy vehicles in exports; the proportion of new energy vehicles in exports was 52.1% in August single month and cumulative 48.0% for January–August.)
As for the full year? CAAM Vice Secretary-General Chen Shihua said "cautiously optimistic, expected to exceed 10 million units". Cui Dongshu was more optimistic, saying it could reach 12 million units. CAAM's expectation at the beginning of the year was 7.4 million units — far surpassed by actual data.
The top three are very concentrated. In August, Chery exported 197,000 units, ranking first; BYD exported 189,500 units, setting a company single-month record; Geely exported 110,100 units, up 205% year-on-year. In September, BYD overseas exports were 179,900 units, Chery 207,800 units, Geely 106,700 units up 162% year-on-year, Changan 96,200 units up 73.8% year-on-year.

Looking back at this curve, it feels slightly unreal. In 2020, China's automotive exports were only 995,000 units; 2023 was 4.91 million — that year surpassed Japan to become the world's largest automotive exporting country. In 2025, according to CAAM figures, it was 7.098 million. Six years, spanning from the million-unit level to the eight-million-unit level.
Destinations are also shifting. The real change is Europe: In the first seven months of this year, independent Chinese automakers exported 777,000 units to the EU, up 106% year-on-year, becoming the number one regional destination. Data from ACEA shows, in August, Chinese brands held a combined share of 11.3% in the EU and UK markets, compared to only 7.1% in the same period last year; in May this year, five Chinese automakers sold 138,400 units in 31 European countries, six Japanese automakers 130,400 units — monthly sales exceeded Japan for the first time.

What's interesting is plug-in hybrids. EU anti-subsidy tariffs mainly target pure EVs; plug-in hybrids still apply a 10% basic tariff, so automakers are boosting plug-in hybrid offerings. Chinese automakers accounted for 34% of plug-in hybrid deliveries in Europe in June this year, a historic high.
Simply relying on shipping is no longer viable; manufacturing locally is necessary. BYD's Rayong factory in Thailand has a parts localization procurement rate of about 92%; the Brazil factory cumulatively produced 100,000 units by July this year, directly employing 5,500 local workers; Geely has 12 overseas manufacturing plants, and in July also announced a plan to invest €221 million to acquire a stake in Ford's Valencia factory in Spain; Chery took over Nissan's old factory in Spain and acquired Nissan's South Africa factory. Ministry of Commerce data: Chinese enterprises have invested in the automotive manufacturing industry in more than 80 countries and regions, selling cars to more than 200 countries and regions.

But on the other side, the domestic market is collapsing. The first half of the year, domestic car sales were 9.921 million units, down 21.1% year-on-year; passenger car retail sales were 8.701 million units, down 20.2% year-on-year; retail sales from September 1–27 decreased 29% year-on-year. One up, one down. This is the so-called "scissors gap" — passenger car wholesale dropped 5.7%, retail dropped 20.2% in the first half of the year. The nearly 15 percentage point difference was borne by channels and also flowed overseas.
Exports do not come without costs. Net profit margins for leading domestic automakers going overseas are generally below 5%; Toyota and Volkswagen's overseas net profit margins are between 15% and 20%; the vast majority of automakers only make money selling cars; overseas after-sales and auto finance in the aftermarket are nearly blank. Trade barriers are rising: EU anti-subsidy tariffs up to 45.3%; Brazil raised new energy vehicle import tariffs to 35% starting July 1. There is also a risk of concentration — more than 50% of exports are concentrated in the EU, Russia, and Brazil markets. In August this year, the Middle East was affected by geopolitical conflicts, with the UAE experiencing a single-month drop of over 30%.

Therefore, on August 24, the Ministry of Commerce, MIIT, and State Administration for Market Regulation jointly issued the "Guidelines on Overseas Competitive Behavior and Compliance Construction for the Auto Industry". This is China's first overseas compliance guidance document targeting a specific industry. The core point is: Pricing must establish a cost-based, internationally supply-and-demand-oriented strategy, without disrupting market order to gain unfair competitive advantage; when setting MSRPs, clear price gradients must be set for different configurations to avoid frequent and significant price fluctuations that could affect brand image.
To sum up in one sentence: Domestic sales are struggling, overseas sales are booming, but the more it sells overseas, the more likely it is to be targeted.
Going overseas has never been a path of refuge, just swapping to a more difficult exam.
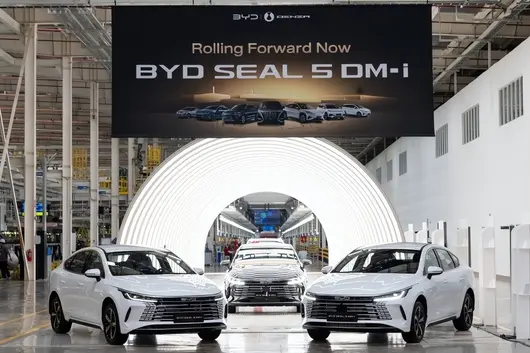
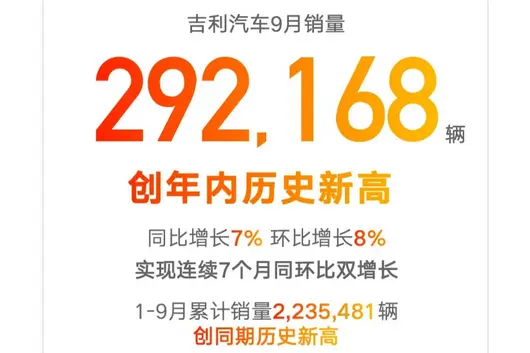
October 1st, Geely Auto announced September delivery data: monthly wholesale sales 292,168 units, up 7% year-over-year, up 8% month-over-month, reaching a new high for the year, and achieving double growth in YoY and MoM for 7 consecutive months; first three quarters cumulative sales 2,235,481 units, reaching a historical high for the same period, which can be said to be a relatively bright report card in the "Golden September".

290,000 Total Volume: Both Fuel / Hybrid Maintain Monthly Sales at 100,000 Level
September New Energy sales 190,868 units, up 16% YoY, accounting for 65% of the total; among which Galaxy 130,479 units, Zeekr delivery 37,216 units, Lynk & Co New Energy 17,039 units, mainstream, premium, luxury three tiers all have incremental growth. However, Geely September China Star sales 105,980 units, up 9% YoY, up 5% MoM, both YoY and MoM still in double growth; first three quarters China Star cumulative sales 873,776 units.
 China Star 100k: Fuel Has Not Retreated, Electrification + Smart Driving Effective
In the September sales breakdown of China Star, Premium series 35,174 units, Boyue Family 25,110 units, Binyue & Binrui Family 28,879 units. Xingrui L PLUS launched pre-sale, adopting i-HEV Smart Engine hybrid; 4th Gen Boyue L equipped with 1.5TD Pro high-power engine and Qianli Haohan H5 assisted driving, function upgrades of over 200 items.
 This is not price cuts to protect gas cars; fuel cars are not competing on displacement and price, but rather bringing HEV, assisted driving, and cockpit infotainment down to the 100,000-150,000 main force price range. In the phase where total domestic gas cars are declining, Geely uses hybrid to reduce fuel consumption and uses smart driving to extend product lifespan, which is an important reason why the gas car foundation can still maintain the 100,000 level.
 AI Going Downward: Qianli Haohan Breaks 1 Million Installations, Gas Cars Also Connected
Qianli Haohan assisted driving September confirmed installation volume breaks 1 million units, growth rate first among independent brands. More realistic than how many are installed is the activation rate 93.8%, daily call frequency is still going up. Before this set was only seen in Zeekr, Lynk & Co high specs, now 4th Gen Boyue L uses Qianli Haohan H5, Xingrui L PLUS also accepted AI driving logic.
 Geely has talked about Domain-wide AI for almost a year, finally landing on 100,000 level gas-hybrid cars. And Geely Smart Charge, single gun peak 2250kW, relying on Xingrui Energy Brain to keep battery temperature within 65°C, solving the problem of fast charging damaging batteries and fast charging not dared to be used
 Exports Break 100k: Consecutive 4 Months Standing at 100k, New Energy Accounts for 70% But Not All
Overseas September exports 106,685 units, up 162% YoY, consecutive 4 months over 100,000 units; first three quarters exports 797,670 units, up 169% YoY. Among which New Energy exports 73,664 units, up 403% YoY, accounting for 69% of exports; first three quarters New Energy exports 484,086 units, up 531% YoY, accounting for 61% of exports.
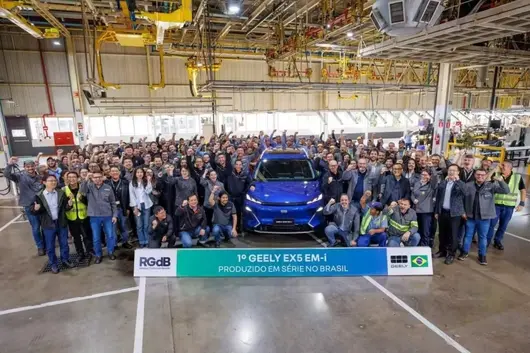
 Zeekr 9X shipped to UAE, pre-sale price equivalent to 800,000 yuan level, 009 in Thailand and Malaysia pure electric MPV continues to lead; Lynk & Co in Ecuador, Tunisia, Mexico focuses on PHEV high-end segment; Geely main brand scales up in Australia, Panama, Brazil, UK. More worth attention is localization, Brazil September production of locally made Galaxy Starship 7 (EX5 EM-i), Lynk & Co Europe from 2027 onwards exclusively distributed by Volvo, Cyprus signs general agent, going overseas shifts from shipping complete vehicles to channel + manufacturing + after-sales.
 Zhang Guan Commentary: Geely Has Its Own Three-Pronged Strategy
Looking at Geely's sales this month, others cut gas cars, it adds hybrid and smart driving to gas cars; others lock AI in models above 200,000 to 300,000, it puts Qianli Haohan into Boyue L this sales-driving gas-hybrid car; others compete on export numbers, it has already established production lines in Brazil, takes Volvo channels to enter Europe. Monthly sales of 290,000 units were not achieved by rushing, but by three strategies not failing simultaneously: gas cars rely on HEV to defend, exports rely on localization to underpin, smart driving relies on high-volume cars to spread costs.
At the Nanning International Convention and Exhibition Center, on the opening day of the 23rd China-ASEAN Expo, SAIC-GM-Wuling's exhibition stands appeared simultaneously in two exhibition halls, the New Energy and Intelligent Connected Vehicle Exhibition Area and the Advanced Technology Exhibition Area. A flagship large six-seater Hua Jing S equipped with Huawei Qiankun technology was parked in a prominent position, next to which was the G20 Summit official vehicle Air ev. Walking further in, models of the three technology brands Tian, Ling, Shen and the I²MS Smart Island Manufacturing System occupied nearly half of the display space.

 Moving the manufacturing system into the auto show is a signal in itself. The theme of SAIC-GM-Wuling's participation this time is called 'Global Wuling Shines in ASEAN', but the core exhibit on the stand was not a single car, but a complete export logic, shifting from product output to full-chain ecosystem output.

This logic was named the Global 5 Global Strategy on site at the Expo. At the press conference, Zhao Xiaobin, Vice President of SAIC-GM-Wuling Motor Co., Ltd., did the math: cumulative global production and sales exceeded 32 million units, New Energy vehicle sales exceeded 4 million units, overseas exports grew for 10 consecutive years, cumulative exports exceeded 1.6 million units/sets. "From initially borrowing ships to go to sea, to today relying on the New Land-Sea Corridor in Western China, intelligent manufacturing, and green manufacturing advantages," he said, "we are no longer just selling cars overseas."

The '5' in Global 5 has five layers of meaning. Shi Jiangong, Vice President of SAIC-GM-Wuling's Overseas Division, broke down the implementation path of this strategy at the press conference: Five major strength bases, Five open cooperation models, Five major service guarantee systems, Five major regional market layouts, Five major development goals.

Among these, the design of the cooperation mode is most noteworthy. For the development stages and policy environments of different markets, SAIC-GM-Wuling launched five models: trade, distribution, production and sales, full industrial chain, and technology licensing, from shallow to deep, partners can choose freely. This means going overseas is no longer a single 'selling cars' logic, they can do only trade, build distribution networks, establish joint ventures, move the entire industrial chain over there, or even only output technology.
Supporting this flexibility is 'Five-Chain Collaboration': Smart Manufacturing Chain, Supply Chain, Sales Chain, Talent Chain, Financial Chain. Shi Jiangong summarized it as 'systematically transforming full-link self-research and self-construction capabilities into overseas market competitiveness'. Specifically on the product side, it is a full-category layout covering SUV, MPV, micro transportation, urban new energy, commercial vehicles, and other scenarios; on the technology side, it is the 'Tian-Ling-Shen' technology system; on the manufacturing side, it is the globally first I²MS Smart Island Manufacturing System, this system breaks the assembly line production method used for a century.

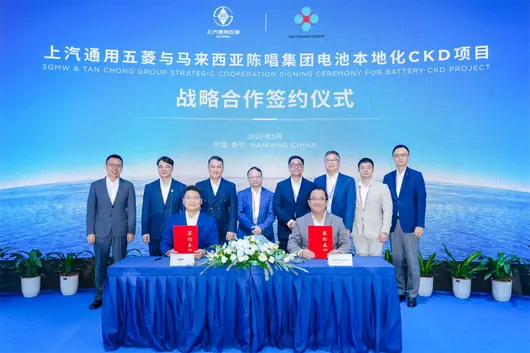
On the day the strategy was released, the first landing project was signed. SAIC-GM-Wuling signed a deep strategic cooperation agreement with Malaysia Chan Tong Group, launching the Malaysia localization industrial layout. Liu Zhijun, Director of the Marketing and Service Department of Liuzhou Sake Technology, and Yun Weishan, General Manager of TQWULING, signed on behalf of both parties. Shi Guoyong, Member of the Party Committee of SAIC-GM-Wuling, Party Secretary of Liuzhou Sake Technology, and Vice President, Executive Vice President Huang Yaosong, Vice President Zhao Xiaobin witnessed it together.
The key of this signing was not in the complete vehicle, but in the supply chain. Relying on the core parts supply chain going overseas, SAIC-GM-Wuling will build a local independent supply chain system in Malaysia. This is exactly the typical path from 'product going overseas' to 'ecosystem going overseas', not transporting cars made in China to sell there, but taking manufacturing capabilities, supply chain systems, talent, and financial services together over there, forming an industrial loop locally.

On the same day, a think tank report was also released. SAIC-GM-Wuling collaborated with People's Forum, inviting three industry experts to jointly release the 'New Paradigm for Collaborative Overseas Expansion of Green Manufacturing and Automotive Industry'. The report refined SAIC-GM-Wuling's practice into three major paths: 'New Quality Ecosystem, New Quality Brand, New Quality Product', and specifically mentioned the deep binding of corporate globalization paths with Guangxi's 'Beijing-Shanghai-Guangdong R&D + Guangxi Integration + ASEAN Application' development path.
Zhang Lei, Director of the Artificial Economy Research Room of the Institute of Economics, Chinese Academy of Social Sciences, said at the press conference, SAIC-GM-Wuling, through Five-Chain Collaboration, systematically transformed domestically accumulated technology, manufacturing, and supply chain advantages into global competitive advantages. Zhou Changping, Executive Vice President of the National Bamboo Industry Research Institute, paid attention to another detail: SAIC-GM-Wuling led the integration of the country's first auto parts 'Bamboo instead of Plastic' full industrial chain. Zhao Xinli, Dean of the School of Advertising and Branding at Communication University of China, interpreted from a brand perspective, believing that SAIC-GM-Wuling broke the low-end prejudice of overseas markets against Chinese brands with high cost-performance and deep scenario adaptation.


Looking at these pieces of information together, the goal of the Global 5 strategy becomes clear. According to the plan, SAIC-GM-Wuling will take ASEAN as a bridgehead, deepening the layout of five major markets in Asia, Africa, America, Europe, and Oceania, covering 150 countries in 3 years, expanding 500 strategic partners, achieving an annual sales growth rate of 50%, finally becoming a world leader in new energy brands and a pioneer in industrial upgrade and green development. Zhao Xiaobin called this layout the 'Two Wings Flying Together' of 'Wuling Development Wing' and 'Wuling Partner Wing'.
China's automotive overseas expansion has gone through several stages. Earliest was complete vehicle export, comparing who's cars were cheaper; later was building factories, doing localization, comparing who has stronger manufacturing capabilities; now it has reached the third stage, outputting standards, outputting supply chains, outputting ecosystems, comparing who can move a whole system overseas and make it run. What SAIC-GM-Wuling displayed at this ASEAN Expo, is exactly a sample of this stage.
Facing the '15th Five-Year Plan', how far this system can go depends on the actual landing effect of Five-Chain Collaboration in the overseas market, and also depends on whether the five cooperation models can truly adapt to the differentiated needs of different countries. But at least looking from the stand in Nanning, the narrative of China's automotive overseas expansion has changed, no longer 'where our cars are sold', but 'where our systems are operating'.
The domestic new energy passenger car market structure is stabilizing, with multiple independent automakers continuing to expand their overseas market layout. July China new energy passenger car export destination data objectively presents the current overseas layout status of domestic new energy vehicles. The top ten export destinations this time cover five major regions: Europe, Oceania, Southeast Asia, East Asia, and Latin America, showing obvious characteristics of a diversified market layout.

From export data, the UK is the top destination for China's new energy passenger car exports in July, with monthly exports reaching 51,300 vehicles, representing a significant overseas market scale. The UK continues to promote the replacement of fuel vehicles, with steady release of demand for new energy passenger cars. Local consumer groups are gradually increasing their acceptance of pure electric and plug-in hybrid vehicle models.

Exports to the UK primarily consist of home-use pure electric SUVs and mid-size new energy sedans. Domestic common models such as the BYD Dolphin and Yuan Plus enter local channels, supplementing the mid-range new energy passenger car market supply. Compared to domestic European automaker products, domestic models differ in cockpit configuration and basic function layout, adaptable to the regular vehicle needs of ordinary families.
Belgium ranks second on the list with an export volume of 48,600 vehicles, with a relatively small sales gap compared to the UK. Affected by geographic location, the Port of Antwerp in Belgium is a major automotive transit hub in Europe. Domestic new energy vehicles arriving there are partially used for local terminal sales, while the rest are diverted to neighboring EU countries. This is the main reason for the relatively large volume of imported Chinese new energy vehicles in the country.
Models exported to the European region are mainly long-range pure electric passenger cars, suitable for long-distance travel across cities and regions in Europe. This includes many XPeng pure electric sedans and SUVs with moderate domestic retention. Currently, many European countries have implemented new energy transformation-related policies, providing a basic market environment for imported new energy models. Dynamic adjustments to regional trade rules and carbon emission standards will increase the overseas operating costs of domestic automakers, and long-term expansion of the European market involves certain uncertainties. Apart from the UK and Belgium, Spain and Italy also make the top ten export list. Europe remains the core region for domestic new energy passenger cars going global.
Oceania market expands steadilyAustralia ranks third on the list, importing 39,700 Chinese new energy passenger vehicles in July. Australia's traditional automotive market has long been dominated by large-displacement fuel SUVs, with new energy model penetration rates generally lower than in Europe. In recent years, local consumption structure has gradually adjusted, and new energy model market capacity has increased.

Domestic models exported to Australia are concentrated in large-space pure electric SUVs. Models on sale such as the BYD Tang and Haval Xilong have batched into the local market, fitting local consumer preferences for large-size vehicles. Vehicle range parameters can meet the needs of long-distance travel between Australian cities, and the overall export scale maintains steady growth. Compared to the European market, Australia's vehicle import access rules are relatively relaxed, belonging to an overseas market with growth potential.
Currently, multiple domestic automakers have included Australia in their overseas layout scope, continuously investing in models on sale. As the local market's understanding of new energy models gradually improves, the subsequent capacity changes in this market have continuous observation value.
The Southeast Asia region showed stable growth in this export list. The Philippines, Thailand, and Indonesia all made the top ten exports. Among them, the Philippines imported 36,400 units in July, ranking fourth. Sales volume was higher than Thailand and Indonesia.

Southeast Asia has a huge population base, and the automotive consumption market is in a growth phase. Local fuel vehicle usage costs are relatively high, while new energy passenger cars have certain advantages in usage costs. The Philippines focuses on short-distance urban commuting. Imported models are mainly small and medium-sized pure electric sedans and small SUVs. Models like the BYD Seagull fit the local mainstream travel needs.
Thailand, as an automotive industry gathering place in Southeast Asia, imported 27,200 Chinese new energy passenger vehicles in July. Local authorities continuously issued new energy industry support policies to promote electrification. Multiple domestic automakers have established local production systems in Thailand, reducing tariff costs and expanding the Southeast Asia market through local production and sales models. Released models cover mainstream categories on sale such as MG and Neta brand home sedans and mid-size SUVs.
Indonesia imported 15,400 units in July. The country has abundant upstream resources for power batteries. The local government relies on the new energy vehicle industry to improve the local industrial chain, attracting overseas automakers to invest locally. As local charging infrastructure continues to improve, the Indonesian new energy vehicle consumption market has expansion potential. The hot and rainy climate characteristics of Southeast Asia place higher requirements on vehicle battery protection and body sealing processes. Overseas automakers need to complete targeted vehicle calibration to ensure stable product operation.
East Asian and Latin American markets achieve breakthroughsSouth Korea ranks sixth on the list, importing 17,800 Chinese new energy passenger vehicles in July. South Korea has a complete vehicle manufacturing industry. The new energy passenger car market competition atmosphere is strong. Domestic models achieving stable batch exports reflect the phased progress of independent brands in this overseas market.

Domestic models exported to South Korea are mostly high-spec pure electric SUVs. NIO and XPeng SUV models gradually enter local channels, cutting into the local market relying on basic configurations and reasonable pricing systems. At the same time, South Korean vehicle safety standards and import certification systems are relatively strict. Market access thresholds are high, and subsequent market development involves certain difficulties.
Mexico ranks tenth on the list with an import volume of 12,100 vehicles, and is the only Latin American country in the top ten list this time. Mexico is adjacent to the North American market. The regional circulation conditions are special. In addition to local terminal consumption, imported vehicles have certain cross-regional circulation space. Models exported to Mexico are mainly compact pure electric passenger cars. Multiple domestic home-use models enter local channels, adaptable to urban commuting, suburban travel, and other diverse scenarios. The popularization progress of new energy vehicles in Latin America is relatively slow. Mexico is an important node for domestic new energy vehicles entering the Latin American continent, with the possibility of radiating surrounding areas.

Comprehensive July overall export data shows that dependence on a single market for domestic new energy passenger cars going global continues to decrease. Europe maintains a stable export volume. Southeast Asia and Oceania market sales steadily increase. East Asia and Latin American markets gradually open up. The going-global pattern of multiple regions in parallel gradually takes shape.
At the same time, vehicle usage habits and travel scenarios differ in different regions. Domestic-adapted vehicle configurations and functions cannot fully adapt to overseas market needs. Automakers need to complete localized adaptation of infotainment system languages, maps, chassis calibration, and basic driving assistance functions based on local road conditions and needs. In addition, the global trade environment has fluctuations. Some regional trade protection tendencies have risen. Tariff adjustments, trade investigations, and other factors continuously impact automaker export business. The construction cycle of overseas after-sales service systems is relatively long. Repair outlets and parts supply chain construction speeds are difficult to match sales growth speeds. Terminal service breakdowns may easily occur, affecting the market reputation of domestic cars abroad.
The journey towards globalization continuesThe global automotive electrification transformation trend remains stable. Overseas traditional fuel automakers' transformation rhythm is relatively slow, leaving corresponding market space for domestic new energy automakers going global. Domestic new energy vehicles have a complete industrial chain covering batteries, motors, electronic controls, and vehicle manufacturing. Perfect industrial supporting conditions constitute the basic support for automakers' layout of overseas markets.

If automakers want to carry out overseas business stably, they need to shift from single-product output to full-dimension localized layout, perfecting the overseas R&D, production, sales, and after-sales full-chain system. Currently, multiple automakers have launched overseas factory construction. Through local production to reduce the impact of tariffs and adapt to local policies and consumer culture, it is the main direction for domestic automakers' global development.
July new energy passenger car export data shows the UK and Belgium support the core European market. Oceania and Southeast Asia sales grow steadily. Mexico becomes an important channel to enter the Latin American market. Cross-continental export sales networks are preliminarily formed.
For domestic new energy automakers, overseas markets are no longer just a supplement to the domestic market, but will form an impact on corporate long-term operations. Subsequent monthly export data, regional market sales fluctuations, overseas access rule adjustments, are all worth the industry's continuous tracking to observe the long-term trend of domestic new energy vehicle global development.

If we draw a curve of the past 20-plus years of Chinese automotive overseas expansion, the earliest comparison was "whether there is one", later it was "how many", and by today, the real question separating the competition has become: Is a Chinese car first built domestically and then sold globally, or is it defined from the very first day of project initiation according to global users, global regulations, and global environments?
These are two completely different concepts. The former is exports, testing channel, cost, and product competitiveness; the latter is true globalization, testing whether a car manufacturer can build a cross-market operating system in R&D, design, testing, manufacturing, services, and even local operations.
At the newly opened 2026 Chengdu Auto Show, Chery once again took the theme "Chinese Cars, Global Champions", with Chery, Exeed, Zongheng, Jetour, and iCAR five major brands and 38 models collectively appearing. Compared to the massive product lineup, what is more noteworthy is that this time Chery repeatedly emphasized one keyword—"Global Car".

From Fengyun T7 and Fengyun A9 to the all-new QQ3 and Arrizo 7, the role these products bear is no longer just that of "export vehicles", but they are trying to answer a new question: After Chinese cars enter the deep waters of globalization, what kind of car deserves the three words "Global Car"? This question is important because Chinese car overseas expansion has reached a stage where standards must be redefined.
In the past few years, the scale of Chinese car exports grew rapidly, "how many countries to sell to" and "how many vehicles exported" were once the most intuitive indicators of globalization. But sales can prove market breakthroughs but not necessarily equal global capability.
A true global car, first of all, cannot just be "domestic version + overseas adaptation". The differences between different markets are far more complex than left-hand/right-hand drive conversion and language switching. European consumers are used to high-speed driving, the Middle East faces long-term high temperatures, Southeast Asia is humid and rainy, and the Nordic region has extreme cold, darkness, and icy environments; consumers in different countries have obvious differences in steering feel, physical buttons, interior materials, lighting methods, and even parking habits. That is to say, the real difficulty of a global car is not "selling the same car to more places", but how to use a product system to respond to the real needs of different markets simultaneously.

Fengyun T7 is a relatively typical example. According to the definition given by Chery, it does not modify for overseas markets after development is completed domestically, but unfolds according to global needs from the product project initiation phase. The project researched global regulations two years in advance, designed benchmarking the 2026 version E-NCAP standards, and conducted surveys around 15 typical countries and more than 5,000 global users, incorporating real needs from different regions into product definitions in advance.
Some details particularly explain the problem. For example, Thai users prefer a heavier steering feel, so the vehicle increases steering force accordingly; Indonesian road conditions have many bumps, so the steering wheel return feel is optimized; Southeast Asia, South Africa, and Australia/New Zealand regions have intense sunlight, so low-reflection materials are used in the steering wheel and center control area; Turkish and Israeli users are more used to physical operations, so physical buttons are retained for high-frequency functions; European users more often park nose-first, so the vehicle automatically displays the front camera when approaching obstacles.
Looking at these functions individually, it is hard to call them "showing off technology", and they might not even appear in a core parameter table. But it is precisely these seemingly insignificant differences that constitute the true threshold of a global car. Because the essence of globalization is not to require global users to adapt to a Chinese car, but for the product to actively understand users in different markets.
This logic also permeates the vehicle verification phase. Fengyun T7 accumulated test mileage exceeding 6 million kilometers, covering 100-plus types of environments and road conditions such as the EU, Australia/New Zealand, Middle East, South Africa, Mexico, Brazil, and others. From Southeast Asian rainy seasons and Middle Eastern high temperatures to Siberian low temperatures, Brazilian gravel roads, and Mexican cobblestone roads, the meaning of testing has gone beyond simply proving whether a vehicle "is durable", but rather trying to move the real environments a vehicle might face in the future into the R&D cycle as much as possible.
This actually also indicates that Chinese automotive globalization is crossing a new threshold. In the past, Chinese brands overseas expansion relied on "product power + cost-effectiveness"; what will increasingly determine how far a brand can go in the future is global regulations, global quality, global verification, and global user understanding capabilities. In other words, sales prove whether you have entered a market, while system capability determines whether you can stay in that market long-term.

What Fengyun A9 represents is another dimension of globalization. For a long time, Chinese cars have faced a problem in design: how to establish their own cultural expression while avoiding falling into excessive symbolization; how to conform to global aesthetics without becoming followers of mature luxury brand design languages.
The "Oriental Originality, Global Aesthetics" emphasized by Fengyun A9 is exactly trying to answer this question. Taking Oriental aesthetics as a starting point, but not simply stacking so-called traditional elements, it attempts to translate the Oriental understanding of lines, proportions, and artistic conception into a more modern and universal automotive design language. Winning the 2026 German Red Dot Product Design Award, of course, is only an external certification, but the significance behind it lies in: Chinese brands beginning to attempt moving from "adapting to global aesthetics" to establishing their own global aesthetic expression.
This step is not easy. Technical parameters can be caught up, configurations can be downgraded, but design recognition and brand awareness require longer accumulation. A truly global brand must eventually not only have product output but also possess its own aesthetic and cultural expression.

Beyond this, the all-new QQ3 provides another observation sample. QQ was once one of the most representative products in the Chinese small car market. Today, the all-new QQ3 re-emphasizes personality, fashion, and user expression, and is gradually entering markets in Southeast Asia, South Asia, South Africa, etc., cumulatively winning global 1.6 million users, bearing a role beyond just a commuting tool.
Europe has MINI and Fiat 500, Japan has its own K-Car culture, and Chinese small cars were more often given the label of "economical and practical" in the past. Today, the QQ series is outputting personalized, youthful lifestyles to the global market again, which is in a certain sense also a microcosm of Chinese automotive culture beginning to go global. Because a truly mature automotive industry ultimately outputs not only vehicles but also the lifestyle and cultural identity formed around automobiles.
Arrizo 7 has taken the matter of "Global Car" to a more mainstream price range. This new car positioned for the 100,000 yuan tier market, developed according to global standards from the very beginning of project initiation, and simultaneously provides fuel and hybrid powertrains. The important signal it releases is: global standards should not belong only to high-end models, nor should it only be the value-added nature of export products. Only when global safety, global verification, global aesthetics, and global quality gradually enter the mainstream market accessible to ordinary consumers, can "Global Car" truly have the opportunity to change from a brand label to a common product capability.
And the fact that Chery can take "Global Car" as today's core proposition is also inseparable from more than 20 years of overseas accumulation.

As of the end of July 2026, Chery Group's cumulative global users have broken through 20.16 million, of which overseas users exceed 6.99 million; in July this year, the group's single-month exports exceeded 200,000 vehicles, January to July cumulative exports broke 1.14 million vehicles, products entered more than 130 countries and regions globally.
But what is more noteworthy than export scale is the change in Chery's globalization method. Currently, Chery's overseas employees exceed 20,000 people, of which local employees account for 85%. From Spain to South Africa, Chery is promoting local production, local employment, and local supply chain construction. This means that the relationship it has with overseas markets is gradually moving from the past simple "produced in China, sold overseas" to deep integration of R&D, manufacturing, talent, supply chain, and market operations.
This is also the real problem that Chinese automotive globalization's next stage must face. Export volume is still important, but it is increasingly like a result. What truly determines a company's global competitiveness is whether it can convert global user needs into product definitions, transform regulations of different countries into R&D standards, turn complex environments into verification systems, and then incorporate local manufacturing, local talent, and local operations into the same global system.

In this sense, "Global Car" has never been a model label, but the ultimate projection of a car manufacturer's global capabilities. In the past more than 20 years, Chinese automobiles have completed the transition from "going out" to "selling out"; but today, the real competition has become how to move from "selling globally" to "built for the globe".
Chery has ranked first in Chinese brand passenger car exports for 23 consecutive years, giving it enough long-term global market experience. But what is more noteworthy than "exports first" is that it is trying to take the more than 20 years of globalization accumulation and re-settle it into a standard that can enter product definitions, R&D, and manufacturing systems.
So looking at "Chery is a Chinese car, but more importantly a global car" today, what it really wants to express might not be so simple as "Chinese cars have gone global". More importantly, Chinese cars are beginning to answer a question that long-term defined by multinational car companies in their own way: What kind of car can truly belong to the globe.
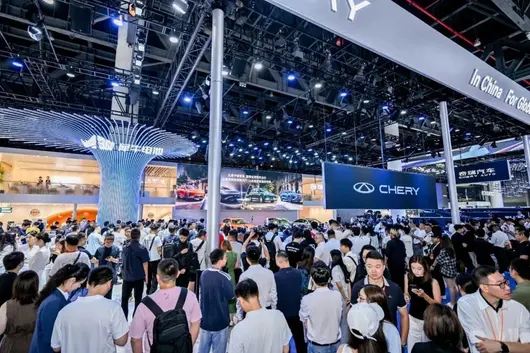
Chery was the first to break the traditional path of "domestic model modifications for export", establishing a new development model for "native global vehicles": From the very first day of product definition, it conducts forward development targeting global market user needs. Safety standards, durability verification, usage scenarios, etc., are based on the highest global requirements. No longer making "fast-moving consumer goods", but "durable goods, works of art".
This concept is being translated into solid market performance.
OMODA&JAECOO dual brands launched only three years ago, global cumulative sales broke 1 million vehicles; entered the UK market less than two years ago, cumulative sales immediately broke 100,000, with JAECOO 7, JAECOO 5, OMODA 5 three models entering the UK top 10 best-selling car list.
LEPAS L6 successfully launched in South Africa and Thailand, its domestic homologous model "native global vehicle" Fengyun T7 directly benchmarks 2026 version European 5-star safety standard, just launched in August, 24-hour orders broke 23,188 vehicles, verifying the "one platform, global blooming" R&D path.

Picture shows LEPAS L6
Energy Switch: For every 7 new energy vehicles exported from China, 1 is from Chery
While scale continues to climb, the export product structure of Chery is undergoing profound transformation, new energy vehicles have become the "powerful engine" driving growth.
January-August, Chery Group new energy exports exceeded 450,000 vehicles, year-on-year growth 136.8%, growth rate exceeding the overall market. According to China Passenger Car Association data, January-July, Chery New Energy cumulative export volume ranked second in the industry; since April, monthly new energy exports have continuously been firmly in the top two of the industry.

Picture shows global best-selling model JAECOO 7
A more convincing number: Currently, for every 5 cars exported from China, 1 is from Chery; for every 7 new energy vehicles exported, 1 is from Chery.
The explosion of new energy exports is not accidental. From LUXEED V9 refreshing the 500,000 level new energy MPV fastest delivery record, to Freelander 8 pre-sale 48-hour orders breaking 10,000, to Fengyun T7 exploding the pure electric SUV market with 24-hour 23,000 orders — Chery is using "hit new energy matrix" to cover all global niche tracks. New energy vehicles have become Chery's new business card for going global, also showing the new image of Chinese automotive technology brands in the global market.
Market Breakthrough: UK Overall Runner-up, Australia Top Three
Chery's export market layout has also achieved breakthrough from emerging markets to global high-regulation markets.
Europe as one of the most stringent automotive regulation markets globally, has become Chery's high-quality overseas export core position: January-July, Chery in Europe 24 countries cumulative sales exceeded 208,000 vehicles, year-on-year growth 201%; among them new energy sales reached 102,000 vehicles, year-on-year big increase 332.47%. In the UK, since March Chery has continuously firmly held the monthly car sales total list runner-up; in Australia, July single-month sales have already entered industry top three.

Picture shows Chery Group overseas vehicles about to board ship
High-regulation market breakthrough means Chery's product power is being verified in the world's pickiest markets, and also further promoted global weight improvement. According to China Passenger Car Association director Cui Dongshu's statistical analysis, January-July, Chery Group world sales share increased to 4.2%, ranked ninth globally. From "China Export Champion" to "Global Sales Share Top Ten", Chery has determined new coordinates in the global automotive industry pattern.
Beyond Business: Globalized "Chery Path"
Beyond business expansion, Chery simultaneously doing another thing: carving "long-termism" into every step of globalization.
August, Chery in partnership with World Conservation Union (IUCN) in Spain launched "Cherish Nature" second phase ocean ecological protection activity, focusing on Posidonia seagrass ecosystem restoration and protection — this is one of the UN-recognized global most important blue carbon ecosystems. Relying on recycled aluminum low-carbon material technology, multiple countries global biodiversity protection projects, social emergency rescue public welfare practices, etc., Chery also won 2026 Chinese Automotive Industry Sustainable Development Practice Cases "Green Development" "Smart Innovation Technology" "Harmony and Shared Benefit" three major honors.

Picture shows Chery Group working with IUCN to carry out Mediterranean Posidonia seagrass monitoring activities and seminars
At the same time "going out" "integrating in", embracing the world, contributing to the world — this is the true moat behind 7 million vehicles.
From 2001 to 2026, from 10 vehicles to 7.18 million vehicles, Chery 25 years of overseas journey is Chinese automotive speeding up globalization vivid microcosm. 7 million vehicles is milestone, even more so new starting point. Chinese automotive new overseas chapter, is writing in every global market.
At the moment the 7,000,000th “Chery-built” vehicle boarded the ship at the port, a new chapter was added to the history of Chinese automobiles "going global".
In August 2026, Chery Group's single-month exports reached 196,984 units, a year-on-year increase of 52.1%, continuing to firmly rank first in Chinese automobile exports; cumulative exports from January to August totaled 1,343,334 units, a year-on-year increase of 68.1%. Calculating down, on average, one “Chery-built” vehicle heads overseas every 16 seconds. Thus, Chery Group's global cumulative sales surpassed 20.44 million units, among which overseas cumulative sales exceeded 7.18 million units, becoming the first Chinese auto manufacturer to cumulatively break through exports of 7 million units.
From 2025 to the present, Chery has successively claimed the three "firsts" records of cumulative Chinese auto manufacturer exports reaching 5 million, 6 million, and 7 million units, completing three million-level leaps in just 14 months. Behind ranking first in Chinese brand passenger car exports for 23 consecutive years, lies Chery's systemic breakthroughs in dimensions such as product development, business structure, market layout, and overseas expansion concepts, exploring a globalization path for Chinese enterprises from "going out" to "integrating in".

Product Evolution: From "Revised Models for Export" to "Native Global Cars"
What Chery first broke was the traditional path of "domestic models revised for export", establishing a new development model of "Native Global Cars": from the first day of product definition, it conducts positive development facing global market user needs, with safety standards, durability verification, usage scenarios, etc., benchmarking the highest global requirements ———— not making "fast-moving consumer goods", but making "durables, artworks".
This concept is being converted into solid market performance.
OMODA&JAECOO dual brand launch was only three years ago, global cumulative sales exceeded 1 million units; having entered the UK market for less than two years, cumulative sales broke 100,000 units, with the three models JAECOO 7, JAECOO 5, OMODA 5 joining the top 10 best-selling models in the UK.
LEPAS L6 was successfully launched in South Africa and Thailand, its domestic homologous model "Native Global Car" Fengyun T7 directly benchmarks the 2026 European 5-Star Safety Standards, launched in August, 24-hour orders broke 23,188 units, validating the R&D path of "One Platform, Global Success".

Image shows LEPAS L6
Power Switch: For Every 7 New Energy Vehicles Exported from China, 1 Comes from Chery
While scale continues to climb, the product structure of Chery's exports is undergoing profound changes, New Energy Vehicles have become the "powerful engine" driving growth.
January to August, Chery Group New Energy Vehicle exports exceeded 450,000 units, year-on-year growth 136.8%, growth rate exceeded the overall market. According to China Passenger Car Association data, January to July, Chery New Energy Vehicle cumulative export volume ranked in the top two in the industry; since April, monthly New Energy Vehicle exports have continuously maintained the top two in the industry.

Image shows Global Best-Selling Model JAECOO 7
A more convincing number: Currently, for every 5 cars exported from China, 1 comes from Chery; for every 7 New Energy Vehicles exported, 1 comes from Chery.
The explosion of New Energy Vehicle exports is not accidental. From Luxeed V9 breaking the 500,000-level New Energy Vehicle MPV fastest delivery record, to Freelander 8 pre-sale 48-hour orders breaking 10,000, to Fengyun T7 exploding the pure electric SUV market with 23,000 orders in 24 hours — Chery is using a "Blockbuster New Energy Vehicle Matrix" to cover all global niche tracks. New Energy Vehicles have become Chery's new card for going global, also showcasing a new technical brand image for Chinese automobiles in the global market.
Market Breakthrough: UK Overall Rank 2nd, Top 3 in Australia
Chery's export market layout has also achieved a breakthrough from emerging markets to global high-regulation markets.
Europe, as one of the markets with the strictest global automotive regulations, has become the core position for Chery's high-quality global expansion: January to July, Chery's cumulative sales in 24 European countries exceeded 208,000 units, year-on-year growth 201%; among which New Energy Vehicle sales reached 102,000 units, year-on-year increase 332.47%. In the UK, since March Chery has continuously maintained the second place in the monthly car sales total ranking; in Australia, July's single-month sales have entered the top 3 in the industry.

Image shows Chery Group export vehicles about to board ship
The breakthrough in high-regulation markets means Chery's product power is being verified in the world's most picky markets, and further promotes the increase of global weight. According to Cui Dongshu, head of the China Passenger Car Association, January to July, Chery Group's world sales share increased to 4.2%, ranking ninth globally. From "Chinese Export Champion" to "Top 10 Global Sales Share", Chery has established new coordinates in the global automotive industry landscape.
More Than Business: The "Chery Path" of Globalization
Beyond business expansion, Chery is synchronously doing another thing: engraving "long-termism" into every step of globalization.
In August, Chery in conjunction with the International Union for Conservation of Nature (IUCN) launched the second phase of "Cherish Nature" marine ecological protection activity in Spain, focusing on the restoration and protection of the Posidonia seagrass ecosystem — this is one of the globally most important blue carbon ecosystems recognized by the UN. Relying on recycled aluminum low-carbon material technology, biodiversity protection projects in multiple countries globally, socialized emergency rescue public welfare practices, etc., Chery also won the 2026 China Automotive Industry Sustainable Development Practice Cases "Green Development", "Innovative Technology", "Harmonious Benefit" three major honors.

Image shows Chery Group working with IUCN to carry out Mediterranean Posidonia seagrass monitoring activities and seminars
Integrating in while going out, embracing the world, contributing to the world — this is the true moat behind 7 million units.
From 2001 to 2026, from 10 units to 7.18 million units, Chery's 25-year journey of going global is a vivid microcosm of Chinese automobiles accelerating globalization. 7 million units is a milestone, more so a new starting point. The new chapter of Chinese automobiles going global is being written in every market globally.
These days, breaking 100,000 units in single-month domestic sales is already big news. But for Geely's overseas market alone, 110,094 units were sold in August, a year-on-year surge of 205%. If only one month looked impressive, it could be attributed to luck. But maintaining sales above 100,000 units for three consecutive months indicates only one thing: Geely's globalization has truly hit the accelerator. Even more exciting, Geely casually raised its 2026 overseas sales target from 640,000 to 920,000 units, aiming to surge past 1 million. Some feel this stride is too big, but after analyzing the overseas battle reports, my conclusion is: This isn't a bluff, it's confidence.

I. Behind Breaking 100,000 Exports, New Energy is the Ace
Checking Geely's August export bill, the most impactful part isn't the total volume, but the structure: New energy exports hit 70,629 units, surging 446% year-on-year, accounting for a high 64% of exports. This means what Geely sells best overseas isn't "cheap and generous" low-end fuel cars, but NEVs with higher technical content. Overseas market response is direct enough: From Jan-July, ZEEKR topped Australia's luxury pure electric sales chart, and sat firmly as the luxury pure electric sales champion in Malaysia; Lynk & Co 08 took the top spot in Tunisia for high-end PHEV sales; Geely Xingyuan won the championship in Thailand and Jordan, and also broke into the top three in Mexico's pure electric market. Look at data before discussing going global, this is globalization that can fight, not just raising a fuss with low prices.

II. From Selling Cars to Rooting Down, Geely Plays a Big Game
Geely's current going-global strategy is long past the days of just dragging cars to the port and calling it a day. In the European direction, it officially announced entry into Austria, sales outlets in Spain broke 50, and Xingyuan also stormed into France; In the Latin America direction, Lynk & Co landed in Argentina, Lynk & Co 01 launched in Chile, and local business was converted to Geely Auto Chile Co., Ltd. direct operation, grabbing service initiative in its own hands; In the Middle East and Africa, ZEEKR 9X started pre-sale, Lynk & Co moved into Jordan, and the first D-segment SUV global car Monjaro EM-i premiered in Egypt. Looking at it this way, it's clear: single-point trial has upgraded to a systematic layout, sales, service, channels, and racing all link together. Lynk & Co boosted brand awareness with CRC champion titles, ZEEKR opened the high-end market with luxury products, Geely main brand used the Galaxy series to seize new energy mindshare—three brands going global synergistically, the speed is naturally different.

III. Target Raised to 920,000, Where Does the Confidence Come From
Someone might ask: With such a large overseas frontline, can the funds withstand it? Geely just released its mid-2026 interim performance in mid-August, total revenue 173.6 billion yuan, core net profit attributable to parents 9.68 billion yuan, sales, price, profit all went up collectively. To put it plainly, fighting overseas needs continuous blood transfusion from domestic markets, and Geely's current cash flow is thick enough to support the global frontline. Plus exports breaking 100,000 for three consecutive months has already run through this going-global model, raising the target isn't a whim. Looking at Jan-July performance, ZEEKR 7X took the Australia medium luxury SUV sales champion, Galaxy Starship 7 EM-i took the Poland C-segment PHEV sales champion and Spain C-segment SUV first, blockbuster models fully possess the ability for global replication. 920,000 units looks like a bold slogan, actually it's just amplifying the already validated tactics further.
Many are used to understanding China car exports as "selling to developing countries", Geely's answer is: Hit developed countries with new energy, deepen emerging markets with systems, build reputation with quality and intelligence. August exports of 110,094 units is a milestone, but definitely not the end. When a Chinese auto company dares to set annual export targets to 920,000 units, then surge to 1 million, the old structure of the global auto industry has started to loosen.
September 1, Geely Automobile Holdings Limited (0175.HK) announced the latest sales data: August sales were 270,194 units, with year-on-year and month-on-month increases for six consecutive months, increasing by 8% year-on-year and 8% month-on-month. Regarding new energy vehicles, August sales (including Geely, Lynk & Co, and Zeekr) totaled 175,877 units, up 19% year-on-year, with the new energy sales share accounting for 65%.
Geely moves towards the "Systematic Globalization" stage, with overseas exports reaching a new high again. August overseas export sales reached 110,094 units, up 205% year-on-year and 3% month-on-month, achieving year-on-year and month-on-month growth for eight consecutive months. New energy product share continues to exceed half, with August new energy product export sales reaching 70,629 units, a surge of 446% year-on-year, accounting for 64%.
Behind the steady growth in sales is the achievement of Geely accelerating the transformation of technological innovation results into product competitiveness. From August 21 to August 30, Geely Automobile Group, bringing Zeekr, Lynk & Co, Geely Galaxy, and the Geely China Star brand matrix, participated in the 2026 Chengdu International Auto Show. More than 49 intelligent products made a collective appearance, covering all energy series including pure electric, hybrid, and fuel, comprehensively showcasing the technological ecosystem and future vision of the "Leader of the AI-Integrated Intelligent Automobile Domain".

Sales and Brand Value Rise Simultaneously; Three Brands Continuously Release Growth Potential
The three brands steadily climb, with main force models performing brightly, jointly promoting the continuous improvement of sales scale and brand value.
The global luxury technology brand Zeekr continues to move upward. August delivery volume reached 36,981 units, up 110% year-on-year. Multiple models lead the sub-market: Zeekr 7X August sales continued to break through 10,000, with global orders exceeding 200,000; Zeekr Shooting Brake sales exceeded 10,000 for 3 consecutive months, with global deliveries exceeding 400,000; Zeekr 9X ranked first in sales of vehicles over 500,000 from January to July; Zeekr 8X ranked first in cumulative sales of hybrid SUVs between 300,000 and 500,000 yuan after three months since listing, and first in reputation for all categories over 300,000 yuan; Zeekr 009 won the dual crown of sales and reputation for pure electric MPVs over 400,000 yuan in mainland China for 3 consecutive months.
On August 21, the Chengdu International Motor Show officially opened. The Zeekr brand brought together 14 products including Zeekr 009, Zeekr 9X, and Zeekr 8X, forming a luxurious product lineup to attract numerous viewers to visit and experience.

The global new energy premium brand Lynk & Co continues to expand. August sales reached 17,027 units, up 4% month-on-month, with new energy product sales of 15,504 units, up 10% month-on-month. Lynk & Co promotes the layout of product width, sports width, and experience width, focusing on developing the sub-market. On August 21, the all-new Lynk & Co 20 appeared at the Chengdu International Auto Show, creating a refined trendy travel new choice for urban users; the all-new Lynk & Co 20 Fly version appeared simultaneously, further strengthening sports attributes with a large carbon fiber rear wing and aerodynamic sport kit.

At the same time, newly listed models such as Lynk & Co 10 and Lynk & Co 07GT were exhibited alongside the Lynk & Co GT concept car Time to Shine, showcasing Lynk & Co's product layout covering multiple energy forms, adapting to diverse travel scenarios, and ultimate performance aesthetics.
Lynk & Co's automotive sports map expanded from track racing to rally racing, starting a new exploration of Chinese brand hybrid rally sports. From August 28 to 30, Lynk & Co took the 07GT Rally Academy Racer to the 2026 China Automotive Rally Championship (CRC) · Huairou Station. Speed Partners-NANA / Speed Partners-Jacky drove this racer to win the CRC S7 Class & Lynk & Co Automotive Rally Challenge Championship.

The Geely brand solidified the foundation of high-quality growth, with August sales of 216,186 units, up 5% year-on-year and 9% month-on-month.
Among them, the mainstream new energy brand Geely Galaxy August sales reached 119,115 units, up 8% year-on-year and 10% month-on-month. Geely Xingyuan August sales reached 60,955 units, with sales exceeding 50,000 for 3 consecutive months, cumulative sales nearing 900,000 units, delivering 1 unit per minute on average, selling more than 1,200 units per day. In addition, in August, Geely Galaxy E5 sales reached 14,132 units.

At the same time, while Geely Galaxy solidifies the mainstream market, multiple new cars reinforce competitive advantages with product power. On August 13, the all-new C-Class AI Pure Electric Sports Sedan Galaxy TT opened for pre-sale, starting from 145,900 Yuan, redefining the value benchmark for 200,000 Yuan class pure electric sports sedans. On August 21, Geely's first AI All-Terrain Hardcore SUV -- Galaxy Warship 700, appeared at the Chengdu International Auto Show. As an embodiment of Chinese-style luxury off-road in the new energy era, it became the focus of the entire show, fully demonstrating the benchmark-level strength of Chinese hardcore off-road, and will open for pre-sale in September.

In the fuel car market, Geely China Star further strengthened its leading position, with August sales of 97,071 units, up 8% month-on-month. Among them, the Twin Bin Family reached 33,515 units, the China Star premium series reached 25,802 units, and the Boyue Family reached 16,656 units.
The fuel car HEV strategy continues to land, with classic products continuously refreshed. The all-new Fourth-Generation Boyue L i-HEV Series landed at the Chengdu Auto Show. The new car is equipped with China's third-generation fuel hybrid technology i-HEV Smart Engine Hybrid, the strongest hybrid dedicated 1.5TD engine in its class, LiDAR, and Qianli Hanhai H5 ADAS solution. With "Great Energy Saving, Great Performance, Great Intelligence" three cross-level strengths, it redefines fuel SUVs, further consolidating Geely Boyue's fuel SUV sales champion status.

On August 31, the all-new flagship model under Geely Automobile -- Xingyue L PLUS was officially announced to appear. The new car adopts a 5-Seat Layout, positioned as a Mid-to-Large Flagship Smart Hybrid SUV, making comprehensive advances in hybrid systems, intelligent configurations, chassis handling, and seating comfort, further consolidating Geely China Star's voice and champion status in the fuel car market, and will debut on September 5.

Accelerate Full-Domain AI Transformation; Inject Growth Power with Technological Innovation
Geely continues to promote full-domain AI transformation, having integrated full-domain AI into the design, R&D, manufacturing, and after-sales full links, achieving "Full-Domain Intelligence", and accelerating the landing of new products and technologies.
On August 28, 2026, Geely Automobile Group officially launched AI New Energy Off-road Technology, gathering GTA Native New Energy Off-road Architecture, AWD AI Electric Hybrid Thunder EM-T, and AI All-Terrain Digital Chassis, three globally first technologies, achieving comprehensive innovation breakthroughs in body structure, power system, intelligent chassis, and full-domain safety, completing systemic reshaping from the technical foundation.

GTA Native New Energy Off-road Architecture breaks the physical space bottlenecks and comfort experience limits of traditional ladder frame structures. With high-rigidity design, it has lightweight advantages, bringing disruptive off-road driving comfort compared to traditional off-road vehicles; AWD AI Electric Hybrid Thunder EM-T combines surging power and precise control, able to calmly cope with various off-road conditions, plus Star Wisdom AI Cloud Power's AI Scenario Engine, providing precise matching of optimal fuel-electric plans, energy consumption optimization of more than 15%; relying on the "AI All-Terrain Digital Chassis" built on the world's first Quantum-level AI Electronic Architecture EEA 4.0, it can identify road conditions ahead through AI, automatically switch intelligent scenario modes, and adjust torque, suspension, and body posture.
New technologies are first mounted on Galaxy Warship 700, breaking traditional off-road technology boundaries and redefining the benchmark for global smart new energy off-road technology.
Accelerate Systematic Globalization Pace; Sprint towards Million Export Sales Target
In August, overseas export sales were 110,094 units, achieving year-on-year and month-on-month growth for eight consecutive months, with exports exceeding 100,000 for three consecutive months. New energy product overseas export sales reached 70,629 units, surging 446% year-on-year, accounting for 64% of total exports.
The three brands continue to break through the global market, topping the front of many sub-markets. Zeekr topped the Australian 1-July luxury pure electric sales list, and also firmly stayed at the Malaysia luxury pure electric brand sales champion for 1-July; Lynk & Co ranked first in Tunisia July premium PHEV brand sales; Geely brand won Panama 1-July and July single-month Chinese brand sales champion, and entered the top three of Ecuador July pure electric brands.
Core model global competitiveness is further显现。January-July, Zeekr 7X topped the Australian mid-size luxury SUV sales champion, Malaysia pure electric luxury SUV first, Zeekr 009 won Thailand and Malaysia pure electric MPV model market first, Singapore luxury pure electric MPV sales champion. Lynk & Co 08 won July Tunisia premium PHEV sales first; Lynk & Co 900 took July Egypt premium new energy market sales first. In July, Geely Xingyuan (Geely EX2) topped Thailand EV sales champion, Jordan pure electric model first, Mexico all-category pure electric sales second; Galaxy Starship 7 EM-i (Geely EX5 EM-i) topped Poland C-Class PHEV sales champion, Spain C-Class SUV first and PHEV second, Mexico PHEV SUV top.
Geely accelerates the globalization pace in multiple markets including Europe, Latin America, Southeast Asia, Middle East, and Africa, continuously improving local sales networks and product layouts.
Regarding the European market, Geely officially announced landing in the Austria market, launching the Austria channel network; Spain market development has entered a rapid growth stage, with national sales network exceeding 50; further deepening cooperation with UK's largest car salary replacement service provider Tusker, enriching Geely Xingyuan's sales channels in the UK market; Geely Xingyuan listed in France.
Regarding Latin America and Southeast Asia, Lynk & Co officially landed in Argentina, with Lynk & Co 01, Lynk & Co 08, and Lynk & Co 06 three models appearing simultaneously; Lynk & Co 01 listed in Chile, and Lynk & Co Chile operations entered a new stage, cultivated by Geely Automobile Chile Company direct operation, achieving comprehensive upgrade from product to service; Lynk & Co 02 (Z20) and Lynk & Co 03 officially landed in the Vietnam market, improving Lynk & Co's full-power product matrix in Vietnam.
Regarding Middle East and Africa markets, Chinese flagship Zeekr 9X landed in the Middle East, and pre-sale has already started; Lynk & Co officially entered the Jordan market, with Lynk & Co 900 appearing as the core model. In addition, Geely's first D-SUV global car Geely Monjaro EM-i started global listing at the end of August, launching the Egypt market, steadily laying out globally.

Out of long-term confidence in overseas growth, Geely Automobile raised the 2026 overseas sales target from 640,000 units to 920,000 units, and sprinting towards an annual sales of 1 million units.
Technical strength and global capabilities continue to advance, with Geely Automobile's operating scale and profit quality steadily improving. On August 17, Geely Automobile released 2026 Mid-Year Performance, with total income of 173.6 billion Yuan, core net profit attributable to parent company reaching 9.68 billion Yuan, achieving "Volume, Price, and Profit All Rise". Relying on the "One Geely" strategy, Geely Automobile will fully leverage the "Leader of the AI-Integrated Intelligent Automobile Domain" momentum, accelerate the full industry chain intelligent transformation, and traverse the cycle with high-quality development determination.
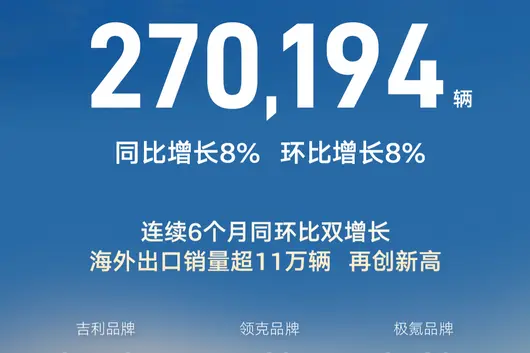
SAIC's overseas market is shifting gears and accelerating.
From January through July this year, SAIC's exports and overseas base sales reached 876,000 units, up 52.1% year-on-year; of which 7 months sales 142,000 units, up 72.5% year-on-year. In the preceding June, SAIC's overseas sales reached 146,000 units, up 61.2% year-on-year, creating a new single-month historical high. According to the 2.384 million units group total sales disclosed by SAIC for the same period, the overseas market contribution has already approached 37%.
Another number is more intuitive. In 2025, SAIC's full-year overseas sales were 1.071 million units, up 3.1% year-on-year; this year it only took 7 months to complete more than 80% of last year's full-year sales volume.
From consecutive years of overseas annual sales of millions of units to re-entering high-speed growth this year, SAIC's overseas expansion is showing new changes.
In 2025, SAIC released overseas strategy 3.0 — Glocal "Global + Local" strategy, proposing upgrading from product export to value chain export. More than a year later, this strategy began to land beyond sales figures: European Engineering Center activated, overseas direct sales systems increased, hybrid, pure electric products etc. were recombined according to different market needs, European local production also began to enter the substantive promotion stage.
This means SAIC's overseas expansion is crossing a new threshold: from selling more cars globally to truly operating the global market.

Europe is no longer just an export market
Europe is the most suitable market to observe this change.
From January through July this year, MG sold 218,000 units cumulatively in Europe, up 22.8% year-on-year, continuing to maintain a leading position in European sales of Chinese car brands. In 2025, MG's Europe sales exceeded 300,000 units, up nearly 30% year-on-year.
More worth attention than the total volume is that MG began to appear on the European mainstream model sales list.
Data from the UK Motor Manufacturers and Traders Association SMMT shows that in July this year, 2,703 MG HS were registered, ranking fifth among all models in the UK, only behind Ford Puma, Nissan Qashqai, Kia Sportage and Jaecoo 7; cumulatively 19,424 units in the first 7 months, ranking seventh in the UK annual model sales.
The significance of this ranking is that measuring MG's position in the UK market no longer requires setting up a separate "Chinese Brand" coordinate system. It is competing with brands like Ford, Volkswagen, Nissan, Kia that have operated the European market for decades for the same batch of family users.
Europe is also one of SAIC's overseas markets facing the greatest pressure.
Currently, among the additional anti-subsidy taxes imposed by the EU on pure electric vehicles produced in China, SAIC's applicable tax rate is 35.3%. After adding original import tariffs, Chinese-produced pure electric models face obvious cost pressure. At the same time, Chinese car companies like BYD, Chery, etc. are also rapidly expanding in Europe and successively advancing local production. Europe has become one of the most fierce markets for Chinese car companies in global competition.
SAIC's response is not to continue relying on single pure electric products.
In June this year, MG's overseas HEV model single-month sales have approached 27,000 units, doubling year-on-year; in the MG Technology Conference held in London in July, Plug-in Hybrid+ hybrid, SolidCore semi-solid-state battery and smart cockpit and assisted driving technologies were centrally displayed.
A few years ago, MG's most distinct product label in Europe was still pure electric models like MG4. Now, from HEV, PHEV to pure electric, the product portfolio is becoming more complete.
Behind this is actually a change in the overseas expansion mindset.
The initial export logic considered more how products matured in the Chinese market can go overseas; true global operation requires studying in reverse what power forms, what prices, what sizes local consumers need, then deciding what products to provide.
For automobile enterprises, what separates the two is a whole set of local product definition capabilities.

More important than how many units sold is
Rooting deeply locally
This year, a series of actions by SAIC in Europe are further crossing the boundary of "export".
Starting July 1st, MG in Belgium and Luxembourg shifted from agent operation to MG Motor Europe direct National Sales Company, directly responsible for local market operations. Previously MG had already become the largest Chinese car brand in Belgium, in 2025 local registration was about 6,000 units, market share over 1.5%.
On the same day, MG Motor Switzerland GmbH was officially established, the Swiss market also shifted from importer operation to wholly-owned, locally managed direct sales system, MG began to directly responsible for sales, after-sales and brand operation.
This is a change that can be easily masked by sales figures, but very much illustrates the degree of globalization.
For an export enterprise, the core question is how many cars sold to overseas dealers; for an enterprise truly operating the local market, it also needs to directly face terminal prices, inventory, channel efficiency, after-sales service, brand building and user relationships.
Greater changes are happening at the manufacturing end.
In June this year, the plan for SAIC to build its first EU automotive production base in Ferrol, Galicia, Spain surfaced. According to information disclosed by Reuters, the project is expected to invest about 200 million euros, planned to start construction in 2027, operate in 2028, subsequent planning annual capacity up to 120,000 units, and will support logistics and local parts procurement.
Building factories in Europe certainly has practical considerations of reducing trade barriers and logistics costs, but the significance is not limited to this.
When vehicle production truly enters Europe, enterprises need to handle local suppliers, employees, regulations, government, channels and consumer relationships simultaneously. Cars are gradually shifting from "Made in China, Sold in Europe" to "European R&D Adaptation, European Production, European Operation".
This is also the truly difficult part of "Local" in the Glocal strategy.
In the past few years, SAIC has formed an overseas R&D, manufacturing, sales and logistics network. The existing system includes overseas R&D innovation and design centers, production bases such as Thailand, Indonesia, India, as well as parts, sales service and self-operated RoRo transport system.
If these layouts built SAIC's global operation chassis, then Europe is becoming a pressure test field for verifying this system's capability.
In a market possessing local giants such as Volkswagen, BMW, Mercedes-Benz, Stellantis, while also possessing strict regulations, mature consumers and trade barriers, relying on export price advantage can win for a period of time, but it is difficult to win a long-term market.
In the end, it is a contest on who can truly integrate in.

From an MG prototype
Turn into group-level global capability
MG is still SAIC's most mature piece of overseas expansion, but SAIC's overseas growth no longer comes entirely from MG.
SAIC-GM-Wuling overseas exports have exceeded 30,000 units consecutively for 4 months, this year January-7 months cumulative breakthrough 200,000 units; SAIC Maxus July overseas sales 14,000 units, up 69% year-on-year, products entered global 100+ countries and regions. Recently, SAIC Hongyan also signed 1,000 new energy heavy truck orders with Thai customers, and carried out vehicle and charging, maintenance system local adaptation for local high temperature, rainy, heavy load environment.
From MG passenger cars, to Wuling small cars, to Maxus light commercial vehicles, pickups and new energy heavy trucks, what SAIC tries to replicate is no longer a certain "global blockbuster", but a group-level global operation system.
This road did not start this year.
In 2001, SAIC began passenger car exports; in 2012 cooperated with CP Group to layout Thailand, subsequently advanced local vehicle production; in 2019 India vehicle base put into production; by 2025, SAIC formally proposed Glocal strategy. Now, SAIC products and services have entered over 170 countries and regions globally, overseas cumulative sales exceeded 7 million units.
In more than 20 years, Chinese car exports themselves have also changed.
Earliest competition was whether there were products that could be exported; subsequently competition was who could reach 100,000, 500,000, 1 million units scale first. Entering today, when more and more Chinese car companies cross the 1 million unit export threshold, pure export quantity is becoming increasingly difficult to decide the final result of global competition.
The next stage, the contest is another set of capabilities: can we define products according to different markets in Europe, Southeast Asia, Middle East, Latin America; can we establish local R&D and manufacturing; can we directly operate channels and users; can we adapt to local regulations, supply chains and even industrial policies.
In other words, Chinese car exports are moving from "Trade Globalization" to "Operation Globalization".
From this perspective, the significance of 876,000 units has also changed.
It is first of all a sales report card, but more importantly, this round of growth appears in the stage where European local production, direct channels, technical local adaptation and global supply chain are promoted synchronously.
True global automobile enterprises were never global enterprises because of large export volumes. Toyota, Volkswagen, GM became multinational automotive groups because they can R&D, produce, organize supply chains, operate brands and serve users in different countries.
For SAIC which has continuously sold millions of units overseas for many years, the next question has also changed from "how many more units can be exported" to "in how many markets can it truly take root".
Europe is giving the first answer. What SAIC wants to prove is not only that Chinese cars can be sold globally, but also that Chinese car enterprises have the capability to become part of the global automotive industry.
That August 1st sales quick report, I read it over and over again. Geely's total July sales reached 250,161 units, nothing unexpected; what really made me pause in front of my computer was the overseas data: exports of 106,663 units, up 202% year-on-year, rising month-on-month and year-on-month for 7 consecutive months, and reaching the 100,000 unit mark for two consecutive months.

Working in this industry for so long, you develop a feel for numbers. Previously when we talked about exports, it was assumed we just pull domestic surplus inventory to the Middle East or Africa to get blood back. But of Geely's 106,000 units this month, new energy vehicles accounted for 62,604 units, a proportion as high as 59%. What does this show? It shows what Geely sends overseas is no longer "surplus stock", but the "elite forces" currently fighting the main battle domestically.
The logic behind this deserves to be broken down and discussed thoroughly.
Model Matrix: No longer single-point explosions, but carpet-style deploymentI see many peers focusing on total sales volume. Actually, break it down by model dimension, you will find Geely's approach has changed. Previously relying on one car to rule the world, now it is rising simultaneously in various sub-segments.

Taking Star Wish (EX2) as an example, it took first place in Thailand's pure electric market in June, pushing BYD Atto 3 aside. This car looks unremarkable domestically, but in Southeast Asia's congested, high-temperature, cost-performance-focused markets, it is simply a dimensional strike. Even more incredibly, this car entered the top two in Brazil and Mexico. An A0-level small car can gain volume simultaneously in Southeast Asia and Latin America with completely different usage scenarios. This is definitely not luck, but right product definition.
Look at Starship 7 EM-i (EX5 EM-i), this car took C-level PHEV first place in Poland. Europeans are shrewd, high fuel prices, inconvenient charging, PHEV is indeed the optimal solution at this stage. Geely taking the domestic Thor Electric Hybrid technology over there, just cut right into the pain points.
Lynk & Co 08 and Zeekr need not be mentioned. Lynk & Co 08 entering the top three in premium plug-in hybrids in a place like Mexico, which is the "heartland of American cars", Zeekr pressing BBA down in right-hand drive markets like Australia, Malaysia. This is no longer explainable by "cost-performance", this is substantive breakthrough in brand elevation. Previously we said Chinese cars going overseas is "encircle the cities from the countryside", now it looks like Geely wants to directly enter "the city" to open stores.
Valencia: This Move Carries More Weight Than 100,000 UnitsTo tell the truth, July sales volume is just the result, that big move Geely and Ford pulled off in Spain at the end of July is the key to deciding the pattern of the next three years.

Geely spent 221 million euros to buy 34% stake of Ford's Spanish Valencia factory. This money looks a lot, but in the background of building factories in Europe costing billions of euros, this is simply "rock-bottom price".
Why is this move so clever? We who work in industry all understand, the European market has always had a "glass door", that is that anti-subsidy tariff. Previously we made cars and sent them over, tariffs were so high it was shocking, price advantage instantly disappeared. Now Geely directly builds a joint venture factory in Spain, using Ford's idle capacity to make Geely cars. This trick of "borrowing a boat to go out", directly bypasses the tariff barriers.
More importantly, this factory was built in 1976, Ford has run it there for decades, supply chain, workers, union relations are all sorted out. Geely spending small money to do big things, not only gained capacity, but also gained the "ticket" to enter the EU market and "compliance credentials". Afterward, Europeans buying Geely cars, packaging might print "Made in Spain". This is not only a business victory, but survival wisdom under geopolitical games.
System Capability: From "Selling Cars" to "Outputting Systems"Having done auto reporting for so many years, I have seen too many companies fail miserably when going overseas. Previously many car manufacturers going overseas, just find an agent, send cars over, whether they sell well depends entirely on heaven. But Geely's current gameplay is "system overseas".
What is a system? It is "One Geely" strategic coordination. Geely, Lynk & Co, Zeekr three brands, positioning clearly divided, fighting each other not at all. Geely focuses on volume, Lynk & Co on quality, Zeekr on high-end. This multi-brand synergy is even more important overseas than domestically, because overseas dealers fear OEM left-right mutual fighting.

Looking deeper, it is technical foundation sharing. CMA, SEA these architectures, plus Thor Electric Hybrid, Shield Battery, all globally universal. This is like building blocks, base is universal, above can according to different country regulations, road conditions, consumer habits change shells. This development efficiency is what those still "one car one car redesign" competitors cannot compare with.
Past decade smashed in 250 billion R&D fees, now look, time for harvest has arrived.
Written at last: Don't just look at the spectacle, look at the essenceOf course, we also must be calm. Although Geely's momentum is fierce, challenges are still ahead. Before Valencia factory first car rolls out in 2028, union negotiations, production line renovation, EU certification, every gate is not easy. Moreover, Lynk & Co and Zeekr really entering Western Europe, facing Mercedes, BMW, Tesla these "local heavyweights", hard battles are still ahead.
But for us spectators, Geely's July 106,000 units, signal meaning already very clear. Chinese cars going overseas, already passed that "selling cars out is enough" untamed era, entered "manufacture locally, sell locally, service locally" system competition stage.
Later you see Zeekr on Sydney streets, or Starship 7 in Warsaw, likely not from Ningbo Port crossing ocean transported over, but European local factory roll-out products. This is true globalization, also Geely this wave operation most makes me feel "sophisticated" place.
This game of chess, Geely has only just started placing stones.