首頁China National Heavy Duty Truck

搜尋歷史
熱門搜尋
經銷商登入 / 註冊

Heavy-duty trucks are a sector with strong cyclical imprints. Ups and downs in prosperity always move in sync with freight rates, infrastructure project start rhythms, and old vehicle replacement windows. For a long time, most players' destinies were passively bound to the domestic market: rushing for volume and share during upturns, profit margins being compressed first when demand tightened.
In Q3 2025, cyclical inertia reappeared. The recovery momentum in the first half gradually slowed. Freight market returns were low, the base from the same period last year rose, compounded by a widening gap between oil and gas prices, making fleet purchasing decisions obviously cautious. Data from the China Association of Automobile Manufacturers showed that cumulative domestic heavy-duty truck sales in the first three quarters reached 929,400 vehicles, a year-on-year increase of 12.96%, with the growth rate significantly falling compared to the first half. The industry bid farewell to general prosperity dividends and officially entered a differentiation stage of stock game, price wars quietly spread, and many car companies fell into the predicament of "selling more but earning less".
Right at the node where industry profitability generally faced pressure, China National Heavy Duty Truck's Q3 report submitted on October 27 followed a trend contrary to the benchmark. Revenue, net profit attributable to parents, and adjusted net profit all broke historical records for the same period. Especially in the off-season Q3, profit growth significantly outperformed revenue, gross profit margin rose against the trend. This financial report is not just a set of eye-catching numbers, but also hides an industry signal worthy of deep research: the main thread of industry growth has shifted from total volume expansion to structural opportunities, and China National Heavy Duty Truck is jumping out of the scale game used by the heavy-duty truck industry for many years, shifting to an efficiency-first growth paradigm.
Off-season Growth Against the Market Trend
In the first three quarters, China National Heavy Duty Truck realized operating revenue of 53.50 billion yuan, a year-on-year increase of 32.12%; net profit attributable to parents was 1.44 billion yuan, a year-on-year increase of 37.23%; adjusted net profit was 1.40 billion yuan, a year-on-year increase of 42.11%. The growth rate of adjusted profits consistently outperformed revenue, which is the most valuable signal of this round of growth, indicating that profit growth is not propped up by non-recurring income such as asset disposal or subsidies, but the profitability resilience of the main business itself is getting stronger in reality.
Focusing on this traditional off-season Q3, this contrast is more intuitive. Single quarter revenue was 1.51 billion yuan, a year-on-year increase of 5.29%, slowing naturally with the benchmark; net profit attributable to parents was 468 million yuan, a year-on-year increase of 22.77%, adjusted net profit was 459 million yuan, a year-on-year increase of 27.96%, gross profit margin increased by 1.69 percentage points compared to the same period.

For a long time, the underlying logic of the heavy-duty truck industry was simple: rely on price cuts to win orders, rely on larger sales volume to spread fixed costs. This path worked well in the up cycle, once demand contracted, profitability would quickly be lost. The essence of China National Heavy Duty Truck's change in this round was changing a set of management rulers. Many peers, when encountering pressure, the first reaction was to compress long-term investments such as R&D to protect short-term profits, it chose reverse operation: R&D expenses in the first three quarters increased by 9.11% year-on-year, resources continued to be invested in new energy vehicle platforms, powertrains and other underlying technologies; at the same time, squeezed water inward, expense ratio dropped to 1.83%, a year-on-year decrease of 0.57 percentage points, creating a low level in the same period.
Continuously reserving chips for the next round of technology competition on one side, while using supply chain centralized procurement, production line process optimization to increase yield, compressing full-chain redundant costs. This combination of "long-term investment + refined cost control" gave it a profit cushion that others found hard to replicate in the fierce price involution.

Today's heavy-duty truck market, incremental dividends have bottomed out, opportunities hide in structural gaps. Domestic fuel heavy-duty truck replacement market involution is white-hot, but overseas market, new energy heavy-duty trucks, core component supporting, are three new curves independent of the domestic cycle. China National Heavy Duty Truck can continuously outperform the benchmark, the core is early risk dispersion, no longer betting all chips on domestic update demand. Car companies guarding a single market are easily swirled by the cycle; multi-track balanced layout, only have the confidence to hedge fluctuations.
Overseas, New Energy, Supporting Long-term Growth Chassis
The resilience of this performance is not brought by one track's short-term explosion, but multiple growth lines synergistic support bottom, overseas expansion is among the most heavy pole.
Domestic market capacity peaked, overseas expansion long ago was not a bonus item, but the imperative for top heavy-duty truck enterprises to traverse the cycle. Currently China National Heavy Duty Truck export sales volume accounts for total sales volume ratio breaking 50%, half of the sales come from overseas, business coverage 150 countries and regions. Africa, Southeast Asia, Central Asia, Middle East's basic foundation solid, Latin America, Australia etc new markets also steadily breakthrough.
The Hannover IAA Commercial Vehicle Exhibition in Germany not long ago was a concentrated debut of this set of globalization thinking. This international stage competition has never been just vehicle model parameters, but also local compliance ability, long-term technical standards, continuous service systems. China National Heavy Duty Truck carried SITRAK pure electric tractor exhibition, facing European market output whole set of energy and logistics transport schemes; simultaneous in Tunisia, Malaysia landed new car release and major customer signing. And industry common "selling cars means finishing" export mode different, its focus placed on localization adaptation: fit local regulations, road conditions, maintenance habits build parts and service networks. Short-term investment higher, but customer stickiness stronger, going out to sea also from one-time running volume, become stable, sustainable long-term growth curve.

Besides whole vehicles, vertical industry chain's value, in the cycle where profits become thin was magnified. Holding subsidiary Jinan Axle this year production, sales, profit synchronous improvement, products except supplying main body whole vehicles, also outward supply group inside other whole vehicle enterprises. Core components independent controllable, meant facing raw material price increase, supply chain fluctuations, enterprises have stronger bargaining power and delivery stability, this is pure assembly type car companies hard to build moat.
New energy is towards next ten years layout. Oil-gas price difference continues to widen, completely rewritten fleet cost account, new energy heavy-duty trucks long ago broke away from policy pilot tags, become fleet cost reduction practical choice. Compulsory traffic insurance data showed, September domestic new energy heavy-duty truck penetration rate broke 50.28%, electrification formally entered scale popularization stage.
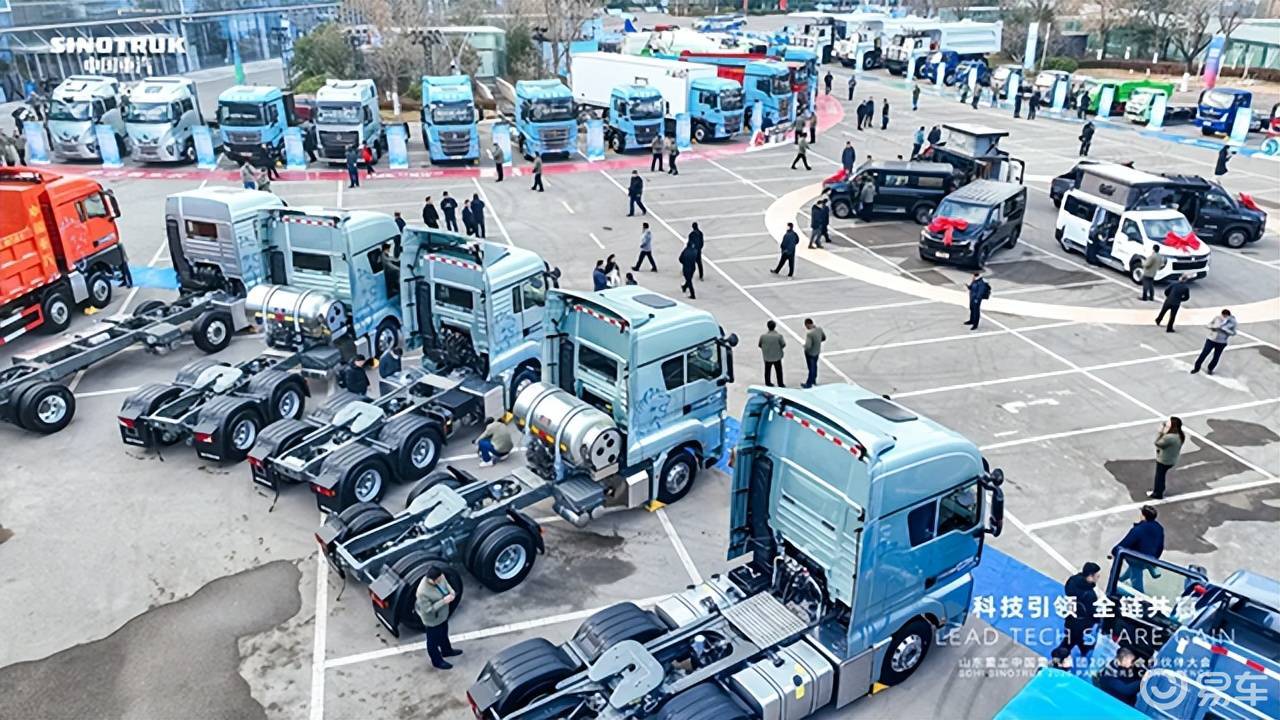
Track heat rose, low price involution followed. China National Heavy Duty Truck did not dive into homogeneous price war, but anchored scenes do custom development: facing mine area heavy load, port short-distance transfer, container trunk transport etc scenes, launched HOWO TS new energy dump truck, new energy container tractor, already in Northwest mine area, Shanghai port achieved batch landing. New energy heavy-duty truck production sales growth rate outperformed industry, confirmed a simple logic: first calculate fleet operation account, then do products, more easily obtain terminal user recognition.
Long-term Operation Ability Determines Win/Loss
Outlook 2026, industry fundamental still have support. Institutional judgment, heavy-duty truck old-for-new replacement policy has hope to continue, old vehicle elimination brought rigid update demand, domestic annual heavy-duty truck sales has hope to maintain around 1.25 million units. Superimposed overseas infrastructure demand continuous release, export prosperity degree has hope to continue, industry overall will not quickly weaken.
But policy dividends will not be universal to all players. Domestic stock competition will only become more and more fierce, overseas markets also need to face international old brands competition, new energy track reshuffling also far from over. Policies can hold up short-term sales volume, determine enterprise ceiling, finally management foundation, supply chain barriers, localization service ability, scene product landing these core competencies.
For China National Heavy Duty Truck, growth framework already clear: internal efficiency stable profit bottom line, overseas markets contribute incremental, autonomous parts system optimize costs, new energy layout locked transformation direction. Multiple curves mutual support, reduced reliance on domestic cycle.

The fundamental nature of heavy-duty truck cycles will not disappear, but enterprise growth rhythm can be defined by itself.
Past this industry competition logic very straight: catch one wave up cycle, volume release can take share; enter differentiation era, competition ruler changed, competing is traversing cycle resilience, catching structural opportunity judgment, long-term system ability precipitation. In Q3 benchmark cooling, involution intensified environment, this financial report provided a sample: steady growth never is wait for wind of opportunity, but actively planting deep multi-dimensional ability chassis, in cycle ups and downs maintaining its own pace.
Of course, this set of multi-line synergistic mode, final quality still needs to be put to bigger pressure environment inspection. Subsequent worth continuous observation is, once industry down pressure increases, this set growth logic can continue fulfill, this also is the litmus test for inspecting long-term value of the leader.