


首頁Camry

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
September 4, GAC Group released the August production and sales announcement. Data shows that from January to August, GAC Group's car sales reached 1.0126 million units, maintaining positive growth year-on-year. Among them, cumulative new energy vehicle sales surged 63.06% year-on-year to 368,200 units, energy-saving vehicles grew 3.30% year-on-year to 288,700 units. Driven by this, GAC's share of energy-saving and new energy vehicles sales in the same period climbed to 64.86%, a significant increase of over 14 percentage points year-on-year.
This year so far, GAC branded cars maintained strong growth momentum. From January to August, sales exceeded 461,500 units, up 31.44% year-on-year. Meanwhile, the overseas business growth trend continued to rise steeply. From January to August, exports of GAC branded cars reached 172,000 units, up 136% year-on-year.

Branded Car Share Approaches 50%
JV Brands Stabilize and Recover
GAC branded cars continue to contribute core growth momentum for GAC Group. In August this year, GAC branded cars contributed sales of 61,378 units, up 20.43% year-on-year, with sales share further increasing to 48.49%. This year so far, the growth rate of GAC branded cars has maintained double-digit growth for 6 consecutive months.
Hyper Aion BU August sales reached 33,694 units, up 38.56% year-on-year, with growth rate remaining double-digit for 6 consecutive months; from January to August, sales were approximately 244,100 units, up 58.37% year-on-year. Aion i60 August terminal sales exceeded 11,000 units, exceeding 10,000 units for consecutive months, firmly ranking at the forefront of A-class dual-power SUVs; Aion N60 won the top spot in LiDAR SUVs in the 100,000-130,000 yuan range for 4 consecutive months. Meanwhile, GAC Aion welcomed a new partner, Huawei's intelligent electric product line. The new model Ray7 co-developed by both sides debuted. The new luxury smart sports SUV Hyper S600 is also in hot delivery, with introductory price starting from 179,900 yuan.

Aion Ray7

Hyper S600
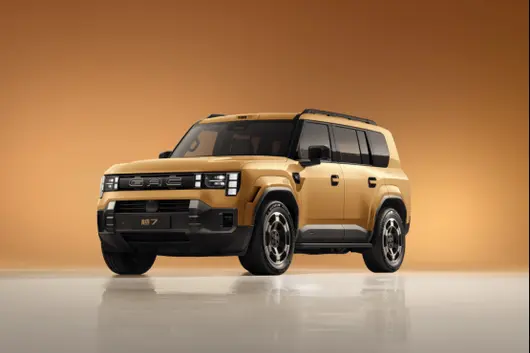
GAC Trumpchi August sales were 26,584 units, up 16.91% month-on-month. From January to August, sales reached 213,700 units, up 8.47% year-on-year. SUV family monthly sales were 17,813 units, up 22.3% year-on-year. Trumpchi's first full-scenario smart hardcore SUV "Yue 7" opened pre-sales on September 2. As of the end of August, its priority program cumulative orders exceeded 15,000 units. In the high-value MPV track, with the 500,000th Trumpchi M8 officially rolling off the production line, Trumpchi global MPV users broke through 900,000, further consolidating its status as "China's MPV Expert".

Trumpchi Yue 7
Qi Jing is a high-end intelligent car brand created by GAC in partnership with Huawei Qikun. Cumulative sales from July to August neared 4,000 units, with new cars delivered to users sequentially. The brand achieved dual breakthroughs in strategic deepening and product landing in August. GAC Group Chairman Feng Xingya met with Huawei founder Ren Zhengfei again, reaching an important consensus, marking Qi Jing's shift from "directional consensus" to "deepened development". The second strategic model, the wide five-seat smart flexible SUV Qi Jing GX7, opened pre-sales on September 4. It features the industry's first 20-second one-key pure flat large bed technology, Level 3 autonomous driving architecture, and is the only one in its class equipped with 4 LiDARs. Standard configuration includes CATL batteries, with comprehensive range exceeding 1,500 km.

Qi Jing GT7 and Qi Jing GX7
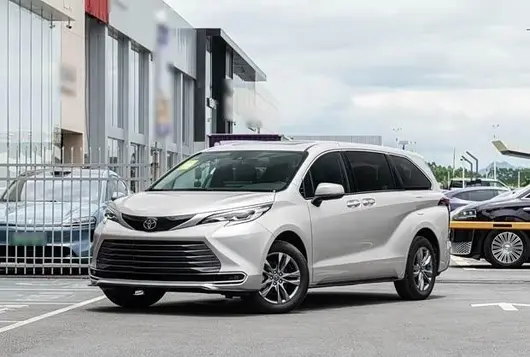
GAC Toyota continues to solidify its core market with flagship cars. From January to August, cumulative sales exceeded 450,000 units, with 52,700 units in August, a month-on-month increase of 13.33%. Camry, Highlander, and Sienna, the three flagship models, sold 23,540 units monthly, accounting for 44.7%. bZ3X sales have consistently ranked high among joint venture new energy vehicles for multiple months. On August 19, the 2027 model Camry was launched equipped with a new intelligent cockpit and AI voice large model.

GAC Toyota Camry
GAC Honda sales steadily recovered. August sales were 12,080 units, up 3.4% month-on-month. The company is undergoing a major strategic upgrade, comprehensively promoting localization around R&D definition, industrial ecosystem, channel network, and business structure. Five new vehicles are planned for the next two years, including two localized new energy vehicle models.

GAC Honda Breeze
Branded Car Exports Near 27,000 Units
Cumulative Export Volume Grows 136%
In August this year, GAC overseas business, which has become the "First Growth Curve", continued to maintain three-digit growth rate. GAC branded car exports neared 27,000 units, up 177% year-on-year. From January to August, cumulative export volume reached 172,000 units, up 136% year-on-year.
Benefiting from the continuous implementation of globalization strategy, GAC accelerated comprehensively in overseas market breakthrough, localized production, channel integration, etc.
In terms of market expansion, GAC achieved high-speed growth in multiple locations globally in August. Among them, the African region became the fastest growing overseas market, with terminal sales up 881% year-on-year. Ethiopia, Ivory Coast, South Africa, and Libya all recorded multiplied growth year-on-year. Terminal sales in the Americas market increased 93% year-on-year. Core markets such as Uruguay, Costa Rica, Brazil, and Colombia also continuously recorded multiplied growth. Terminal sales in Europe increased 93% month-on-month. UK, Portugal, and Poland increased 89%, 167%, and 33% month-on-month respectively. In the same month, GAC sales ranked second in Greece's pure electric vehicle market. Terminal sales in the Southeast Asia market increased 24% year-on-year. Among them, Philippines sales increased nearly triple year-on-year. Singapore, Thailand, and Indonesia all recorded double-digit growth year-on-year. Meanwhile, cumulative users in the Middle East market have already broken through 100,000.

Middle East users visit GAC booth at Middle East Falcon Festival
Regarding localized production and channel construction, GAC continued to make moves in August. The company reached cooperation with Amijie in Egypt, achieving a key leap from exports to localized production; simultaneously landing in West Africa Ghana, with Trumpchi M8, Aion i60, Aion V and other models landing synchronously to cover full-scenario travel needs. In Europe, GAC signed with car retailer Ying Zhijie in Romania to accelerate Eastern European channel layout. Meanwhile, GAC All-Australia Dealer Conference was already held in August, further integrating channel resources to accelerate Australia market expansion.
GAC Group officially released July production and sales data on August 4. Overall, the first seven months of this year saw the group's cumulative vehicle sales cross the 886,000 units threshold, achieving a 1.28% year-on-year growth. Notably, cumulative sales of new energy vehicles reached 311,700 units, a surge of 66.20% year-on-year, further increasing the proportion of energy-saving and new energy vehicles in total sales to 63.96%. Meanwhile, the pace of overseas exports for independent brands accelerated significantly, with cumulative exports reaching 145,000 units in the first seven months, a 130% year-on-year soar; this figure has already surpassed the 2025 full-year target. Additionally, in the recently passed July, GAC Group welcomed a major milestone of cumulative production and sales breaking 30 million units.

Focusing on the independent brand segment, its cumulative sales from January to July exceeded 400,000 units, a year-on-year increase of 33.31%. Looking at July alone, independent brand sales exceeded 54,200 units, with a year-on-year growth of 19.91%. By brand, the Hyper Aion BU performed strongly, with cumulative sales reaching 210,400 units in the first seven months, up 62.08% year-on-year; July single-month sales were 28,807 vehicles, up 36.37% year-on-year. As for GAC Trumpchi, cumulative sales this year exceeded 187,100 units, up 9.83% year-on-year, with July sales at 22,739 vehicles. Of note, the newly launched Enjing GT7 delivered 2,658 units in its first full sales month, preliminarily gaining market and consumer recognition.

In the joint venture sector, GAC Toyota's cumulative sales from January to July exceeded 402,500 units, with July sales at 46,500 vehicles. The three flagship models composed of Camry, Highlander, and Sienna sold a combined 22,843 units in July, accounting for a high of 49% in the brand's total sales. Meanwhile, the bZ Series continued a stable monthly sales over 10,000 trend, contributing 12,002 vehicles in July, accounting for over 25%; its main model, the bZ3X, had single-month sales of 9,546 vehicles. GAC Honda achieved sales of 11,686 vehicles in July and welcomed a milestone of cumulative sales breaking 11 million units during this period. More importantly, both shareholders of GAC Honda have officially signed a renewal agreement, extending the cooperation period to 2038, aiming to jointly accelerate electrification and intelligence transformation. According to the established plan, GAC Honda will launch 5 new vehicles within the next two years, including two locally developed new energy vehicles and brand new iteration of hybrid products.


Regarding overseas market expansion, GAC's independent brands reached single-month exports of 23,575 vehicles in July, a 119% year-on-year growth. Reviewing the first seven months, the cumulative export of 145,000 units has already exceeded the annual target. Entering July, GAC's layout in the five major regional markets sped up significantly, focusing on three directions: localization production, new product launch, and policy coordination simultaneously. In the American market, terminal sales increased by 139% year-on-year, with vehicle sales in countries like Uruguay, Costa Rica, Colombia, and Brazil all achieving several-fold growth. Additionally, GAC successfully approved joining Brazil's "Green Mobility and Innovation Plan," marking its deep integration into local green development strategies. In the CIS region, terminal sales increased by 112% year-on-year, and the world's 7th KD factory has officially landed in Kazakhstan, with the first model rolled off the line being the GS8.

Good news continued to spread in the Asia-Pacific market, with terminal sales increasing by 78% year-on-year in July. The Thailand factory has cumulatively achieved over 10,000 complete vehicles rolled off the line, and multiple new models have also landed in the Philippines market. In the Middle East and Africa region, GAC terminal sales increased by 51% year-on-year, and it has officially entered the Morocco market; the first three SUVs launched will cover fuel, hybrid, and plug-in hybrid powertrain types. Meanwhile, GAC maintains a steady breakthrough trend in the European market; especially in the Greek pure electric passenger car market, its market share has increased to 7.7%, ranking second in that market, with model promotion and listing preparation work in multiple countries also being steadily promoted.

In terms of infrastructure, so far, GAC's "9 Verticals and 10 Horizontals" recharging network has covered 31 provinces and 213 cities across the country, achieving the goal of "a station within 1 km in the core urban area". The number of self-operated charging piles exceeds 27,000 units, with supercharging piles breaking 20,000 units. Looking forward to the second half of the year, GAC's product offensive remains strong, planning to heavily launch multiple models including Trumpchi's first hardcore off-road SUV Yue 7, Aion's all-new pure electric coupe RAY 7, and Enjing GX7.
 Auto-First | Li Dezhe
Toyota Motor recently announced plans to further increase the scale of its overseas production cuts, raising the total overseas production reduction volume from June to November of this year from the previously planned 38,000 units significantly to 83,000 units, doubling the production cut magnitude. Combined with the preliminary production cut of 40,000 units by Japanese domestic factories for the Middle East market in the first quarter of this year, Toyota's total vehicle capacity reduction plan within half a year exceeds 120,000 units.
Toyota's capacity adjustment this time is highly targeted, mainly aiming at sluggish markets and slow-selling models, including overseas factories in Thailand, India, Malaysia, etc., and overseas production lines dedicated to the Middle East market. Main models with production cuts are concentrated on fuel version RAV4, Camry, Fortuner, Innova and other traditional fuel SUVs and family sedans. Hybrid models and pure electric models capacity remains basically unchanged.
On the surface, short-term geopolitical crisis and supply-demand imbalance might be the main reasons for Toyota's current production cuts, but actually, this also reflects that holding firm to the internal combustion engine base in the global new energy wave has already fallen into a strategic disadvantage.
For a long time, Toyota insisted on hybrid technology route, pure electric model R&D and launch pace was slow, relying on durability and resale value advantages to deep-plow global fuel car blue ocean market. Especially in emerging markets like Middle East, Southeast Asia long-term occupied absolute leading position. However, in recent years, global auto industry landscape completely reconstructed, core markets like China, Europe comprehensively accelerated electrification substitution, Southeast Asia, Middle East and other traditional fuel car "safe havens" also began to gradually introduce new energy supportive policies, local new energy models rose rapidly, diverting fuel car market share.

Toyota continuously shrinking overseas capacity also reflects the new logic of current multinational automakers' global layout. In the past, automakers pursued global layout, capacity full coverage, to reduce production costs with economies of scale; Nowadays global geopolitical conflicts frequent, regional trade barriers rising, car market regional division intensifying, blind expansion of global capacity risk surged. Multinational automakers began to shift from "global expansion" to "precision layout", shut down inefficient, slow-selling fuel car capacity, concentrate funds and capacity into high-growth electrification tracks, becoming common industry practice.
It can be said, this global capacity shrinkage wave initiated by Toyota, also sounded a warning bell for current Chinese independent brands expanding overseas.
In recent years domestic car market fierce competition intensified, top automakers increased investment in overseas factories, complete vehicle exports, Middle East, Southeast Asia are exactly the core growth markets for Chinese automakers going overseas, in 2025 China's car export volume to the Middle East exceeded 1.4 million units, coinciding with Toyota passively yielded market share due to logistics disruption, geopolitical turmoil, many domestic automakers followed suit to increase regional capacity deployment and inventory stocking. But Toyota's dilemma directly exposed the common risks of global car building: single region geopolitical turmoil, sea shipping routes blocked, regional demand changes, can instantly severely damage heavy-asset overseas capacity layout.

At the same time, Chinese automakers going overseas also currently hide two hidden risks: One is some automakers blindly copying Japanese past heavy-asset factory building models, rapidly launching complete vehicle factories in emerging markets, capacity expansion pace far exceeds local new energy penetration rate, very easy to follow Toyota's fuel car capacity excess trap; Two is some overseas products structure single, over-rely on fuel cars or low-price entry-level new energy cars, lack diverse product matrix adapted to different regional policies, road conditions, insufficient ability to resist market volatility.
In addition, geopolitical supply chain risks Toyota is currently facing also reminding Chinese automakers, going overseas cannot only pursue sales volume scale, must simultaneously build diversified shipping routes, disperse regional market layout, accelerate overseas supply chain localization support, reduce impact brought by external sudden risks.
Looking at the overall situation, Toyota's overseas production cut is another heavy signal of the end of the global fuel car era. Auto industry stock competition arrives, geopolitical risk, energy change, electrification wave triple variables are reshaping global auto industry new rules. For all multinational automakers, relying on fuel cars to lie back and win era has completely ended, only by accelerating capacity structure reform, can adapt to the brand new global auto market layout.
 Auto-First | Li Dezhe
Toyota Motor recently announced plans to further increase the scale of its overseas production cuts, raising the total overseas production reduction volume from June to November of this year from the previously planned 38,000 units significantly to 83,000 units, doubling the production cut magnitude. Combined with the preliminary production cut of 40,000 units by Japanese domestic factories for the Middle East market in the first quarter of this year, Toyota's total vehicle capacity reduction plan within half a year exceeds 120,000 units.
Toyota's capacity adjustment this time is highly targeted, mainly aiming at sluggish markets and slow-selling models, including overseas factories in Thailand, India, Malaysia, etc., and overseas production lines dedicated to the Middle East market. Main models with production cuts are concentrated on fuel version RAV4, Camry, Fortuner, Innova and other traditional fuel SUVs and family sedans. Hybrid models and pure electric models capacity remains basically unchanged.
On the surface, short-term geopolitical crisis and supply-demand imbalance might be the main reasons for Toyota's current production cuts, but actually, this also reflects that holding firm to the internal combustion engine base in the global new energy wave has already fallen into a strategic disadvantage.
For a long time, Toyota insisted on hybrid technology route, pure electric model R&D and launch pace was slow, relying on durability and resale value advantages to deep-plow global fuel car blue ocean market. Especially in emerging markets like Middle East, Southeast Asia long-term occupied absolute leading position. However, in recent years, global auto industry landscape completely reconstructed, core markets like China, Europe comprehensively accelerated electrification substitution, Southeast Asia, Middle East and other traditional fuel car "safe havens" also began to gradually introduce new energy supportive policies, local new energy models rose rapidly, diverting fuel car market share.
Toyota continuously shrinking overseas capacity also reflects the new logic of current multinational automakers' global layout. In the past, automakers pursued global layout, capacity full coverage, to reduce production costs with economies of scale; Nowadays global geopolitical conflicts frequent, regional trade barriers rising, car market regional division intensifying, blind expansion of global capacity risk surged. Multinational automakers began to shift from "global expansion" to "precision layout", shut down inefficient, slow-selling fuel car capacity, concentrate funds and capacity into high-growth electrification tracks, becoming common industry practice.
It can be said, this global capacity shrinkage wave initiated by Toyota, also sounded a warning bell for current Chinese independent brands expanding overseas.
In recent years domestic car market fierce competition intensified, top automakers increased investment in overseas factories, complete vehicle exports, Middle East, Southeast Asia are exactly the core growth markets for Chinese automakers going overseas, in 2025 China's car export volume to the Middle East exceeded 1.4 million units, coinciding with Toyota passively yielded market share due to logistics disruption, geopolitical turmoil, many domestic automakers followed suit to increase regional capacity deployment and inventory stocking. But Toyota's dilemma directly exposed the common risks of global car building: single region geopolitical turmoil, sea shipping routes blocked, regional demand changes, can instantly severely damage heavy-asset overseas capacity layout.
At the same time, Chinese automakers going overseas also currently hide two hidden risks: One is some automakers blindly copying Japanese past heavy-asset factory building models, rapidly launching complete vehicle factories in emerging markets, capacity expansion pace far exceeds local new energy penetration rate, very easy to follow Toyota's fuel car capacity excess trap; Two is some overseas products structure single, over-rely on fuel cars or low-price entry-level new energy cars, lack diverse product matrix adapted to different regional policies, road conditions, insufficient ability to resist market volatility.
In addition, geopolitical supply chain risks Toyota is currently facing also reminding Chinese automakers, going overseas cannot only pursue sales volume scale, must simultaneously build diversified shipping routes, disperse regional market layout, accelerate overseas supply chain localization support, reduce impact brought by external sudden risks.
Looking at the overall situation, Toyota's overseas production cut is another heavy signal of the end of the global fuel car era. Auto industry stock competition arrives, geopolitical risk, energy change, electrification wave triple variables are reshaping global auto industry new rules. For all multinational automakers, relying on fuel cars to lie back and win era has completely ended, only by accelerating capacity structure reform, can adapt to the brand new global auto market layout.


