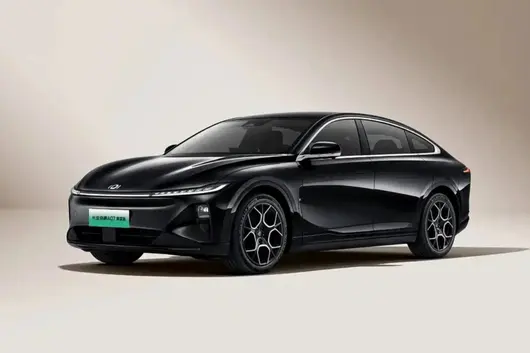
首頁BYD Han

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
Have you ever seen the roads in India?
I've seen them online.
The scene is usually like this: a sedan blocked behind a cow, motorcycles running wild nearby, even milk tea vendors nearby, so "clean and hygienic".

However, in a place where many feel physically uncomfortable after watching, Toyota, Suzuki, Honda and other Japanese car companies decided to bet on India.
According to the Indian "Brand Quality Foundation" website, the three car companies will invest nearly $11 billion to build factories, increase capacity, and develop exports in India.
Some netizens commented: Did the three Japanese car companies have too much money?
In fact, they didn't have endless money to spend, nor were they bewildered by Indian curry. These Japanese car executives are much clearer than us.
Current Japanese car revenue and market share are declining. Raw material costs are soaring. Looking at the world map, finding a market that can accommodate capacity, expand share, and has gentle competition is not easy.
So, it wasn't that Japanese car companies chose India, but because they had no choice.
The Pain of Japanese Car Companies
Past Japanese cars were truly the envy of others.
Ask old drivers who drove Japanese cars over ten years ago, talking about Japanese cars, almost no one doesn't give a thumbs up, cheap price, fuel saving, durable...
Even many Japanese cars needed to be bought at a markup, but who would think this iron fortress would be beaten out of sight in a few short years.
With the wave of new energy vehicles coming, electrification and intelligence became the goal for many domestic car companies to "leapfrog". Relying on China's strong new energy vehicle industry chain advantages and car companies' own persistence on R&D and technology, Chinese independent brands quickly achieved "leapfrogging".
Domestic cars once criticized are now becoming more and more common on the roads, even surpassing joint ventures in share.
According to CPCA data, in April 2026, the share of independent brands reached as high as 62.5%, far exceeding Japan's 13.1%.

You need to know, the Chinese car market is the largest car market in the world. Losing speed in the Chinese market is like losing a huge piece of cake.
Meanwhile, the main theme of the Chinese market in recent years is still price wars. Racing on configuration, price, and service has become a normal state, which also had a huge impact on Japanese cars' profits.
Apart from China, Japanese cars are also not doing well in the US.
On January 20, 2025, Trump swore in as the 47th US President, starting a series of chaotic operations, including imposing additional car tariffs in the name of national security, causing the tariff rate for imported Japanese cars to reach as high as 27.5% at one point. Although it decreased later, it was still far higher than the initial tax rate.
This operation directly led to a tariff loss of over 2 trillion yen for seven Japanese car companies in fiscal year 2025.
Looking at Japan itself, it is actually not easy either.
Middle East geopolitical conflicts blocked shipping in the Strait of Hormuz, transportation costs and raw material costs soared, Japanese car companies also had to suffer in silence.

Executives looking at the reports, their backs went cold, only to find a new growth curve.
So, Japanese car companies didn't fall in love with India, there was nowhere else to go.
Deep Thought on Choosing India
So, what magic does India have, to make Japanese car companies invest heavily?
The first advantage is big. In 2025, the Indian car market achieved 5.517 million new car sales, up 6% year-on-year, breaking the historical record, ranking as the third largest car market in the world, exceeding Japan for four consecutive years, second only to China and the United States.
The value of this doesn't need me to say much. India achieved this result mainly because India has been promoting tax reduction policies to promote consumption, which led to a significant increase in domestic consumption willingness.
The second advantage is close, meaning it is close to places where Japanese cars sell well, such as Africa.
So, India for Japanese car companies is more like a convenience store built in the center of a crossroad. You don't need to ship cars to eight countries separately, just build well at this stop in India, then unload ship by ship, and you can save a lot of costs.

The Nikkei also believes that India is expected to become its global car supply center.
The third advantage is stability. You know, Japanese cars' advantage is fuel cars, after all, the three major components of engines, gearboxes, and chassis, they have played for many years, technology accumulation is number one in the world.
But the Chinese car market has fully promoted electrification and intelligence development, leading to Japanese cars' advantage becoming weaker and weaker, impossible to play out. But India is different, it has the characteristics of few charging piles and slow electrification process. Indian old people buying cars still look for cheap, fuel saving, easy to fix, and these three points are exactly Japanese cars' old trade.
Especially Suzuki, always been India's car market evergreen, almost always sitting on the best-selling model throne, reputation of being worry-free, better than any advertisement.
So, Japanese car companies' vigorous layout of the Indian market is obviously carefully considered.
But, is the Indian market really that easy to mix?
The Hard-to-Bite Indian Market
Of course, India is not perfect like a hot commodity, its disadvantages are as obvious as its advantages, and every one is enough for Japanese car companies to face a hard time.
First talk about electrification. Yes, right now India has few charging piles and electric cars don't sell well, it is indeed a shelter for Japanese fuel cars. But you have to think, how long can this "shelter" avoid?
India previously shouted the slogan of 30% of new cars being electric vehicles by 2030. Although it sounds like bragging, but can't help but they really give subsidies, really build charging stations.
Imagine, what if one day India suddenly wakes up, starts vigorously promoting electrification, doing infrastructure, charging piles popping out like mushrooms after rain, then Japanese cars will be dumbfounded?
Isn't this a version of the Thai market?
Back then Japanese cars in Thailand won easily. The entire Southeast Asian market was called Japanese cars' backyard. Result Thailand took the lead in promoting electrification. Chinese electric vehicles came in, directly became a hot commodity. Look at Japanese cars again, share in Thailand falling down rapidly.

If India accelerates electrification, history will likely repeat, and this time, Japanese cars don't even have a place to flee, how to prevent will become the first problem for Japanese car companies.
Next talk about policy. India's policy is like a pot of curry, you never know if you will eat chicken or potato next time.
This magical country, today low tariff encourages building factories, tomorrow may fine you a huge amount. What's more annoying is mandatory joint venture. Foreign car companies want to sell cars in India, have to find local partners to partner up. When your factory is built, supply chain is done, India directly backstabs you. At that time whether adding money or withdrawing capital, what you get is heartache.
So you see, this market like India is like a mango that looks very sweet, bite the first mouth it's okay, chew two more mouths hit the hard core.
Japanese cars now is calculating, while the core hasn't bit the tooth, hurry up to nibble a few more mouths, but the core will bite sooner or later, just don't know which day.
Epilogue
Japanese cars this trip to India, not go for tourism, is go to make a living.
Chinese and Southeast Asian dining tables are more crowded, production and transportation costs have risen. Looking around the world, only this pot in India is still steaming, even if what is boiling inside is curry-flavored stones, have to bite hard and chew down.
Japanese car companies want to expand market, India wants to pull economy, solve employment, both sides have their own thoughts.
As for the ending is Japanese cars in India regain their glory, or like past competitors shamefully walk away, then is not known.
But no matter how, this play just started, we slowly watch is okay.
Anyway India's story, never bored.
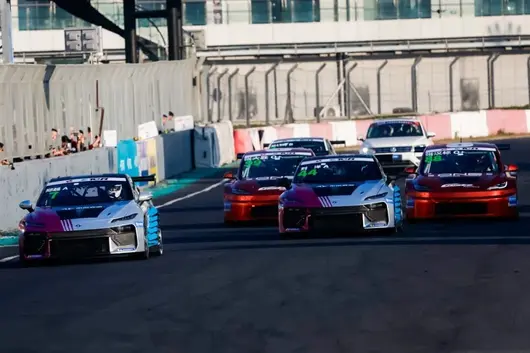
2026 年,CTCC 電動賽車盃&XRACING ETCR CUP 將繼續展開賽季的爭奪,旨在推動中國電動賽車運動規範化、專業化正向發展。目前,賽事的初步賽歷正式揭曉,將橫跨國內多地專業賽道,聯動國際知名賽場,以多元賽道陣容開啟全新電動競速征程。


9 月 19 日至 20 日,賽事將在上海天馬賽車場,打響年度揭幕戰。作為長三角經典場地賽道,緊湊多彎的天馬賽車場將全面考驗 ETCR 賽車的操控與調校實力。

隨後,賽事將在 10 月 10 日至 11 日移師寧波國際賽道。這條依山而建、彎道組合複雜多變的賽道,將再度迎來 ETCR 的極限比拼。

10 月 24 日至 25 日,賽事將轉戰湖南國際賽車場,與 CTCC、TCR World Tour 國際汽聯汽車世界巡迴賽同場聯動,聯袂獻上高規格競速盛宴。


11 月 21 日至 22 日,ETCR 賽車將以靜態展示形式在澳門格蘭披治大賽車賽事期間亮相,向車迷集中展現國內電動賽車運動的發展成果。

12 月 12 日至 13 日,賽季收官戰將在馬來西亞雪邦國際賽車場打響。作為東南亞唯一的 FIA 一級認證賽道,雪邦賽車場寬闊的佈局與高速路段,將為年度總冠軍的誕生埋下懸念,為賽季畫上圓滿句號。

電驅馳騁、逐風競速,2026 賽季 CTCC 電動賽車盃&XRACING ETCR CUP 大幕即將拉開。敬請期待!
Folks, today let's talk about big news on going global—not selling cars, but selling "drivers". On June 2, WeRide and Uber jointly announced a plan: to launch the country's first commercial Robotaxi pilot service in Madrid, Spain. In other words: Spanish residents will soon be able to hail a driverless taxi via Uber. This is the first time WeRide and Uber are partnering to enter the European market. Madrid also becomes the 12th city globally where WeRide's Robotaxi arrives.
According to official news, with the support of the Madrid regional government, this service will officially launch within this year. At that time, friends in Madrid can open the Uber App and call WeRide's Robotaxi with one click. It's just like calling an ordinary ride-hailing service, the difference is the arriving car has no driver—at least initially, there is still a difference. In the initial operation phase, a professionally trained safety monitor will be on board, as it's just launched, safety comes first.
This company, WeRide, you might have heard of it, or you might not. A brief introduction: Established in 2017, it has been dedicated to Robotaxi technology R&D and commercialization. Currently, its Robotaxis cover Guangzhou, Beijing, Singapore, Abu Dhabi, Dubai, Riyadh, Zurich... plus Madrid now, totaling 12 cities. Spain is also the 5th European market WeRide has entered—previously entered Switzerland, France, Belgium, Slovakia. According to the plan agreed by WeRide and Uber in May 2025, they plan to deploy Robotaxi services in 15 new international cities within five years, deploying tens of thousands of Robotaxis globally. With the Madrid launch, the deployment in 4 cities has been completed, and 11 more will be covered successively before 2030.
To be honest, it's not the first time Chinese autonomous driving companies are going global, but the combination of Chinese technology + global mobility platform + European market is quite interesting. Madrid is one of the European Robotaxi markets with the most commercial potential, with a large population, high travel demand, and friendly local policies. Being able to take root in this market is a significant milestone for WeRide. For Uber, introducing Robotaxis is also a way to reduce costs—after all, drivers don't need salaries. For Madrid residents, hailing a taxi might be cheaper in the future.
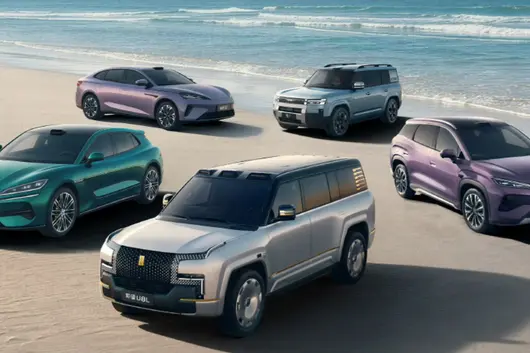
比亞迪正式發布 2026 年 5 月產銷快報,全品牌新能源汽車單月銷量 383453 輛,同比微增 0.26%,時隔十個月實現單月銷量同比轉正;其中乘用車交付 376990 輛,環比大漲 19.4%,一掃前期車型換代陣痛,呈現國內基本盤穩固、海外銷量狂飆、高端品牌全線放量的全新格局,在國內新能源內捲加劇、特斯拉 FSD 入華、自主新品密集上市的市場環境中,走出獨有的結構性增長路線。

王朝 + 海洋兩大主力品牌 5 月合計售出 330215 輛,佔據集團總銷量超八成,仍是比亞迪銷量壓艙石,全系列共 8 款車型單月銷量突破 2 萬台,產品從 5 萬入門代步到 20 萬家用 SUV 實現全覆蓋。

王朝網內部,元家族 56691 輛、宋家族 51370 輛。雙雙跨過五萬門檻,成為品牌兩大銷量支柱,兼顧家用代步與城鄉出行需求;秦家族緊隨其後交出 28360 台穩定表現,漢、唐系列月銷維持六千級體量,深耕中大型家用轎車、SUV 細分市場;全新車型夏處於市場培育期,單月交付 1810 台,後續隨渠道鋪開有望穩步上量。
海洋網增長勢頭更為迅猛,全系五款車型跨入兩萬俱樂部:海獅 42615 台、海豹 34117 台、海鷗 39919 台、海豚 22260 台、宋 PLUS 27755 台。其中海鷗憑藉 6-8 萬親民定價穩居入門代步銷冠,海獅作為全新走量車型上市即站穩四萬量級,補齊海洋網中型 SUV 產品空白,完善海洋產品梯隊佈局。從代步小車到緊湊 SUV,兩大主品牌依托 DM-i 混動與純電雙線技術,牢牢鎖住 15 萬以內國內主流家用市場份額。
方程豹同比暴漲 139.7% 品牌向上落地見效騰勢、方程豹、仰望組成的高端矩陣 5 月合計銷售 46489 輛,正式擺脫小眾定位,成為比亞迪品牌溢價與利潤增長新支點,打破自主品牌高端化難破局的行業魔咒。

越野品牌方程豹單月 30186 輛,同比暴漲 139.7%,創下品牌上市以來月度銷量新高,旗下鎦 7 單月 18280 台,豹 5、豹 8 穩定輸出,在 25-40 萬硬派越野細分市場持續擠壓合資、進口車型生存空間。

騰勢 5 月交付 16303 台,MPV 標桿 D9 售出 6721 台,Z9 系列近 6000 台,MPV、中大型轎車雙線發力,站穩豪華新能源賽道;百萬元級超豪華品牌仰望穩步爬坡,當月交付 286 台,同比增幅 105.8%,完成自主品牌天花板產品的市場驗證,形成從十幾萬家用、三四十萬越野、五十萬豪華 MPV 到百萬元級旗艦的全價格帶產品佈局。

5 月比亞迪乘用車和皮卡海外銷量 160177 輛,同比大漲 80.7%,出口佔全系總銷量突破 42%,創下品牌出海歷史新高,成為穩住 5 月整體銷量、實現同比轉正的核心驅動力。
東南亞、歐洲、拉美成為主力增量市場,海鷗、宋 PLUS、元系列持續登頂多國新能源熱銷榜單,SHARK 皮卡連續兩月單月出口突破 4000 台;依托泰國、巴西、匈牙利、烏茲別克斯坦四大海外整車工廠落地投產,本地化生產持續落地,規避關稅同時快速下沉終端渠道。在國內車市存量競爭、價格戰常態化背景下,高速擴容的海外市場有效對沖國內車型換代帶來的銷量波動,正式從補充市場升級為比亞迪核心增長引擎。截至當前,比亞迪新能源汽車全球累計銷量已經突破 1650 萬輛,全球化版圖持續拓寬。
智駕賦能產品迭代 下半年新品蓄力衝量5 月比亞迪智能化落地迎來關鍵節點,天神之眼智駕系統成為車型核心加分項:全品牌搭載高級智駕車型保有量突破 315 萬輛,日均路測數據超 2 億公里;當月比亞迪落地城市領航、智能泊車雙安全兜底服務,成為全球首家實現兩項智駕兜底的車企,政策落地三天後,搭載天神之眼系統車型的城市 NOA 激活率暴漲 50%,智能化體驗升級直接拉動終端到店訂單轉化,為後續車型持續走量築牢產品競爭力,直面 FSD 入華帶來的智駕市場衝擊。
從數據細節來看,2026 年 1-5 月比亞迪累計銷量 1405039 輛,同比下滑 20.32%,核心誘因是全系主力車型集中換代、第二代閃充刀片電池產能爬坡受限。新款閃充電池升級快充與低溫性能,全系換代車型優先換裝新電池,但產線改造拖累產能釋放,熱門車型訂單積壓、交付延後,一定程度壓縮 5 月交付體量。
隨著二季度末二代刀片電池產能持續釋放,疊加騰勢 N8L、方程豹鎦 7 純電版、海獅 05、夏 L 等多款新車陸續登陸市場,業內普遍預判比亞迪 6 月全品牌銷量有望突破 40 萬輛。依托低端走量鎖份額、高端提利潤、海外衝增量、智能化提產品力的四維發展邏輯,在國內新能源淘汰賽加劇的當下,比亞迪全品類佈局優勢持續放大,坐穩國內新能源龍頭,加速向著全球頭部車企穩步邁進。

Auto Industry Data Says
Do you believe it? Some car companies sell 200,000 units, wishing to beat drums and announce holidays for three days; but Changan sold 209,100 units, yet people still fixate on the 6.78% year-on-year decline, making an expression as if 'the sky is falling'. To be honest, my first reaction after reading May sales was not 'bad', but rather — do these people have some misunderstanding of 'bad'?
On June 1, Changan Auto revealed official sales data: Overall sales for May 2026 were 209,100 units. New energy 92,400 units, accounting for 44.2%; overseas exports 70,700 units, surging 38% year-on-year. Among the three sub-brands, Qiyuan and Deepal both reached the 34,000 unit milestone, Avatr 7,336 units.
CheYu World found, looking across all of China, there are only four domestic brands with monthly sales over 200,000. Changan sits firmly in the fourth spot, ahead of BYD 383,000, Chery 247,800, and Geely 237,800.
Do you think this performance deserves a 'good job'?

Changan Qiyuan A07
We need to speak fairly
209,100 units, showing a slight growth compared to May. What does that mean? Put three years ago, this is a number that could crush most joint-venture brands.
Even in today's fiercely competitive market, Changan remains one of China's top car players. Those who just fixate on 'Changan is down' without seeing anything else, might as well ask themselves — how many 4S dealers on the street downstairs from your home can sell 2,000 units in a month?
So, the first conclusion is clear: Changan's May sales are not face-losing, but quite capable.
But CheYu World also understands why the decline is watched. Because Changan sold 224,300 units last year at this time, 15,200 units less this year. A 6.78% year-on-year decline, in an opinion field of 'fight for first, don't ask for second', is indeed easily amplified. Plus, new energy growth was only 5.8%, lower than the industry average growth rate, so attracting attention here is not surprising.

Deepal S07
Take it easy, let's calculate the accounts one by one
First, look at new energy. 92,400 units, accounting for 44.2%. Is this ratio high? Put last year at this time, Changan's new energy penetration rate was less than 35%.
Increased nearly ten percentage points in a year, do you call this 'failing to keep up with the rhythm'? That's called running forward. It's just that rivals on this track run crazier — BYD is fully new energy, penetration rate 100%; Geely and Chery are also scrambling to catch up.
Changan's 5.8% growth rate is indeed not high, but CheYu World believes you must know, Changan's fuel base still has CS75PLUS, Eado these 'cash cows' stably pumping blood. It is not 'All in' new energy walking on one leg, but both legs are exerting force. CheYu World believes, this 'steady progress' approach, in the current economic environment, is not necessarily a bad thing.

Avatr 07L
Next look at overseas. 70,700 units exports, 38% year-on-year growth. Thailand, Middle East, Latin America, Europe, Changan's strides are quite large. Deepal overseas surged 167% in the first 5 months, indicating the overseas market is starting to recognize Chinese brand new energy products. Don't underestimate this 38%, when domestic market competition is heated, price wars kill until rivers of blood flow, overseas market is Changan's most reliable 'second battlefield'. Moreover, generally, cars sold overseas, profit margins are often higher than domestic by a margin. This deal, is worth it.
Finally look at brand structure. Qiyuan 34,528 units, Deepal 33,243 units, the two together nearly 68,000 units, supporting most of Changan's new energy.
Avatr 7,336 units, although number is small, average price over 300,000, is Changan's 'only seed' truly charging premium. Some say Avatr sells not good enough, but you must admit, the pure electric market above 300,000, originally is not about moving volume. Avatr can stabilize at over 7,000, plus Huawei intelligent driving support, this performance actually is not bad.
What really needs watching is the second half of the year — Avatr's new models can open the situation, can explain clearly 'why I am worth your buy'. Once this problem is solved, Avatr might take off.

Changan
So does Changan have worries or problems?
Of course there are. Any large factory selling over 2 million units a year, cannot be perfect without flaws.
For example, one hidden worry, I feel it is not the 6.78% decline year-on-year, but the question of 'whether Qiyuan and Deepal actually have internal friction'.
Objectively speaking, these two brands may have some overlap in some aspects, such as, some model prices overlapping, target customers may also have some overlap, etc. In fact, this question, should have also caused Changan side to think. Changan needs to think clearly: Qiyuan and Deepal, who is the goalkeeper, who is the striker?
Another problem, is how Changan's 'new brand voice' story is told. This is not a product problem, might be a communication and positioning problem.

The official might have also noticed this problem
CheYu World believes, Changan has technology, has capacity, has channels, but, Deepal, Avatr, Qiyuan, if building a brand story that allows consumers to 'remember at a glance, understand upon talking', might be a question worth the brand side thinking about. Of course, this is just personal opinion.
Its full year sales target, can it be completed? Changan 2026 overall sales target is 3.3 million units, 13.3% year-on-year growth; Among them new energy 1.4 million units, 26.2% year-on-year growth; Overseas 750,000 units, 17.7% year-on-year growth.
According to Changan announced data, this year Jan-May, its cumulative delivery amount 1.0122 million units, completion rate 30.7%. Meaning, Changan Auto needs in remaining 7 months, average per month complete 326,000 units.
Obviously, according to Changan current sales level, this should have pressure. But speaking back, CheYu World believes, these are not fatal injuries. For a car company selling 200,000+ units, still continuously expanding overseas, increasing new energy ratio, these problems at best called 'growing pains', not 'life or death crisis'.

Deepal
I want to say a heart-to-heart words:
Do our requirements for Changan, is it a bit too high? Of course, this might be 'love is deep, criticism is sharp'. You always think it should be better.
209,100 units, put in any global car market, are numbers worth popping champagne. Chinese consumers are impacted by 'monthly sales 300,000', 'monthly sales 400,000' these numbers, seeing 200,000 feel instead unsatisfied. But you think calmly, globally car companies that can stabilize monthly sales over 200,000, counting on fingers are limited.
CheYu World believes, Changan is not without anxiety, also not without pressure or transformation pangs. It's just, the way it chose is not crying miserably, but quietly going overseas, quietly launching new, quietly doing new energy ratio to 44%. This 'working quietly on big things' spirit, instead makes me feel secure.
Of course, second half of the year exam is also key. Qiyuan and Deepal can step up again? Avatr can tell new stories? Overseas market can withstand trade barriers etc pressure? These problems, Changan itself inside might have number, we as bystanders, might as well give more patience.

Eado Classic Version
Finally, I want to pass the microphone to you:
You think Changan current gameplay, is 'steady and sure', or 'too conservative'? If you are Changan planner, would you first solve Qiyuan and Deepal possible overlap or internal friction problem, or first tell Avatr, Deepal, Qiyuan stories through? Come comment section, we chat while eating sunflower seeds.
Finally, this article involves related data, sourced from brand official and authoritative media news, for reference only, specific details shall prevail according to official response. If there are typos etc caused information, data mismatch, as official information. Hope everyone view rationally, do not believe rumors, do not spread rumors.
Article Statement:
This article is CheYu World original article, Issue No. 14088, some images sourced from internet, marked source data and related materials all are cited. CheYu World original copyright owned, infringement will be pursued.