首頁Arrizo 8 PRO

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
Recently, Chery Chairman Yin Tongyue said some ill-timed words at the 2026 World Intelligent Connected Vehicle Conference: "We should learn from the experience of motorcycles going global; we must firmly avoid a price war; prepare well and do not go global blindly." He also reminded peers not to become "overseas boasters" abroad.
The reason these words were piercing was not because they were harsh, but because they were timely. In 2026, the global expansion of Chinese cars is at its most frenzied moment: exports will break 12 million units, 20 out of 60 brands at the Paris Motor Show are from China, overseas factory planned capacity is close to 7 million units, and almost every car company has "go global or get out" on their lips. At this moment, China's largest car exporter said: Don't learn from motorcycles.
Someone who has already sold cars to over 130 countries could have talked only about achievements. He insisted on talking about lessons. Few people in the industry understood the weight of this sentence.
Over twenty years ago, Chinese motorcycles experienced a complete demise in Vietnam. In 1998, Japanese brands accounted for 98% of the Vietnam market, selling cars for $2,000 each; Jialing, Zongshen, and Loncin rushed in with wholesale prices of $700 to $800, capturing nearly 90% of the market share by 2002. Then the price war began: $800 dropped to $700, then to $600, and finally fell to $170; selling a car only earned over thirty yuan. Steel sheets became thinner, engines used non-standard parts, and after-sales service points were not built. In 2003, a frame fracture accident was exposed by television, triggering an avalanche of trust. By 2006, Japanese brands regained over 95%, and Chinese motorcycles were left with less than 1%.
What killed Chinese motorcycles was not low prices, but the lack of a retreat after low prices: profits were too thin to invest in quality, service, and brand; a single accident could cause the entire category to perish.
Cars are not motorcycles. But that transmission chain—price wars, thinning profits, quality and service hemorrhaging, trust collapse, policy backlash—has already appeared in Thailand, Europe, and Russia simultaneously.
More exports, more like motorcycles back then
The underlying logic of domestic price wars is overcapacity, product homogenization, and dealers holding inventory. In the first half of 2026, domestic passenger car retail sales slid 20% year-on-year, industry profit margin was 3.3%, and capacity utilization was 70.8%, below the 80% break-even line. Cars are not selling well, so exports became the pressure relief valve.
Exports in the first 9 months of 2026 reached 8.63 million units, with the proportion of total production moving from two tenths close to three tenths. Chery exported 1.344 million units in 2025, and BYD exported 1.054 million units. The numbers look good, but the pressure relief valve has side effects: the domestic tactics will go out with the cars.
More alarming is that going global has become a collective sprint. Over 130 overseas production bases, 7 million units of planned capacity, and 20 Chinese brands at the Paris Motor Show; everyone is racing for the window. Yin Tongyue's warning came at this moment of collective sprint, when suddenly someone shouted: There is a cliff ahead.
The cars are the same batch, the dealers are the same rebates and inventory pressing, the sales pitch is still "drop a bit more to increase volume." The only change is that overseas market depth is shallower, consumer patience is shorter, and policy hands are harder.
In August 2026, the Ministry of Commerce, Ministry of Industry and Information Technology, and State Administration for Market Regulation jointly issued the "Guidelines on Overseas Competitiveness Behavior and Compliance Construction for the Automotive Industry," clearly requiring car companies to avoid "frequent and significant price fluctuations affecting overseas consumer interests and brand image," and to respect local dealer independent pricing rights. The regulatory layer saw the danger before the companies.
Exports are not a cure, they are painkillers. Cars that don't sell domestically won't become good business just with a different customs.
Thailand acted it out first: subsidy withdrawal, share dropped from 47% to 11%
In 2025, Chinese brands sold 134,000 units in Thailand, market share 22.2%, Japanese brands first dropped below 70%. In January 2026, Chinese brands won 47.34% to 47.33%, a narrow victory of 0.01 percentage points, topping Thailand.
A month later, Thailand subsidies were withdrawn, import car consumption tax adjusted back from 2% to 10%. Chinese brand share plummeted from 47.3% to 11.6%.
Of that 47%, a significant portion was not brand loyalty, but policy rent. Price wars spent the rent early.
BYD ATTO 3 dropped from 1.19 million Baht to 900,000, and dropped another maximum of 340,000 in July 2026; Dolphin dropped from 800,000 to over 500,000. BYD used one year of free charging to soothe old car owners, but still some brands were complained about due to price drops.
Even worse was Neta. The Thai government wanted to recover 2 billion Baht in subsidies because Neta failed to fulfill local production commitments: 2024 target 16,000 units, actually only produced about 4,000 units. 18 dealers sued jointly, showrooms shrank from over ten to three, and some insurance companies stopped underwriting. When a brand explodes, the whole "Chinese car" category perishes along with it.
Chinese car companies' planned capacity in Thailand exceeds 550,000 units, while the entire Thai market is only 600,000 units. Factories are built, the market is not that big, price drops to swap volume became a "helpless choice".
Prices can buy market share, not loyalty; subsidies can create a market, but can also be taken back overnight. Using domestic methods to fight overseas means market share is rented.
European residual value accounting: The bill for price wars arrives three years later
In the first half of 2026, Chinese brands sold 643,000 units in Europe, market share rose from 4.5% to 8.9%, year-on-year growth 111.5%. Entry-level models are 20% to 30% cheaper than European competitors.
But Europe has an account rarely calculated domestically: residual value.
Data from German DAT shows that Chinese brand plug-in hybrids retain only 47% of car price after three years of use, it was 61% at the beginning of 2024; dropped 14 percentage points in two years, while German EVs overall only dropped 7 percentage points in the same period. Chinese car depreciation speed is twice the market.
Residual value is the foundation of European auto finance. Europeans use loans, leases, and trades heavily; every point drop in residual value becomes a monthly payment. A 38,000 Euro car, with residual value dropping 14 percentage points in three years, means selling 5,320 Euros less; amortized over 36 months of lease, adding 148 Euros per month. Large leasing companies have started to increase leasing prices for Chinese brands.
More troublesome is expectations. DAT survey shows nearly half of German consumers believe some Chinese brands will exit Europe within five years. Used car buyers squeeze prices, financial institutions increase down payments, brands try to fill the pit with subsidies—a self-reinforcing negative cycle.
Chinese car companies haven't not calculated this account. BYD invested 4 billion Euros in its Hungary factory, initial capacity 150,000 units, depreciation per vehicle amortized 2,600 Euros alone; annual sales need to reach 120,000 to 150,000 units to cover fixed costs. If continuing to drop prices to grab share, residual value will break the financial model first.
Dropping prices domestically hurts old car owners' hearts, dropping prices in Europe hurts the financial model's life. The former can be soothed with one year of free charging, the latter takes three or five years to fix.
Russia and Mexico remind: Markets will close, policies will turn face
The biggest risk of Chinese car global expansion is not cars not selling, but markets suddenly not letting you sell.
Russia imported over 1.16 million Chinese cars in 2024, dropped to 632,000 units in 2025, nearly halved; Chinese brand share dropped from 58.5% to 51.7%. In Q1 2025, Russia closed 274 car showrooms, 213 were Chinese brands, accounting for 78%. Chery has already sold some assets and distribution channels in Russia.
The reason is not complex: scrap tax increased 70% to 85%, tariffs adjusted to 20% to 38%, parallel imports blocked, certification cycles lengthened. When policies turn, the number one market becomes number three.
Mexico was still China's number one export destination for cars in 2025, from January 2026 tariffs of up to 50% on Chinese cars; Chinese exports to Mexico dropped 33.7% in the first half. After the EU imposed tariffs of up to 45.3% on pure EVs, it is now discussing expanding restrictions to hybrids.
These policies target not just one enterprise, but the "export model" itself. Cars shipped from China to earn manufacturing efficiency and exchange rate differences; the host country adds tax, changes certification, or collects subsidies, the advantage is gone.
The only thing to hedge against is leaving manufacturing, R&D, supply chain, and employment locally. But Chinese car companies' overseas fully integrated factory planned capacity is close to 7 million units, overseas production in 2025 was only about 1.2 million units; of over 130 production bases, only 17 are truly fully integrated; overseas localization rate is about 30%, while European, American, and Japanese car companies are over 80%.
7 million units of planning is like moving domestic overcapacity exactly as is to other ports. Localization is not a panacea, but without localization, there is not even the qualification to get sick.
Cars are not motorcycles, but there is no immunity badge
Cars and motorcycles are not the same. Motorcycles have no core technology, sell and leave; Chinese cars have three electrification technologies, smart cockpits, smart driving; in Thailand can sell Seal for 270,000 Yuan, in Brazil can sell BYD to single month retail first.
But "not the same" does not equal "having immunity badge".
Motorcycles died from "no ability to do three things after low price": make quality steady, make after-sales dense, make brand go up. These three things, Chinese cars have not fully achieved. Australia has already seen Chinese EVs under regulatory attention due to closed maintenance data, consumers complaining about long parts wait times; Cui Dongshu's judgment is direct: Chinese cars overseas are still "cost advantage main, technology premium auxiliary, brand premium not yet formed", difficult to break through above 400,000 Yuan.
Price wars happen to destroy these three things. Profits thinned, no money for quality verification, building after-sales, investing in brand; residual value not rising, financial costs cannot go down; full lifecycle cost more expensive, low price finally becomes "expensive".
Hyundai Motor is the opposite reference. Excel entered the US in 1986, sold 168,000 units in the first year; years later quality collapsed, became a talk show joke, sales dropped to 90,000 units in 1998. That year Hyundai launched 10-year/100,000-mile warranty, by 2004 new car quality caught up with Honda. But warranty was just a signal, Hyundai took twenty years to truly make products good.
Japanese cars are another reference. Forced to accept voluntary export restraints to the US in 1981, 1.68 million units annually, lasting until 1994. Japanese car companies did not continue to drop prices, but went to build factories in the US: from 1985 to 1990, US production increased from 820,000 to 1.8 million units, share rose from 18% to over 25%, and launched Lexus, Acura, Infiniti at the same time.
Trade barriers did not stop Japanese cars, localization and brand upgrade did. These two things, Chinese cars are still on the way.
Yin Tongyue's warning is first for Chery itself
Chery is one of the biggest beneficiaries of going global. 2025 revenue 300.29 billion Yuan, overseas revenue 157.42 billion Yuan, accounting for 52.4%—overseas revenue exceeded domestic for the first time; exports 1.344 million units, number one for 23 consecutive years.
But in the first half of 2026, Chery exports grew 71.5%, net profit attributable to the parent company dropped 11.7%. Revenue almost stood still, gross margin rose to 16.1%, net profit actually decreased. Going global scale is rising, making money is harder.
Chery's gross margin was originally not high. Q1 2025 12.4%, lower than BYD 20.1%, Geely 15.9%, Great Wall 17.84%. It relies on scale, channels, and cost-performance to sell cars globally, fears overseas becoming domestic-like price wars.
So Yin Tongyue's warning is not moral persuasion, it is accounting. Chery has half revenue overseas, overseas gross margin higher than domestic; overseas price war, Chery's income statement will hurt first.
Chery is also finding a retreat for itself. Barcelona, Spain, Chery and EV MOTORS joint venture restarted original Nissan factory, producing EBRO S700, one car out of line every 75 minutes, first phase annual capacity 50,000 units, creating over 1,000 local jobs; as of May 2026, EBRO registered 11,131 units in Spain.
Yin Tongyue has spoken of Chery's "cat philosophy": "We are like cats, entered quietly, then quietly became part of his family." This sentence is exactly opposite to "sea braggers". It is not posture, it is method: sell cars first, then build channels, then localize, finally become part of local industry.
Yin Tongyue is not singing doom, it is warning.
He brought out the old accounts the industry is most unwilling to hear, because he knows, if this account is not reviewed, it will be paid sooner or later.
Epilogue
In 2002, when Chinese motorcycles took 80% share in Vietnam, no one thought that was the end. In 2026, when Chinese car exports stood at 12 million units, no one thought that was the end.
The difference is, motorcycles have no second chance, cars do. The timeliness of Yin Tongyue's words is not because it exposed some secret, but because it exposed too early—early enough for the industry to still have time to change.
Chinese cars have technology, have supply chain, have local factories, also have profit space to fix quality, after-sales, brand. But opportunities will not automatically redeem, it depends on one choice: treat overseas as a sewer to digest domestic inventory, or as a second entrepreneurial venture.
Next to verify is only one thing: when domestic retail continues to slide, which car company dares to be the first to stop using overseas markets to digest inventory?
The answer to this question will better explain the substance of Chinese cars going global than 12 million units.
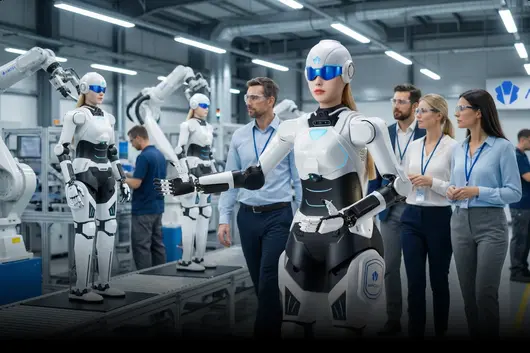
August 19, Chery Executive Vice President, General Manager of International Business Group and General Manager of MoJia Robotics Zhang Guibing revealed during the 2026 World Robot Conference that MoJia Robotics (AiMOGA Robotics) under Chery has launched IPO preparations, is currently negotiating with multiple listing venues, and the timetable is yet to be determined. He stated that listing can raise financing for technical investment and also help improve governance transparency.

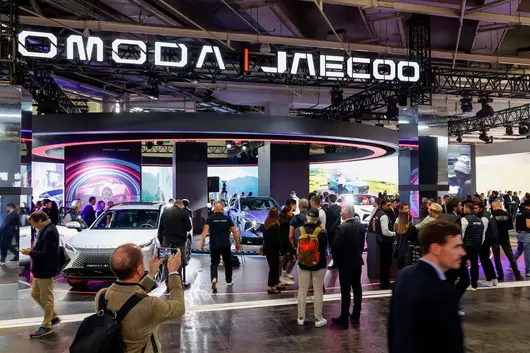
MoJia's starting point was not building robots, but the digital virtual avatar Mornine (Mornine). Around 2023, Chery's overseas brand OMODA heated up the C5 model, creating virtual human Mornine that resonates with Gen Z, active on promotional animations, brand live streaming platforms, and more.
The turning point began with operational pain points encountered in Chery's overseas stores. Zhang Guibing revealed that overseas sales are affected by peak and off-peak seasons, staff turnover is frequent, recruitment is difficult, and even if hired, multi-language training is a high threshold. The team thus conceived the idea of "letting Mornine walk into reality", which became the origin of the AiMOGA Robot project.
At the end of 2023, Mornine's first prototype went off the line, and in early 2024, it made its first public appearance at Chery's Global Dealer Conference. After more than two years of technical accumulation, on January 7, 2025, Chery officially invested to establish "Anhui MoJia Smart Innovation Robotics Technology Co., Ltd.", with registered capital of 100 million yuan, legal representative Zhang Guibing, MoJia transformed from an internal project to an independent legal entity.

In February of the same year, Mornine completed its first overseas commercial debut at the Kuala Lumpur store in Malaysia; in April, it appeared at the Shanghai Auto Show, demonstrating multi-modal perception and dexterous operation capabilities; in October, at the Chery Global Innovation Conference, it gave an autonomous speech in seven languages, becoming the focus of the whole event.

From December 2025 to January 2026, MoJia completed the first round of capital increase and strategic investment, registered capital increased to about 104 million yuan. After capital increase, the latest equity structure shows Chery Motors holds 96%, Bethel 1.40%, Fuchun Dyeing 1.20%, Hexie Chaoyue Fund 0.40%, Zhiyuan Innovation 0.20%, Wuhu Economic Development Zone Weida Venture Capital 0.40%, Wuhu Sci-Tech Investment Fund 0.40%.
In terms of performance, MoJia's cumulative global deliveries have exceeded 3,000 units, approximately 2,000 sold overseas, business covers 60 countries and regions, it is the world's first humanoid robot to complete dual EU software and hardware certification. On April 27, 2026 press conference, signed an order for 1,000 intelligent police robots at once and delivered 110 units on-site, product line thus expanded from "4S store sales associates" to the public security field.
Key customers cover Chery's overseas dealer network and public security departments of multiple cities.
Zhang Guibing revealed plans to increase global delivery volume to 10,000 units in 2027, join the industry's first tier, and proposed "three specific actions: improving reliability and cost-effectiveness of large-scale applications, iterating in over 50 countries and 100+ scenarios, achieving 100 unit deliveries to trigger 1,000 unit intent signings."
Industrialization advances in three stages according to "scenario-driven technology", first make child companion scenario robots, then expand to public service and enterprise service scenarios, finally promote robots entering homes.
In terms of supporting construction, 31 innovation labs have been set up, "AiMOGA Academy" established, signed with 100 universities to train talent, quadruped robot production line annual capacity reaches 15,000 units.

At Chery AI Night in January of this year, Chery Chairman Yin Tongyue proposed a "One Bottom Line, Three Directions" strategy, using cars as the cornerstone to promote AI extension to the physical world, covering humanoid robots, Robotaxi, smart agricultural machinery and other scenarios, "putting the car brain into the bodies of other industries". He revealed Chery's R&D budget for 2026 exceeds 32 billion yuan, the "2R Technology" composed of Robotaxi and MoJia is one of the four key focuses, and stated that the original intention of the layout is a rethinking of the "second growth point after the total number of future cars decreases".
At the April 27 MoJia press conference, he once again stated: "We most do not want to be defined as a car company, but as a high-tech, embodied, innovative company facing the future."
He proposed "intelligent cars are mobile robots", robots and intelligent cars have highly homogeneous underlying technologies in perception, planning, control, etc., technology modules and supply chains can be transferred.
2026 is regarded by the industry as the year of concentrated release of automakers' embodied intelligence layouts, globally over 20 mainstream automakers have entered the game through self-research, incubation, investment, etc., the industry is shifting from technology exploration to mass production racing.
MIIT data shows, China's quadruped robots already account for nearly 70% share of global sales. The industry generally judges that 2026 to 2028 will be the key verification window for humanoid robots to go from "prototypes" to "mass production of 10,000 units", but commercialization loop is still in early "strategic loss" stage, bottlenecks such as limited application scenarios and high costs remain to be broken. Against the background of the automotive industry profit margin falling below 3%, embodied intelligence has been regarded by many automakers as a "second growth curve" to hedge against the slowdown of the main business growth.
Source: Car Observer