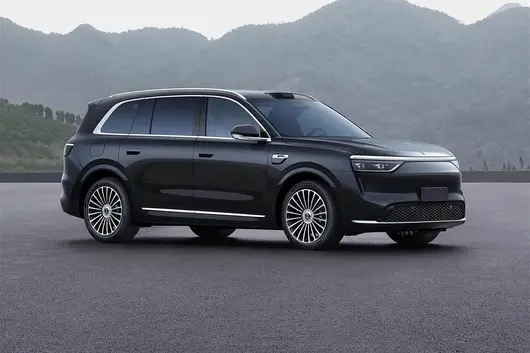
首頁AITO M8

搜尋歷史
熱門搜尋
經銷商登入 / 註冊
In one month, 19,000 units vanished out of thin air.
Roughly calculating based on AITO's average transaction price of over 300,000 yuan, this represents over 6 billion yuan in revenue, gone just like that.
This is Seres' August report card: NEV sales of 24,244 units, a year-over-year drop of 43.96%.

Yet, hidden in the same table is a contradictory situation — the all-new AITO M9, a major player with an average price of 600,000, delivered over 30,000 units cumulatively in 12 weeks! It sat at the number one sales spot in the 500,000-price-segment market for two consecutive months.
Premium sales are getting better, yet the total volume collapsed by 40%. Putting these two numbers together is where the most significant aspect to consider lies in this decline in August.

So what exactly happened to AITO? Is it really in trouble?
My view: Don't rush to predict doom, nor rush to find excuses for it. This stumble is half because it stood too high last year, and half because Huawei stores no longer have AITO as the sole prime spot — and AITO happened to catch the timing between old models phasing out and new ones not yet arriving.
First, the most practical point: That number from last year was inherently abnormal
Year-over-year data is easiest to deceive with. It compares not how much was sold this year, but how much less was sold this year compared to last.
That summer in 2025, the AITO M8 EV version exploded in orders upon launch. The entire August saw AITO M8 EV and Extended Range models sell over 20,000 units in one month, forcibly pulling the whole brand onto a high stage. When you jump down from a two-meter-high platform, the drop in landing is naturally significant.

Change the calculation and it becomes clear: Seres cumulative sales from January to August reached 227,250 units, down 12.58% year-over-year. Single month down 40%, cumulative down over 10%. These two numbers together show the true water level — the drop mainly hit the base number.
This month of August, AITO was exactly stuck in the gap of gear shifting
Few have fully explained this layer of reason, but it is the most crucial.
Look at AITO's current product lineup and it becomes clear: The old M7 is at the end of its lifecycle, sales were naturally declining; M8 is in the middle of a facelift switch, old stock cleared out, new version not yet selling, the channel is basically empty; M9's Ultimate Lingshi Long Wheelbase version was announced for a long time, ready for delivery only by the end of August, people wanting to buy are clutching money waiting.

The old are exiting, the new haven't arrived, this month in between is a vacuum.
AITO M6 is considered the most volume-capable model at the moment, with cumulative deliveries already breaking 50,000 units. But it alone cannot fill the hole left by M7 plus M8.

So in the 43.96%, there is indeed a part that was a choice — rather than letting old cars exit gracefully, it wouldn't do the cosmetic change clearance sale routine. But this layer only explains one-third.
The rest requires looking one level higher
HarmonyOS Intelligent Solution now has five brands. Last year when there were three brands, the best booths in Huawei stores and the first recommendation from sales staff were basically reserved for AITO. Now it's different: Shangjie Z7 starts from 219,800, Luxeed V9 sells up from 389,800. Stores are that size, foot traffic is that amount, sales staff only have that much time per day.

Numerical data confirms this. AITO's sales share within HarmonyOS Intelligent Solution dropped from 69.64% in the first half of last year to 67.19% this year. It only looks like a drop of two percentage points, but this happened under the premise that the other four brands were all pushing new cars — the pie got bigger, but AITO's slice didn't grow with it.
There is a colder fact: August saw HarmonyOS Intelligent Solution full-series deliveries of 42,101 units, also down 5.56% year-over-year. It's not just AITO pulling back. Meanwhile, Leapmotor delivered 356,500 units in the first half with a 60% increase year-over-year, Nio delivered 191,100 units with a 67.4% increase, and HarmonyOS Intelligent Solution only grew by 18.6% in the first half.

Huawei's technical label was once a river exclusive to AITO. Now this river is used together by the five brands across two environments.
The financials are actually still strong
After discussing the pressure, we must also talk about the confidence, otherwise it becomes predicting doom.
M9 has truly stood firm: Winning the sales crown in the 500,000-price-segment market for two consecutive months, full-series cumulative deliveries breaking 300,000 units, ranking first on the J.D. Power NPS list five times consecutively. Selling nearly 10,000 units per month at prices over 500,000, few domestic brands can achieve this, and it's not achieved by price cuts.
The money is enough. As of June 30, Seres sits on 73.15 billion yuan in cash reserves; R&D investment in the first half was 7.007 billion yuan, a year-over-year increase of 34.8%. Selling fewer units, R&D investment instead becomes more aggressive — indicating management has figured it out: Short-term volume can be lost, but the technical rhythm must not break. Magic Cube Technology Platform 2.0, next-generation Super Extended Range, Intelligent Safety are the tools to make a living in the next three years.

There are hard indicators on the brand front. In the Brand Finance 2026 Top 100 Global Automotive Brand Values, AITO, valued at $3.448 billion, is the only Chinese face in the Global Luxury Brand TOP 10. This position cannot be exchanged for a monthly sales volume of tens of thousands.
Overseas is also not idle: Indonesia factory 100,000 unit capacity baseline, Middle East secured the first batch of 200 units orders, overseas selling price is higher than domestic by a chunk. This move is still early, but the direction is right.
So is it viable?
My judgment is: Short-term pain exists, it is too early to conclude now, but there are two checkpoints that cannot be glossed over.
The first is if the facelifted M8 launches in September, whether it can pick up sales, directly testing if the "gear shifting" argument holds water. If it returns to over 30,000 units, August was just a small pit; if sales continue to be sluggish, the problem is not just gear shifting.

The second is the Fourth Quarter. AITO first-half sales were about 160,800 units, up 5.6% year-over-year, the annual goal of 500,000 units, the completion rate is about 32%. To make up for this gap, sales of models under the brand need to maintain high growth.
This industry is a marathon not a sprint, this is correct. But those who have run a marathon know — you can adjust breathing midway, but your pace cannot drop too hard, otherwise it is hard to catch up later. And Seres' problem now is likely a midway adjustment, not failing to keep up with market development, but Seres actively adjusting the new-old model transition in a rhythmic pattern. So we believe it will catch up soon.